
 Metallized PET Cartons Market | 2026-2036
Metallized PET Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Metallized PET Cartons Market Outlook
Subscription-based packaging design services is pivoting how converters monetize customer relationships beyond unit sales. Amcor Plc leverages its global pre-press and metallization R&D network to anchor premium flexible packaging contracts with multinational food brands. Mondi Plc competes through integrated pulp-to-packaging operations that sustain margin control across metallized PET substrate supply. Toray Industries specializes in ultra-thin vapor-deposited film technologies that differentiate its carton-grade offerings in Asian and European markets.
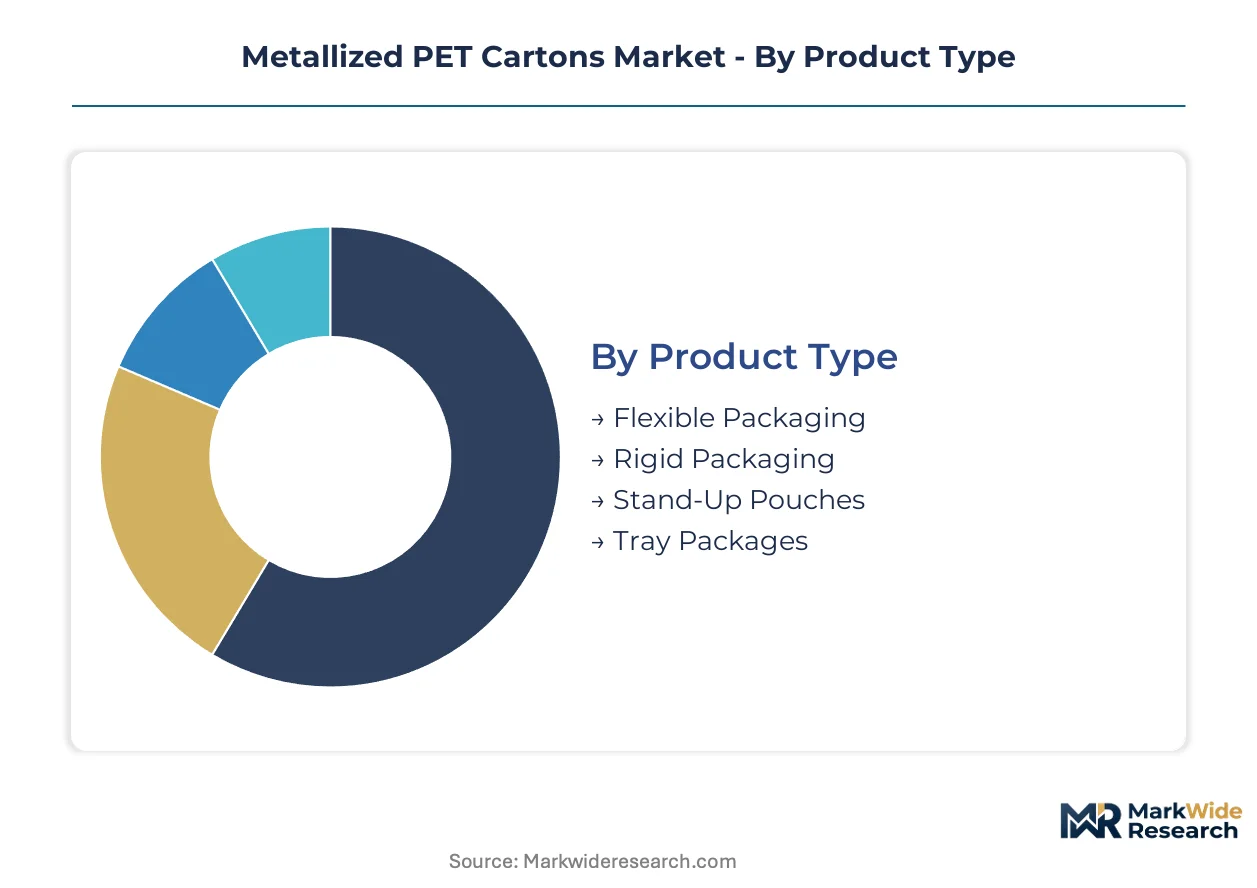
Metallized PET cartons are fiber-based containers laminated with aluminum-vapor-deposited polyethylene terephthalate film, typically achieving oxygen transmission rates below 0.1 cc per square meter per day to preserve sensitive contents. The structure combines the rigidity and recyclability of paperboard with the moisture and gas barrier properties of metalized plastic, serving primarily as premium primary packaging for shelf-stable and refrigerated consumer goods. Flexible packaging dominates current metallized PET carton volumes due to established converter infrastructure and brand familiarity, while rigid packaging and stand-up pouches represent faster-growing formats as snack and personal care brands seek dimensional differentiation on retail shelves. Tray packages occupy a narrower but higher-margin niche in frozen food and ready-meal applications where structural integrity at sub-zero temperatures commands price premiums.
The US FDA maintains strict migration limits for aluminum and PET components in food-contact cartons, while EPA guidelines on volatile organic compound emissions from metallization chambers shape domestic converter capital expenditure decisions. Europe's REACH chemicals framework and F-Gas Regulation restrict certain barrier-coating chemistries and process gases, pushing suppliers toward electron-beam and plasma-enhanced metallization alternatives. Stakeholders must monitor evolving extended producer responsibility schemes and single-use packaging directives across multiple jurisdictions, as these frameworks will determine which metallized PET carton constructions retain market access and which require fundamental material redesign.
Market Dynamics
Europe's F-Gas Regulation is compressing metallization process timelines and forcing converters toward electron-beam alternatives, reshaping capital deployment across the supply base.
Growth Catalysts
- Premium Shelf Appeal:Food and beverage brands in Germany are specifying high-barrier metallized PET cartons for shelf-stable dairy and confectionery, leveraging oxygen transmission rates below 0.1 cc per square meter per day.
- REACH Compliance Innovation:The ECHA framework is accelerating material science investment in lower-carbon vapor deposition chemistries that maintain barrier performance while reducing fluorinated gas dependence.
- Central European Converter Clustering:Packaging converters in Bavaria and Baden-Württemberg are scaling metallized PET carton capacity to serve brand owners across Austria, Switzerland, and Poland.
Market Restraints
- Aluminum Price Volatility:Input cost swings for vapor-deposition-grade aluminum foil are compressing converter margins and complicating long-term contract pricing.
- Equipment Concentration Risk:Roll-to-roll metallization chamber manufacturing concentrates among a handful of German and Japanese machinery suppliers, creating procurement bottlenecks.
- Recyclability Certification Delays:Extended producer responsibility schemes in France and Italy are withholding market access pending fiber-plastic separation protocol validation.
Strategic Opportunities
- Pharmaceutical Cold Chain:Metallized PET cartons with sub-zero structural integrity are penetrating vaccine and biologic secondary packaging in Switzerland and the Netherlands.
- EU Green Deal Alignment:The bloc's packaging and packaging waste directive revisions are creating preferential procurement pathways for mono-material-compatible barrier constructions.
- Electron-Beam Metallization:Convergence of plasma-enhanced deposition with renewable-powered production lines is opening premium positioning for carbon-accounted carton grades.
Industry Challenges
- Vapor Deposition Technician Scarcity:Specialized vacuum chamber operation and thin-film quality control expertise is concentrating among aging workforces in Stuttgart and Düsseldorf industrial zones.
- Legacy Press Integration:Retrofitting existing flexographic and offset lines for metallized PET lamination without throughput degradation demands substantial capital reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallized PET Cartons Market |
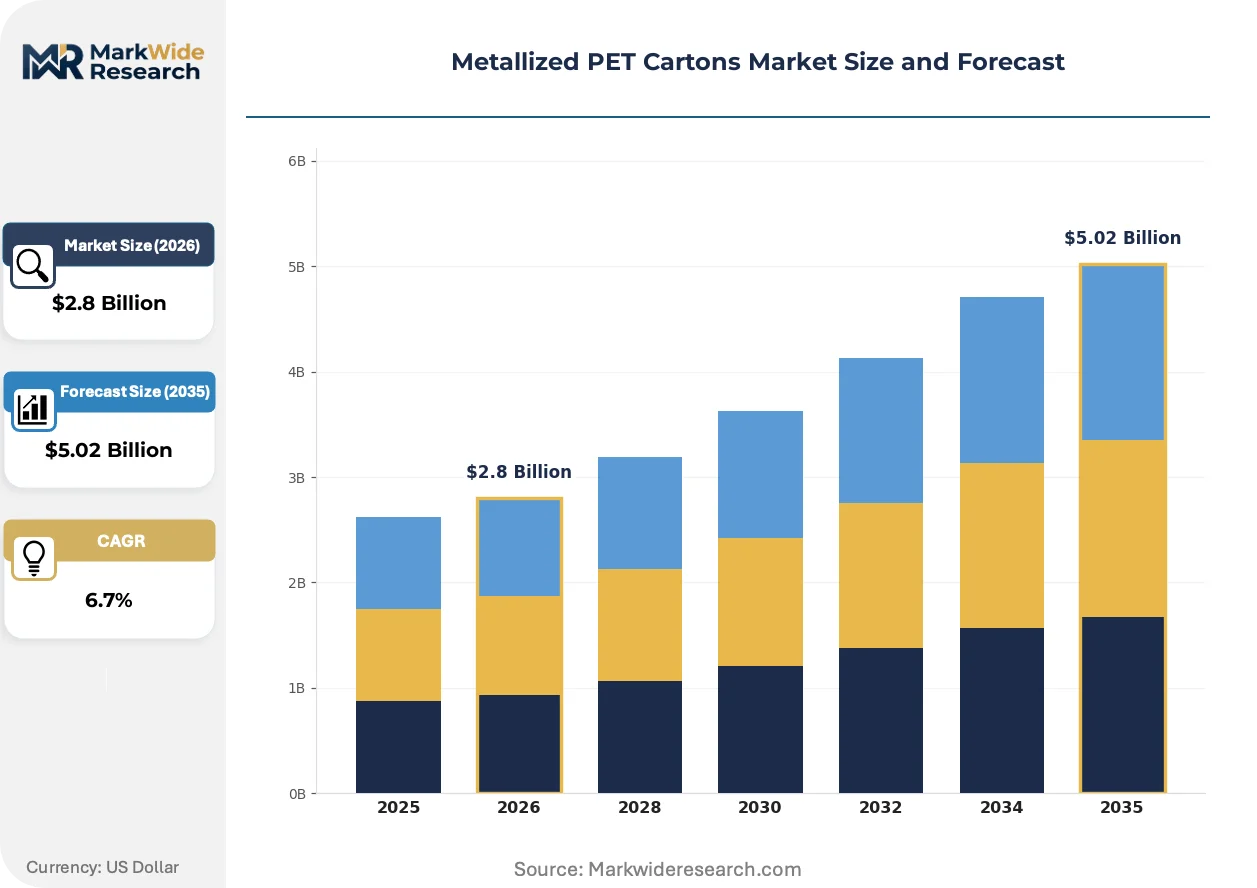
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Stand-Up Pouches, Tray Packages End User: Food & Beverage, Personal Care, Pharmaceuticals, Electronics Application: Dry Foods, Beverages, Snacks, Frozen Foods Distribution Channel: Online Retail, Hypermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | Amcor Plc, Berry Global, Mondi Plc, Sealed Air Corporation, Toray Industries, Uflex Limited, Jindal Poly Films, Cosmo First Limited, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallized PET Cartons Market Strategic Shifts
Metallized PET carton production is pivoting from conventional thermal evaporation toward energy-modulated deposition techniques that align with tightening EU process emissions standards.
Plasma-enhanced chemical vapor deposition is electrifying barrier performance at reduced aluminum thicknesses. Snack and personal care brands in France are specifying 12-micron downgauged constructions for stand-up pouch formats. This technology is compressing material intensity per unit while maintaining oxygen and moisture barriers.
The F-Gas Regulation is prohibiting hydrofluorocarbon process gases in metallization chambers by 2030. Converters in Germany and Italy are trialing electron-beam evaporation systems that eliminate fluorinated chemistry entirely. Frozen food tray applications are absorbing the highest compliance costs as sub-zero barrier requirements resist easy material substitution.
Brand owners are consolidating carton specifications around certified-recyclable mono-material constructions. Retailers in the Netherlands and Belgium are delisting multi-laminate barrier cartons lacking fiber-stream compatibility. Dairy and ready-meal segments are driving this specification tightening, with private-label suppliers adapting fastest.
Metallized PET Cartons Market Segmentation
Converters configure metallization capacity around specific format geometries, with chamber dimensions and lamination lines dedicated to particular product types. End-user specifications cascade through substrate selection, barrier requirements, and print finishes. Understanding these segment boundaries reveals where capital deployment concentrates and where margin pools diverge.
Product Type:
Roll-to-roll metallization equipment concentrates in southern Germany and northern Italy, with chamber widths and winding tensions optimized for specific format categories.
- Flexible Packaging:Roll-fed laminates dominate converter throughput, with oxygen transmission rates below 0.1 cc per square meter per day preserving shelf-stable dairy and confectionery across Central European supply chains. German brand owners specify this format for 70% of metallized carton volumes due to established flexographic print infrastructure and line speeds exceeding 300 meters per minute.
- Rigid Packaging:Thermoformed or pre-cut carton constructions demand thicker PET substrates and specialized vacuum metallization chambers with modified tension control. French cosmetics brands are specifying rigid formats for premium fragrance secondary packaging, absorbing higher unit costs for dimensional shelf presence.
- Stand-Up Pouches:Gusseted constructions with metallized PET lidding are penetrating snack and personal care segments in the Netherlands and Belgium.
- Tray Packages:Deep-draw frozen food applications require sub-zero structural integrity and specialized barrier coatings for extended freezer storage.
Today's leader: Flexible Packaging. Tomorrow's challenger: Stand-Up Pouches.
End User:
Customer procurement sophistication varies sharply, with multinational food brands demanding carbon-accounted supply chains while regional electronics assemblers prioritize unit economics.
- Food & Beverage:Shelf-stable dairy, confectionery, and ready-meal brands specify high-barrier metallized PET cartons for Central European retail distribution. Bavarian converters maintain dedicated production lines for this segment, with EFSA-compliant migration limits shaping laminate specifications.
- Pharmaceuticals:Cold chain secondary packaging for vaccines and biologics is absorbing metallized PET tray formats in Switzerland and the Netherlands. Swissmedic-registered suppliers are qualifying sub-zero barrier constructions with documented temperature excursion resistance.
- Personal Care:Premium cosmetics brands in France specify rigid metallized cartons for fragrance and skincare primary packaging.
- Electronics:ESD-sensitive component shipping containers utilize metallized PET for moisture and static protection.
Food & Beverage commands current capacity allocation. Pharmaceuticals is climbing the fastest as cold chain requirements harden.
Application:
Moisture sensitivity and oxygen exposure tolerance determine metallization thickness and adhesive selection across food categories.
- Dry Foods:Coffee, powdered nutrition, and cereal brands specify metallized PET cartons with moisture vapor transmission rates below 0.5 g per square meter per day. Italian roasters are consolidating specifications around 12-micron downgauged constructions for sustainability positioning.
- Snacks:Savory and sweet snack brands in France and Germany are migrating from multi-laminate films to mono-material-compatible metallized cartons for retailer compliance.
- Frozen Foods:Ready-meal and vegetable tray applications demand structural integrity at minus 18 degrees Celsius.
- Beverages:Shelf-stable liquid cartons utilize metallized PET lidding and sleeve formats for extended ambient distribution.
Dry Foods anchors barrier R&D investment. Snacks is gaining share fastest as format flexibility trumps absolute barrier performance.
Distribution Channel:
Order fragmentation and lead time tolerance separate procurement patterns across retail formats.
- Hypermarkets:Centralized private-label procurement by German and French retail chains drives volume concentration in metallized PET carton specifications. Aldi and Lidl are mandating mono-material compatibility for shelf-ready packaging across dairy and snack categories.
- Online Retail:Direct-to-consumer fulfillment demands damage-resistant metallized cartons with print quality sustaining unboxing experiences. Dutch e-commerce specialists are specifying reinforced corner constructions for last-mile durability.
- Convenience Stores:Smaller format requirements and rapid turnover favor flexible pouch configurations over rigid cartons.
- Specialty Stores:Premium positioning allows higher unit costs for custom print finishes and specialized barrier grades.
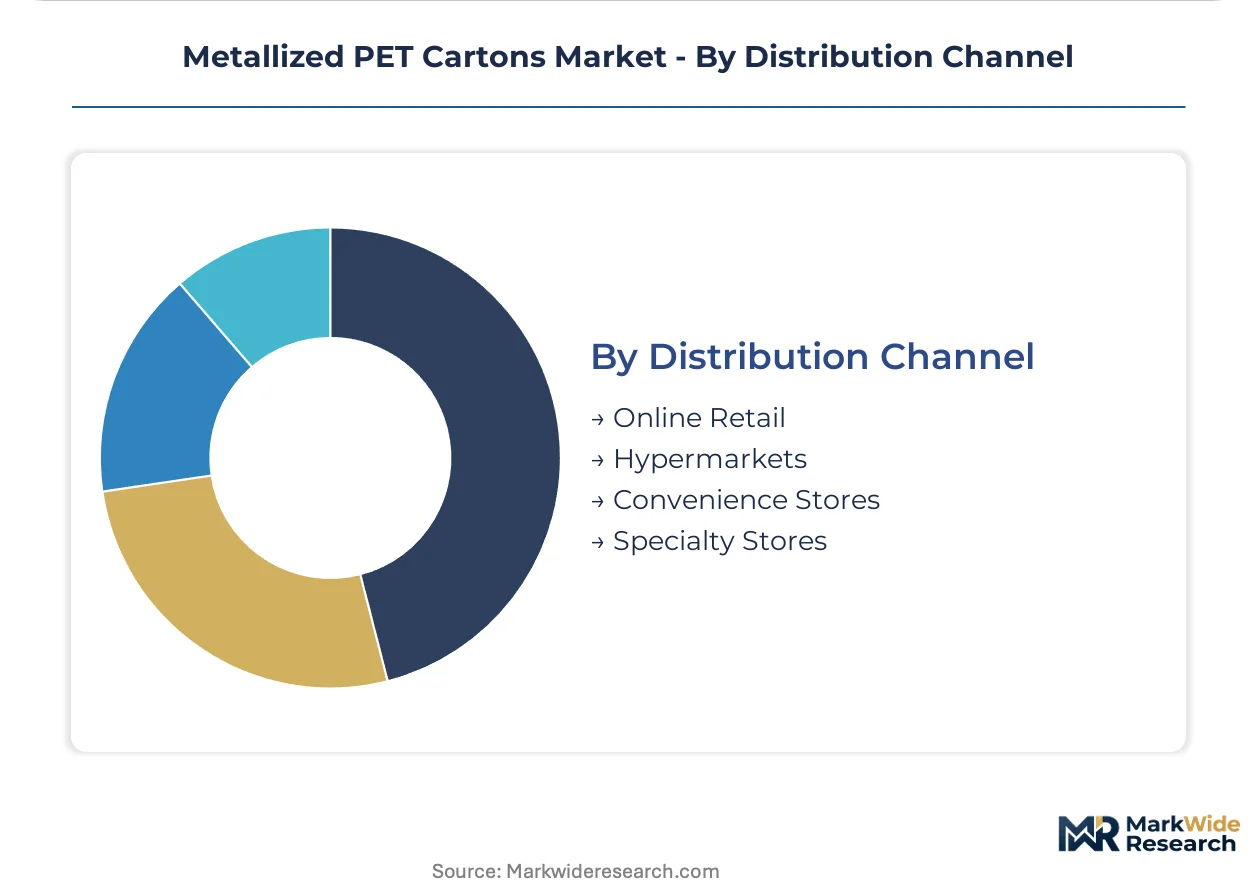
Hypermarkets dictate specification standards. Online Retail is expanding most quickly as unboxing economics reshape secondary packaging priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands metallized PET carton conversion capacity while Switzerland's pharmaceutical cold chain demand pulls premium tray formats southward, revealing divergent specialization patterns across adjacent markets.
Germany
Bavarian converters in Augsburg and Munich serve Central European brand owners with high-barrier carton solutions for shelf-stable dairy and confectionery. The F-Gas Regulation is compressing metallization process timelines and forcing capital deployment toward electron-beam alternatives. Baden-Württemberg's machinery cluster around Stuttgart supplies roll-to-roll metallization chambers to domestic and Italian converters.
Switzerland
Swissmedic-registered suppliers qualify sub-zero barrier constructions for vaccine and biologic secondary packaging in Basel and Zurich. REACH compliance requirements shape laminate specifications for pharmaceutical exports into EU markets. The country's precision manufacturing heritage supports technician training programs for vacuum chamber operation.
Netherlands
Dutch retailers in Rotterdam and Amsterdam mandate mono-material compatibility for shelf-ready packaging, delisting multi-laminate barrier cartons lacking fiber-stream validation. E-commerce specialists specify reinforced corner constructions for last-mile durability. The national extended producer responsibility scheme accelerates separation protocol innovation.
France
Cosmetics brands in Paris and Grasse specify rigid metallized cartons for premium fragrance secondary packaging, absorbing higher unit costs for dimensional shelf presence. ANSM guidelines on food-contact materials influence barrier coating chemistries for dairy applications. The country's packaging and packaging waste directive implementation creates preferential procurement pathways for certified-recyclable constructions.
Italy
Coffee roasters in Milan and Turin consolidate specifications around downgauged metallized PET constructions for sustainability positioning. The national extended producer responsibility scheme withholds market access pending fiber-plastic separation validation. Northern Italian converters trial plasma-enhanced deposition systems to eliminate fluorinated chemistry entirely.
Metallized PET Cartons Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with multinational converters anchoring premium food contracts and regional players capturing private-label volume. The vendor base concentrates among integrated pulp-to-packaging operators, film specialists with vapor deposition expertise, and diversified flexible packaging conglomerates. Three archetypes dominate: substrate-integrated multinationals, thin-film technology specialists, and emerging market cost leaders. Competitive moves center on backward integration into metallization capacity and geographic expansion into Central European converter clusters.
Within the substrate-integrated tier, Amcor Plc and Mondi Plc occupy positions that exemplify divergent scale strategies, while Toray Industries anchors the thin-film technology specialist archetype with Japanese precision manufacturing heritage. These three companies represent the competitive poles around which mid-cap regional converters and private-label specialists orbit, each archetype commanding different margin pools and customer relationship structures.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global |
| Mondi Plc |
| Sealed Air Corporation |
| Toray Industries |
| Uflex Limited |
| Jindal Poly Films |
| Cosmo First Limited |
| Huhtamaki Oyj |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation compliance gates qualified supply and premium-tier pricing access, as converters investing in electron-beam metallization capacity capture carbon-accounted contract premiums while legacy thermal evaporation operators face delisting from retailer-approved supplier rosters.
Pricing Analysis
Capacity additions in Germany and northern Italy are reshaping price floors for metallized PET carton grades, compressing margins for thermal evaporation-dependent converters while electron-beam-equipped suppliers maintain three-tier pricing stratification across premium certified-recyclable, standard barrier, and economy flexible formats. Price differentiation hinges on REACH-compliant coating chemistry and mono-material fiber-stream certification, with hypermarket private-label buyers exhibiting acute price sensitivity compared to Swiss pharmaceutical cold chain purchasers who absorb premiums for sub-zero structural integrity.
Supply Chain Analysis
Freight costs for vapor-deposition-grade aluminum foil from German and Japanese machinery suppliers amplify total delivered costs for southern European converters, while roll-to-roll metallization chamber manufacturing concentrates in Stuttgart and Düsseldorf industrial zones. Raw material dependencies span PET resin, high-purity aluminum feedstock, and specialized barrier adhesives, with single-source vulnerability around electron-beam equipment manufacturers posing the dominant structural risk. Distribution runs through converter-direct relationships with Central European brand owners and tiered distributor networks serving fragmented Italian and French regional processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metallized PET carton procurement functions as a geographic-arbitrage play, with Swiss pharmaceutical cold chain specifications commanding 40-60% unit price premiums over German food-grade volumes despite comparable production costs.
For Market Incumbents: Lock in backward integration into captive metallization capacity before equipment lead times extend beyond 18 months, while securing EFSA-compliant migration documentation to defend against emerging plasma-enhanced deposition specialists from Asia. Prioritize electron-beam retrofit investments at Bavarian facilities to maintain access to Aldi and Lidl private-label contracts as F-Gas prohibitions harden. For New Entrants and Emerging Players: Launch via direct-to-ecommerce fulfillment partnerships with Dutch last-mile specialists, targeting reinforced corner carton constructions for unboxing economics. White-space opportunities concentrate in Italian coffee roaster sustainability mandates and Belgian retailer mono-material compliance deadlines, with plasma-enhanced deposition technology offering the most penetrable technical differentiation angle against established thermal evaporation incumbents. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap regional converters with certified-recyclable product portfolios because extended producer responsibility schemes are consolidating procurement around pre-validated supplier lists. Long-term viability centers on electron-beam equipment ownership and pharmaceutical cold chain qualification. Watch Swissmedic registration timelines as the inflection signal for premium tray format demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electron-Beam Metallization Retrofit | Eliminates F-Gas compliance exposure while unlocking carbon-accounted contract premiums from Dutch retailers. |
| Mono-Material Certification Investment | Secures shelf access under France's extended producer responsibility scheme and Belgium's fiber-stream mandates. |
| Pharmaceutical Cold Chain Qualification | Captures Swissmedic-registered demand for vaccine secondary packaging with sub-zero barrier documentation. |
| Backward Integration into Metallization | Reduces aluminum foil margin leakage and insulates against Japanese equipment supplier concentration risk. |
| Plasma-Enhanced Deposition Licensing | Enables 12-micron downgauged constructions for Italian coffee roaster sustainability specifications. |
Study Parameters
Coverage spans Germany, Switzerland, Netherlands, France, and Italy, with primary inputs from each market's converter clusters and brand owner procurement functions. The analysis combines interviews with vacuum chamber operators, packaging R&D directors, retail category buyers, and barrier coating chemists with secondary validation from ECHA regulatory filings, EFSA migration limit databases, and national extended producer responsibility scheme documentation. Bottom-up volume estimates from identified metallization capacity across Bavarian and Baden-Württemberg facilities triangulate against top-down demand projections from Central European food and pharmaceutical packaging consumption patterns.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, with segmentation modeling across flexible packaging, rigid cartons, stand-up pouches, and tray formats further disaggregated by end-use intensity in dairy, confectionery, ready-meals, and pharmaceutical cold chain applications. CAGRs derive from installed capacity utilization trajectories, brand owner specification migration timelines, and regulatory compliance cost pass-through elasticity. Industry-specific inputs include F-Gas Regulation phase-out schedules and Swissmedic temperature excursion validation protocols.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum price volatility spikes or accelerated electron-beam equipment obsolescence cycles. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and retailer delisting timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Liquid Packaging Cartons Market
Cartons
Africa Folding Carton Market
Cartons
GCC Folding Carton Market
Cartons
Carton Liners Market
Cartons
Horizontal Cartoning Machines Market
Cartons
Cartoning Machines Market
Cartons
Braille Cartons Packaging Market
Cartons
Japan Corrugated Boxes Market
Cartons
Beverage Cartons Market
Cartons
Cardboard Crates Market
Cartons
MET-PET Cartons Market
Cartons
Fluted Carton Trays Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
Soap Boxes Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Carton Sealer Machine Market