
 LDPE Films Market | 2026-2036
LDPE Films Market Size, Share, and Industry Trends Forecast 2026-2036
LDPE Films Market Outlook
REACH is broadening the cost-of-entry calculus for LDPE film producers seeking access to European consumer markets. ExxonMobil Chemical leverages its upstream ethylene integration to sustain margin stability across volatile feedstock cycles. LyondellBasell Industries anchors its position through large-scale blown film operations serving North American food packaging customers. Berry Global Group differentiates via multi-layer co-extrusion capabilities that address healthcare barrier requirements.
LDPE films are low-density polyethylene sheets manufactured through blown or cast extrusion at thicknesses ranging from 20 to 50 microns, valued for flexibility, clarity, and moisture resistance in protective packaging applications. Stretch films dominate volume within the product type category as palletization demand from retail distribution networks remains structurally embedded. Co-extrusion technology commands premium positioning because multi-layer architectures deliver oxygen and moisture barriers that commodity monolayer films cannot match. Shrink films represent the fastest-growing product segment as e-commerce fulfillment centers adopt automated wrapping systems for irregular parcel geometries.
FDA food contact regulations in the United States, EU REACH restrictions on substance migration, and China's GB standards for plastic packaging collectively shape formulation choices and market access protocols for LDPE film suppliers. These frameworks compel converters to maintain dual certification portfolios that increase fixed compliance costs but create defensible positions against uncertified regional competitors. Stakeholders must monitor how recycled content mandates evolve across jurisdictions, as mechanical recycling compatibility will determine which extrusion technologies retain long-term viability.
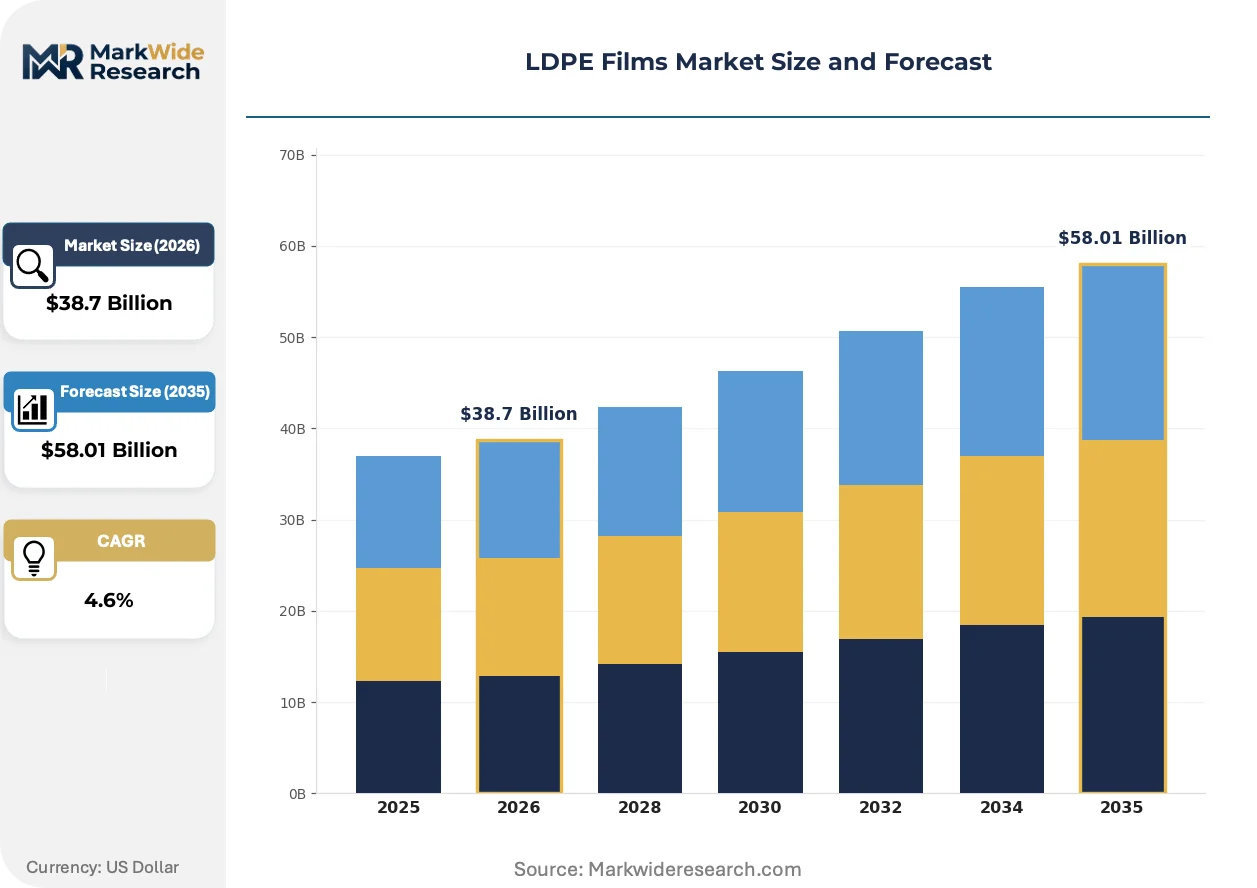
Market Dynamics
Mechanical recycling compatibility requirements are forcing LDPE film converters to requalify extrusion lines for post-consumer feedstock streams, altering capital deployment timelines and supplier qualification protocols across packaging supply chains.
Growth Catalysts
- E-commerce fulfillment automation:Automated wrapping systems for irregular parcel geometries are pulling shrink film volumes into distribution centers serving omnichannel retail networks.
- REACH substance migration limits:European ECHA restrictions on additive leaching are accelerating reformulation toward compliant masterbatches that command premium positioning.
- Agricultural blown film expansion:Domestic converters in China are scaling capacity for greenhouse and silage applications, concentrating demand in Shandong and Jiangsu provinces.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracker margins swing with crude oil benchmarks, compressing converter profitability during upstream price spikes.
- Monolayer technical ceiling:Single-layer LDPE cannot match oxygen transmission rates below 500 cc/m²/day, capping penetration into modified atmosphere packaging.
- Import substitution in China:Domestic resin capacity additions are displacing Korean and Thai virgin LDPE shipments, reshaping regional trade flows.
Strategic Opportunities
- India food packaging underpenetration:Organized retail expansion in Maharashtra and Karnataka is creating first-mover positions for certified food-contact film suppliers.
- Chemical recycling convergence:Pyrolysis oil integration with conventional extrusion is opening feedstock pathways for 30%+ recycled content claims.
- EU Green Deal packaging mandates:Recycled content thresholds for 2030 are incentivizing converter investments in wash-line and pelletizing infrastructure.
Industry Challenges
- Multi-layer delamination complexity:Separating EVOH and tie-layer residues from PE streams requires density-based flotation systems that extend processing cycles.
- FDA food contact notification timelines:New additive approvals average 180-day review windows, delaying product launches for North American customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LDPE Films Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Films, Shrink Films, Bags, Liners End Use Industry: Food Packaging, Healthcare, Agriculture, Retail Thickness: 20 Microns, 30 Microns, 40 Microns, 50 Microns Technology: Blown Film Extrusion, Cast Film Extrusion, Co-extrusion, Recyclable Films |
| Companies Covered | Novolex Holdings, Winpak, Amcor plc, ExxonMobil Chemical, LyondellBasell Industries, Berry Global Group, Sigma Plastics Group, Blueridge Films, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LDPE Films Market Strategic Shifts
Active barrier technologies and circular feedstock integration are compressing the performance gap between commodity films and engineered multilayer structures, reshaping how converters segment their product portfolios.
Metallocene-catalyzed LLDPE is rewriting the stiffness-toughness tradeoff in stretch film formulations. Third-party logistics providers serving beverage distribution networks are adopting these resins for downgauging initiatives. The technology is rewriting load containment economics by enabling 12-micron replacements for 20-micron conventional films without pallet failure.
EU REACH restrictions on substance migration are compelling reformulation of slip and anti-block additives. ECHA evaluations of zinc-based masterbatches are driving migration toward amide alternatives that maintain coefficient of friction targets. Food packaging converters serving European retail chains are qualifying new additive packages ahead of 2025 substance evaluation deadlines.
Consolidated buying by omnichannel grocery platforms is compressing supplier qualification cycles. Amazon Fresh and Walmart fulfillment networks are unbundling film procurement from legacy packaging distributors, forcing direct converter relationships. This pattern is most visible in North American produce packaging, where specification control has shifted from regional distributors to centralized sustainability teams.
LDPE Films Market Segmentation
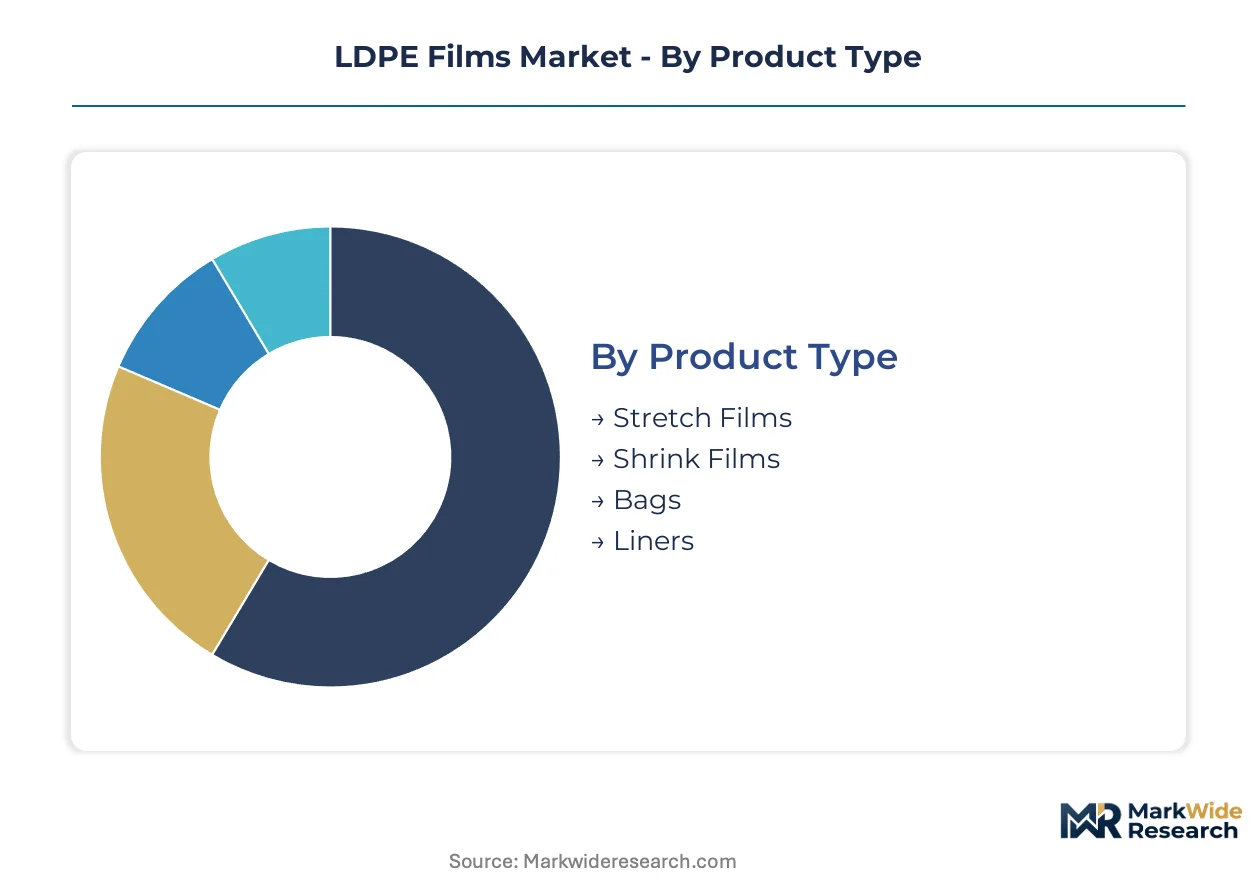
LDPE film converters segment their portfolios across four intersecting dimensions that determine pricing power and capital intensity. Product type and end-use concentration dictate margin profiles, while thickness and technology choices lock in equipment amortization cycles and recycling compatibility.
Product Type:
Supply concentration in stretch film manufacturing has consolidated around large-scale blown film operations serving third-party logistics networks.
- Stretch Films:Manufactured through blown extrusion with cling additives for pallet unitization. Demand concentrates in beverage distribution centers across Germany and the United States as downgauging initiatives push specifications toward 12-micron metallocene formulations.
- Shrink Films:Biaxially oriented structures that contract under heat application to conform to irregular geometries. E-commerce fulfillment centers in Poland and the Netherlands are pulling volumes as automated wrapping systems replace manual carton sealing.
- Bags:Side-sealed or bottom-sealed configurations for bulk commodity containment. Agricultural cooperatives in Brazil and Argentina drive specifications for UV-stabilized silage bags.
- Liners:Insert films for intermediate bulk containers and drum protection. Chemical processors in the US Gulf Coast specify anti-static formulations for powder handling.
Today's leader: Stretch Films. Tomorrow's challenger: Shrink Films.
End Use Industry:
Application-driven cost tiers separate food-contact certified operations from general industrial supply.
- Food Packaging:Modified atmosphere and vacuum structures requiring FDA or EFSA compliance. European retail chains are consolidating supplier lists around dual-certified converters with wash-line capabilities.
- Healthcare:Sterile barrier systems with Tyvek lidding compatibility. Medical device manufacturers in Massachusetts and Minnesota specify particulate-free cleanroom extrusion.
- Agriculture:Greenhouse covers, mulch films, and silage wraps with UV stabilization packages. Domestic production in Shandong province is displacing imported Korean resin for 200-micron greenhouse applications.
- Retail:Carry-out bags and merchandise protection with printed branding. India's organized retail expansion in Maharashtra is creating first-mover positions for certified food-contact suppliers.
Food Packaging commands premium positioning. Healthcare offers the steepest expansion trajectory for barrier-qualified converters.
Thickness:
Volume-weighted demand clusters at standard gauges where equipment utilization peaks.
- 20 Microns:Ultra-thin specifications for lightweight primary packaging. Japanese convenience store chains specify this gauge for onigiri and sandwich wraps to minimize material taxation.
- 30 Microns:General-purpose films balancing puncture resistance and yield. This gauge dominates produce overwrap applications in French hypermarkets.
- 40 Microns:Heavy-duty industrial liners and drum protection. Chemical processors in Belgium specify this thickness for hygroscopic powder containment.
- 50 Microns:Maximum puncture resistance for abrasive agricultural contents. Argentine silage operations require this gauge for extended outdoor exposure.
30 Microns anchors current volume. 20 Microns is climbing the fastest as downgauging mandates tighten.
Technology:
Capital deployment timelines diverge sharply between commodity extrusion and multi-layer barrier systems.
- Blown Film Extrusion:Tubular bubble process creating balanced orientation in machine and transverse directions. This technology dominates stretch film supply to German automotive component distributors.
- Cast Film Extrusion:Chill-roll process delivering superior optical clarity and gauge uniformity. Italian fresh pasta packagers specify cast films for retail display windows.
- Co-extrusion:Multi-layer architectures combining LDPE with EVOH or nylon for oxygen barrier. Healthcare converters in North Carolina are qualifying five-layer systems for sterile device packaging.
- Recyclable Films:Mono-material designs compatible with mechanical recycling streams. EU Green Deal packaging mandates are accelerating converter investments in wash-line compatible formulations.
Blown Film Extrusion holds installed base dominance. Recyclable Films are gaining share fastest as regulatory deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer engineers and blown film technicians cluster around petrochemical corridors and packaging hubs. Germany's Ruhr Valley, China's Shandong province, and the US Gulf Coast anchor the deepest talent pools for LDPE film manufacturing.
United States
E-commerce fulfillment networks in Dallas-Fort Worth and Chicago drive shrink film specifications for automated parcel wrapping. FDA food contact regulations govern formulation choices for retail packaging applications. ExxonMobil Chemical maintains upstream ethylene integration along the Gulf Coast, supplying converters in Texas and Louisiana.
China
Domestic blown film capacity for agricultural greenhouse covers and retail carry bags concentrates demand in Shandong and Jiangsu provinces. GB standards for plastic packaging migration limits shape masterbatch selection for food-contact applications. Qingdao and Yantai host expanding converter operations displacing Korean virgin resin imports.
Germany
Automotive component distributors in Stuttgart and Munich specify downgauged stretch films for pallet unitization. EU REACH substance migration restrictions accelerate reformulation of slip additives toward amide-based alternatives. The Ruhr Valley chemical cluster sustains integrated supply chains for film-grade resin.
India
Organized retail expansion in Maharashtra and Karnataka creates first-mover positions for certified food-contact film suppliers. FSSAI packaging safety standards govern import qualification for virgin resin converters. Mumbai-Pune industrial corridor attracts blown film investments serving domestic FMCG brands.
Brazil
Agricultural cooperatives in São Paulo state and Paraná drive specifications for UV-stabilized silage bags and mulch films. ANVISA pharmaceutical packaging regulations influence barrier film requirements for healthcare applications. Campinas hosts converter operations supplying grain storage and produce protection markets.
LDPE Films Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation around large-scale blown film operations serving third-party logistics networks has compressed mid-tier margins. Strategic archetypes include upstream-integrated petrochemical suppliers, multi-layer co-extrusion specialists, and regional converters with wash-line recycling capabilities. Capacity expansion and M&A activity dominate competitive moves as players position for recycled content mandates.
Among North American packaging conglomerates, Novolex Holdings and Berry Global Group represent scale-driven archetypes with broad extrusion footprints. ExxonMobil Chemical anchors the upstream-integrated tier through captive ethylene supply. These three exemplify how backward integration and multi-layer technology capabilities separate premium positioning from commodity supply.
| Leading Market Players |
|---|
| Novolex Holdings |
| Winpak |
| Amcor plc |
| ExxonMobil Chemical |
| LyondellBasell Industries |
| Berry Global Group |
| Sigma Plastics Group |
| Blueridge Films |
| Sealed Air Corporation |
| Others |
Value Chain & Pricing Dynamics
Specialized blown film technicians in Germany's Ruhr Valley command wage premiums that widen spreads between certified food-contact grades and commodity industrial supply. Labor-cost differentials between European technical specialists and Asian operational workforces stratify pricing tiers across export markets.
Pricing Analysis
Bundled converter services combining extrusion with printed branding and logistics management capture 15-20% premiums over unbundled commodity film supply. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified food contact grades from general industrial specifications and agricultural commodity tiers. Pricing pressure stems from ethylene feedstock volatility linked to naphtha-cracker margin swings. Third-party logistics providers exhibit highest price sensitivity, while healthcare sterile barrier customers accept premium positioning for particulate-free cleanroom certification.
Supply Chain Analysis
Freight cost differentials between containerized resin shipments and regional rail distribution reshape procurement patterns for inland converters. Virgin LDPE supply concentrates in China, South Korea, and the United States Gulf Coast petrochemical corridors. Raw material streams draw from naphtha crackers, ethane-fed crackers, and pyrolysis oil chemical recycling feedstocks. Single-source vulnerability persists for metallocene-catalyzed LLDPE resins with limited qualified suppliers. Distribution runs through third-party logistics networks serving omnichannel retail fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LDPE films market functions as a regulatory compounder where EU Green Deal packaging mandates with 2030 recycled content thresholds are accelerating capital deployment across converter operations.
For Market Incumbents: To counter import substitution pressures from Chinese domestic resin capacity, anchor market position through backward integration into captive ethylene supply or regional blown film capacity additions in Shandong province. Prioritize wash-line infrastructure investments that qualify operations for EU recycled content certification tiers. For New Entrants and Emerging Players: REACH substance migration restrictions in Europe open a window for additive masterbatch specialists with ECHA-compliant amide-based formulations. Target India's Maharashtra organized retail corridor with FSSAI-certified food contact films. Pursue direct converter relationships with Amazon Fresh and Walmart sustainability teams bypassing legacy packaging distributors. For Investors and Strategic Acquirers: Petrochemical conglomerates seeking downstream packaging integration represent the most active acquirer in this space. Five-to-ten year viability hinges on mechanical recycling compatibility and chemical recycling feedstock access. Monitor EU Green Deal implementation timelines as inflection indicators for wash-line infrastructure valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Supply | Captive naphtha-cracker access insulates ExxonMobil Chemical from feedstock volatility cycles. |
| Multi-Layer Co-Extrusion Capacity Expansion | Five-layer EVOH barrier systems qualify Berry Global Group for healthcare sterile device packaging. |
| Wash-Line and Pelletizing Infrastructure | Mechanical recycling compatibility positions converters for EU Green Deal 2030 mandates. |
| Direct E-Commerce Platform Relationships | Amazon Fresh procurement unbundling shifts specification control from distributors to converters. |
| Metallocene LLDPE Downgauging Programs | 12-micron stretch film formulations reduce material intensity for German beverage distributors. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down resin production tracking forms the analytical core of this study. Primary interviews with blown film plant managers, procurement leads at food packaging OEMs, distribution channel partners, and technical R&D directors combined with secondary validation against customs/trade data, ACC and Cefic industry reports, and SEC 10-K filings. Triangulation between converter capacity utilization surveys and virgin resin import statistics anchors volume estimates.
Input-output matrices map ethylene feedstock availability through extrusion capacity to end-use demand across product type, thickness gauge, technology platform, and regional production hub dimensions. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate blown film line qualification timelines for post-consumer feedstock streams and REACH additive reformulation adoption curves.
Revisions become necessary when EU Green Deal implementation accelerates, chemical recycling pyrolysis oil supply scales unexpectedly, or Chinese domestic resin capacity displaces import volumes faster than modeled. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
In-Mould Label Film Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
Biaxially Oriented Polypropylene (BOPP) Films Market
Poly film
PP Laminating Films Market
Poly film
North America BOPP Films Market
Poly film
Resealable Films Market
Poly film
Thermoforming Films Market
Poly film
Polyurethane (PU) Film Market
Poly film
Bopet Films Market
Poly film
Formable Films Market
Poly film
Polymer Waterproof Rolls Market
Poly film
Light Reflective Film Market
Poly film
Chocolate Wrapping Films Market
Poly film
MOPP Packaging Films Market
Poly film
Craft Plastic Films Market