
 Global PVDC Coated Films Market | 2026-2036
Global PVDC Coated Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global PVDC Coated Films Market Foresight
ISO 9001 and BRCGS certification cycles are rotating supplier eligibility across the PVDC coated films value chain, filtering out uncertified converters. Cosmo Films Ltd. leverages its integrated biaxial orientation lines to control substrate quality from resin to finished roll. Jindal Poly Films Limited anchors South Asian supply through captive PET and BOPP film production. Kureha Corporation dominates PVDC resin chemistry, supplying polymer to downstream coaters under long-term offtake arrangements.
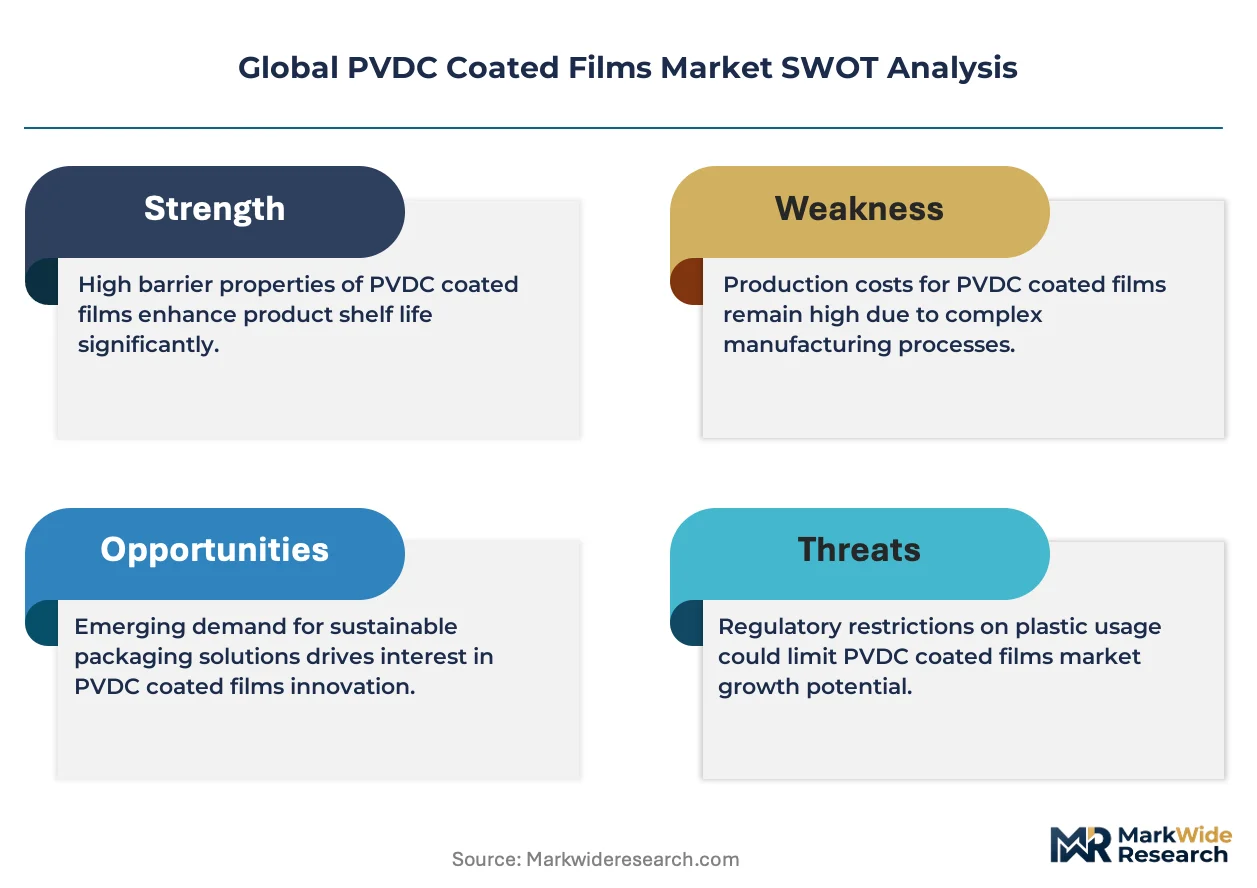
PVDC coated films consist of polyvinylidene chloride emulsion or extrusion layers applied to polyester, polypropylene, or polyethylene substrates, typically achieving oxygen transmission rates below 1 cc/m²/day to preserve shelf-sensitive contents. These multilayer constructions serve primarily to block moisture and gas permeation in perishable and regulated goods. Barrier Films lead product-type revenue due to pharmaceutical serialization and extended-distribution stability mandates, while Specialty Coated Films capture expanding margin pools from aseptic and retort applications. Food Packaging anchors application volume through modified-atmosphere meat and cheese formats, though Pharmaceutical Packaging generates premium pricing from validation-intensive blister and cold-form foil laminates.
FDA food-contact notification requirements and EU REACH Annex XVII restrictions on chlorine-bearing polymers shape formulation choices and migration-testing burdens for film exporters. China's SAMR enforces GB standards for composite food packaging that increasingly reference PVDC layer adhesion and solvent residue thresholds. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs and customs detention risks.
Market Dynamics
Barrier performance specifications in pharmaceutical serialization are compressing coating tolerances and forcing substrate-coater integration decisions across the value chain.
Growth Catalysts
- EU REACH Annex XVII:Chlorinated polymer restrictions are filtering out non-compliant converters and consolidating qualified supplier pools for European pharmaceutical exports.
- Cold-chain pharmaceutical distribution:Temperature excursion sensitivity in biologics is mandating sub-1 cc/m²/day oxygen transmission rates that only PVDC constructions reliably deliver.
- China SAMR GB standards:Solvent residue thresholds for composite food packaging are accelerating domestic coating line upgrades and import substitution.
Market Restraints
- VCM monomer supply concentration:Kureha Corporation's dominance in PVDC resin chemistry creates single-source vulnerability for downstream coaters without long-term offtake arrangements.
- Ethylene-vinyl alcohol copolymer substitution:EVOH multilayer films are capturing modified-atmosphere meat applications where clarity and recyclability outweigh absolute barrier performance.
- REACH migration testing burdens:Annex XVII compliance costs are prohibiting small and mid-size converters from serving EU pharmaceutical accounts.
Strategic Opportunities
- India cold-chain infrastructure:Underdeveloped pharmaceutical distribution networks present first-mover positioning for validated barrier film suppliers as CDSCO serialization mandates expand.
- Aseptic retort applications:Sterilization-stable PVDC laminates are penetrating ready-meal formats where metal cans face lightweighting pressure.
- Dual carbon goals in China:MEE emissions standards are incentivizing water-based emulsion coating retrofits that reduce solvent recovery capex for domestic producers.
Industry Challenges
- ISO 15378 GMP certification timelines:Pharmaceutical-grade film validation cycles extend 18-24 months, freezing converter capacity allocation decisions.
- Biaxial orientation line integration:Substrate quality control demands are forcing coaters to backward integrate into resin extrusion or surrender margin to captive suppliers.
- BRCGS packaging certification rotation:Annual audit cycles for food-contact applications are consuming quality assurance bandwidth at mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PVDC Coated Films Market |
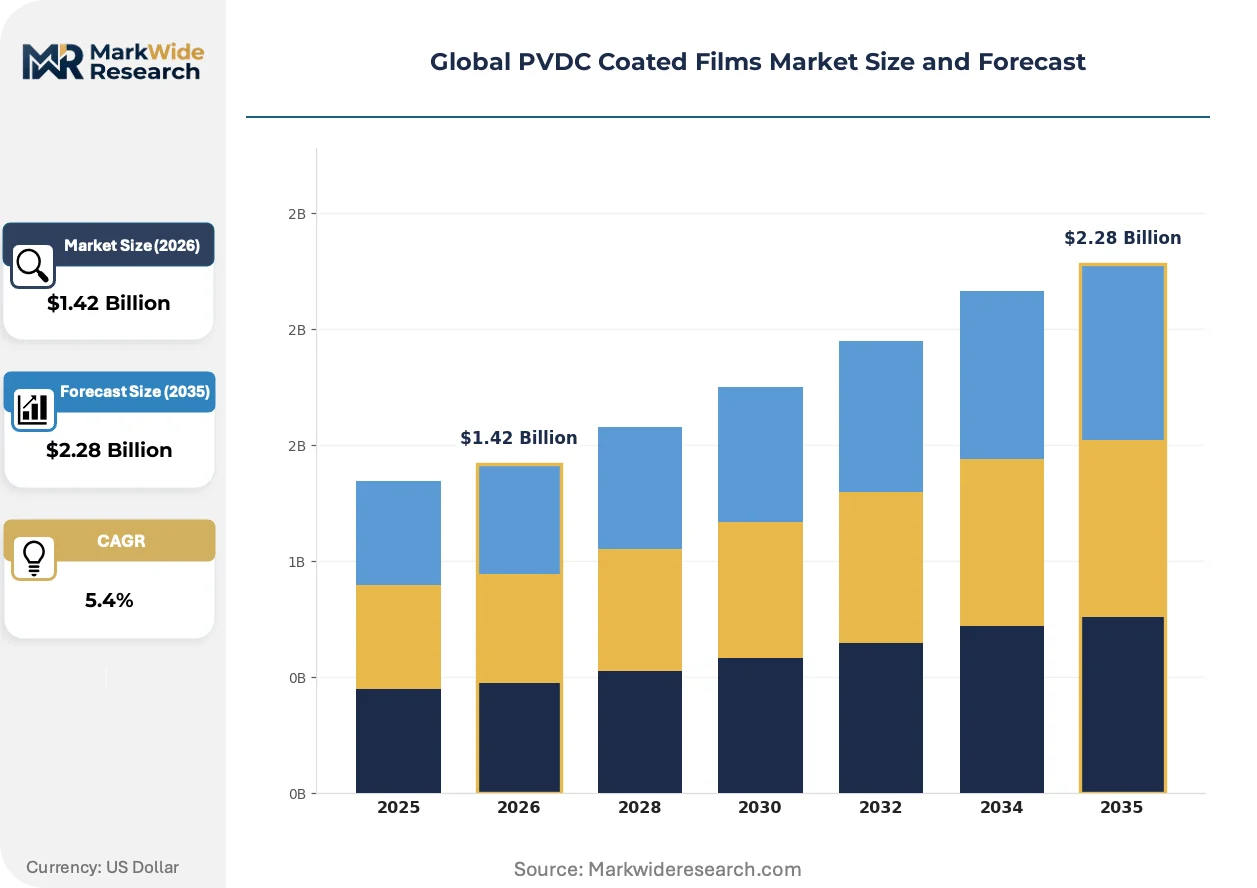
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barrier Films, Single Coated Films, Double Coated Films, Specialty Coated Films Application: Food Packaging, Pharmaceutical Packaging, Cosmetic Packaging, Industrial Wrapping End User: Packagers, Pharmaceutical Manufacturers, Cosmetic Producers, Industrial Suppliers Packaging Type: Flexible Packs, Blister Packs, Shrink Wraps, Vacuum Bags |
| Companies Covered | Cosmo Films Ltd., Jindal Poly Films Limited, SKC Inc., Vibac Group S.P.A., Kureha Corporation, SKF Limited, Polinas Corporate, Mondi Group plc., Toray Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PVDC Coated Films Market Shifts & Advancements
Coating chemistry and substrate engineering are converging to redefine barrier performance benchmarks while regulatory fragmentation is splitting formulation strategies by destination market.
Water-based PVDC emulsion technology is decomposing the solvent-coating equipment lock-in that has protected incumbent converters. Pharmaceutical blister pack manufacturers in Germany and Switzerland are piloting aqueous lines to eliminate solvent recovery infrastructure. The technology is decomposing regional supply advantages tied to volatile organic compound permitting.
EU F-Gas Regulation phase-down schedules are pressuring fluorinated polymer alternatives in high-barrier applications. PVDC coatings are capturing displaced demand in pharmaceutical cold-form foil laminates where perfluorinated incumbent materials face quota restrictions. Medical device packaging in Ireland and the Netherlands is switching formulations ahead of 2030 prohibition timelines.
Serialization-driven lot-level traceability is compressing converter-buyer contracting cycles. Pharmaceutical packagers in the United States are demanding quarterly certificate-of-analysis updates rather than annual compliance documentation. Quality assurance teams at Midwest distribution hubs are reallocating procurement resources toward supplier audit frequency over unit price negotiation.
Global PVDC Coated Films Market Segmentation
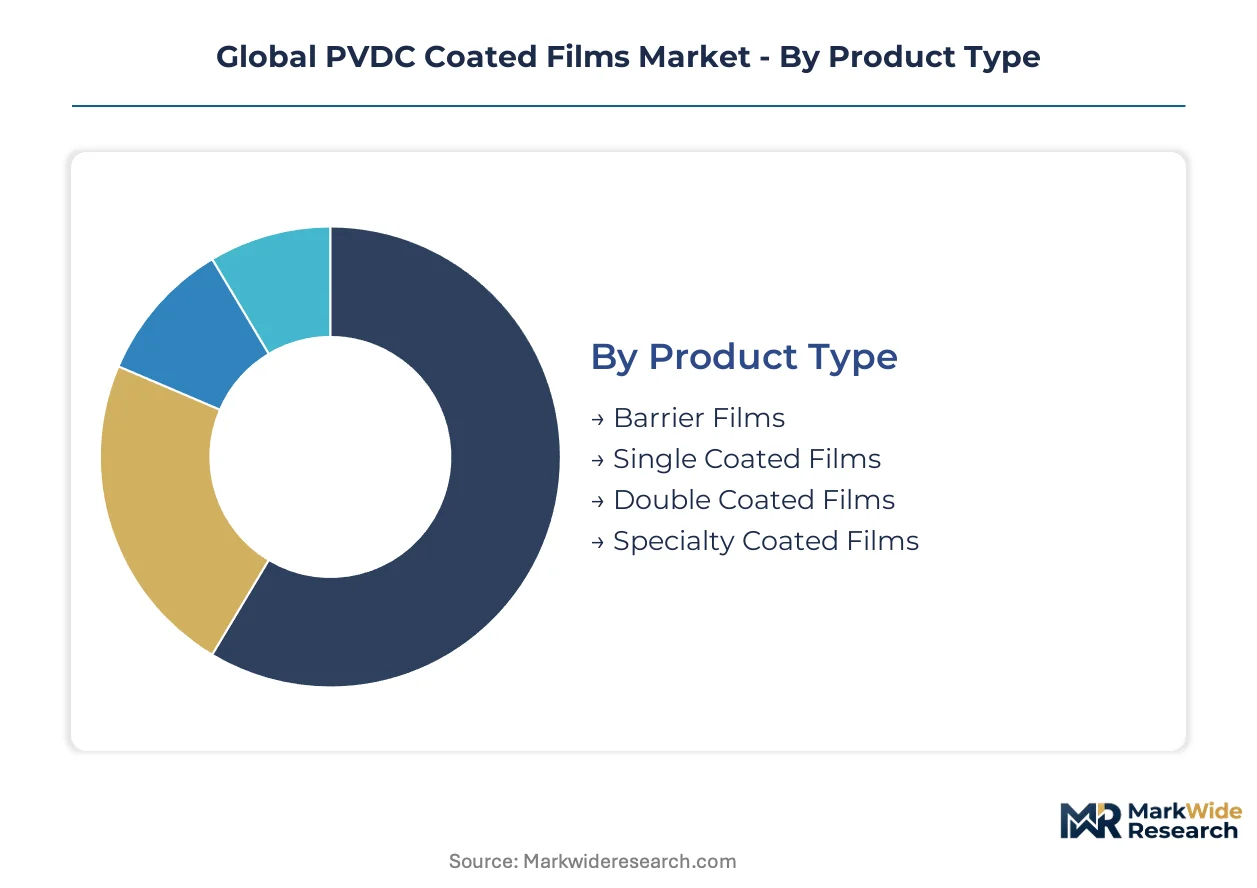
PVDC coated films serve divergent technical requirements across pharmaceutical serialization, perishable food distribution, and industrial logistics. Segmentation reveals where barrier specifications, regulatory validation burdens, and supply chain integration demands concentrate margin and volume.
Product Type:
Barrier Films and Specialty Coated Films dominate export-led demand to regulated European and North American pharmaceutical markets, while Single and Double Coated Films serve price-sensitive domestic food packaging across Asia-Pacific.
- Barrier Films:Multilayer constructions achieving oxygen transmission rates below 1 cc/m²/day through PVDC emulsion or extrusion layers on polyester or polypropylene substrates. Pharmaceutical serialization mandates in Germany and Switzerland are compressing coating tolerances and forcing substrate-coater integration decisions for suppliers serving these accounts.
- Specialty Coated Films:Sterilization-stable laminates engineered for aseptic and retort applications requiring thermal resistance beyond standard barrier specifications. Ready-meal formats in Japan and medical device packaging in Ireland are switching to these constructions as metal cans face lightweighting pressure and fluorinated alternatives face EU F-Gas Regulation quota restrictions.
- Single Coated Films:One-side PVDC layers on BOPP or PET substrates for modified-atmosphere meat and cheese formats where cost sensitivity limits multilayer complexity.
- Double Coated Films:Symmetrical PVDC coatings on both substrate faces delivering enhanced moisture barrier for tropical climate distribution of snack and confectionery products.
Barrier Films holds the largest share; momentum sits with Specialty Coated Films as aseptic applications displace conventional packaging formats.
Application:
Pharmaceutical Packaging commands premium pricing through validation-intensive specifications, while Food Packaging anchors volume through fragmented converter networks serving retail distribution.
- Food Packaging:Modified-atmosphere formats for meat, cheese, and snack products requiring oxygen and moisture exclusion to extend shelf life. Domestic flexible packaging output in China is scaling rapidly as SAMR enforces GB standards for composite food packaging that increasingly reference PVDC layer adhesion and solvent residue thresholds.
- Pharmaceutical Packaging:Blister packs, cold-form foil laminates, and strip packs demanding sub-1 cc/m²/day oxygen transmission rates for temperature excursion-sensitive biologics. CDSCO serialization mandates in India are expanding validated barrier film requirements as cold-chain infrastructure develops.
- Cosmetic Packaging:Fragrance and skincare sachets utilizing PVDC barriers to prevent volatile ingredient loss and moisture ingress.
- Industrial Wrapping:Corrosion-inhibiting films for metal components and precision machinery requiring humidity protection during extended storage or maritime shipment.
Food Packaging generates the highest shipment volumes; Pharmaceutical Packaging captures the steepest expansion trajectory as biologics distribution networks proliferate.
End User:
Pharmaceutical Manufacturers impose the most stringent qualification protocols, while Packagers serve as the aggregation point for fragmented food and cosmetic brand demand.
- Packagers:Contract converters serving multiple brand owners across food, cosmetic, and industrial segments with flexible equipment configurations and rapid changeover capabilities.
- Pharmaceutical Manufacturers:Integrated drug producers requiring direct film supply relationships to manage ISO 15378 GMP certification cycles and quarterly certificate-of-analysis documentation.
- Cosmetic Producers:Beauty and personal care brands sourcing sachet and sample formats with fragrance barrier requirements.
- Industrial Suppliers:Logistics and manufacturing service providers procuring corrosion protection films for metal finishing and equipment preservation.
Pharmaceutical Manufacturers represent the most concentrated value pool; Packagers aggregate the broadest volume base across customer segments.
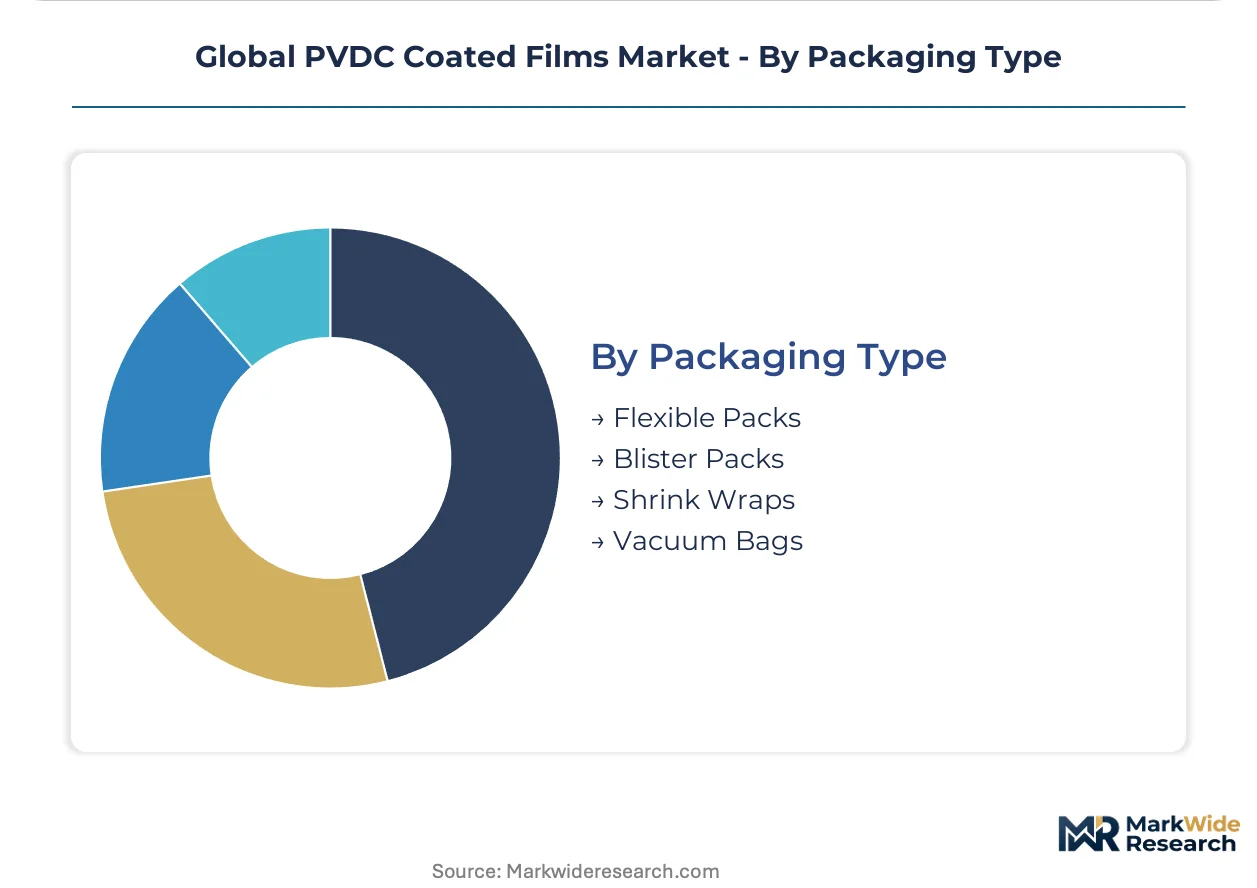
Packaging Type:
Blister Packs and Flexible Packs split the market between rigid pharmaceutical validation requirements and adaptable food distribution formats.
- Flexible Packs:Rollstock and preformed pouches for horizontal and vertical form-fill-seal operations across food and industrial applications. Water-based PVDC emulsion retrofits are reducing solvent recovery capex for domestic producers in China under MEE emissions standards.
- Blister Packs:Thermoformed cavities with lidding foil constructions for unit-dose pharmaceutical distribution. German and Swiss manufacturers are piloting aqueous coating lines to eliminate solvent recovery infrastructure and decompose regional supply advantages tied to volatile organic compound permitting.
- Shrink Wraps:PVDC-coated films providing clarity and barrier during heat-shrink consolidation of multi-unit retail packs.
- Vacuum Bags:Chamber-sealable constructions for protein and cheese products requiring oxygen exclusion under mechanical compression.
Flexible Packs command the widest application range; Blister Packs are gaining share fastest as serialization mandates proliferate across national pharmaceutical regulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers in Germany, China, and India concentrate validated PVDC film procurement, while food packagers in Japan and the United States drive specialty coated film volumes for modified-atmosphere and retort applications.
Germany
Blister pack serialization mandates from the country's national pharmaceutical regulator compress coating tolerance specifications for domestic converters. EU REACH Annex XVII chlorine-bearing polymer restrictions filter supplier pools serving European export markets. The Rhine-Main cluster around Frankfurt anchors aqueous coating line pilot programs eliminating solvent recovery infrastructure.
China
Domestic flexible packaging output scales rapidly as cold-chain pharmaceutical distribution networks proliferate in tier-one cities. SAMR enforces GB standards for composite food packaging with escalating PVDC layer adhesion and solvent residue thresholds. The Yangtze River Delta concentration of coating facilities retrofits water-based emulsion lines under MEE emissions standards.
India
Underdeveloped pharmaceutical cold-chain infrastructure presents positioning opportunities for validated barrier film suppliers. CDSCO serialization mandates expand lot-level traceability requirements across domestic drug distribution. Maharashtra's Mumbai-Pune industrial corridor concentrates contract packaging operations awaiting ISO 15378 GMP certification upgrades.
Japan
Ready-meal format lightweighting pressures displace metal cans with sterilization-stable PVDC laminates for aseptic retort applications. METI industrial standards shape migration testing protocols for domestic food-contact specifications. The Kansai region around Osaka maintains specialty coated film capacity for high-barrier medical device packaging.
United States
FDA food-contact notification requirements and evolving standards reshape formulation choices for film exporters serving North American pharmaceutical accounts. Quarterly certificate-of-analysis updates replace annual compliance documentation at Midwest distribution hubs. The Southeast packaging corridor concentrates flexible film converting for modified-atmosphere protein formats.
Global PVDC Coated Films Market Competitive Landscape
Player mix skews toward integrated resin-to-film manufacturers and captive substrate producers, creating a tiered structure where backward integration into biaxial orientation lines determines margin capture. Three archetypes dominate: resin chemistry specialists controlling polymer supply, integrated film producers with captive coating capacity, and independent converters dependent on long-term offtake arrangements. Competitive moves center on substrate-coater integration decisions and aqueous coating technology licensing to decompose regional permitting advantages.
Within the integrated substrate tier, Cosmo Films Ltd. and Jindal Poly Films Limited exemplify producers leveraging captive biaxial orientation lines. Kureha Corporation occupies a distinct position as the resin chemistry anchor supplying polymer downstream. These three entities represent the concentration points where substrate quality control and coating tolerance specifications intersect.
| Leading Market Players |
|---|
| Cosmo Films Ltd. |
| Jindal Poly Films Limited |
| SKC Inc. |
| Vibac Group S.P.A. |
| Kureha Corporation |
| SKF Limited |
| Polinas Corporate |
| Mondi Group plc. |
| Toray Industries Inc. |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four-month ISO 15378 GMP certification timelines concentrate pricing power with validated suppliers while compressing margins for converters lacking backward integration into biaxial orientation lines. Pharmaceutical manufacturers absorb premium pricing for quarterly certificate-of-analysis documentation, whereas food packagers negotiate on solvent residue thresholds and coating tolerance specifications.
Pricing Analysis
Cost-plus contracts with VCM monomer indexation dominate long-term offtake arrangements between Kureha Corporation and downstream coaters. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and industrial wrapping levels separates validation-intensive blister laminates from modified-atmosphere meat formats. Pricing pressure stems from EVOH multilayer substitution in clarity-sensitive applications where recyclability outweighs absolute barrier performance. Food packagers exhibit highest price sensitivity due to fragmented converter networks, while pharmaceutical manufacturers prioritize coating tolerance consistency over unit cost.
Supply Chain Analysis
Strategic stockpiling of PVDC resin prevails among coaters lacking long-term offtake arrangements, whereas just-in-time substrate flows characterize integrated producers with captive biaxial orientation lines. Supply concentrates in Japan, India, and Germany where resin chemistry specialists, integrated film producers, and pharmaceutical validation clusters anchor production. Raw material dependencies center on VCM monomer, polyester substrates, and solvent-based coating chemicals. Single-source vulnerability in PVDC resin chemistry creates structural risk for independent converters. Distribution runs through converter-buyer direct relationships for pharmaceutical accounts and fragmented wholesaler networks for food packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EVOH multilayer films and fluorinated polymer alternatives are reshaping competitive positioning in barrier applications, forcing PVDC incumbents to defend substitution-prone segments through chemistry innovation and regulatory compliance acceleration.
For Market Incumbents: Compound certification advantages by accelerating aqueous coating line pilots ahead of EU F-Gas Regulation phase-downs. Deepen backward integration into biaxial orientation lines to capture substrate quality control margins currently surrendered to captive suppliers. Prioritize ISO 15378 GMP certification cycles as defensive moats against EVOH substitution in pharmaceutical serialization applications. For New Entrants and Emerging Players: Anchor in India's underdeveloped cold-chain infrastructure where CDSCO serialization mandates expand validated barrier film requirements. Target Maharashtra's Mumbai-Pune industrial corridor for contract packaging operations awaiting ISO 15378 upgrades. Pursue water-based emulsion coating licensing to bypass solvent recovery capex barriers protecting incumbent regional positions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across water-based coating retrofits as MEE emissions standards incentivize equipment conversions. Long-term viability favors integrated resin-to-film manufacturers with captive substrate production and pharmaceutical validation relationships. Monitor aqueous coating technology adoption rates as inflection indicator for regional supply advantage decomposition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biaxial Orientation Lines | Captures substrate quality control margins from resin extrusion through finished roll at Cosmo Films and Jindal Poly. |
| Water-Based Emulsion Coating Retrofit | Eliminates solvent recovery infrastructure burdens under Germany's volatile organic compound permitting constraints. |
| Long-Term Resin Offtake Arrangement | Secures VCM monomer supply from Kureha Corporation against single-source vulnerability for downstream coaters. |
| ISO 15378 GMP Certification Acceleration | Freezes converter capacity allocation decisions for 18-24 month validation cycles serving pharmaceutical manufacturers. |
| Aqueous Coating Technology Licensing | Decomposes regional supply advantages tied to solvent permitting in Rhine-Main and Yangtze River Delta clusters. |
Research Methodology
Operator-level perspectives from coating line engineers, pharmaceutical packaging procurement managers, flexible film converters, resin chemistry R&D directors, and SAMR compliance officers anchored the qualitative base. Primary interview findings triangulated against secondary validation from customs trade databases, FDA food-contact notification filings, ECHA REACH Annex XVII restriction updates, and SEC 10-K disclosures from integrated film producers. Bottom-up volume modeling across product type, application, end user, and packaging type dimensions converged with top-down macroeconomic sanity checks.
Sensitivity analysis tested forecast robustness across regulatory divergence scenarios, substitution elasticity parameters, and cold-chain infrastructure buildout trajectories. Segmentation dimensions modeled include barrier performance tier, substrate material, coating chemistry, end-use industry, and regional regulatory cluster. CAGRs derived from logistic curve fitting to historical shipment data, adjusted for capacity expansion announcements and certification cycle timelines. Forecast inputs incorporated EVOH substitution rates, aqueous coating adoption curves, and pharmaceutical serialization mandate implementation schedules.
Material uncertainties — VCM monomer supply disruptions, REACH migration testing burden escalations, and EVOH clarity improvements — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification cycle stability and regulatory fragmentation persistence. Revision becomes warranted when aqueous coating technology adoption crosses threshold penetration in European pharmaceutical packaging or when India cold-chain infrastructure investment accelerates beyond baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Stretch Films Packs Market
Poly film
North America Polyimide Films Market
Poly film
Middle East and Africa Plastic Packaging Films Market
Poly film
Co Extruded Films Market
Poly film
Global EVOH Films for Packaging Market
Poly film
Nylon Films for Liquid Packaging Market
Poly film
Peelable and Resealable Films Market
Poly film
PVC Film for Medical Market
Poly film
Polyolefin Battery Separator Films Market
Poly film
Global Specialty Films Polymer Market
Poly film
Polyvinyl Alcohol (PVA) Films Market
Poly film
Polyethylene Film Market
Poly film
Polysaccharide Films Market
Poly film
Japan Polypropylene Packaging Films Market
Poly film
North America BOPP Films Market
Poly film
Polytetrafluoroethylene (PTFE) Films Market