
 Global Beverage Container Market | 2026-2036
Global Beverage Container Market Size, Share, and Industry Trends Forecast 2026-2036
Global Beverage Container Market Analysis
Lightweighting technology and recycled content integration is reshaping beverage container manufacturing economics and design protocols. Crown Holdings leverages its global metal packaging footprint to sustain supply relationships with multinational brewers and soft drink bottlers. Ball Corporation anchors North American aluminum can supply through integrated recycling and rolling operations. Amcor Limited competes across flexible and rigid plastic formats with specialized barrier technologies for carbonated and still beverages.
Beverage containers are engineered enclosures designed to preserve liquid product integrity, prevent contamination, and enable efficient distribution through specified pressure ratings, thermal stability thresholds, and seal performance metrics. Metal containers, particularly aluminum cans, dominate volume throughput due to infinite recyclability and rapid chilling properties that align with retail cold-chain requirements. Plastic formats lead in lightweight logistics efficiency and shape flexibility for sports drinks and enhanced waters, while glass maintains premium positioning in wine and craft spirits segments where oxygen transmission rates and aesthetic weight signal quality. Closure type selection directly influences shelf-life extension and consumer convenience, with screw caps displacing traditional cork in mainstream wine and twist-off formats gaining share in ready-to-drink categories.
The EPA governs recycled content claims and waste stream management for containers sold in the United States, while the EU Green Deal and REACH framework mandate extended producer responsibility and restricted substance thresholds across European supply chains. FDA food-contact regulations in the United States and EFSA standards in Europe determine permissible material compositions and migration limits for all beverage-contact surfaces. Stakeholders must monitor evolving packaging waste legislation across multiple jurisdictions to anticipate material substitution requirements and compliance cost structures.
Market Dynamics
The EU Green Deal's extended producer responsibility mandates are compressing material transition timelines across beverage container supply chains, forcing simultaneous investment in recycled content infrastructure and lightweighting R&D.
Growth Catalysts
- EU Green Deal packaging waste directives:Mandatory recycled content thresholds are pulling forward capital deployment into aluminum re-melt and rPET flake capacity across export-oriented manufacturing hubs.
- Ready-to-drink coffee and functional beverage expansion:Brands are procuring specialized barrier cans and hot-fill bottles as on-the-go consumption patterns concentrate demand in single-serve formats.
- Southeast Asia bottling cluster formation:Vietnam, Indonesia, and Thailand are attracting greenfield container manufacturing investments to serve regional beverage production growth.
Market Restraints
- Aluminum ingot price volatility:Primary metal cost swings compress margin predictability for can manufacturers locked into annual supply contracts with brewers and soft drink bottlers.
- rPET feedstock scarcity:Collection infrastructure gaps in key markets limit food-grade recycled resin availability, constraining compliance with EU and state-level recycled content mandates.
- Glass furnace restart economics:High natural gas and electricity intensity makes European container glass production structurally disadvantaged against imported alternatives.
Strategic Opportunities
- India beverage manufacturing growth:FSSAI packaging regulations and PLI scheme incentives for food processing are creating demand for aseptic carton and PET bottle capacity.
- Digital printing on metal:Direct-to-can decoration technology enables micro-batch customization for craft brewers and seasonal limited releases without plate changeover costs.
- Refillable bottle system revival:Deposit-return scheme expansions in Germany, Denmark, and emerging markets are reopening closed-loop glass logistics as a viable service model.
Industry Challenges
- Migration testing protocol complexity:EFSA and FDA food-contact substance evaluation timelines create 18-24 month delays for novel barrier coatings and bio-based materials.
- Multi-jurisdiction labeling convergence:Divergent nutrition declaration formats and recycling symbol requirements across EU member states, US states, and Asian markets multiply SKU complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Beverage Container Market |
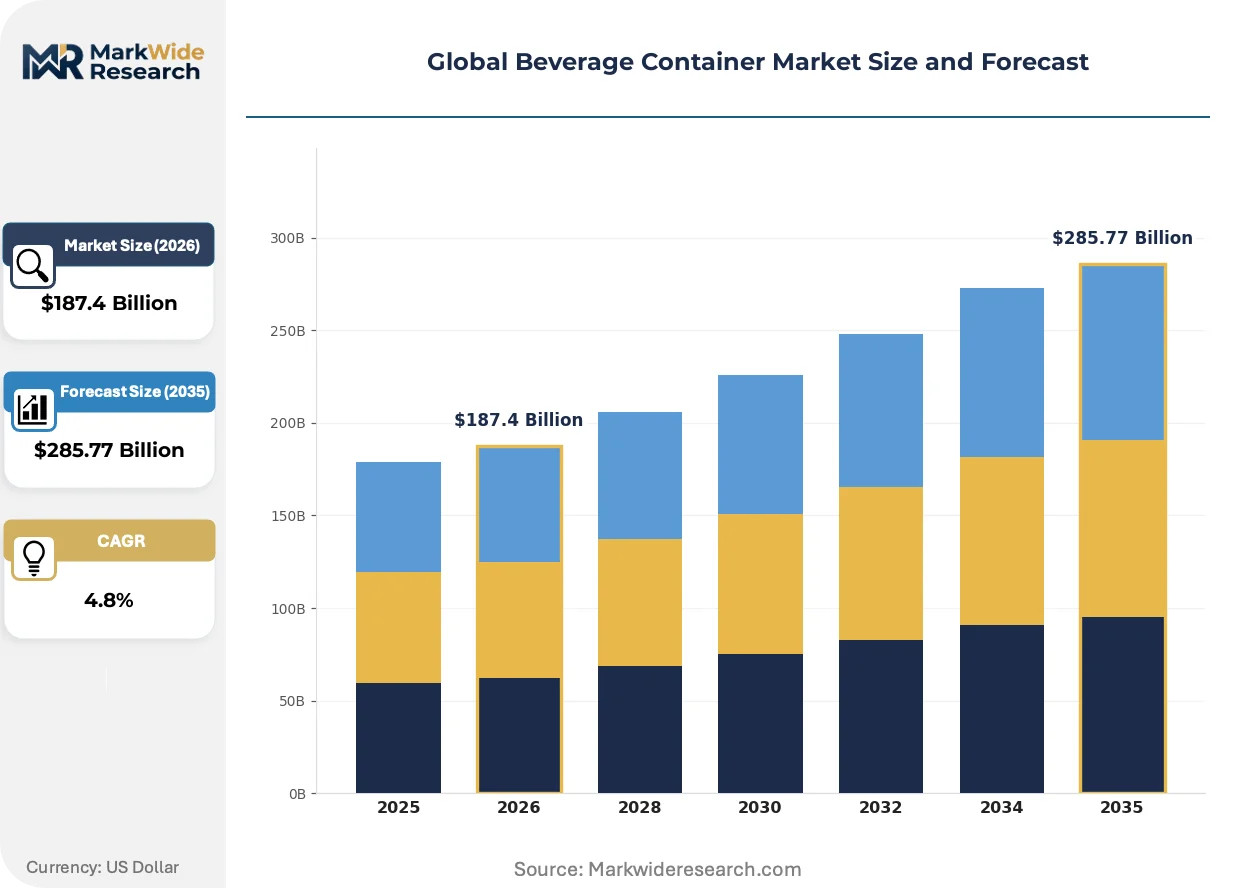
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Metal, Glass, Paper Container Size: Small, Medium, Large, Extra Large Closure Type: Screw Cap, Snap-On, Cork, Twist-Off Usage Category: Single-Use, Reusable, Bulk, Premium |
| Companies Covered | Crown Holdings, Owens-Illinois, Amcor Limited, Toyo Seikan Group Holdings, Rexam Inc., Ball Corporation, Silgan Holdings, Mondi Group, Ardagh Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Beverage Container Market Emerging Trajectories
Material science breakthroughs and regulatory compression are simultaneously enabling lighter-weight containers and stricter performance requirements, reshaping competitive advantage around integrated recycling capabilities rather than virgin material access.
Digital printing technology is digitizing beverage container decoration workflows by replacing mechanical plate systems with inkjet deposition that enables variable data and short-run economics. Craft breweries and functional beverage startups are adopting this capability for market testing and regional customization without minimum order constraints. The technology is digitizing brand-owner relationships with packaging suppliers by collapsing design-to-shelf timelines from weeks to days.
REACH substance restrictions and EU Green Deal packaging waste regulations are mandating elimination of certain epoxy-based can linings and perfluorinated barrier treatments. Container manufacturers are reformulating internal coatings and accelerating migration to polyester and oleoresin alternatives. Aluminum can producers serving European export markets face the most compressed compliance timelines and are qualifying new lining systems ahead of 2026 restriction phases.
Direct-to-consumer beverage subscription models are fragmenting traditional bulk procurement relationships between container suppliers and national bottlers. Smaller batch sizes and mixed-SKU pallets are displacing full-truckload can and bottle orders in the craft and premium segments. This pattern is most visible in North American and Western European markets where e-commerce alcohol delivery regulations have loosened and DTC fulfillment infrastructure has matured.
Global Beverage Container Market Segmentation
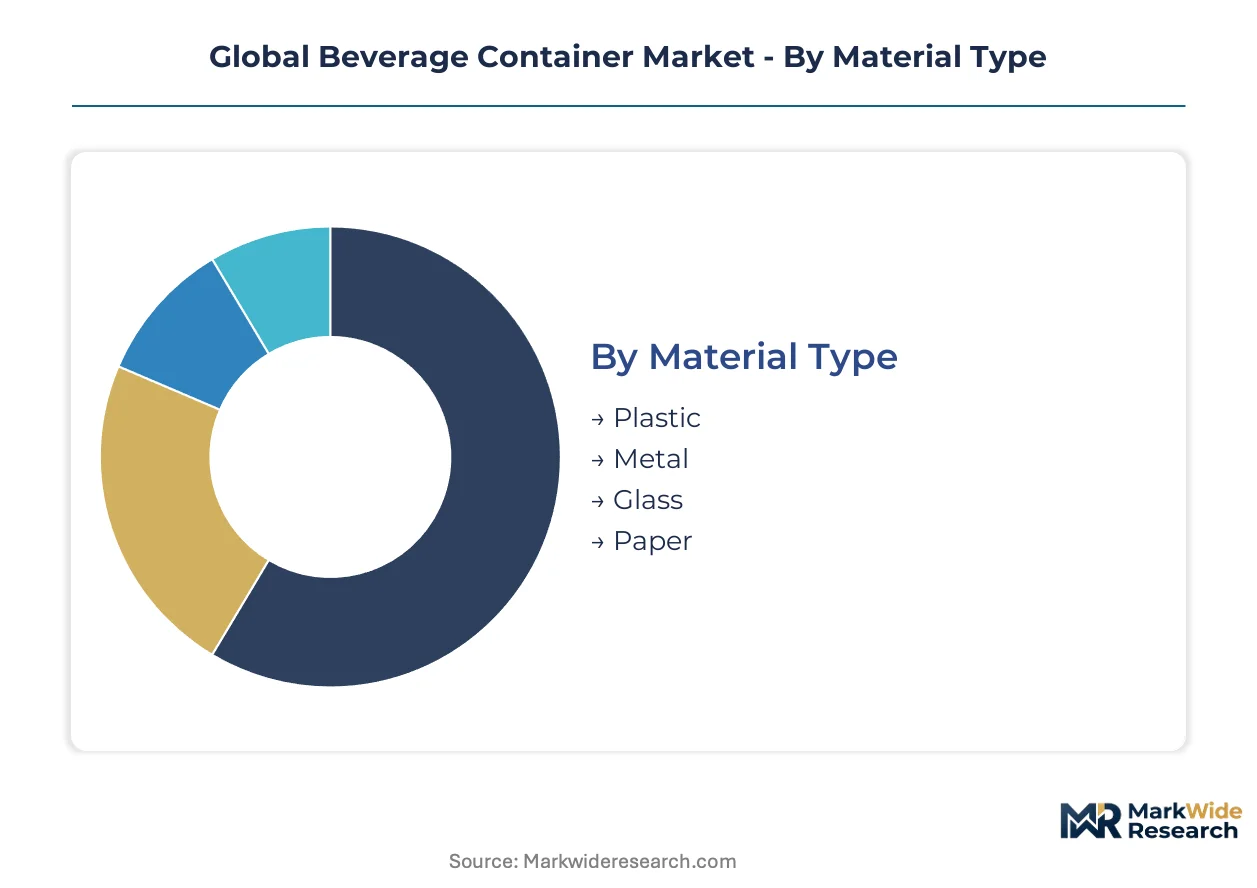
Beverage container procurement decisions cascade across material specifications, dimensional requirements, and regulatory compliance tiers. Each segmentation axis carries distinct aftermarket service intensity and supply chain configuration implications.
Material Type:
After-sales service intensity varies sharply by material substrate, with metal and glass demanding specialized reclamation infrastructure versus plastic's established collection networks.
- Metal:Aluminum and steel containers deliver infinite recyclability through re-melt processes that recover material without quality degradation. EU Green Deal mandates are accelerating can-to-can closed-loop investments in Germany, Denmark, and the Netherlands as extended producer responsibility schemes tighten compliance windows.
- Plastic:PET, HDPE, and polypropylene formats dominate lightweight logistics applications with barrier-coated multilayer constructions for carbonated and sensitive beverages. rPET feedstock scarcity in Southeast Asian collection markets constrains compliance with EU recycled content thresholds for export-bound production.
- Glass:Soda-lime and borosilicate containers maintain premium positioning through oxygen transmission control and aesthetic weight signaling.
- Paper:Aseptic cartons and molded fiber formats serve ambient-stable milk and juice categories with laminated barrier structures.
By volume, Plastic leads. By growth pace, Metal is ahead.
Container Size:
Cost tier differentiation separates commodity single-serve formats from engineered bulk solutions with specialized handling equipment requirements.
- Small:Sub-250ml formats concentrate in energy shots, functional wellness concentrates, and airline hospitality procurement. Japanese vending machine networks and Southeast Asian convenience store chains anchor demand concentration for miniaturized aluminum and PET constructions.
- Medium:250ml to 500ml containers represent the standard single-serve configuration across carbonated soft drinks, ready-to-drink coffee, and premium water categories.
- Large:500ml to 1.5L bottles serve family consumption and foodservice fountain refill applications with reduced per-ounce packaging cost profiles.
- Extra Large:Above-1.5L formats target institutional catering, e-commerce bulk subscription, and warehouse club retail channels with pallet-optimized cube efficiency.
Medium formats dominate unit shipments. Small formats are expanding most quickly.
Closure Type:
Application-specific sealing performance dictates closure selection, with carbonation retention requirements and reseal convenience driving specification divergence across beverage categories.
- Screw Cap:Threaded polypropylene and aluminum closures deliver reseal functionality for still beverages, sports drinks, and functional waters. German mineral water producers and US premium bottled water brands specify tamper-evident band configurations with torque-release calibration.
- Snap-On:Press-fit polyethylene closures serve value-tier still water and juice categories with lowest-cost sealing economics.
- Cork:Natural and synthetic cork maintains wine industry tradition with oxygen transmission modulation for cellar-aged products.
- Twist-Off:Threaded metal lug closures enable tool-free opening for ready-to-drink cocktails, hard seltzers, and aluminum bottle formats.
Screw Cap commands installed base. Twist-Off is climbing the fastest.
Usage Category:
Customer type stratification separates institutional procurement with deposit-return obligations from premium brand positioning with extended shelf-life engineering.
- Single-Use:Designed-for-recycling containers dominate volume throughput with optimized lightweighting for one-way collection infrastructure. EU packaging waste directives and US state extended producer responsibility legislation are compressing design-for-recycling requirements across export supply chains.
- Reusable:Returnable bottle systems with standardized washing and refill protocols are reviving in Germany, Denmark, and emerging deposit-return markets as closed-loop logistics mature.
- Bulk:Bag-in-box, keg, and intermediate bulk containers serve foodservice fountain, winery, and brewery tanker applications with minimized per-liter packaging cost.
- Premium:Heavy-weight glass, decorated metal, and specialty closures signal quality positioning in craft spirits, estate wines, and limited-release beverages.
Single-Use holds volume leadership. Reusable shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational brewers and ready-to-drink brands concentrate procurement decisions in manufacturing hubs with integrated recycling infrastructure and favorable regulatory treatment. Container suppliers align capacity investments with these buyer clusters.
United States
Aluminum can demand from craft brewers and hard seltzer brands drives specialized container procurement. FDA food-contact regulations and EPA recycled content claims govern material compliance. Texas and the Pacific Northwest host aluminum rolling and re-melt facilities serving domestic beverage production.
Germany
Deposit-return scheme density and refillable bottle system revival create dual-track container demand. EU Green Deal extended producer responsibility mandates accelerate can-to-can closed-loop investments. Bavaria and North Rhine-Westphalia concentrate glass furnace and aluminum can manufacturing serving Central European markets.
China
Domestic beverage brand expansion and export-oriented manufacturing pull container capacity growth. GB standards and SAMR food-contact regulations determine material specifications. The Yangtze River Delta and Pearl River Delta cluster PET bottle and aseptic carton production for regional and global supply chains.
Vietnam
Regional beverage manufacturing relocation and greenfield bottling investments concentrate procurement demand. FSSAI-aligned packaging regulations for export-bound production shape compliance requirements. Ho Chi Minh City and Hanoi anchor new aluminum can and PET bottle capacity serving Southeast Asian markets.
India
Aseptic carton and PET bottle demand from dairy and juice processors expands with cold-chain infrastructure. FSSAI packaging regulations and PLI scheme incentives for food processing attract manufacturing investment. Maharashtra and Gujarat host emerging beverage container production clusters serving domestic consumption growth.
Global Beverage Container Market Vendor Landscape
Channel-controlling players compete with product-specialist players across material substrates and closure technologies. The vendor base organizes around three archetypes: integrated metal packaging conglomerates with global recycling footprints, flexible and rigid plastic specialists with barrier technology portfolios, and regional glass and paperboard fabricators serving premium and ambient-stable categories. Competitive moves concentrate on M&A for recycling infrastructure control and capacity expansion in Southeast Asian manufacturing hubs.
Among North American metal packaging leaders, Ball Corporation and Crown Holdings exemplify integrated recycling-to-can manufacturing archetypes. Amcor Limited occupies a position spanning flexible and rigid plastic formats with specialized barrier capabilities. Toyo Seikan Group Holdings represents Asia-Pacific container diversification across metal, plastic, and paper substrates.
| Leading Market Players |
|---|
| Crown Holdings |
| Owens-Illinois |
| Amcor Limited |
| Toyo Seikan Group Holdings |
| Rexam Inc. |
| Ball Corporation |
| Silgan Holdings |
| Mondi Group |
| Ardagh Group |
| Others |
Supply Flow & Price Mechanics
Aluminum ingot price volatility compresses margin predictability for can manufacturers and simultaneously widens pricing tier spreads between virgin-material and recycled-content supply chains. This commodity exposure forces brewers and soft drink bottlers into annual contract renegotiations that reshape procurement relationships across export-oriented manufacturing hubs.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate aluminum can procurement between multinational brewers and metal packaging suppliers. Price differentiation rests on recycled content thresholds and EU Green Deal compliance certification tiers. Cost compression in standard-grade containers is intensifying because rPET feedstock scarcity constrains food-grade resin availability. Value-tier bottlers exhibit highest price sensitivity, while premium craft spirits brands prioritize oxygen transmission performance over unit economics.
Supply Chain Analysis
Contract manufacturing concentration sits with Ball Corporation, Crown Holdings, and Ardagh Group across North American and European aluminum rolling and re-melt facilities. Geographic supply concentration centers on Germany, Vietnam, and China for can-to-can closed-loop infrastructure. Raw material dependencies draw from bauxite refining, primary aluminum smelting, and post-consumer PET flake collection networks. Single-source vulnerability runs through Southeast Asian rPET washing and pelletizing capacity. Distribution runs through pallet-optimized full-truckload shipments to regional bottling clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Beverage Container Market sits at a cyclical recovery phase driven by EU Green Deal packaging waste directive implementation. Mandatory recycled content thresholds are pulling forward capital deployment into aluminum re-melt and rPET flake capacity.
For Market Incumbents: Entrench closed-loop recycling infrastructure through captive control of post-consumer collection networks in Germany and Vietnam. Defend margin position by qualifying polyester and oleoresin can lining alternatives ahead of REACH substance restriction phases. Capacity addition in Ho Chi Minh City bottling clusters secures regional procurement relationships with expanding ready-to-drink brands. For New Entrants and Emerging Players: Establish a beachhead in digital direct-to-can decoration services for craft brewery micro-batch customization. White-space concentration in aseptic carton capacity serving Indian dairy and juice processors offers lowest competitive density. Go-to-market leverage rests on FSSAI packaging regulation compliance advisory bundled with container supply. For Investors and Strategic Acquirers: The market sits at a regulatory compression phase that favors integrated recycling-to-manufacturing archetypes over virgin-material-dependent operators. Long-term viability across the five-to-ten-year window rests on aluminum re-melt asset control and deposit-return scheme logistics infrastructure. Acquisition target archetype: mid-cap specialists with Southeast Asian manufacturing footprints and EU export compliance capabilities. The signal to watch is state-level extended producer responsibility legislation passage in US beverage markets.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Infrastructure Buildout | Ball Corporation's aluminum re-melt investments in Texas secure can-to-can closed-loop supply for craft brewers. |
| Digital Printing Technology Adoption | Crown Holdings' direct-to-can decoration capability collapses design-to-shelf timelines from weeks to days for seasonal releases. |
| Southeast Asian Manufacturing Expansion | Greenfield PET bottle capacity in Vietnam serves relocating beverage production from China tariff exposure. |
| Barrier Coating Reformulation | Amcor's polyester and oleoresin alternatives replace epoxy linings ahead of EU Green Deal restriction phases. |
| Deposit-Return Scheme Logistics | Ardagh Group's refillable bottle system revival in Germany reopens closed-loop glass as a viable service model. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with beverage procurement directors, container manufacturing plant managers, aluminum rolling mill operators, and retail category buyers. Secondary validation drew from EPA recycled content filings, EU Green Deal implementation progress reports, FDA food-contact substance databases, and customs trade data for aluminum ingot and rPET flake flows. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections.
Calibration against historical aluminum can shipment data and PET bottle production statistics anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include material substrate, container size tier, closure technology, and usage category with regional regulatory cluster overlays. CAGRs were derived from trend extrapolation moderated by regulatory mandate implementation timelines and raw material cost cycle positioning. Forecast inputs incorporated EU packaging waste directive compliance cost structures and Southeast Asian collection infrastructure buildout rates.
Stress conditions across aluminum ingot price swings, rPET feedstock availability gaps, and glass furnace restart economics were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal phase-in schedules and state-level extended producer responsibility adoption patterns. Quarterly review of LME aluminum pricing volatility and deposit-return scheme expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Cold Beverage Cups Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Tumblers Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Beverage Cups Market
Beverage Packaging
Middle East and Africa Soft Drinks Packaging Market
Beverage Packaging
North America Beverage Packaging Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Juice Packaging Market
Beverage Packaging
Multicomponent Bottle Market
Beverage Packaging
Sugarcane Bottles Market
Beverage Packaging
Bottle Shippers Market
Beverage Packaging
Foamer Bottle Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
US Beverage Packaging Market