
 Cold Beverage Cups Market | 2026-2036
Cold Beverage Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Beverage Cups Market Analysis
Buyer concentration in the quick-service restaurant channel is shifting as national chains consolidate purchasing while regional beverage concepts fragment demand across smaller distributors. Huhtamaki leverages its European fiber-forming expertise to supply compostable cold cups to major coffee and juice chains. Dart Container anchors North American production through its integrated foam and plastic cup manufacturing network. Georgia-Pacific competes in the paper-based segment with cupstock capacity tied to its broader packaging infrastructure.
Cold beverage cups are single-use or reusable vessels engineered to contain chilled drinks between 0°C and 10°C, typically constructed from extruded polystyrene, polypropylene, coated paperboard, or molded fiber with moisture barriers applied through spray or dip coating. Their primary commercial purpose is to maintain beverage temperature, prevent condensation leakage, and provide printable surfaces for brand communication in away-from-home consumption settings. The material type dimension shows plastic retaining volume leadership in emerging markets while biodegradable substrates capture premium positioning in regulated European and North American cities. Size segmentation tilts toward medium and large formats as fountain drink portions expand in quick-service settings. The functionality split reveals custom printed cups commanding margin premiums through brand-contracted supply agreements, while insulated variants sustain pricing power in specialty coffee and bubble tea applications.
The US FDA regulates food-contact substances in cup substrates and liners, while the EPA oversees per- and polyfluoroalkyl substance restrictions that are reshaping barrier coating formulations across the industry. The EU REACH framework and Single-Use Plastics Directive restrict certain polymer grades and mandate labeling schemes that affect export-oriented manufacturers. India's BIS certification requirements for food-contact plastics and the country's Plastic Waste Management Rules create compliance thresholds for multinational suppliers entering that market. Stakeholders must monitor evolving extended producer responsibility schemes and material bans to align capacity investments with jurisdiction-specific compliance timelines.
Market Dynamics
The EU Single-Use Plastics Directive and parallel state-level mandates in California are forcing material transitions across the cold beverage cup supply chain, compressing polystyrene volumes while accelerating fiber-based and biodegradable substrate capacity investments.
Growth Catalysts
- California SB 54 Extended Producer Responsibility:The state's packaging reduction mandates are pulling fiber-forming capacity into West Coast distribution networks, creating guaranteed offtake for compostable cup producers.
- Bubble tea and specialty coffee expansion:Cold beverage concepts across Taiwan, South Korea, and Vietnam are standardizing large-format insulated cups, driving premium material specifications.
- India's Plastic Waste Management Rules:The 2022 amendments banning select single-use plastics are redirecting quick-service restaurant procurement toward paperboard alternatives in Mumbai and Bangalore.
Market Restraints
- Fluoropolymer barrier coating restrictions:EPA oversight of per- and polyfluoroalkyl substances is eliminating conventional moisture barrier chemistries, forcing costly formulation redevelopment.
- Pulp supply concentration:Nordic and Brazilian pulp producers control the bleached eucalyptus and softwood fiber streams essential for food-grade cupstock, exposing converters to input volatility.
- Performance gaps in biodegradable substrates:Current PLA and PHA blends exhibit inferior cold-crack resistance below 5°C, limiting their deployment in frozen beverage applications.
Strategic Opportunities
- Indonesia's quick-service underpenetration:Cold beverage cup consumption per capita in Jakarta and Surabaya remains one-fifth of Bangkok levels, presenting volume expansion potential as Western chains localize.
- Reusable cup-as-a-service models:Deposit-return schemes in Berlin and Paris are creating infrastructure for stainless-steel and durable polymer alternatives to single-use formats.
- Spray-applied bio-based barrier convergence:The pairing of nanocellulose dispersions with existing paperboard forming lines offers retrofit pathways for mid-scale converters.
Industry Challenges
- Food-contact certification timelines:FDA and EFSA novel food-contact substance approvals for emerging barrier coatings extend 18-36 months, delaying product launches.
- Legacy thermoforming asset stranding:Polystyrene-dedicated tooling and extrusion lines face accelerated depreciation as buyer specifications exclude fossil-based polymers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Beverage Cups Market |
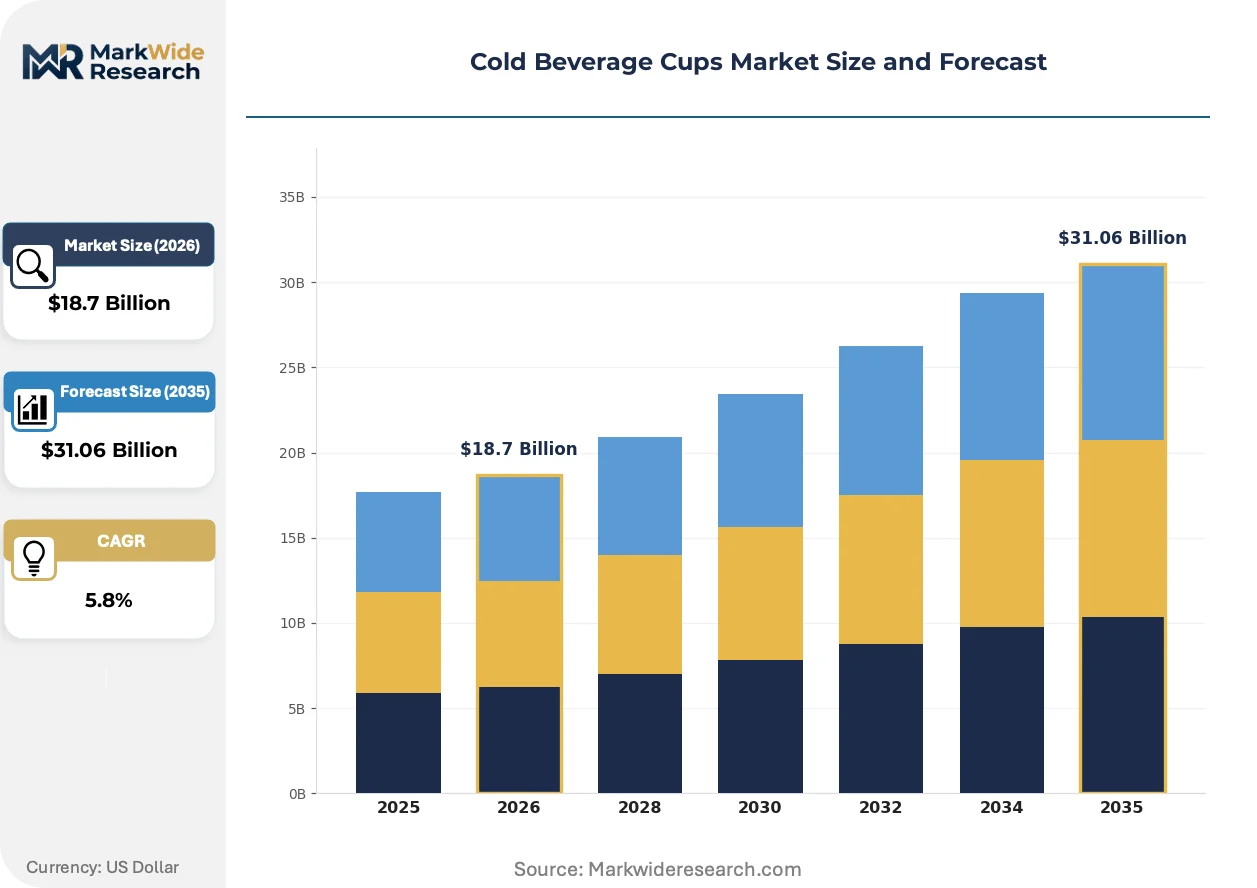
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Foam, Biodegradable Size: Small, Medium, Large, Extra Large End User: Restaurants, Cafes, Events, Retail Stores Functionality: Disposable, Reusable, Insulated, Custom Printed |
| Companies Covered | Dart Container, Huhtamaki, Georgia-Pacific, Berry Global, Pactiv Evergreen, Genpak, WestRock Company, Graphic Packaging International, Eco-Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Beverage Cups Market Emerging Trajectories
Material science advances and regulatory stringency are converging to reshape competitive positioning in cold beverage cup manufacturing, with barrier technology and end-of-life credentials now primary differentiation vectors.
Molded fiber with spray-applied bio-based barriers is rewriting the technical feasibility of plastic-free cold cups. Quick-service chains in California and the Netherlands are piloting these formats for iced coffee and fountain beverages. The technology is compressing the cost premium between conventional plastic and fiber alternatives from 40% to 15% at commercial scale.
The EU Single-Use Plastics Directive's labeling and consumption reduction targets are restructuring export compliance requirements. Manufacturers serving European quick-service accounts must now maintain dual material certifications and traceability documentation. Small and mid-scale converters in Turkey and Poland are responding by consolidating testing and certification functions through shared service platforms.
Chain-level sustainability scorecards are altering procurement evaluation criteria. Major quick-service buyers in the United States now weight end-of-life attributes at 30% of total supplier score, displacing price-per-thousand as the dominant selection metric. This shift is most visible in Florida and Texas, where coastal municipality bag and cup bans have preceded state-level action.
Cold Beverage Cups Market Segmentation
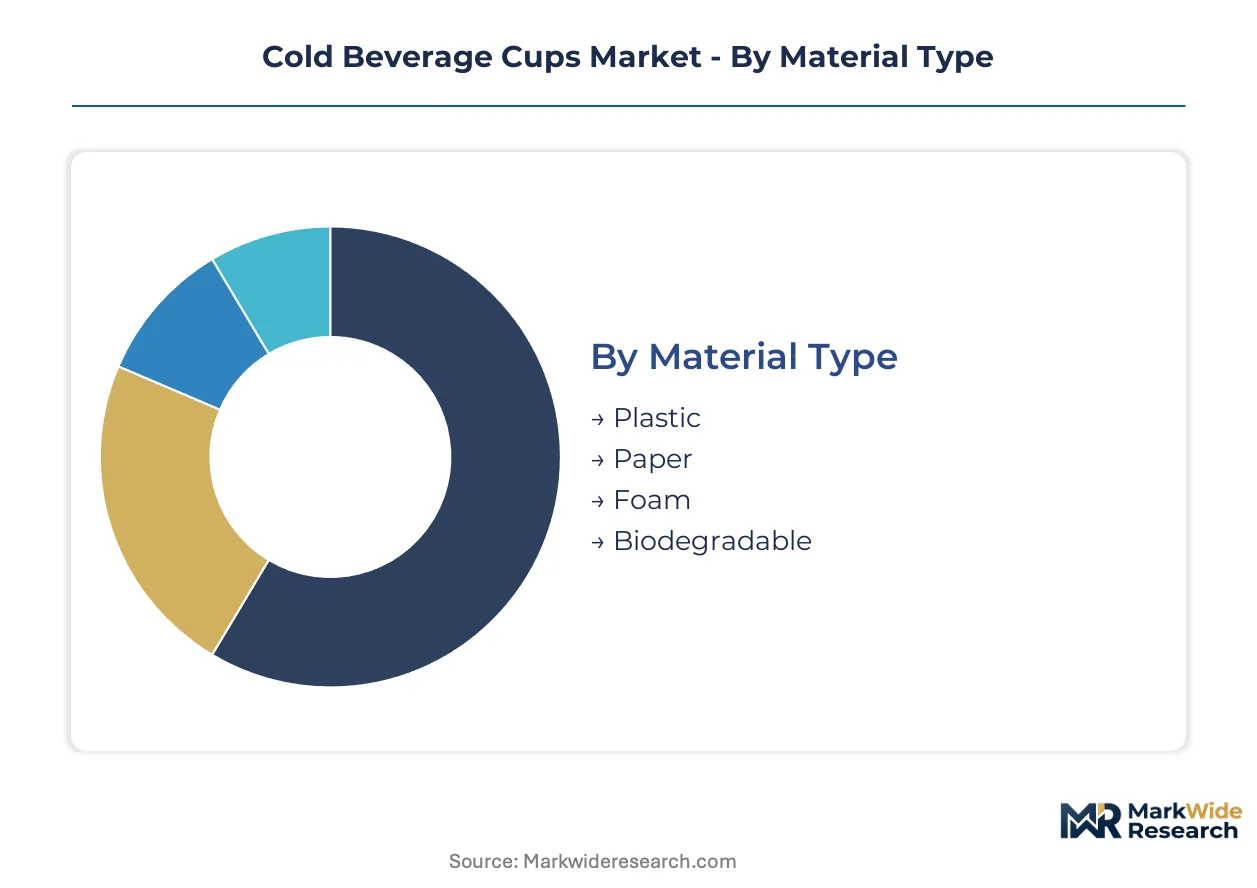
Cold beverage cup procurement varies sharply by use case, with material specifications and size formats diverging across quick-service chains, specialty coffee operators, and event catering. Understanding these segment boundaries clarifies where capacity investments align with buyer requirements.
Material Type:
Customization versus standardization tension runs highest here, with branded chains demanding substrate-specific certifications while independent operators prioritize cost-minimizing commodity grades.
- Plastic:Extruded polystyrene and polypropylene formulations retain dominance in fountain drink applications across the United States and India. FDA food-contact compliance and established thermoforming infrastructure sustain this position despite regulatory pressure in California and EU markets.
- Paper:Coated paperboard with polyethylene or bio-based barriers captures premium positioning in European quick-service networks subject to Single-Use Plastics Directive constraints. Georgia-Pacific and Huhtamaki compete on cupstock supply security and printability specifications.
- Foam:Expanded polystyrene maintains residual volume in cost-sensitive U.S. regional chains, though California SB 54 and municipal bans are accelerating phase-out timelines.
- Biodegradable:PLA and molded fiber alternatives with spray-applied barriers are climbing fastest in Netherlands and California pilot programs for iced coffee and juice concepts.
Leading the category by volume: Plastic. Growing fastest: Biodegradable.
Size:
Volume concentration tracks fountain drink portion inflation and bubble tea format standardization, with medium and large formats absorbing disproportionate capacity expansion.
- Small:Concentrated in specialty coffee shots, children's portions, and sample tastings at U.S. quick-service test markets. Limited growth trajectory as portion sizes trend upward.
- Medium:The workhorse specification for iced coffee and fountain beverages across U.S. coastal urban corridors. Chains in Florida and California standardize around this format for menu consistency.
- Large:Bubble tea operators in Taiwan, South Korea, and Vietnam have normalized 700ml+ specifications, driving insulated cup demand and premium material tolerances.
- Extra Large:Movie theater chains and convenience store fountain programs in the United States deploy this format, though regulatory scrutiny on portion sizes constrains expansion.
Volume leader: Medium. Steepest expansion trajectory: Large.
End User:
Procurement sophistication varies dramatically, with national quick-service chains consolidating specifications while fragmented foodservice accounts accept distributor-branded alternatives.
- Restaurants:Quick-service chains dominate cold cup procurement through centralized buying, with specifications increasingly mandating compostable or recyclable substrates under sustainability scorecards.
- Cafes:Specialty coffee and bubble tea concepts drive insulated cup demand with custom print requirements, accepting 15-40% cost premiums for brand differentiation.
- Events:Stadium and festival catering prioritizes cost minimization and logistics efficiency, often accepting generic unprinted formats in high-volume contracts.
- Retail Stores:Convenience chains and grab-and-go grocery formats favor standardized medium formats with clear lids for beverage visibility.
Category anchor by volume: Restaurants. Gaining share fastest: Cafes.
Functionality:
Margin structure inverts across this dimension, with basic disposable formats commoditized while insulated and custom-printed variants sustain pricing power.
- Disposable:The baseline specification across all material types, with cost-per-thousand dominating procurement evaluation in India and Southeast Asian markets.
- Reusable:Deposit-return schemes in Berlin and Paris are creating infrastructure for stainless-steel alternatives, though scale remains limited outside these pilot markets.
- Insulated:Double-wall construction and foam-lined barriers command sustained premiums in bubble tea and specialty iced coffee applications across East Asian markets.
- Custom Printed:Brand-contracted supply agreements with dedicated print runs generate margin premiums of 20-35% above generic equivalents in U.S. and European quick-service chains.
Volume concentration: Disposable. Premium expansion: Custom Printed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bleached softwood pulp from Nordic and Brazilian sources feeds cupstock production across major consumption clusters, with regulatory pressure redrawing manufacturing footprints faster than raw material flows can adjust.
United States
Quick-service fountain programs in California and Florida drive medium-format plastic cup procurement despite municipal bans spreading across coastal cities. The EPA's PFAS restrictions under TSCA Section 6 are eliminating conventional barrier coatings, forcing reformulation investments by Georgia-Pacific and WestRock. Atlanta anchors Southeast paperboard converting capacity while Los Angeles distribution networks pull compostable alternatives westward.
Germany
Berlin and Hamburg pilot deposit-return schemes for reusable stainless-steel cups, creating infrastructure that competes with single-use formats. The EU Single-Use Plastics Directive mandates labeling and consumption reduction targets that reshape export compliance for Turkish and Polish converters supplying German quick-service accounts. Bavaria's packaging cluster concentrates fiber-forming expertise serving Dutch and Belgian beverage chains.
India
Mumbai and Bangalore quick-service procurement is redirecting toward paperboard alternatives following 2022 Plastic Waste Management Rule amendments banning select single-use plastics. BIS certification requirements for food-contact plastics create compliance thresholds for multinational suppliers entering the market. Gujarat's petrochemical corridor retains polystyrene capacity serving cost-sensitive regional chains.
China
Bubble tea format standardization across Shanghai and Shenzhen drives large-format insulated cup demand with premium material tolerances. The country's dual carbon goals pressure coastal converters toward bio-based substrate trials. Zhejiang province's molded fiber equipment manufacturers are scaling spray-applied barrier technology for domestic and export markets.
Netherlands
Amsterdam and Rotterdam quick-service networks pilot molded fiber cups with spray-applied bio-based barriers for iced coffee applications. The EU Single-Use Plastics Directive's consumption reduction targets accelerate fiber-forming capacity investments by Huhtamaki. Randstad logistics infrastructure enables rapid distribution of compostable formats across Benelux and into German border regions.
Cold Beverage Cups Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based barrier specialization and reusable service models. The market structures around three tiers: integrated pulp-to-cupstock operators, specialized thermoforming converters, and regional distributors with private-label capabilities. Competitive moves concentrate on capacity relocation toward California and EU compliance zones, plus partnerships with quick-service chains for custom-printed supply agreements.
Within the integrated fiber-forming tier, Huhtamaki and Georgia-Pacific exemplify divergent geographic anchoring strategies, with the former leveraging European compostable expertise and the latter commanding North American cupstock supply security. Dart Container occupies a distinctive position bridging foam legacy production and plastic thermoforming scale. These three entities represent the archetype spectrum from regulatory-compliant fiber innovation to cost-optimized conventional manufacturing.
| Leading Market Players |
|---|
| Dart Container |
| Huhtamaki |
| Georgia-Pacific |
| Berry Global |
| Pactiv Evergreen |
| Genpak |
| WestRock Company |
| Graphic Packaging International |
| Eco-Products |
| Others |
Supply Flow & Price Mechanics
Specialized fiber-forming technicians in Nordic regions and coastal China command wage premiums that compress margins at mid-tier converters while widening the spread between commodity plastic cups and certified compostable alternatives.
Pricing Analysis
Volume concentrates in disposable plastic formats where per-thousand-unit pricing dominates procurement scorecards, while insulated and custom-printed variants sustain margin premiums through brand-contracted supply agreements. Price differentiation rests on certification tier—FDA food-contact clearance versus EU compostability labeling—and geographic delivery cost to coastal urban corridors. Cost compression in standard polystyrene formats is intensifying as California SB 54 mandates pull buyers toward fiber alternatives. Quick-service chains exhibit highest price sensitivity, while specialty coffee and bubble tea operators accept substantial premiums for thermal performance and print fidelity.
Supply Chain Analysis
Freight costs from Brazilian and Nordic pulp terminals to North American and European converting facilities represent a structural margin drain for cupstock-dependent producers. Raw material flows draw from bleached eucalyptus plantations in Brazil, softwood fiber streams in Scandinavia, and petroleum feedstocks along the U.S. Gulf Coast. Single-source vulnerability concentrates in barrier coating formulations where EPA PFAS restrictions are eliminating qualified suppliers. Distribution runs through quick-service chain direct procurement, foodservice distributor networks, and private-label regional converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cold beverage cup sector sits in a material-transition phase where spray-applied bio-based barriers are displacing conventional fluoropolymer coatings across regulated markets.
For Market Incumbents: Deepen backward integration into pulp supply through offtake agreements with Nordic and Brazilian producers to secure cupstock cost position against emerging fiber specialists. Accelerate spray-applied barrier R&D to outpace regulatory timelines on PFAS elimination. Defend share in quick-service chain scorecards by pre-certifying compostable formats for California and EU compliance zones before specifications harden. For New Entrants and Emerging Players: California SB 54 opens a window for compostable cup specialists to capture guaranteed offtake from quick-service chains scrambling to meet packaging reduction mandates. Target Indonesia's underpenetrated quick-service networks where per-capita cold cup consumption lags Bangkok levels by four-fifths. Enter through distributor partnerships offering localized print capabilities and rapid format customization rather than competing on commodity volume. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale converters possessing spray-applied barrier equipment and existing quick-service relationships, given the technology convergence compressing cost premiums between plastic and fiber formats. Long-term viability favors assets with geographic positioning in California and EU compliance corridors. Monitor FDA novel food-contact substance approval timelines as an inflection signal for barrier technology winners.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Technology Licensing | Spray-applied bio-based coating patents from Zhejiang equipment manufacturers accelerate fiber cup cost parity. |
| Compostable Certification Investment | BPI and TUV OK compost labels unlock quick-service procurement in California and Netherlands pilot programs. |
| Pulp Supply Integration | Captive offtake from Brazilian eucalyptus plantations insulates converters from Nordic softwood price volatility. |
| Reusable Cup Infrastructure Partnership | Deposit-return scheme operators in Berlin and Paris create recurring revenue streams displacing single-use volumes. |
| Regional Converting Footprint Expansion | West Coast capacity placement captures California SB 54 compliance pull before East Coast competitors relocate. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with quick-service procurement directors, foodservice distributor category managers, molded fiber equipment engineers, and barrier coating R&D leads. FDA food-contact substance petitions, EPA TSCA Section 6 correspondence, EU Single-Use Plastics Directive implementation reports, and Indian BIS certification databases provided compliance trajectory inputs. Bottom-up volume modeling triangulated against top-down packaging consumption estimates across the analysis window.
Granularity extended to material type, size format, end-user channel, and functionality specifications, with geographic disaggregation to coastal urban corridors and regulatory compliance zones. CAGRs derived from trend extrapolation of quick-service chain expansion, bubble tea format standardization, and material substitution elasticities under extended producer responsibility schemes. Pulp price indices, thermoforming capacity utilization, and composting infrastructure penetration served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for spray-applied nanocellulose barriers would alter the outlook if cold-crack resistance thresholds advance faster than projected. Forecasts reflect assumptions on regulatory enforcement timelines, pulp supply continuity, and quick-service chain sustainability scorecard weightings. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Biotainer Market
Beverage Packaging
Indonesia Plastic Bottles Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Bamboo Cups Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Tumblers Market
Beverage Packaging
Fruit Juice Packaging Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
United States Aluminum Beverage Cans Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Drink Can Market
Beverage Packaging
Cup Filler Market
Beverage Packaging
Bottle Shippers Market
Beverage Packaging
North America Beverage Packaging Market