
 Europe Beverage Container Market | 2026-2036
Europe Beverage Container Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Beverage Container Market Intelligence
The EU's Single-Use Plastics Directive is expanding the cost-of-entry calculus for new materials and designs. Ball Corporation leverages its scale in aluminum can manufacturing to meet circular economy goals. Ardagh Group differentiates through its focus on both glass and metal packaging solutions across Europe. Amcor positions its portfolio around flexible and rigid plastic innovations that comply with evolving European standards.
A beverage container is a vessel designed for the containment, protection, and transport of liquids for consumption. These containers are manufactured from materials like Polyethylene Terephthalate (PET) or aluminum, often engineered for specific barrier properties against oxygen and light. Within the market, aluminum cans are gaining share in the alcoholic beverages segment due to high recyclability. Glass bottles remain a premium choice for specific applications, while cartons dominate the dairy drinks category.
The European Green Deal and its associated packaging waste regulations set stringent targets for recycled content and collection rates. Compliance with EFSA food contact material standards and CE marking requirements is mandatory for market access in the European Union. Beverage manufacturers must now balance material performance, consumer appeal, and verifiable sustainability claims to maintain market position.
Market Dynamics
The European beverage container market is defined by the structural pressure of circular economy mandates clashing with the technical and cost realities of material science. This dynamic forces manufacturers to innovate packaging that meets stringent recycling and reuse targets without compromising product integrity or affordability.
Growth Catalysts
- Circular Economy Mandates:The EU's Circular Economy Action Plan accelerates demand for mono-materials and easily separable components, particularly benefiting aluminum cans and clear PET bottles designed for high-quality recycling loops.
- Functional Beverage Expansion:Demand from the health and wellness sector for functional drinks, such as vitamin-infused waters and protein shakes, requires packaging with advanced barrier properties, spurring innovation in PET additives and coatings.
- Deposit-Return Schemes:The expansion of Deposit-Return Schemes (DRS) across more European nations creates a powerful financial incentive for consumers to return containers, improving collection rates and the supply of high-purity recyclate.
Market Restraints
- Raw Material Volatility:Price fluctuations for key inputs like aluminum ingot and virgin PET resin create significant cost uncertainty for container manufacturers, impacting margins and challenging long-term pricing strategies.
- Recycled Content Limitations:Technical challenges in processing post-consumer recyclate, such as discoloration and reduced mechanical performance in rPET, limit its application in certain high-clarity or carbonated beverage containers.
- Regulatory Compliance Burden:The intricate and evolving nature of EFSA food contact material regulations adds complexity and cost to new product development, slowing time-to-market for novel packaging materials and designs.
Strategic Opportunities
- Smart Packaging Integration:Incorporating technologies like QR codes or NFC tags onto containers offers opportunities for enhanced traceability, brand interaction, and verification of sustainability claims directly to consumers.
- Reusable Packaging Models:The development of standardized, durable, and cleanable reusable container systems for beverage-on-tap or refill-at-home services presents a significant growth avenue, especially in urban markets like Berlin and Paris.
- Bio-Based Polymer Development:Investment in commercially viable, non-food-source bio-based polymers that meet performance and food safety standards offers a path to decouple packaging from fossil fuel feedstocks.
Industry Challenges
- Recyclate Supply Inconsistency:Securing a stable and high-quality supply of post-consumer recyclate remains a primary operational challenge, hindering manufacturers' ability to meet legally mandated recycled content targets consistently.
- Capital-Intensive Line Conversion:The need to retool manufacturing lines to accommodate new designs, such as tethered caps required by the Single-Use Plastics Directive, demands significant capital expenditure from converters.
- Greenwashing Scrutiny:Beverage brands and packaging producers face the challenge of substantiating environmental claims under increasing regulatory and consumer scrutiny, requiring robust data and transparent reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Beverage Container Market |
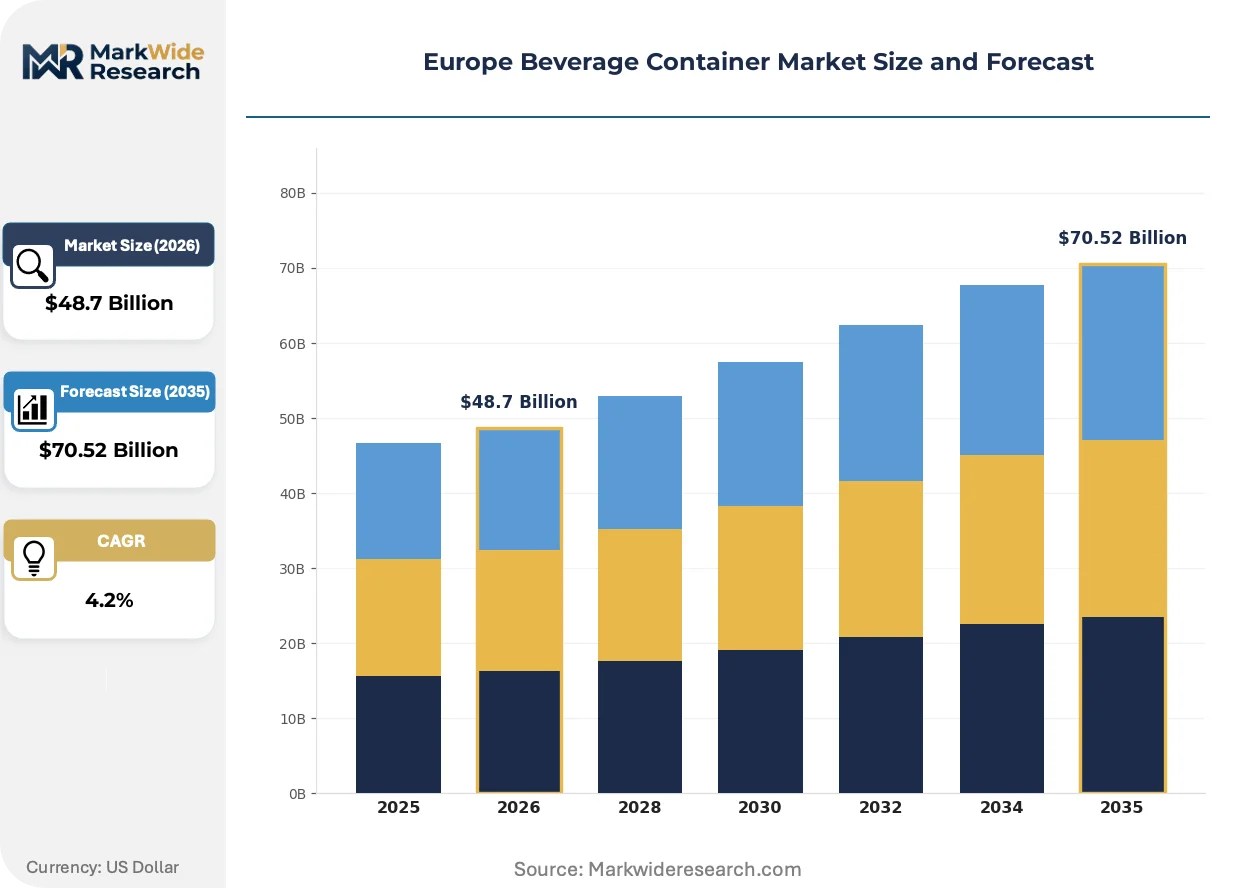
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $70.52 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Glass Bottles, Aluminum Cans, Plastic Bottles, Cartons, Tetra Pak, Pouches Material Composition: Polyethylene Terephthalate, High-Density Polyethylene, Aluminum, Glass, Paperboard, Steel Application: Carbonated Drinks, Juices, Bottled Water, Alcoholic Beverages, Functional Beverages, Dairy Drinks End User: Beverage Manufacturers, Bottling Companies, Distributors, Retail Chains, Foodservice Operators, Event Organizers |
| Companies Covered | Ball Corporation, Crown Holdings, Ardagh Group, Amcor, Tetra Pak, Owens-Illinois, Vetropack Holding, Gerresheimer, CANPACK, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Beverage Container Market Strategic Shifts & Innovations
The industrialization of sustainability is the central theme, as circularity goals transition from corporate social responsibility initiatives to core engineering requirements. This shift forces a practical re-evaluation of material science, supply chain logistics, and packaging design across the entire European market.
Advanced sorting technology is a critical enabler for Europe's circular economy ambitions. These systems use AI-powered optical scanners and digital watermarks to identify and separate different polymer types and colors from post-consumer waste streams with high precision. Material recovery facilities (MRFs) and plastics recyclers are the primary adopters, driven by demand for purer feedstock. The push for higher quality rPET and other recyclates is consolidating the recycling industry around operators who can afford these sophisticated sorting systems.
The EU's Packaging and Packaging Waste Regulation (PPWR) is fundamentally altering design and material choices. This regulation establishes legally binding targets for recycled content, waste reduction, and the mandatory recyclability of all packaging placed on the market. The beverage sector, particularly producers of PET bottles for water and soft drinks, is most directly affected, forcing an acceleration of investment into food-grade rPET production and collection infrastructure.
A notable shift in consumer behavior involves the adoption of refill-at-home and concentrate-based beverage systems. This trend disrupts the traditional single-use container model dominant in retail, favoring smaller-format packaging for concentrates or bulk containers for dispensers. This shift is most pronounced in environmentally conscious urban demographics in Germany and Scandinavia for products like water enhancers, soda concentrates, and cold-brew coffee.
Europe Beverage Container Market Segmentation

The European beverage container market exhibits diverse segmentation, reflecting varied material preferences, application-specific requirements, and end-user demands across the region. Understanding these distinct segments is crucial for manufacturers to align product portfolios with evolving regulatory landscapes and consumer sustainability expectations.
Container Type:
Buyers prioritize different container types based on product integrity, brand image, and environmental impact considerations.
- Aluminum Cans:These lightweight, infinitely recyclable containers offer excellent barrier properties against light and oxygen. Demand is concentrating in alcoholic beverages and soft drinks, driven by high recyclability and convenience in Germany and France.
- Plastic Bottles:Primarily made from PET, these bottles provide transparency, resealability, and cost-effectiveness for various liquid products. Consumption is highest in bottled water and functional beverages, particularly in Southern European markets.
- Glass Bottles:Valued for their premium perception and inertness, glass bottles remain a choice for high-end beverages and returnable systems.
- Cartons:Multi-layered paperboard-based containers offer extended shelf life for sensitive products, dominating the dairy and juice categories.
- Tetra Pak:These aseptic carton packages are widely used for long-life milk, juices, and plant-based drinks, ensuring product freshness without refrigeration.
- Pouches:Flexible and lightweight, pouches offer convenience and reduced material usage for specific beverage formats like fruit purees or energy gels.
Volume sits with Plastic Bottles; growth tilts toward Aluminum Cans.
Material Composition:
Material composition largely dictates a container's barrier properties, recyclability, and overall environmental footprint within the European market.
- Polyethylene Terephthalate (PET):This transparent, lightweight polymer is extensively used for bottles due to its clarity and recyclability. Demand is concentrated in bottled water and carbonated soft drinks, especially with increasing rPET content mandated by EU regulations.
- Aluminum:Known for its high strength-to-weight ratio and infinite recyclability, aluminum is gaining share in the European beverage sector. Its adoption is accelerating for cans across alcoholic and non-alcoholic segments due to circular economy mandates.
- High-Density Polyethylene:HDPE is a durable and opaque plastic, commonly employed for milk and juice bottles requiring robust construction.
- Glass:An inert and fully recyclable material, glass is favored for premium beverages and returnable bottle systems, especially in countries like Germany.
- Paperboard:The primary component of cartons, paperboard provides structural integrity and printability for aseptic and chilled beverage packaging.
- Steel:Used for specialized beverage containers like large format beer kegs or some energy drink cans, steel offers strength and recyclability.
Polyethylene Terephthalate maintains its broad application base, while aluminum is experiencing significant market share expansion.
Application:
The specific beverage application determines the required container properties, including barrier protection, shelf stability, and aesthetic appeal for European consumers.
- Bottled Water:This segment extensively uses PET bottles due to their cost-effectiveness, transparency, and consumer convenience. It represents a foundational volume segment across all European nations.
- Functional Beverages:Requiring advanced barrier properties for sensitive ingredients, functional beverages drive innovation in specialized PET and aluminum packaging. Demand is particularly strong in health-conscious markets like Scandinavia and Germany.
- Carbonated Drinks:These beverages primarily utilize aluminum cans and PET bottles, which must withstand internal pressure and prevent CO2 loss.
- Juices:Cartons and PET bottles are common for juices, with barrier properties important for preserving vitamins and flavor.
- Alcoholic Beverages:Glass bottles and aluminum cans are prevalent, with material choice often reflecting brand positioning and recyclability goals in markets like France and Italy.
- Dairy Drinks:Cartons and HDPE bottles dominate this category, providing necessary light protection and shelf life for milk and yogurt-based beverages.
Bottled water represents a foundational volume segment, with functional beverages driving innovation in material science.
End User:
End users exhibit distinct procurement patterns and packaging requirements based on their operational scale and distribution channels within Europe.
- Beverage Manufacturers:These entities procure containers in massive volumes, driving demand for cost-efficient, high-performance packaging solutions. Their requirements are heavily influenced by EU sustainability mandates and consumer preferences.
- Retail Chains:Requiring diverse packaging formats for shelf appeal and consumer convenience, retail chains influence packaging design and material choices. They play a critical role in promoting sustainable packaging options across Europe.
- Bottling Companies:These specialized firms purchase containers for filling and packaging, often serving multiple beverage brands.
- Distributors:Involved in logistics and supply chain management, distributors require packaging that is durable and efficient for transport.
- Foodservice Operators:Restaurants, cafes, and hotels utilize beverage containers for on-premise consumption, often favoring glass or reusable options.
- Event Organizers:Sporting events and concerts demand high-volume, single-serve, and often easily recyclable containers like aluminum cans.
Beverage manufacturers form the largest procurement segment, while retail chains exert significant influence on packaging innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for beverage containers across Europe concentrates in highly populated and economically robust nations. These markets drive significant innovation in packaging materials and recycling infrastructure. Consumer preferences for sustainable options influence material choices across the continent.
Germany
High consumer demand for beverages, coupled with a well-established beverage industry, drives container consumption. Germany's robust Deposit-Return Schemes (DRS) significantly boost collection rates for PET bottles and aluminum cans. Bavarian beverage manufacturers, for instance, actively invest in rPET production lines to meet circular economy goals.
France
Consumer preference for premium and sustainable packaging shapes container demand in France. The French government's AGEC law mandates increased recycled content in packaging. Paris-based beverage brands are exploring reusable packaging solutions for urban distribution.
United Kingdom
The UK's large soft drinks market and evolving consumer habits influence beverage container choices. Proposed UK Deposit Return Scheme initiatives aim to improve plastic and aluminum packaging collection rates. London's vibrant food service sector sees growing adoption of aluminum cans for convenience and recyclability.
Italy
Bottled water consumption and a strong wine industry contribute substantially to container demand in Italy. Italian regulations, aligned with the EU's Single-Use Plastics Directive, push for higher recyclability across beverage packaging. Northern Italian bottling companies actively integrate advanced sorting technologies for post-consumer recyclate.
Poland
The expanding market for non-alcoholic beverages and increasing disposable incomes elevate container demand in Poland. Poland's national waste management plan emphasizes enhanced recycling infrastructure and collection targets. Warsaw-based beverage producers are adapting packaging designs to meet evolving EU sustainability standards.
Europe Beverage Container Market Key Industry Players
European producers anchor one tier, while global packaging specialists hold significant cross-regional influence. The market structure exhibits consolidation among large-scale manufacturers and fragmentation among niche material providers. Strategic archetypes include integrated material suppliers, multi-material solution providers, and specialized sustainable packaging innovators. Companies pursue capacity expansion and strategic partnerships to navigate evolving regulatory landscapes.
At the scale-driven end, Ball Corporation exemplifies a major aluminum can manufacturer with a strong European footprint, focusing on infinitely recyclable solutions. Ardagh Group, an Ireland-based packaging company, represents a diversified player offering both glass and metal solutions across the continent, emphasizing material versatility. Tetra Pak, a Sweden-based multinational, anchors the aseptic carton segment, particularly for dairy and juice applications in Europe, providing extended shelf-life capabilities. These entities leverage their operational scale and material expertise to meet the region's circular economy mandates and evolving consumer preferences for sustainable packaging.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings |
| Ardagh Group |
| Amcor |
| Tetra Pak |
| Owens-Illinois |
| Vetropack Holding |
| Gerresheimer |
| CANPACK |
| Others |
Cost & Logistics Intelligence
Vertical integration into raw material processing anchors container manufacturers' supply stability and pricing power within the European beverage market. This strategic control mitigates volatility from external material suppliers.
Pricing Analysis
Volume-driven segments like bottled water often operate on thinner margins, whereas specialized functional beverage packaging commands premium pricing. The dominant pricing structure is contract-based long-term offtake agreements between manufacturers and beverage brands. Price differentiation stems from material quality certifications, such as EFSA compliance for rPET, and customization levels for specific barrier properties. Pricing pressure stems from volatile raw material costs for aluminum ingot and virgin PET resin. Beverage manufacturers are the least price-sensitive for critical packaging, while smaller brands exhibit higher price sensitivity.
Supply Chain Analysis
Logistics and freight costs significantly influence the delivered price of beverage containers across Europe, particularly for bulky glass bottles. Geographic supply concentration for key inputs like aluminum ingots draws from regions outside Europe, while PET resin production concentrates in Germany and Poland. Raw material dependencies include bauxite for aluminum and crude oil derivatives for PET. Single-source vulnerability for specialized barrier coatings poses a structural supply chain risk. Distribution runs through a mix of direct manufacturer-to-bottler shipments and regional warehousing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European beverage container market is undergoing a technology-transition phase, with advanced sorting technology replacing traditional manual or less efficient material recovery methods. This shift is crucial for achieving high-purity recyclate streams.
For Market Incumbents: Cement market leadership by investing in advanced rPET production lines to meet EU recycled content mandates. Diversify material portfolios to include high-recycled-content aluminum and glass, mitigating the threat from single-material regulatory shifts. Leverage scale for long-term raw material contracts, reducing exposure to commodity price volatility. Ball Corporation and Ardagh Group must secure consistent, high-quality post-consumer recyclate supply.
For New Entrants and Emerging Players: Direct-to-consumer refill models offer a white-space opportunity, particularly in urban centers like Berlin and Paris. Target the functional beverages segment with innovative bio-based polymers for advanced barrier properties. Focus on packaging designs that simplify consumer interaction, such as QR codes for traceability. A go-to-market angle emphasizing verifiable sustainability claims resonates with environmentally conscious European consumers.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized recyclers and advanced material science firms over a 5-10 year horizon. Target acquisition archetypes include technology providers offering advanced sorting solutions or those developing commercially viable bio-based polymers. A signal to watch is the consistent achievement of EU recycled content targets by mid-sized packaging converters, indicating scalable innovation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in rPET Production | Increases supply of food-grade recycled PET to meet EU regulatory mandates across Europe. |
| Investment in Advanced Sorting Technologies | Improves the purity and availability of post-consumer recyclate for European container manufacturers. |
| Development of Reusable Packaging Systems | Creates new revenue streams by addressing consumer demand for circular economy solutions in Germany. |
| Strategic Partnerships for Bio-Based Materials | Accelerates the commercialization of sustainable packaging alternatives, reducing fossil fuel dependence for Amcor. |
| Geographic Expansion into Eastern Europe | Captures growth in expanding non-alcoholic beverage markets and increasing disposable incomes in Poland. |
Research Approach
EFSA food contact material standards, EU Single-Use Plastics Directive documentation, and Eurostat trade data formed the secondary backbone for this analysis. This was combined with primary interviews involving beverage manufacturing executives, packaging procurement managers, material science researchers, and recycling facility operators across Europe. Bottom-up and top-down triangulation validated data points and market trends.
Historical trendline analysis informed the quantitative modeling for the European beverage container market across the analysis window. Segmentation dimensions modeled included container type, material composition, application, and end-user, alongside regional regulatory impacts. Compound annual growth rates were derived from projected market drivers and restraints, incorporating inputs like rPET availability and consumer preference shifts for sustainable packaging.
The model holds under current EU regulatory frameworks; deviation in raw material price stability or unforeseen geopolitical events would shift market trajectories. Forecasts reflect assumptions documented through extensive primary and secondary research. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Square Media Bottle Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
Bullet Bottles Market
Beverage Packaging
Combi Cans Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Global Beverage Container Market
Beverage Packaging
Biotainer Market
Beverage Packaging
Skep Bottle Market
Beverage Packaging
Europe Soft Drinks Packaging Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
US Soft Drinks Packaging Market
Beverage Packaging
Stackable Beaker Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Aluminium Cup Market
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
Dispensing Carboy Market