
 Middle East and Africa Soft Drinks Packaging Market | 2026-2036
Middle East and Africa Soft Drinks Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Soft Drinks Packaging Market Foresight
Market Dynamics
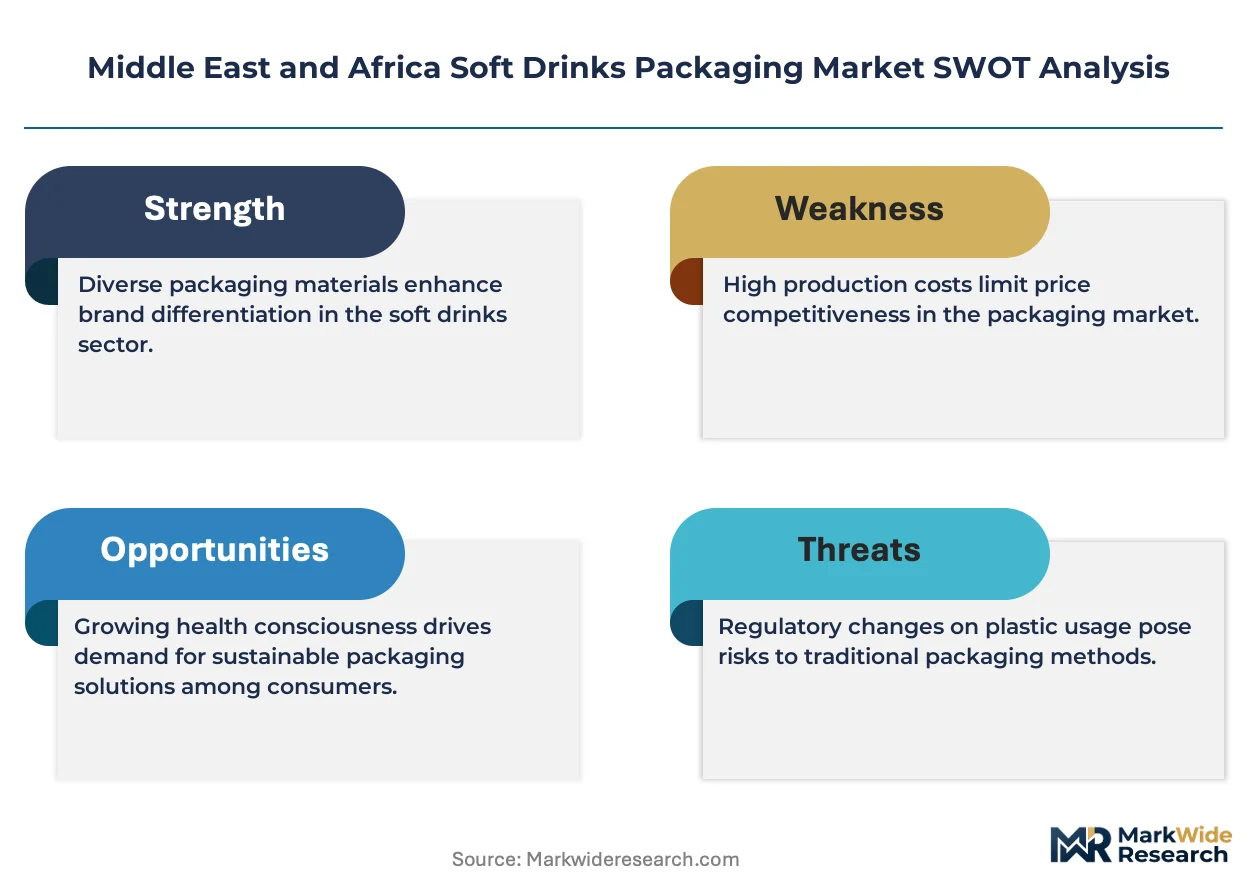
Adequate polymer compounding and aseptic filling technician pools across the Gulf and North Africa is collapsing as fast-growing bottling lines outpace vocational training output. Tetra Pak International SA leverages its regional aseptic carton technical service hubs to sustain equipment uptime for dairy and juice converters. Amcor plc anchors flexible and rigid plastic supply through its Egyptian and South African manufacturing complexes. SIG Group AG competes on aluminum-free carton barrier technology for temperature-sensitive soft drink distribution.
Technical and Segment Profile
Middle East and Africa soft drinks packaging encompasses primary and secondary containment systems engineered from PET, HDPE, aluminum, coated paperboard, and glass, designed to preserve carbonation, prevent UV degradation, and withstand ambient distribution temperatures reaching fifty degrees Celsius in Gulf climates. The industrial purpose centers on extending shelf stability, enabling brand differentiation through shape and label real estate, and complying with halal certification and food-contact migration limits across diverse national standards. Plastic bottles dominate volume across Nigeria and Egypt due to cost scalability and local resin conversion capabilities, while aluminum cans capture premium positioning in UAE and South African urban retail channels. Fiber-based cartons represent the fastest-expanding material class as Gulf dairy and juice processors seek shelf-stable alternatives to refrigerated distribution. Screw caps and flip-top closures concentrate margin pools through proprietary tamper-evident designs that differentiate family-size and single-serve offerings.
Regulatory Environment
Saudi Standards, Metrology and Quality Organization (SASO) mandates food-contact material testing and halal compliance certification for all imported packaging substrates entering the Kingdom. South Africa's Department of Forestry, Fisheries and the Environment implements extended producer responsibility regulations requiring brand owners and importers to register and fund post-consumer packaging collection and recycling targets. Egypt's Egyptian Organization for Standardization and Quality (EOS) enforces polymer migration limits for carbonated beverage containers. Stakeholders must monitor diverging national registration timelines and recyclability mandates that will determine which material-format combinations retain market access across the region's fragmented regulatory landscape.
Market Dynamics
Aseptic carton technology is compressing traditional cold-chain dependency across Gulf beverage operations as ambient distribution networks expand into secondary cities and rural trade corridors.
Growth Catalysts
- Extended Producer Responsibility mandates:South Africa's Department of Forestry, Fisheries and the Environment requires brand owners to fund post-consumer collection infrastructure, creating pull-through demand for recyclable PET and aluminum formats.
- Urban retail modernization:Organized grocery penetration in Nigeria and Egypt accelerates single-serve and family-size packaging procurement from multinational bottling operations.
- Halal certification harmonization:SASO technical regulations on food-contact materials streamline cross-border substrate approvals between Saudi Arabia, UAE, and Bahrain.
Market Restraints
- Resin import dependency:Local polymer compounding capacity in Egypt and Nigeria lags behind bottling line expansion, exposing converters to freight cost volatility from Asian petrochemical suppliers.
- Technician pipeline collapse:Vocational training output across the Gulf and North Africa fails to match aseptic filling equipment deployment rates, constraining uptime at dairy and juice processing facilities.
- Glass substitution pressure:Premium positioning in UAE and South African urban channels favors aluminum cans for carbonated soft drinks, eroding returnable glass bottle economics.
Strategic Opportunities
- Ethiopian market entry:Underpenetrated organized retail and nascent bottling infrastructure create first-mover positioning for aseptic carton and PET preform suppliers.
- Aluminum-free barrier innovation:SIG Group AG's polymer-based oxygen barrier technology enables shelf-stable juice distribution without cold-chain investment in temperature-sensitive climates.
- Reverse vending deployment:Dubai's mandatory deposit-return scheme for plastic bottles and cans mandates collection infrastructure that rewards local recycling partnerships.
Industry Challenges
- Aseptic technician scarcity:Gulf dairy and juice processors compete for limited pools of sterilization system operators capable of maintaining Tetra Pak and Krones equipment uptime.
- Multi-jurisdiction registration lag:Divergent national timelines for EOS polymer migration testing in Egypt versus SASO halal compliance in Saudi Arabia delay product launches by 4-8 months.
Report Scope
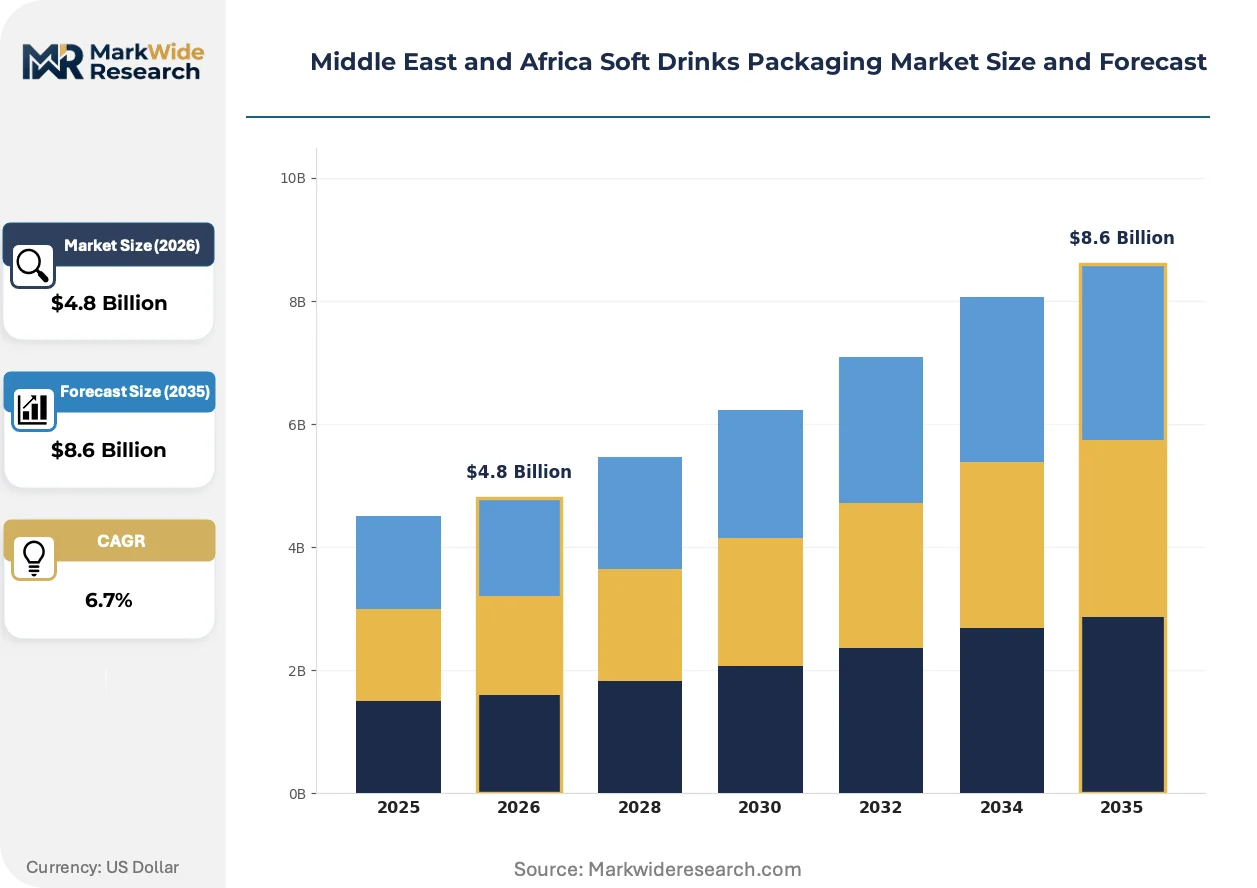
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Soft Drinks Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Cans, Cartons, Pouches Material: Plastic, Glass, Metal, Fiber Closure Type: Twist-off, Crown Caps, Flip-top, Screw Caps Size: Single Serve, Family Size, Bulk, Mini Packs |
| Companies Covered | Tetra Pak International SA, Amcor plc, SIG Group AG, Ball Corporation, Crown Holdings Inc., Pactiv LLC, Graham Packaging Company, Owens-Illinois Inc, Plastipak Holdings Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Soft Drinks Packaging Market Shifts & Advancements
Material science convergence with ambient distribution requirements is restructuring competitive advantage across Middle East and Africa soft drinks packaging. Three developments dominate strategic planning.
Lightweighted PET preforms with enhanced UV barrier additives are displacing multilayer glass and coated paperboard in Gulf carbonated beverage applications. Saudi bottlers adopting 26-gram neck finish designs reduce resin consumption per unit while maintaining fifty-degree Celsius shelf stability. This displacement compresses traditional premium positioning for returnable glass in family-size formats.
SASO's 2024 technical regulations on food-contact material migration testing mandate third-party laboratory certification for all imported packaging substrates entering Saudi Arabia. Industrial consequence includes consolidation of supplier qualification around regional testing hubs in Riyadh and Jeddah. Carbonated soft drink converters with existing SASO registration capture disproportionate shelf space as smaller importers face compliance delays.
Buying patterns among Nigerian and Egyptian bottlers are compressing supplier qualification cycles from annual tenders to quarterly performance reviews. Modern trade procurement teams now unbundle equipment service contracts from resin supply agreements, forcing packaging vendors to compete on technical service response times rather than volume discounts alone. This behavioral shift is most visible in Lagos and Cairo, where multinational retail chains centralize packaging procurement decisions.
Middle East and Africa Soft Drinks Packaging Market Segmentation
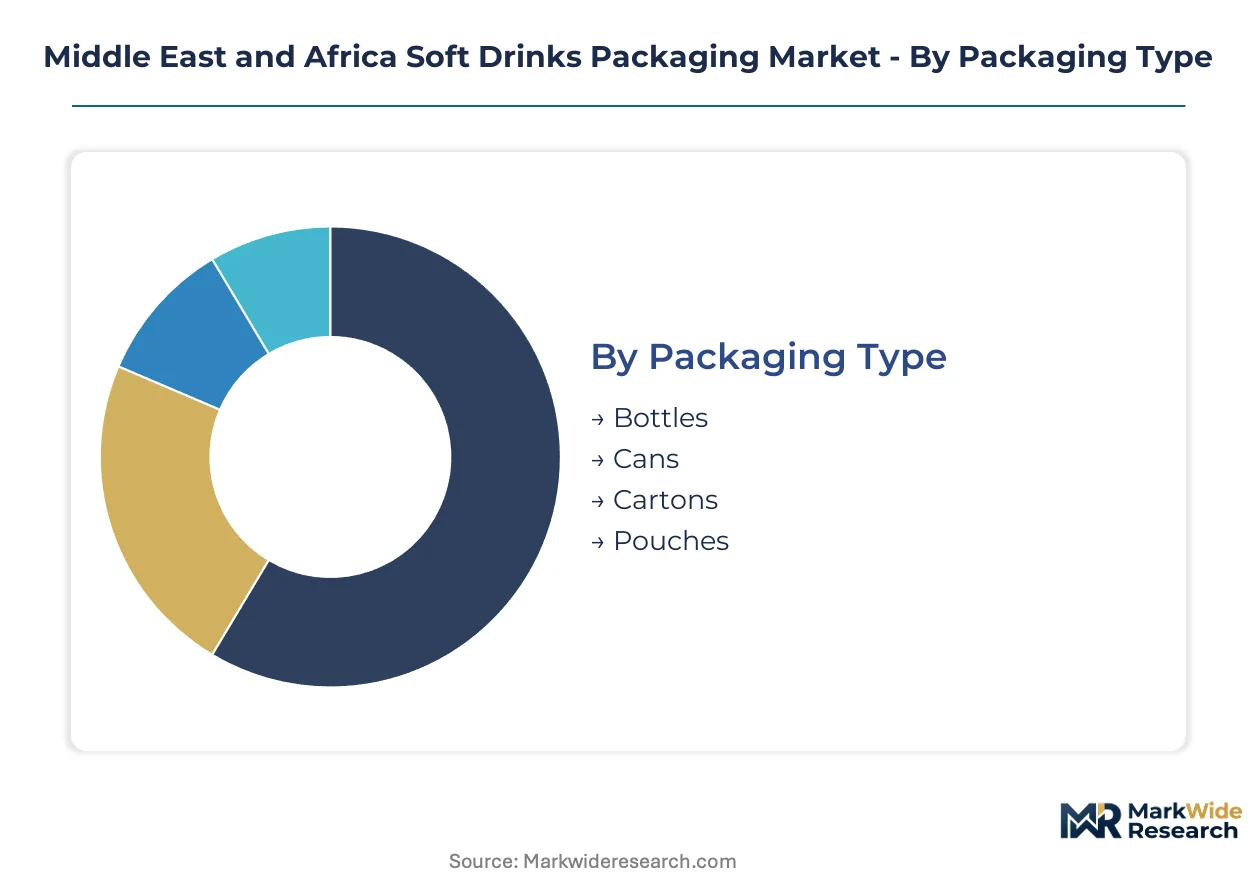
Packaging format selection in Middle East and Africa soft drinks markets determines cold-chain investment requirements, shelf stability economics, and compliance pathways across divergent national regulatory regimes. Material and closure specifications cascade into halal certification complexity and recycling infrastructure funding obligations.
Packaging Type:
Bottles capture the deepest margin pools through proprietary preform designs and brand-differentiated neck finishes that lock in converter relationships across Gulf bottling operations.
- Bottles:PET and HDPE formats dominate Nigerian and Egyptian carbonated soft drink distribution through local resin conversion capabilities and cost scalability at ambient temperature storage. Saudi bottlers are deploying lightweighted 26-gram neck finish designs that reduce per-unit resin consumption while maintaining fifty-degree Celsius shelf stability in Gulf climates.
- Cans:Aluminum two-piece and three-piece designs command premium positioning in UAE and South African urban retail channels, displacing returnable glass through superior logistics efficiency and single-serve convenience. Cold-chain independence and stackability advantages accelerate procurement from multinational bottling operations in organized grocery formats.
- Cartons:Aseptic coated paperboard formats enable dairy and juice processors to bypass refrigerated distribution networks across Gulf secondary cities and rural trade corridors.
- Pouches:Flexible laminated structures concentrate in value-oriented Nigerian and Egyptian informal retail channels where cost minimization overrides barrier performance requirements.
Bottles hold installed capacity. Cans are rotating up the share rankings.
Material:
Polymer substrates concentrate volume leadership through backward integration into regional petrochemical supply, while fiber-based alternatives climb fastest on ambient distribution advantages.
- Plastic:PET and HDPE resins anchor Nigerian and Egyptian bottling economics through established local compounding infrastructure and migration limit compliance under EOS and SASO frameworks. Gulf converters face freight cost volatility from Asian petrochemical suppliers where local polymer capacity lags bottling line expansion.
- Metal:Aluminum sheet and coil supply feeds UAE and South African can manufacturing through rolling mill proximity to beverage production clusters, capturing premium carbonated soft drink positioning in modern trade channels.
- Glass:Returnable and non-returnable formats retain family-size water and traditional beverage applications in Egypt and Levant markets where deposit-return infrastructure and cultural preferences sustain refill economics.
- Fiber:Coated paperboard and molded fiber formats are expanding most quickly as Gulf dairy and juice processors adopt aseptic carton alternatives to cold-chain dependency, with SIG Group and Tetra Pak technical service hubs sustaining equipment uptime.
Plastic holds installed capacity. Fiber is rotating up the share rankings.
Closure Type:
Tamper-evident and resealability features concentrate margin capture in family-size and single-serve formats where brand differentiation and consumption occasion segmentation drive procurement decisions.
- Screw Caps:Polypropylene and HDPE threaded designs dominate PET bottle applications across Nigerian and Egyptian carbonated soft drink production, with proprietary tamper-evident bands enabling brand security and retail shelf differentiation.
- Flip-top:Hinged polyolefin closures concentrate in Gulf single-serve sports and energy drink segments where one-handed consumption convenience commands price premiums in convenience retail channels.
- Twist-off:Metal lug and PT-lined designs retain glass bottle applications in traditional Egyptian and Levant beverage markets where crown cork alternatives face cultural resistance.
- Crown Caps:Steel shell and PVC-free liner formats persist in returnable glass systems and craft beverage positioning where authenticity signaling overrides resealability requirements.
Screw caps hold installed capacity. Flip-top is rotating up the share rankings.
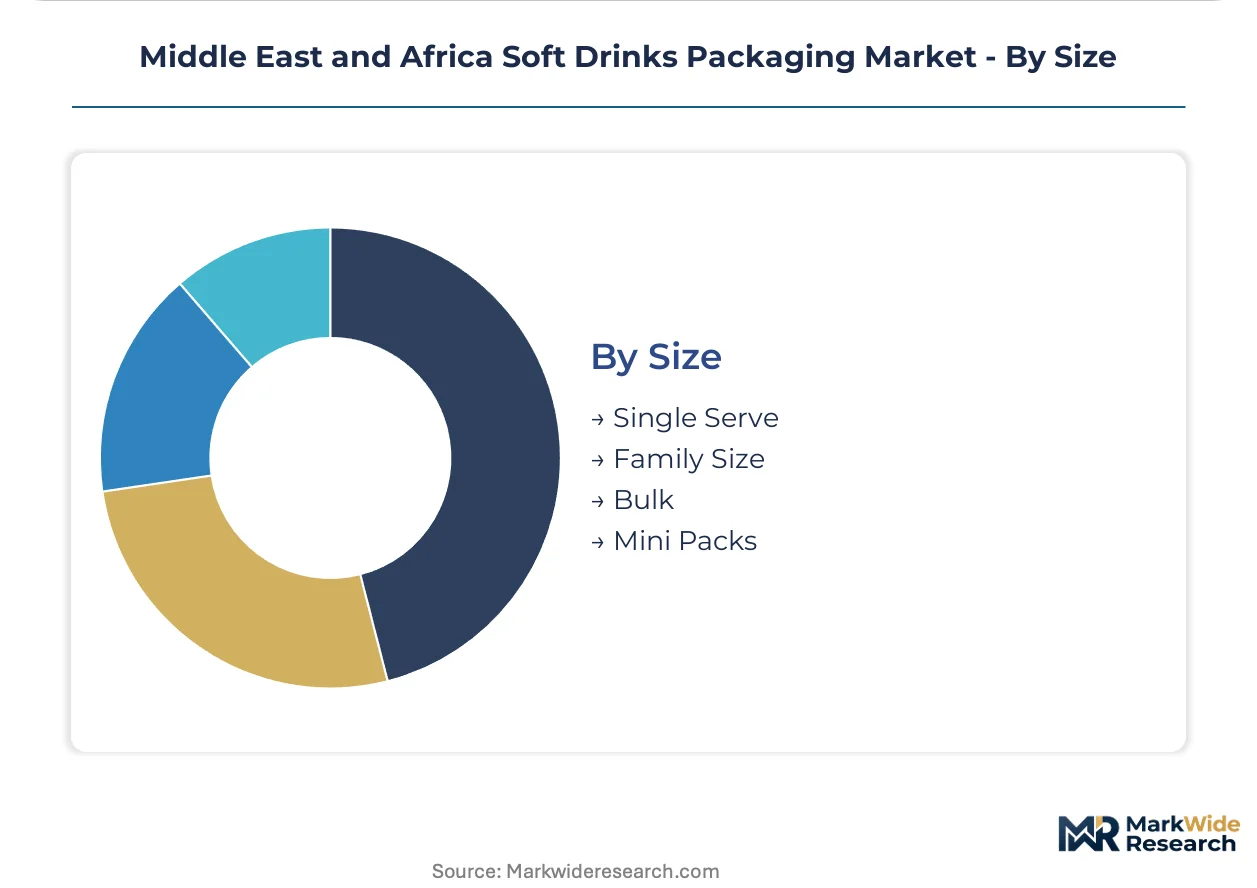
Size:
Volume-per-unit specifications determine distribution economics, retail shelf space allocation, and consumption occasion targeting across modern trade and traditional trade channel strategies.
- Single Serve:200-500 milliliter formats concentrate procurement from organized retail chains in Lagos and Cairo where multinational bottlers target on-the-go consumption and impulse purchase occasions in climate-stressed Gulf and North African markets.
- Family Size:1.5-2.25 liter PET bottles anchor Saudi and UAE household stock-up purchasing through modern trade penetration, with lightweighted designs reducing resin intensity per liter delivered.
- Bulk:5-19 liter returnable and non-returnable formats serve institutional and hospitality channels across Gulf states where water consumption volumes and storage economics favor larger unit sizes.
- Mini Packs:Multi-unit shrink-wrapped configurations target value-conscious Nigerian and Egyptian traditional trade segments where per-unit affordability and household inventory management drive purchase decisions.
Family size holds installed capacity. Single serve is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SASO technical regulations on food-contact materials anchor Saudi Arabia's dominant position in Gulf packaging compliance, with migration testing mandates rippling across UAE, Bahrain, and Kuwait border regimes.
Saudi Arabia
Riyadh and Jeddah bottling corridors drive PET preform demand as retail modernizes. SASO mandates third-party laboratory certification for all imported packaging substrates, compressing supplier qualification timelines. Eastern Province dairy processors deploy aseptic carton lines to bypass cold-chain investment in rural distribution.
United Arab Emirates
Dubai's mandatory deposit-return scheme for plastic bottles and aluminum cans creates infrastructure pull-through for recycling partnerships. Abu Dhabi and Sharjah manufacturing zones concentrate aluminum can production for premium carbonated soft drink positioning. MOHAP food-contact material standards run parallel to SASO frameworks, enabling cross-border substrate approvals.
South Africa
Department of Forestry, Fisheries and the Environment extended producer responsibility regulations require brand owners to fund post-consumer collection infrastructure. Gauteng and Western Cape bottling clusters pivot procurement toward recyclable PET and aluminum formats. Cape Town retail modernization accelerates single-serve format requirements in organized grocery channels.
Egypt
Cairo and Alexandria urban retail penetration drives family-size PET bottle demand for household stock-up purchasing. Egyptian Organization for Standardization and Quality enforces polymer migration limits for carbonated beverage containers, delaying product launches against SASO timelines. Delta region juice processors adopt lightweighted preform designs to reduce resin intensity per liter delivered.
Nigeria
Lagos organized retail chains centralize packaging procurement decisions, compressing supplier qualification cycles to quarterly performance reviews. Local polymer compounding capacity lags bottling line expansion, exposing converters to freight cost volatility from Asian petrochemical suppliers. Kano and Ibadan secondary cities accelerate single-serve format penetration in modern trade channels.
Middle East and Africa Soft Drinks Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational converters controlling aseptic carton and rigid plastic supply through regional manufacturing complexes. The mid-tier fragments across family-owned preform specialists and regional distributors serving Nigerian and Egyptian bottling operations. Three archetypes dominate: integrated material converters with backward resin control, equipment-anchored technical service providers, and aluminum rolling mill proximate can fabricators. Competitive moves concentrate on M&A for regional testing hub access and strategic partnerships for aseptic filling technician training pipelines.
Among Swiss and Australian-anchored packaging conglomerates, Tetra Pak International SA and Amcor plc occupy positions as integrated leaders with regional technical service infrastructure. SIG Group AG exemplifies the barrier-technology specialist tier competing on aluminum-free oxygen barrier innovation for ambient distribution climates.
| Leading Market Players |
|---|
| Tetra Pak International SA |
| Amcor plc |
| SIG Group AG |
| Ball Corporation |
| Crown Holdings Inc. |
| Pactiv LLC |
| Graham Packaging Company |
| Owens-Illinois Inc |
| Plastipak Holdings Inc. |
| Others |
Supply & Pricing Matrix
Long-term resin offtake contracts with Asian petrochemical suppliers lock in both PET preform supply access and six-month price visibility for Egyptian and Nigerian bottlers facing volatile freight rates from Gulf polymer ports. Saudi converters leverage backward integration into SABIC feedstock streams to compress input cost variance against importers dependent on spot resin markets.
Pricing Analysis
Gulf-to-Nigeria price spreads for virgin PET resin exceed those for recycled flake by a factor reflecting freight cost asymmetry and local compounding capacity gaps. Three-tier pricing structure across premium aseptic carton, standard PET bottle, and economy flexible pouch formats stratifies procurement decisions. Cost compression in economy pouches is intensifying because Asian laminate suppliers are absorbing margin erosion to maintain volume commitments. Price-sensitive traditional trade buyers in Kano and Ibadan informal channels drive spot purchasing behavior, while premium modern trade accounts in Dubai and Riyadh accept annual contract premiums for technical service bundling.
Supply Chain Analysis
Strait of Hormuz transit underwrites resin import economics for UAE and Saudi bottling corridors, exposing converters to geopolitical premium volatility in freight forwarding markets. Polymer supply concentrates in Saudi Arabia, UAE, and Egypt through SABIC, Borouge, and SIDPEC compounding infrastructure. Raw material dependencies span purified terephthalic acid, ethylene glycol, and aluminum coil stock from rolling mills in Bahrain and South Africa. Single-source vulnerability in aseptic carton substrate supply from Tetra Pak and SIG regional hubs creates concentration risk for Gulf juice processors. Distribution runs through Jebel Ali and Port Said container terminals into secondary city bottling plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Lagos and Cairo organized retail chains that have compressed supplier qualification cycles and unbundled equipment service from resin supply agreements. This consolidation among procurement decision-makers is tilting margin capture downstream.
For Market Incumbents: Compound technical service differentiation by embedding sterilization system operators directly at Gulf dairy and juice processing facilities, countering technician scarcity that constrains Tetra Pak and Krones equipment uptime. Pursue SASO certification pre-registration for all substrate imports into Saudi Arabia to capture shelf space as smaller competitors face compliance delays. Vertical integration into Egyptian polymer compounding addresses resin import dependency threatening Nigerian bottling economics. For New Entrants and Emerging Players: Anchor in Ethiopian organized retail white space where underpenetrated modern trade and nascent bottling infrastructure create first-mover positioning for aseptic carton and PET preform technical service providers. Target aluminum-free barrier innovation for temperature-sensitive juice distribution in Gulf secondary cities lacking cold-chain investment. Go-to-market leverage rests on SIG Group-style polymer-based oxygen barrier licensing rather than capital-intensive manufacturing footprint. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-anchored technical service providers with multi-year sterilization system maintenance contracts at Gulf dairy processors. Long-term viability across the analysis window favors acquisition targets with regional SASO testing hub access and established halal certification pathways. Signal to monitor: Dubai deposit-return scheme enforcement intensity as a proxy for recycling infrastructure pull-through demand.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Technician Training Pipeline | Addresses Gulf dairy processor equipment uptime constraints through certified sterilization system operator pools. |
| SASO Pre-Registration Investment | Captures Saudi shelf space as migration testing mandates compress competitor qualification timelines. |
| Aluminum-Free Barrier Licensing | Enables SIG Group-style shelf-stable juice distribution without cold-chain capital deployment. |
| Reverse Vending Partnership | Aligns with Dubai mandatory deposit-return infrastructure for plastic bottle and aluminum can collection. |
| Lightweighted Preform Scale-Up | Reduces per-unit resin consumption for Saudi 26-gram neck finish designs at fifty-degree Celsius stability. |
Research Methodology
Operator-level perspectives from PET preform plant managers, aseptic filling line technicians, modern trade category buyers in Lagos and Cairo, and SASO compliance officers anchored the qualitative base. Primary interviews with Tetra Pak regional service engineers and Egyptian polymer procurement leads combined with secondary validation from SASO technical regulation filings, EOS migration limit standards, South African EPR registration databases, and customs trade data for resin imports through Jebel Ali and Port Said. Bottom-up capacity estimates from bottling line counts triangulated against top-down consumption models.
Sensitivity analysis across resin price volatility scenarios and regulatory compliance delay probabilities shaped the analytical framework. Segmentation dimensions modeled include packaging format, material substrate, closure type, and size tier across the projection horizon. CAGRs derived from installed capacity expansion rates, retail modernization penetration curves, and per-capita soft drink consumption elasticities. Industry-specific inputs encompass Gulf ambient temperature distribution constraints and halal certification harmonization timelines.
Material uncertainties — polymer import tariff shifts, SASO testing backlog durations, and aseptic technician training output gaps — sit outside the modeled envelope. Forecasts reflect assumptions around continued urban retail modernization in Nigeria and Egypt and sustained EPR funding obligations in South Africa. Revision becomes warranted when Saudi-Egypt regulatory divergence on migration testing crosses thresholds that fragment cross-border substrate approvals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Bomber Bottles Market
Beverage Packaging
Stackable Beaker Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Zippered Bottle Suit Market
Beverage Packaging
Cup Sleeves Market
Beverage Packaging
Biotainer Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
Beverage Packaging Machine Market
Beverage Packaging
Twin Neck Bottles Market
Beverage Packaging
Bottled Water Packaging Market
Beverage Packaging
Europe Soft Drinks Packaging Market
Beverage Packaging
PET Bottle Market
Beverage Packaging
Water Cooler Market
Beverage Packaging
Beverage Cans Market
Beverage Packaging
Baritainer Jerry Can Market