
 Bottle Shippers Market | 2026-2036
Bottle Shippers Market Size, Share, and Industry Trends Forecast 2026-2036
Bottle Shippers Market Analysis
Buyer concentration across craft beverage e-commerce is broadening as direct-to-consumer alcohol platforms multiply and fragment order volumes across thousands of small producers. Sonoco Products Company leverages its molded fiber manufacturing scale to serve high-volume wine subscription clients. DS Smith Plc anchors European supply through recycled corrugated expertise and circular design protocols. Amcor plc competes with multi-material barrier solutions that bridge premium presentation with transit durability.
Bottle shippers are engineered protective packaging systems designed to immobilize individual or multi-unit liquid containers during distribution, typically employing corrugated board, molded pulp, or expanded foam with internal retention features such as die-cut cavities, finger-lock dividers, or cushioned sleeves. Their primary commercial purpose is to eliminate breakage-induced leakage, preserve label integrity, and satisfy carrier damage-claim thresholds for fragile liquid goods. The beverage end-user segment dominates volume consumption as wineries and distilleries scale direct fulfillment, while eco-friendly product types capture accelerating preference as brands face Scope 3 emissions scrutiny and retailer sustainability scorecards. Custom size configurations command premium positioning by reducing dimensional weight penalties and void fill waste, though small and medium stock formats retain the broadest SKU coverage.
The EPA guides recycled content thresholds for corrugated packaging in the United States, while the EU Packaging and Packaging Waste Regulation tightens recyclability mandates and extended producer obligations across European supply chains. California's SB 54 and Germany's VerpackG impose material-specific compliance costs that favor pulp-based and single-material fiber solutions over multi-component formats. Stakeholders must monitor regulatory divergence between North American state-level extended producer responsibility experiments and harmonized EU packaging rules to avoid stranded inventory and reformulation penalties.
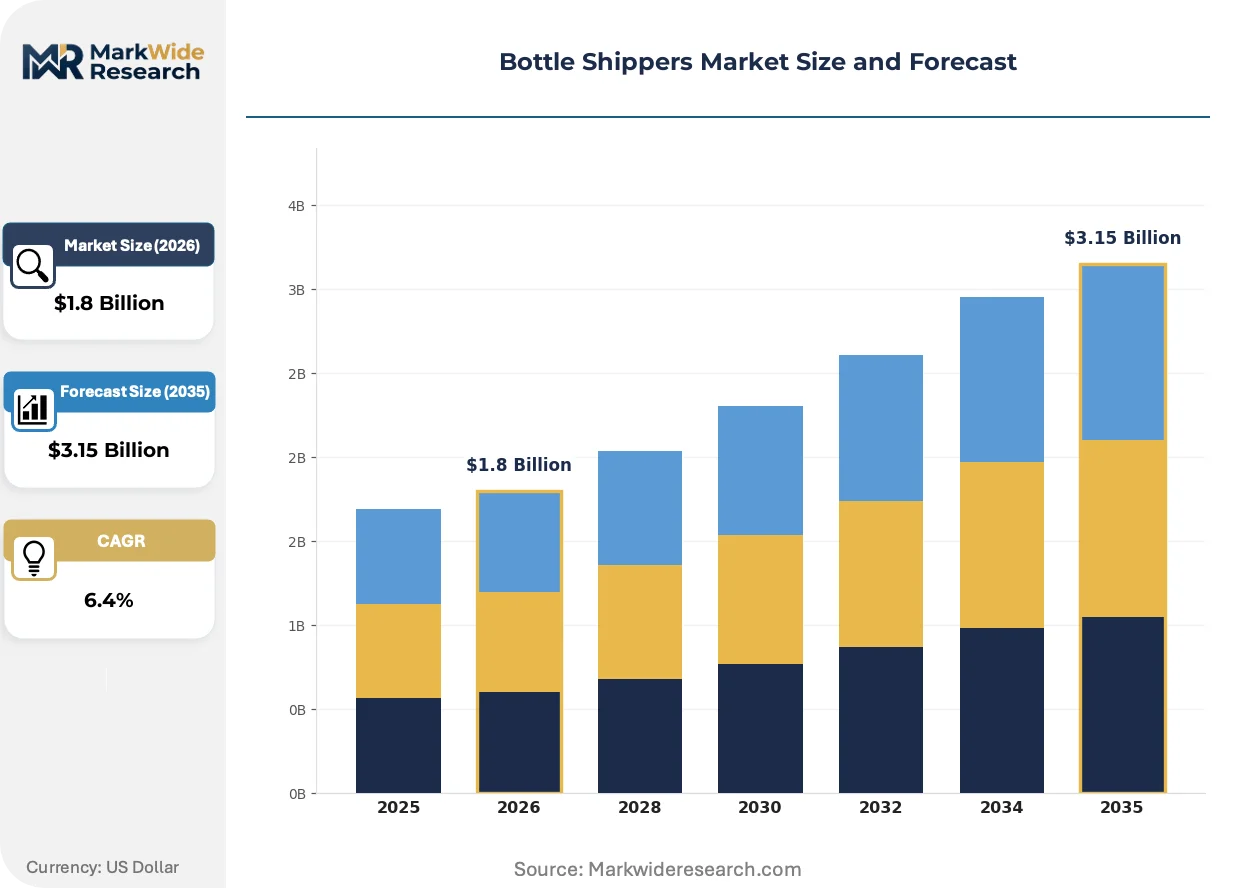
Market Dynamics
Direct-to-consumer alcohol shipping liberalization is fragmenting order volumes across thousands of small craft producers, forcing packaging suppliers to reconfigure production systems for shorter runs and faster turnaround times.
Growth Catalysts
- California SB 54 Extended Producer Responsibility:The law mandates recyclable packaging formats, accelerating corrugated and molded pulp adoption among wine and spirits brands seeking compliance.
- E-commerce Subscription Models:Monthly wine clubs and craft distillery direct fulfillment are generating recurring demand for protective transit packaging with consistent damage thresholds.
- Molded Pulp Manufacturing Scale:Investment in fiber-forming equipment is reducing unit costs for protective cavities, making sustainable formats cost-competitive with expanded polystyrene.
Market Restraints
- OCC Price Volatility:Old corrugated containerboard input costs swing with recycling collection rates, compressing margins for converters serving price-sensitive beverage clients.
- Multi-Material Format Stranding:Germany's VerpackG imposes higher fees on non-recyclable composite packaging, penalizing legacy foam-and-corrugated hybrid designs.
- Dimensional Weight Penalties:Parcel carriers apply density-based surcharges that disadvantage bulky protective inserts, forcing redesign toward minimal void configurations.
Strategic Opportunities
- Australia Direct Shipping Liberalization:Regulatory reforms permitting interstate alcohol e-commerce are opening demand for compliant protective packaging among emerging craft producers.
- Reusable Shipper Systems:Deposit-return logistics for high-value wine collections are creating a new service layer around packaging asset recovery and refurbishment.
- EU Packaging and Packaging Waste Regulation:Harmonized recyclability mandates across member states favor single-material fiber solutions that qualify for extended producer responsibility fee reductions.
Industry Challenges
- Structural Design Talent Scarcity:Engineers capable of optimizing protective geometry for both drop-test performance and material minimization command premium compensation in tight labor markets.
- Carrier Certification Timelines:ISTA 3A and Amazon Frustration-Free Packaging validation cycles extend 8-14 weeks, delaying product launches for seasonal beverage releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottle Shippers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Metal, Eco-friendly Packaging Type: Box, Crate, Pallet, Sleeve Size: Small, Medium, Large, Custom End User: Beverage Industry, Cosmetics, Pharmaceuticals, Others |
| Companies Covered | Sonoco Products Company, DS Smith Plc, Western Pulp Products Company, RADVA Corporation, Packaging Services Industries, Saxon Packaging Limited, Amcor plc, TricorBraun Inc., ULINE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottle Shippers Market Emerging Trajectories
Material science advances and regulatory stringency are compressing the viable design space for protective packaging, rewarding suppliers who integrate performance testing with rapid prototyping capabilities.
Molded fiber engineering is converging with precision thermoforming techniques to produce pulp-based retention features that match expanded polystyrene's cushioning performance. Wine subscription services in the United States and Germany are specifying these formats for premium tier shipments. The technology is converging with automated packaging lines to eliminate manual insertion labor and reduce per-unit handling costs.
The EU Packaging and Packaging Waste Regulation tightens recyclability definitions and extended producer responsibility obligations across European supply chains. Industrial consequence includes mandatory design-for-recycling protocols that disqualify multi-component formats from fee reductions. Wine and spirits exporters to the European Union are responding by qualifying single-material corrugated and molded pulp shippers ahead of enforcement deadlines.
Buyer procurement patterns are compressing supplier qualification cycles as direct-to-consumer platforms multiply. Small craft distilleries and urban wineries are bypassing traditional distribution intermediaries to source packaging directly from converters. This disintermediation is most visible in California, Texas, and New York, where regulatory liberalization has spawned hundreds of new alcohol e-commerce permits.
Bottle Shippers Market Segmentation
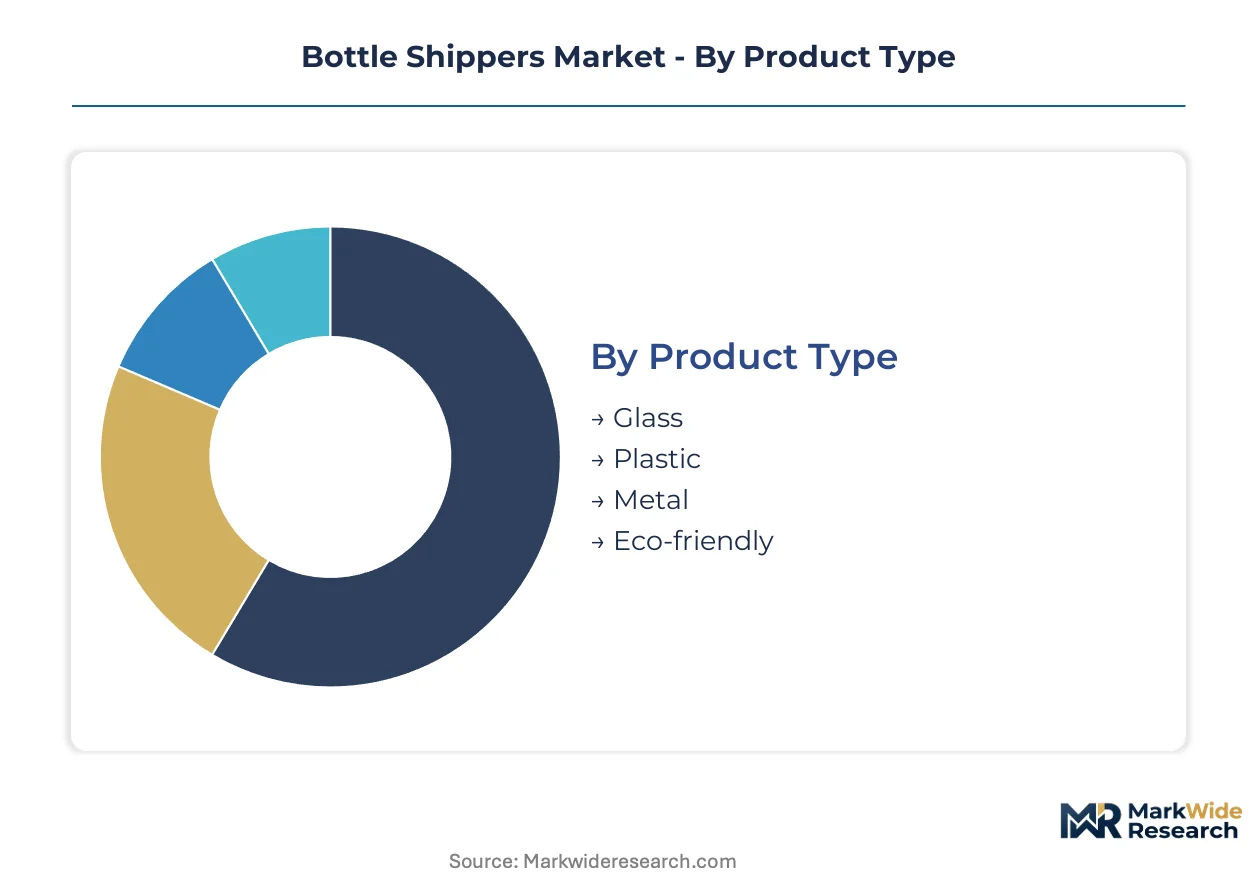
Segmentation in bottle shippers reveals how protective packaging specifications diverge across material science capabilities, logistics formats, and end-use compliance requirements. Understanding these divisions helps suppliers align production assets with the precise performance and regulatory demands of each customer tier.
Product Type:
Glass shippers function as standalone protective systems requiring engineered cushioning, while plastic and metal formats embed into broader multi-material logistics chains.
- Glass:Engineered corrugated and molded pulp cavities immobilize fragile wine and spirits bottles against impact and vibration. California wineries and German exporters specify these formats for direct-to-consumer shipments facing carrier damage claim thresholds.
- Plastic:PET and HDPE bottle shippers serve spirits and ready-to-drink beverages with lighter weight profiles that reduce dimensional weight penalties. Demand concentrates among craft distilleries in Texas and New York seeking cost-efficient protective solutions.
- Metal:Aluminum can shippers protect carbonated beverages and specialty cocktails during parcel distribution.
- Eco-friendly:Molded pulp and recyclable fiber formats satisfy California SB 54 and EU Packaging and Packaging Waste Regulation mandates.
Glass leads volumes today; eco-friendly formats are gaining share fastest.
Packaging Type:
Cost tiering separates single-parcel solutions from consolidated freight systems, with each tier commanding distinct margin structures and equipment requirements.
- Box:Corrugated fiberboard containers with die-cut retention features dominate wine club subscriptions and individual bottle shipments. These units integrate with automated fulfillment lines in California and Australian distribution centers.
- Crate:Reusable plastic and fiber crates serve high-value wine collections and deposit-return logistics programs. German and Australian producers specify these for recurring shipment cycles.
- Pallet:Bulk protective systems secure multi-case shipments for wholesale redistribution.
- Sleeve:Minimalist corrugated and pulp sleeves reduce material intensity for short-haul distribution.
Box formats anchor revenue today; crate systems are climbing the fastest as reusable logistics expand.
Size:
Volume concentration follows e-commerce order patterns, with fragmentation across small producers driving demand for flexible format ranges.
- Small:Single and dual-bottle configurations serve premium wine subscriptions and gift shipments. Urban wineries in New York and San Francisco specify these for last-mile delivery optimization.
- Medium:Four to six bottle units balance protective performance with parcel carrier dimensional weight thresholds. Australian craft distilleries favor these formats for interstate e-commerce compliance.
- Large:Case-quantity shippers support wholesale and club store distribution.
- Custom:Bespoke dimensions reduce void fill waste for irregular bottle geometries and limited-edition releases.
Medium sizes dominate unit volumes today; custom configurations are expanding most quickly among premium tier producers.
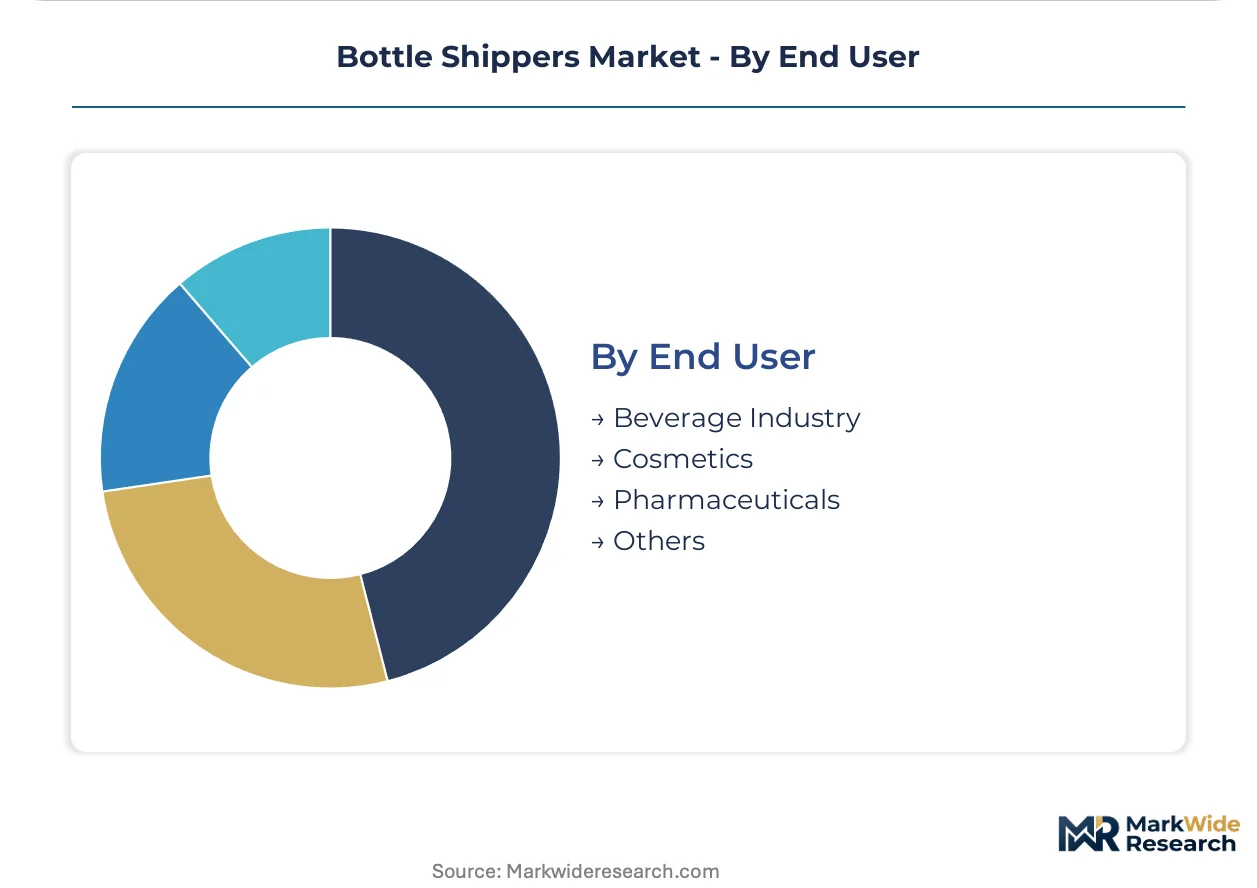
End User:
Application maturity varies sharply, with beverage industry requirements setting performance benchmarks that other sectors adapt at reduced specification intensity.
- Beverage Industry:Wineries, distilleries, and breweries specify ISTA 3A certified shippers with defined drop-test performance. California, Germany, and Australia concentrate demand as direct shipping regulations liberalize.
- Cosmetics:Fragrance and skincare brands adopt beverage-grade protective formats for glass bottle security. European luxury houses specify molded pulp solutions to satisfy EU recyclability mandates.
- Pharmaceuticals:Liquid medication and diagnostic kit producers require validated cold chain and shock protection.
- Others:Specialty food oils and artisanal condiments adapt standard beverage shipper designs.
Beverage Industry leads volumes today; Cosmetics is gaining share fastest as premium beauty e-commerce accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for bottle shippers outpaces German volume by roughly two-to-one, yet both markets face tightening extended producer responsibility frameworks that favor fiber-based formats over legacy foam solutions.
United States
California wineries and Texas craft distilleries drive protective packaging procurement as direct-to-consumer alcohol shipping permits multiply. The EPA guides recycled content thresholds for corrugated packaging, while California's SB 54 mandates recyclable formats with specific compliance timelines. Los Angeles and San Francisco distribution centers automate fulfillment lines around molded pulp shipper specifications.
Germany
German wine exporters and beer subscription services generate sustained demand for ISTA-certified transit protection. The VerpackG packaging law imposes escalating fees on non-recyclable composite formats, pushing converters toward single-material fiber solutions. The Rhine-Main region anchors converter capacity serving pan-European beverage logistics.
Australia
Interstate alcohol e-commerce liberalization unlocks demand among emerging craft producers previously blocked from direct fulfillment. The Australian Competition and Consumer Commission oversees consumer protection standards affecting damage claim protocols. Melbourne and Sydney fulfillment clusters specify medium-format shippers optimized for parcel carrier dimensional weight thresholds.
France
Champagne houses and Bordeaux exporters adopt beverage-grade protective formats for premium tier international shipments. The EU Packaging and Packaging Waste Regulation tightens recyclability definitions with enforcement deadlines approaching. The Grand Est region concentrates molded fiber manufacturing capacity serving luxury spirits brands.
United Kingdom
London-based wine merchants and craft gin distilleries scale direct fulfillment infrastructure following post-Brexit customs stabilization. The Environment Agency implements packaging waste regulations aligned with EU circular economy frameworks. The Midlands logistics corridor hosts automated packaging lines integrating pulp-based retention systems.
Bottle Shippers Market Vendor Landscape
United States producers anchor one tier; European specialists hold certification and circular design expertise that commands premium positioning in regulated markets. The vendor base spans integrated packaging conglomerates and regional molded fiber specialists, with consolidation pressure mounting as beverage clients reduce supplier counts. Three archetypes dominate: scale-driven fiber formers, multi-material barrier innovators, and reusable logistics system operators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with converters seeking geographic proximity to emerging craft production clusters.
Among North American-based fabricators, Sonoco Products Company and ULINE exemplify scale-driven archetypes, while DS Smith Plc anchors European supply through recycled corrugated expertise. Amcor plc occupies a position bridging premium presentation with transit durability through multi-material solutions. These three companies represent the structural poles around which mid-tier specialists and regional converters organize competitive positioning.
| Leading Market Players |
|---|
| Sonoco Products Company |
| DS Smith Plc |
| Western Pulp Products Company |
| RADVA Corporation |
| Packaging Services Industries |
| Saxon Packaging Limited |
| Amcor plc |
| TricorBraun Inc. |
| ULINE |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up molded fiber specialists have consolidated regional converter capacity across California and the Rhine-Main corridor, tightening supply discipline while extracting procurement leverage from fragmented craft beverage clients facing California SB 54 compliance deadlines.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for ISTA-certified corrugated and molded pulp formats. Three-tier pricing structure across premium, standard, and economy levels separates custom-engineered solutions with rapid prototyping capabilities from stock-format commodity shippers. Price differentiation hinges on certification grade and volume scale, with small urban wineries exhibiting acute price sensitivity while Champagne houses absorb premium positioning. Cost compression in standard-tier formats is intensifying because OCC input volatility transfers directly to converter margins.
Supply Chain Analysis
Domestic-content mandates under California SB 54 and Germany's VerpackG are reshaping sourcing patterns toward localized fiber recovery and regional pulp forming operations. Supply concentrates in the United States, Germany, and Australia as direct-to-consumer alcohol shipping liberalizes. Raw material dependencies center on old corrugated containerboard streams, recycled pulp fiber, and molded fiber forming equipment. Single-source vulnerability runs through specialized thermoforming machinery constrained by structural design talent scarcity. Distribution runs through converter-direct relationships with craft producers, bypassing traditional distribution intermediaries in California, Texas, and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with regulatory-driven format transitions under California SB 54 and EU Packaging and Packaging Waste Regulation generating recurring replacement demand across installed base volumes.
For Market Incumbents: Anchor defensive positioning through backward integration into regional pulp recovery networks and captive supply of molded fiber forming capacity. Invest in ISTA 3A certification infrastructure to extend validation timeline advantages over emerging competitors. Consolidate around automated packaging line integration capabilities as craft producers eliminate manual insertion labor. For New Entrants and Emerging Players: Begin with Australia's interstate alcohol e-commerce liberalization, where regulatory reform has outpaced established converter footprint. Target medium-format corrugated shippers for emerging craft distilleries in Melbourne and Sydney fulfillment clusters. Pursue deposit-return logistics partnerships as a service-layer wedge beyond commodity shipper manufacturing. For Investors and Strategic Acquirers: Valuations sit cheapest among regional molded fiber specialists lacking automated line integration capabilities but holding California SB 54-compliant format libraries. Five-to-ten year viability rests on circular design expertise transferability across EU and North American regulatory convergence. Watch molded pulp unit cost parity with expanded polystyrene as the inflection signal for sustainable format share acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Recovery | Captive fiber supply secures margin stability under OCC price volatility. |
| ISTA 3A Certification Infrastructure | Validation capabilities compress launch timelines for seasonal beverage releases. |
| Automated Packaging Line Integration | Elimination of manual insertion labor reduces per-unit handling costs for wine subscriptions. |
| Deposit-Return Logistics Partnership | Asset recovery services create recurring revenue streams beyond single-use shipper sales. |
| Custom Rapid Prototyping Capabilities | Speed-to-market for limited-edition releases commands premium positioning among urban wineries. |
Methodological Framework
Bottom-up beverage industry modeling reconciled against top-down corrugated and molded pulp capacity tracking forms the analytical core. Primary interviews with packaging converters, craft distillery operations managers, wine club fulfillment directors, and California regulatory compliance officers combined with secondary validation from EPA recycled content guidelines, EU Packaging and Packaging Waste Regulation texts, customs trade data for protective packaging imports, and SEC filings from listed packaging conglomerates. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of wine and spirits e-commerce shipment volumes, direct-to-consumer permit issuance patterns, and protective packaging procurement cycles informed projection frameworks. Segmentation dimensions modeled include material format, packaging type, size configuration, and end-use industry across the analysis window. CAGRs derive from regression against e-commerce penetration curves and regulatory enforcement timeline assumptions, with specific inputs from carrier dimensional weight penalty schedules and extended producer responsibility fee structures.
Caveats apply where OCC commodity price spikes, carrier surcharge regime changes, or accelerated EU recyclability mandate enforcement could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory timeline adherence and craft producer e-commerce adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Ice Transport Buckets Market
Beverage Packaging
Heavy Wall Bottles Market
Beverage Packaging
Beveled Bottles Market
Beverage Packaging
Combi Cans Market
Beverage Packaging
Beverage Cans Market
Beverage Packaging
Slip Cover Cans Market
Beverage Packaging
Water Cooler Market
Beverage Packaging
Water Bottle Racks Market
Beverage Packaging
Beverage Packaging Machine Market
Beverage Packaging
Aluminium Cup Market
Beverage Packaging
Drink Can Market
Beverage Packaging
Bamboo Cups Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
Tumblers Market