
 Can Sleeves Market | 2026-2036
Can Sleeves Market Size, Share, and Industry Trends Forecast 2026-2036
Can Sleeves Market Outlook
Premium-grade thermal insulation specifications are reorganizing competitive dynamics across the can sleeves landscape. Avery Dennison Corporation leverages its materials science portfolio to dominate high-performance barrier segments. Fuji Seal International anchors Asia-Pacific supply networks through specialized shrink-sleeve manufacturing capabilities. CCL Industries Inc. differentiates via custom-printed decorative sleeves serving beverage brand owners.
Can sleeves are cylindrical wraps manufactured from neoprene, latex, silicone, or foam substrates, typically 3-5 millimeters thick, designed to insulate beverage containers and provide printable branding surfaces. Insulated sleeves lead product-type revenue due to their functional temperature-retention properties in outdoor consumption settings, while custom sleeves capture expanding margin pools as beverage manufacturers prioritize limited-edition brand campaigns. Neoprene dominates material-type volume for its durability and water resistance, though silicone is gaining traction in reusable premium segments.
EU REACH compliance and FDA food-contact material standards govern substrate chemistry and migration limits, directly influencing raw material selection and supplier qualification timelines. The EU Green Deal's packaging waste targets are accelerating shifts toward recyclable and mono-material sleeve constructions. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in closed-loop recycling partnerships or pivot to bio-based substrate alternatives.
Market Dynamics
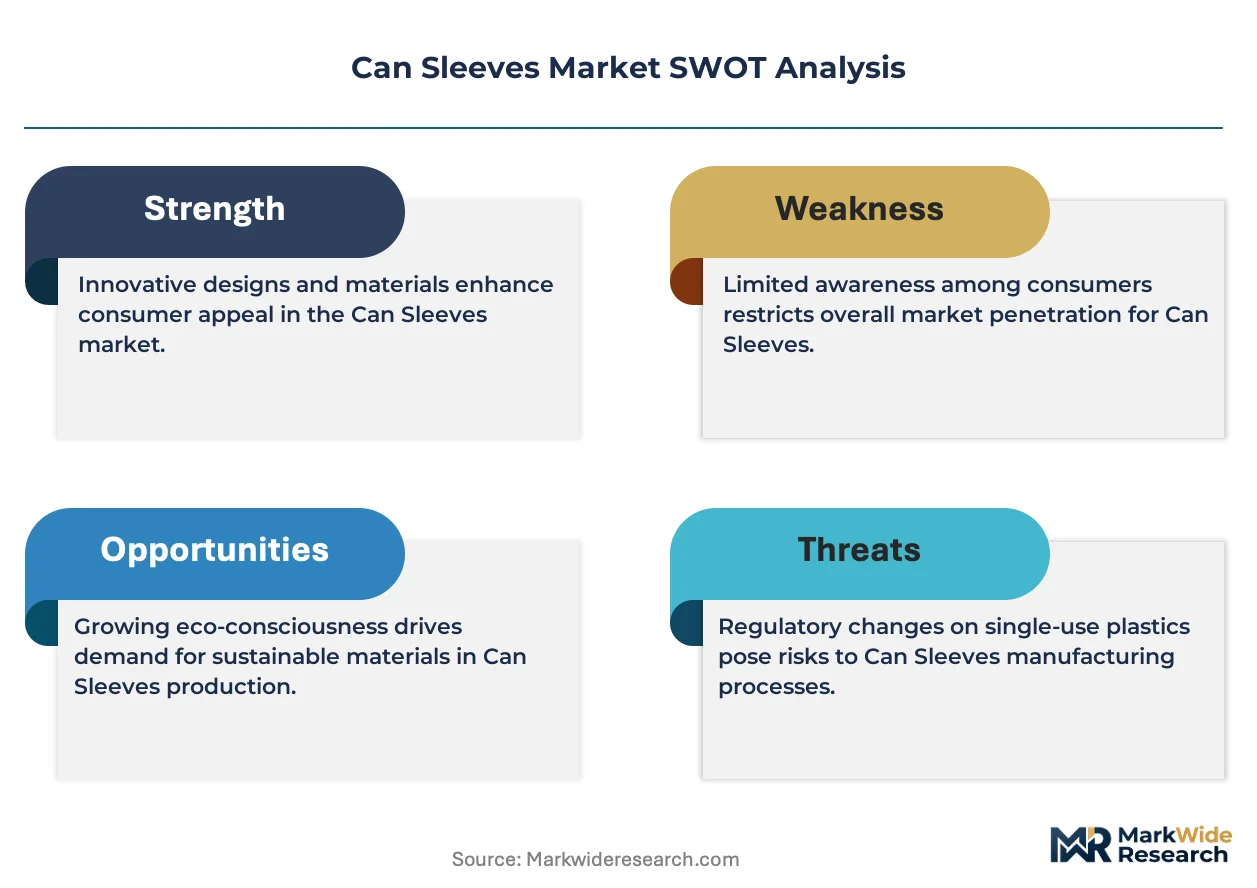
EU REACH compliance and the EU Green Deal's packaging waste targets are forcing substrate chemistry redesigns across the can sleeves supply base, compressing qualification timelines and elevating technical barriers for new entrants.
Growth Catalysts
- Outdoor Event Culture:Germany's craft brewery density and festival economy sustain specialized sleeve procurement for temperature-sensitive beverage distribution.
- Extended Producer Responsibility:EU member state frameworks mandate mono-material sleeve constructions, pulling investment into recyclable barrier technologies.
- Neoprene Durability Standards:Water resistance specifications in marine and coastal consumption settings protect incumbent material positions against silicone alternatives.
Market Restraints
- Petrochemical Feedstock Volatility:Neoprene and synthetic rubber prices fluctuate with crude oil derivatives, compressing margin predictability for mid-tier converters.
- Asia-Pacific Supply Concentration:Shrink-sleeve substrate and specialized printing equipment cluster in regional manufacturing hubs, exposing buyers to logistics disruption.
- Silicone Premium Pricing:Reusable segment adoption faces cost barriers against single-use foam alternatives in price-sensitive beverage categories.
Strategic Opportunities
- India PLI Scheme:Domestic packaging material incentives attract contract manufacturing investment for export-oriented beverage brands.
- Bio-Based Substrate Convergence:Algae-derived foams and agricultural waste fibers intersect with composting infrastructure expansion in Nordic markets.
- Direct-to-Brewery Digital Channels:Custom sleeve configurators bypass traditional distributor markups for small-batch craft producers.
Industry Challenges
- Migration Testing Timelines:FDA food-contact certification for novel substrates extends 18-24 months, delaying product launches.
- Legacy Printing Integration:Digital sleeve decoration systems require capital retrofitting of gravure and flexographic lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Can Sleeves Market |
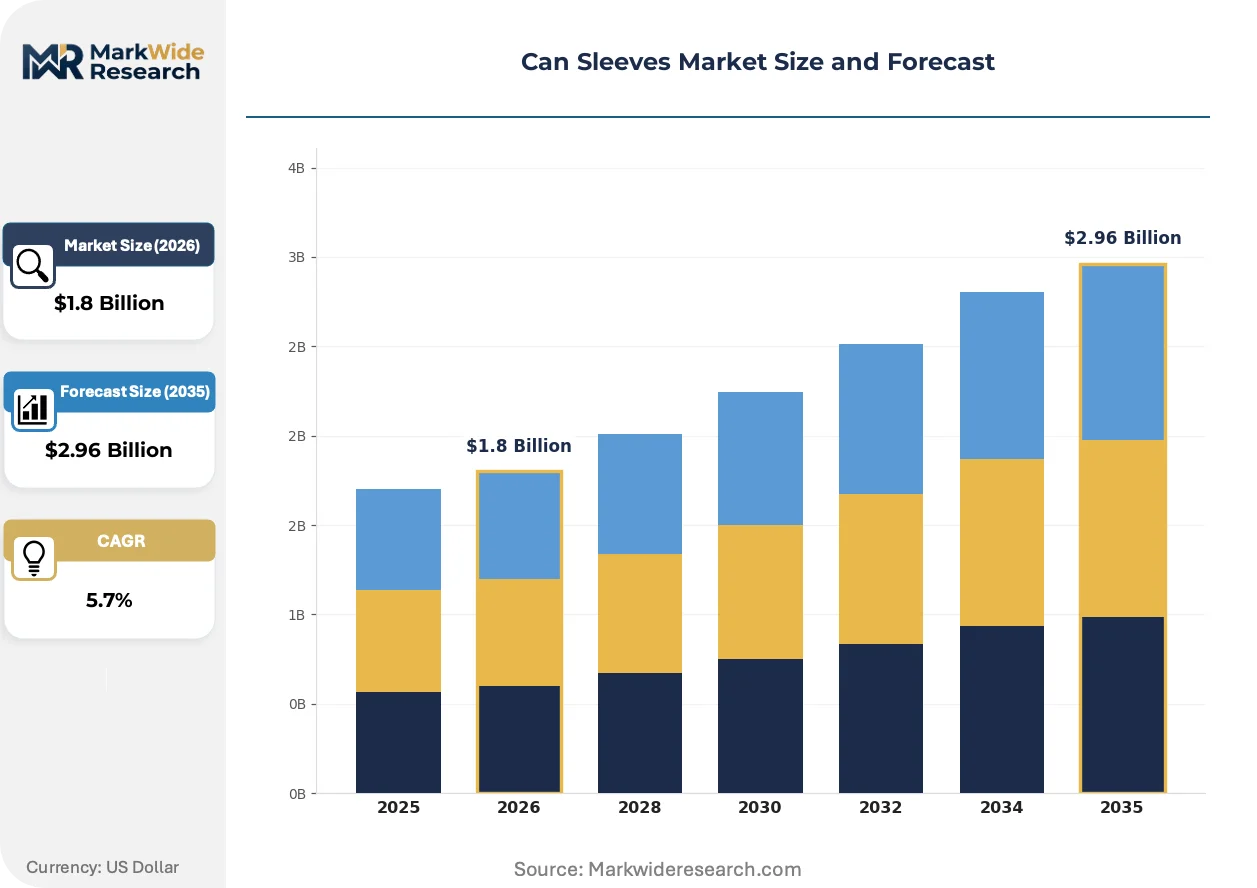
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Neoprene, Latex, Silicone, Foam Product Type: Insulated Sleeves, Non-Insulated Sleeves, Custom Sleeves, Standard Sleeves End User: Beverage Manufacturers, Retail Stores, Event Organizers, Promotional Companies Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Avery Dennison Corporation, Fuji Seal International, Amcor Plc, CCL Industries Inc., Huhtamaki Oyj, Klöckner Pentaplast Group, Berry Global Group, Multi-Color Corporation, Sonoco Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Can Sleeves Market Strategic Shifts
Mono-material sleeve architectures and digital printing workflows are dismantling established converter economics while opening margin pools for specialized barrier technologists.
Silicone foam laminates are decomposing the traditional neoprene-insulated sleeve hierarchy. Premium outdoor equipment brands and reusable beverage container manufacturers are adopting these substrates for dishwasher-safe durability. The technology is decomposing volume concentration among petrochemical-dependent foam converters.
EU Green Deal packaging waste targets are mandating recyclable mono-material constructions. REACH compliance timelines now require full substrate chemistry disclosure for food-contact approval. German brewers and Nordic beverage exporters face the steepest reformulation deadlines.
Brand owners now specify limited-edition sleeve campaigns with 48-hour design-to-delivery requirements. Traditional catalog-based distributors are losing share to digital-native converters with automated pre-press workflows. Craft brewery clusters in Belgium and the Netherlands demonstrate the most aggressive procurement cycle compression.
Can Sleeves Market Segmentation
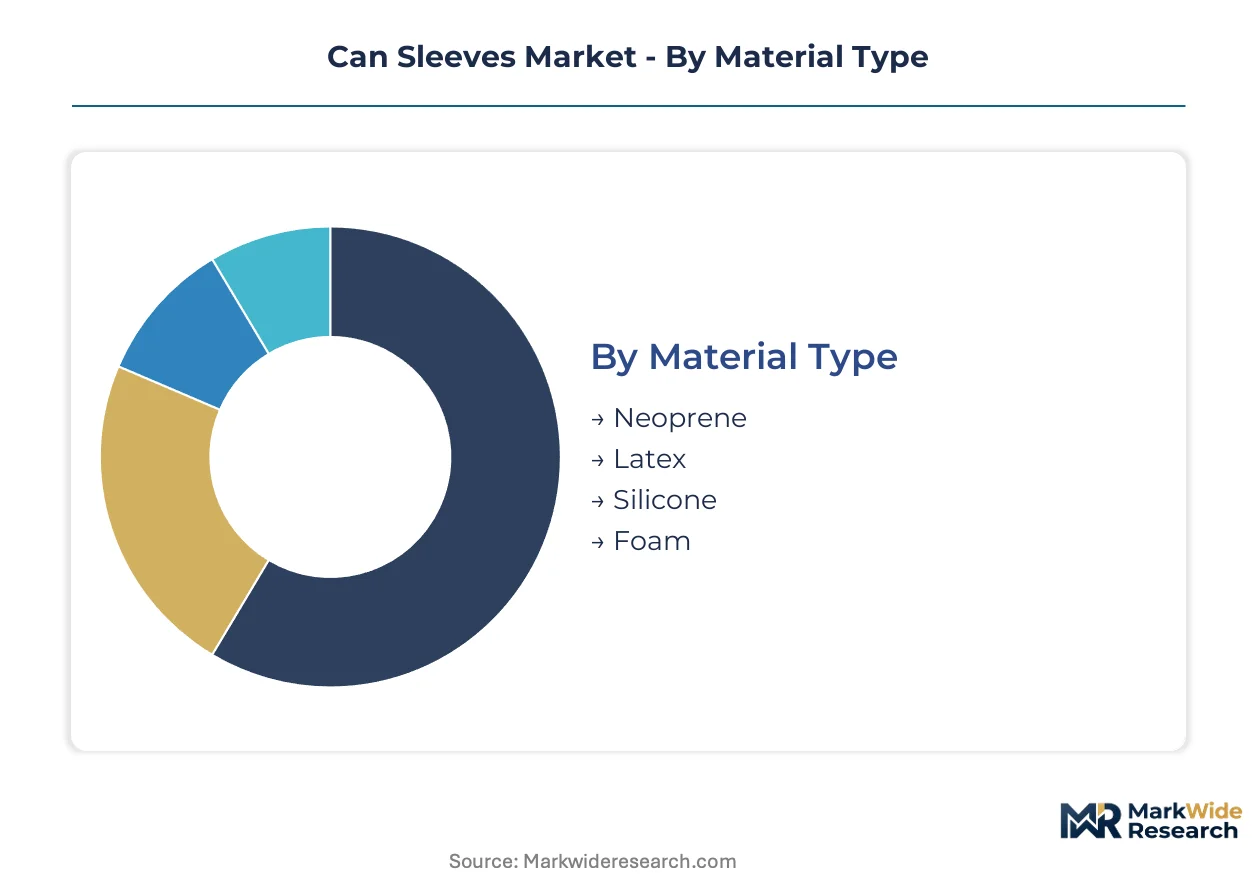
Can sleeves segmentation reveals divergent supply chain configurations across material chemistry and procurement channels. Distinct qualification requirements separate domestic converter relationships from export-oriented contract manufacturing arrangements.
Material Type:
Neoprene and foam substrates dominate domestic European production, while silicone and latex sourcing concentrates in Asia-Pacific export hubs serving brand owners with extended producer responsibility mandates.
- Neoprene:Closed-cell synthetic rubber construction delivers 3-5 millimeter thermal barriers with superior water resistance for marine and coastal consumption settings. German craft breweries and Nordic outdoor equipment brands specify neoprene for dishwasher-safe durability in reusable beverage programs. REACH compliance timelines for chloroprene-based chemistry now compress supplier qualification windows.
- Silicone:Platinum-cured elastomer formulations enable food-contact certification with migration limits below FDA thresholds. Premium outdoor equipment manufacturers in Switzerland and Austria specify silicone for temperature ranges spanning -40°C to 230°C, though petrochemical feedstock volatility elevates unit costs against foam alternatives.
- Latex:Natural rubber derivatives serve price-sensitive promotional segments with biodegradable disposal pathways.
- Foam:Polyethylene and polyurethane open-cell structures dominate single-use event distribution with lowest unit economics.
Neoprene holds the largest share; momentum sits with silicone as reusable container programs expand.
Product Type:
Cost tier stratification separates functional insulation specifications from decorative brand campaigns, with premium thermal performance commanding 3-4x manufacturing investment against standard printable wraps.
- Insulated Sleeves:Multi-layer barrier constructions combining closed-cell substrates with reflective metallized films achieve 4-6 hour temperature retention for outdoor festival distribution. German Oktoberfest operators and Belgian brewery cooperatives specify insulated formats for extended consumption windows in ambient conditions.
- Custom Sleeves:Digital printing workflows enable 48-hour design-to-delivery cycles for limited-edition brand activations. Netherlands craft brewery clusters and Danish beverage exporters compress procurement cycles through automated pre-press configurators bypassing traditional distributor markups.
- Non-Insulated Sleeves:Single-layer printable substrates serve indoor retail environments with minimal thermal performance requirements.
- Standard Sleeves:Catalog-based volume formats with gravure decoration support promotional commodity procurement.
Insulated sleeves command the highest production investment; custom sleeves are climbing the fastest as brand campaign frequency accelerates.
End User:
Application intensity varies sharply across customer types, with beverage manufacturers integrating sleeves into primary packaging specifications while event organizers treat procurement as discretionary operational spend.
- Beverage Manufacturers:Integrated sleeve specifications accompany premium product line launches with mono-material constructions mandated by EU Green Deal packaging waste targets. German and Austrian brewery groups now require full substrate chemistry disclosure for food-contact approval, extending supplier onboarding to 18-24 month cycles.
- Event Organizers:Seasonal procurement patterns concentrate demand in German festival economy clusters and Belgian outdoor event circuits, with temperature-sensitive beverage distribution driving specialized sleeve requirements.
- Retail Stores:Private-label sleeve programs for house-brand beverage accessories.
- Promotional Companies:Low-minimum-order-quantity procurement for corporate branding campaigns.
Beverage manufacturers anchor volume commitment; event organizers demonstrate the steepest expansion trajectory as festival culture proliferates across Northern Europe.
Distribution Channel:
Channel selection correlates directly with customer scale and customization requirements, with digital-native converters capturing share from legacy catalog distributors among small-batch producers.
- Online Retail:Direct-to-brewery digital channels enable automated sleeve configurators with real-time artwork approval workflows. Belgium and Netherlands craft producer clusters demonstrate highest platform adoption rates, bypassing traditional wholesale markups.
- Wholesale Distributors:Inventory-carrying intermediaries serve retail chains and event operators with standardized catalog formats and 2-4 week lead times.
- Specialty Stores:Curated selection for outdoor equipment and beverage accessory retail.
- Direct Sales:Converter field organizations manage beverage manufacturer accounts with integrated packaging specification teams.
Wholesale distributors maintain the broadest reach; online retail is gaining share fastest among sub-scale craft producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neoprene and silicone substrate manufacturing clusters in Germany, China, and the United States supply converters across three continents. REACH compliance timelines in Europe, FDA certification requirements in North America, and export-oriented contract manufacturing in Asia shape distinct procurement patterns.
Germany
Oktoberfest operators and craft brewery cooperatives in Bavaria drive insulated sleeve specifications for ambient temperature distribution. The EU Green Deal mandates mono-material constructions by 2030, compressing supplier reformulation cycles. Munich and Berlin host the densest converter networks serving Nordic beverage exporters.
United States
Outdoor equipment brands in the Pacific Northwest and Colorado specify dishwasher-safe silicone laminates for reusable container programs. FDA food-contact material standards govern substrate migration limits, extending novel material qualification to 18-24 months. Portland and Denver clusters specialize in digital-native sleeve configurators for craft producers.
China
Shrink-sleeve substrate and specialized printing equipment concentrate in Guangdong and Zhejiang provinces serving export markets. Dual carbon goals and MEE environmental standards are accelerating shifts toward recyclable mono-material barrier technologies. Shenzhen converters dominate high-volume promotional sleeve production for North American beverage brands.
India
Maharashtra and Karnataka beverage manufacturers are expanding sleeve-integrated premium product lines under PLI scheme incentives for domestic packaging materials. FSSAI food-contact regulations and BIS standards govern substrate chemistry disclosure. Mumbai and Bangalore clusters attract contract manufacturing investment for export-oriented craft brewery supply.
Japan
Platinum-cured silicone formulations from Nagoya and Osaka converters serve premium outdoor equipment specifications with temperature ranges spanning -40°C to 230°C. METI industrial standards and PMDA food-contact frameworks elevate technical barriers for imported substrates. Kansai-region specialists supply Swiss and Austrian alpine equipment brands.
Can Sleeves Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the can sleeves supply base. Materials science specialists with barrier film portfolios compete against high-volume converters with gravure and flexographic decoration capabilities. Three archetypes dominate: integrated packaging conglomerates with substrate-to-print vertical control, specialized sleeve converters with digital workflow automation, and regional foam fabricators serving promotional segments. Competitive moves center on M&A for barrier technology acquisition and capacity expansion in India and Southeast Asia to serve export demand.
Within the materials science tier, Avery Dennison Corporation and CCL Industries Inc. exemplify substrate-to-decoration integration strategies. Fuji Seal International anchors Asia-Pacific supply networks through its specialized manufacturing footprint. These three companies occupy positions across premium thermal barrier and custom-printed decorative segments respectively.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Fuji Seal International |
| Amcor Plc |
| CCL Industries Inc. |
| Huhtamaki Oyj |
| Klöckner Pentaplast Group |
| Berry Global Group |
| Multi-Color Corporation |
| Sonoco Products |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with German craft brewery cooperatives lock in neoprene substrate access while insulating converters from petrochemical feedstock volatility. These arrangements tether unit economics to REACH compliance timelines and EU Green Deal mono-material mandates, compressing margin visibility for spot-market participants.
Pricing Analysis
EU REACH compliance dictates the pricing tier structure across the can sleeves landscape. Three-tier pricing structure across premium silicone, standard neoprene, and economy foam levels separates dishwasher-safe reusable programs from single-use event distribution. Price differentiation stems from FDA food-contact certification grade and customization turnaround speed. Cost compression in the foam tier is intensifying because polyethylene feedstock tracks crude oil derivatives. Promotional companies and event organizers exhibit the highest price sensitivity, while Swiss and Austrian outdoor equipment brands absorb silicone premiums for temperature-range specifications.
Supply Chain Analysis
China and Germany anchor can sleeves substrate manufacturing, with Guangdong province hosting shrink-sleeve equipment clusters and Bavaria housing neoprene converter networks for Nordic beverage exports. Raw material dependencies center on chloroprene rubber, platinum-cured silicone elastomers, and metallized barrier films. Single-source vulnerability concentrates in Asia-Pacific printing equipment, exposing European buyers to logistics disruption. Distribution runs through wholesale distributors for retail chains and direct-to-brewery digital channels for Belgium and Netherlands craft producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier film formulation expertise and REACH-compliant chemistry disclosure capabilities are concentrated among a narrow tier of materials science specialists, creating acquisition premiums for qualified substrate suppliers.
For Market Incumbents: Compound technical moats by acquiring digital sleeve decoration specialists with automated pre-press workflows, defending against direct-to-brewery configurators that bypass traditional distributor markups. Extend backward integration into platinum-cured silicone supply to capture reusable segment premiums before bio-based foams achieve scale. For New Entrants and Emerging Players: FDA food-contact certification fast-tracks for novel substrates unlock entry into premium outdoor equipment supply chains currently served by Nagoya and Osaka converters. White-space sits in algae-derived foam formulations for Nordic composting infrastructure and contract manufacturing under India's PLI scheme for export-oriented beverage brands. Lead with 48-hour design-to-delivery digital platforms targeting Belgium craft brewery clusters. For Investors and Strategic Acquirers: Digital-native sleeve converters with automated artwork approval workflows represent the most defensible acquisition archetype as procurement cycle compression accelerates. Long-term viability hinges on mono-material construction capabilities aligned with EU Green Deal packaging waste targets. Watch for inflection when German brewers begin disqualifying non-compliant suppliers from specification lists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Supply | Captures reusable segment margins from Swiss and Austrian outdoor equipment brands. |
| Digital Sleeve Configurator Launch | Bypasses wholesale markups for Belgium and Netherlands craft brewery clusters. |
| REACH-Compliant Substrate Certification | Unlocks German brewery cooperative procurement with 18-24 month qualification timelines. |
| Algae-Derived Foam Scale-Up | Aligns with Nordic composting infrastructure expansion under EU Green Deal targets. |
| India PLI Contract Manufacturing | Serves export-oriented beverage brands with FSSAI-compliant domestic production. |
Study Parameters
Desk research of EU regulatory filings, customs trade data, and beverage manufacturer sustainability reports preceded structured interviews with converter plant managers, brewery procurement leads, and outdoor equipment brand supply chain directors. Primary fieldwork across German Oktoberfest operators and Belgian craft brewery clusters was cross-validated against secondary sources including ECHA substance registration databases and FDA food-contact material guidance documents. Bottom-up volume modeling was triangulated with top-down packaging spend analysis.
Variance decomposition across material type, product tier, and end-use application shaped the analytical framework throughout the forecast period. Segmentation dimensions included substrate chemistry, thermal performance specification, procurement channel, and regional regulatory cluster. CAGRs were derived from installed base growth and replacement cycle analysis, with neoprene durability standards and silicone adoption curves as key industry-specific inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable petrochemical feedstock availability; material deviation would warrant model refresh. Specific risk factors include REACH compliance timeline extensions, bio-based substrate breakthroughs, and Asia-Pacific logistics disruption. Recalibration cycles align with material shifts in regulatory enforcement and substrate technology substitution rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Slip Cover Cans Market
Beverage Packaging
PET Bottle Market
Beverage Packaging
Combi Cans Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Disposable Tea Flask Market
Beverage Packaging
Water Cooler Market
Beverage Packaging
Sugarcane Bottles Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
Middle East and Africa Soft Drinks Packaging Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Europe Beverage Container Market
Beverage Packaging
Beverage Cups Market
Beverage Packaging
Stackable Beaker Market
Beverage Packaging
Zippered Bottle Suit Market