
 Global Container Glass Market | 2026-2036
Global Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Global Container Glass Market Intelligence
The return to glass from plastics for premium product packaging is shifting the economic calculus for beverage and cosmetics brands. This trend is driven by consumer perceptions of glass as a higher quality and more sustainable material. Owens-Illinois Inc leverages its extensive manufacturing footprint to serve large multinational beverage clients. Ardagh Group SA specializes in both glass and metal packaging, offering diversified solutions to food and beverage customers. Gerresheimer AG leads the high-value pharmaceutical glass segment with its focus on vials and ampoules.
Container glass is a specific formulation of soda-lime glass, primarily composed of silica sand, soda ash, and limestone, formed into rigid containers. Manufacturing utilizes either the press-and-blow process for wide-mouth jars or the blow-and-blow process for narrow-neck bottles. Within applications, the beverage segment, particularly for alcoholic drinks, constitutes the largest volume share. Pharmaceutical vials and ampoules, while a smaller volume, represent a high-margin category due to stringent quality and regulatory requirements.
Regulations governing food-contact materials, such as those from Europe's EFSA, dictate composition and testing protocols. Environmental mandates, including recycling targets set by the US EPA and emissions standards enforced by China's MEE, influence manufacturing processes and raw material sourcing. Producers must balance investments in energy-efficient furnace technology against the persistent cost competition from alternative packaging materials.
Market Dynamics
The central tension shaping the container glass industry is the collision between sustainability mandates and the sector's inherent energy intensity. Demands for higher recycled content and reduced packaging weight are pressuring manufacturers to innovate while simultaneously navigating volatile energy costs for furnaces.
Growth Catalysts
- Premiumization in Beverages:The shift in consumer preference towards premium spirits, craft beer, and functional beverages, which favor glass for its inertness and premium image, stimulates volume demand.
- Circular Economy Policies:Government initiatives, such as the EU's proposed Packaging and Packaging Waste Regulation, mandate higher recycled content and recyclability, creating a strong pull for cullet and glass packaging.
- Food Processing Expansion:Growth in the food processing industry in economies like India and Brazil, particularly for products like jams, pickles, and sauces, expands the addressable market for wide-mouth jars.
Market Restraints
- Energy Cost Volatility:The manufacturing process is highly dependent on natural gas for melting furnaces, making producers' cost structures extremely vulnerable to fluctuations in global energy markets.
- Competition from PET:Polyethylene terephthalate (PET) and other rigid plastics present a persistent lower-cost and lightweight alternative, particularly in the non-alcoholic beverage and personal care segments.
- High Logistics Costs:The weight and fragility of glass containers compared to alternatives result in higher transportation and handling costs, limiting practical shipping distances from production sites.
Strategic Opportunities
- Pharmaceutical Packaging Growth:The expansion of biologic drugs and vaccines creates demand for high-value, specialized borosilicate glass vials and syringes that meet stringent regulatory standards from bodies like the FDA and EMA.
- Digital Printing Technology:Advances in direct-to-glass digital printing offer opportunities for late-stage customization, enabling brands to execute short-run promotions and personalized packaging without traditional labels.
- Smart Packaging Integration:Embedding QR codes or NFC tags into glass containers opens new avenues for brand engagement, supply chain traceability, and consumer interaction, particularly for premium food and wine products.
Industry Challenges
- Cullet Supply Inconsistency:Securing a consistent supply of high-quality, color-sorted recycled cullet remains a significant operational hurdle, limiting the ability to meet high recycled-content targets without process adjustments.
- Capital-Intensive Furnace Relines:The significant capital expenditure and production downtime required for periodic furnace rebuilds and technology upgrades challenges the financial planning for small and mid-sized producers.
- Workforce Skill Gaps:A shortage of technicians and engineers with expertise in modern, automated glass-forming processes and sensor-based quality control systems hinders productivity improvements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Container Glass Market |
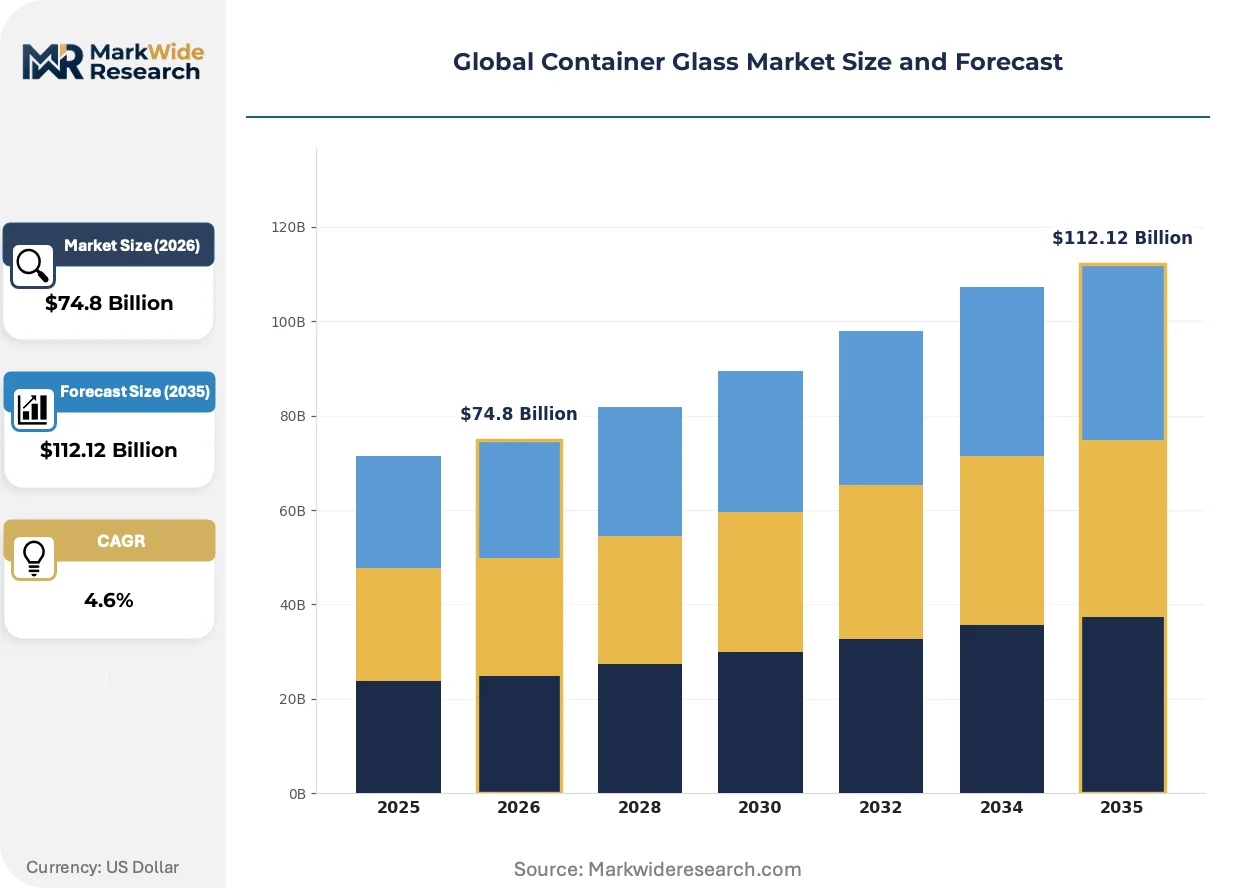
| Market Size in 2026 | $74.8 Billion |
| Market Size in 2035 | $112.12 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottle, Jar, Vial, Ampoule, Tube Application: Beverages, Pharmaceuticals, Cosmetics, Food Packaging, Chemicals End User: Breweries, Drug Manufacturers, Personal Care Brands, Food Processors, Chemical Producers Distribution Channel: Direct Sales, Distributors, Online Retailers, Exporters, Wholesalers |
| Companies Covered | Verallia, Gerresheimer AG, Ardagh Group SA, Stoelzle Glass Group, Bormioli Rocco, Owens-Illinois Inc, Vitro, Vetropack Group, Vidrala SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Container Glass Market Strategic Shifts & Innovations
The industrialization of sustainability is the core theme, as manufacturers embed environmental considerations directly into production technology and material science. This shift is a direct response to regulatory pressures and brand owner demands for packaging with a verifiably lower carbon footprint.
All-electric and hybrid furnace technology provides a pathway to decarbonize the energy-intensive melting process. Adoption is accelerating among European producers navigating the EU Emissions Trading System, who see it as a long-term hedge against carbon pricing. This fundamental change is electrifying the front-end of glass manufacturing, enabling the direct use of renewable power sources and reducing reliance on fossil fuels.
The US EPA's renewed focus on recycling infrastructure and domestic material circularity underpins new policy directions. These initiatives aim to improve the quality and availability of post-consumer recycled glass, or cullet, for manufacturers. The beverage segment is most impacted, as brand owners are increasingly setting public goals for recycled content in their bottles, creating a direct demand signal for improved collection systems.
A distinct behavioral change is the move by large food and beverage conglomerates toward strategic supplier consolidation. Instead of sourcing from numerous regional players, procurement teams are forming deeper partnerships with a few global glass manufacturers capable of ensuring supply chain resilience and consistent quality across continents. This trend is most evident in the global spirits and wine categories, favoring suppliers with a multi-national manufacturing footprint.
Global Container Glass Market Segmentation
The container glass market exhibits diverse segmentation, reflecting the varied requirements of end-use industries and manufacturing processes. Understanding these distinct segments is crucial for manufacturers to tailor product offerings, optimize production capabilities, and navigate competitive landscapes effectively.
Product Type:
The availability of specialized manufacturing lines dictates the supply structure for different container glass product types.
- Bottle:Bottles are typically formed using the blow-and-blow process, creating narrow-neck containers for liquids. Demand concentrates in the alcoholic and non-alcoholic beverage sectors, driven by consumer preference for glass's inertness and premium aesthetic.
- Jar:Jars are produced via the press-and-blow method, resulting in wide-mouth containers suitable for solid or semi-solid products. The food processing industry, particularly for jams, pickles, and sauces in India and Brazil, fuels significant volume demand for glass jars.
- Vial:These small, cylindrical containers, often made from borosilicate glass, serve critical containment needs for pharmaceutical liquids.
- Ampoule:Hermetically sealed glass capsules, ampoules provide sterile, single-dose packaging primarily for injectable drugs and vaccines.
- Tube:Glass tubes find application in laboratory settings and for small-volume cosmetic samples, valued for their chemical resistance.
Today's leader: Bottle. Tomorrow's challenger: Vial.
Application:
The functional requirements of different applications heavily influence glass container design and material specifications.
- Beverages:Glass in beverages provides an inert barrier, preserving flavor integrity without leaching chemicals. Premium spirits and craft beer segments globally increasingly choose glass for its perceived quality and brand differentiation.
- Pharmaceuticals:High-purity borosilicate glass is essential for pharmaceutical packaging, ensuring drug stability and patient safety. The expansion of biologic drugs and vaccines globally drives demand for specialized, regulatory-compliant glass vials and ampoules.
- Cosmetics:Glass containers elevate brand perception for perfumes, lotions, and creams, appealing to discerning consumers.
- Food Packaging:Jars and bottles secure various food items like sauces and baby food, valued for barrier properties and recyclability.
- Chemicals:Specialized glass containers store corrosive or sensitive chemical compounds, leveraging glass's chemical inertness.
The beverage sector represents the largest volume segment, while pharmaceutical applications command premium pricing.
End User:
End-user procurement strategies shape demand for specific container glass attributes and supply chain capabilities.
- Breweries:Breweries require robust, often amber-colored glass bottles to protect beverages from UV light and maintain carbonation. The global craft beer movement and brand differentiation strategies in countries like Germany and the US sustain demand for unique glass bottle designs.
- Drug Manufacturers:These manufacturers demand ultra-clean, sterile, and chemically resistant glass containers for sensitive pharmaceutical formulations. Stringent regulatory bodies like the FDA and EMA dictate material and quality standards, driving demand for specialized glass suppliers.
- Personal Care Brands:These brands leverage glass for its premium aesthetic and recyclability, enhancing product perception for cosmetics.
- Food Processors:Food processors rely on glass jars and bottles for product preservation, safety, and consumer appeal across diverse food categories.
- Chemical Producers:Chemical producers utilize chemically resistant glass containers for safe storage and transport of various industrial and laboratory chemicals.
Drug manufacturers prioritize quality and compliance, while breweries emphasize brand differentiation and supply chain reliability.
Distribution Channel:
The chosen distribution channel reflects the scale of operations and the geographic reach required by container glass buyers.
- Direct Sales:Large-volume buyers, particularly multinational beverage and pharmaceutical companies, engage directly with glass manufacturers. This channel ensures supply chain security, consistent quality, and often allows for custom container designs and long-term contracts.
- Distributors:Distributors serve as intermediaries, providing regional inventory and smaller order quantities to diverse customers. Small and medium-sized enterprises in regions like Europe and North America often rely on distributors for flexible sourcing and logistics support.
- Online Retailers:Emerging for niche and personalized glass products, this channel facilitates direct-to-consumer sales for smaller brands.
- Exporters:Exporters facilitate the cross-border movement of glass containers, supporting global supply chains for various industries.
- Wholesalers:Wholesalers aggregate products for resale to retailers or smaller businesses, common for standard glass container formats.
Direct sales dominate for high-volume, custom orders, while distributors cater to fragmented demand across smaller clients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European container glass manufacturing base, alongside high-growth economies in Asia, collectively shapes global supply and demand dynamics. Significant investments in energy-efficient furnace technology are occurring in established markets. Meanwhile, expanding food processing and beverage industries in emerging regions drive new capacity requirements.
United States
Demand for premium spirits and craft beverages consistently drives container glass volumes across the United States. US EPA initiatives focus on improving recycling infrastructure and the availability of high-quality cullet. Major glass plants in states like Pennsylvania and Ohio concentrate production for diverse end-use markets.
Germany
Strong consumer preference for premium beer and wine sustains demand for glass bottles in Germany. The EU's Packaging and Packaging Waste Regulation mandates higher recycled content for glass packaging. The Rhine-Ruhr region hosts significant glass manufacturing facilities, integrating advanced electric furnace technologies.
China
The expanding food and beverage processing sector fuels substantial demand for glass jars and bottles in China. China's MEE enforces stringent emissions standards, influencing furnace technology investments. Industrial parks in Shandong and Guangdong provinces feature large-scale glass production for domestic and export markets.
India
Rapid growth in the food processing industry, particularly for pickles and sauces, expands the addressable market for glass jars in India. The Food Safety and Standards Authority of India (FSSAI) regulates food-contact materials for glass containers. Manufacturing clusters around Mumbai and Delhi cater to burgeoning consumer packaged goods brands.
Brazil
Beverage consumption, including alcoholic drinks and juices, drives consistent demand for glass packaging across Brazil. ANVISA sets quality and safety standards for pharmaceutical and food-contact glass. The São Paulo industrial belt is a key hub for glass production, serving South American markets.
Global Container Glass Market Key Industry Players
Global majors compete with regional champions across manufacturing footprint and specialized product offerings within the container glass market. The industry exhibits consolidation at the top tier, with a more fragmented landscape among regional and niche players. Strategic archetypes include global scale providers, diversified packaging specialists, and high-value pharmaceutical glass manufacturers. Dominant competitive moves include geographic expansion into high-growth economies and technology innovation in lightweighting and decarbonization.
Within the global container glass market, large-scale manufacturers like Owens-Illinois Inc. exemplify extensive manufacturing footprints, serving multinational beverage clients. Ardagh Group SA occupies a position as a diversified packaging provider, offering both glass and metal solutions to food and beverage customers. Gerresheimer AG anchors the high-value pharmaceutical glass segment with its specialized focus on vials and ampoules.
| Leading Market Players |
|---|
| Verallia |
| Gerresheimer AG |
| Ardagh Group SA |
| Stoelzle Glass Group |
| Bormioli Rocco |
| Owens-Illinois Inc |
| Vitro |
| Vetropack Group |
| Vidrala SA |
| Others |
Cost & Logistics Intelligence
Volatile energy costs, particularly for natural gas, directly influence container glass production expenses, which then flow through to contract-based pricing agreements with large beverage and pharmaceutical clients.
Pricing Analysis
Input cost pass-through mechanisms are fundamental to pricing in the container glass market. Contract-based long-term offtake agreements dominate, especially for high-volume beverage and pharmaceutical customers. Price differentiation stems from customization levels for unique bottle designs and certification levels required for drug manufacturers. Pricing softness reflects persistent competition from alternative packaging materials like PET. Small and medium-sized beverage brands exhibit higher price sensitivity compared to large pharmaceutical companies.
Supply Chain Analysis
EU's Packaging and Packaging Waste Regulation mandates for higher recycled content are reshaping sourcing strategies for cullet. Geographic supply concentrations for raw materials include silica sand from countries like the United States and China, alongside soda ash from Turkey and the United States. The supply chain relies heavily on consistent energy supplies, making it vulnerable to commodity price volatility. Distribution runs through a dual model of direct sales to large multinational clients and distributors serving fragmented demand from smaller customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the EU's proposed Packaging and Packaging Waste Regulation directly stimulating demand for glass and recycled content mandates.
For Market Incumbents: Deploy advanced furnace technology to mitigate energy cost volatility and reduce carbon emissions. Consolidate manufacturing footprints in high-growth economies like India to serve expanding food and beverage processing industries. Defend market share against PET alternatives by emphasizing glass's premium image and inertness. Invest in R&D for lightweighting innovations to reduce logistics costs.
For New Entrants and Emerging Players: Small and mid-sized personal care brands represent an underserved buyer archetype seeking flexible, customized packaging solutions. Target regional craft beverage producers in North America and Europe, offering digital printing capabilities for late-stage customization. Focus on specialized borosilicate glass vials for niche pharmaceutical applications, leveraging stringent regulatory requirements as a barrier to entry. A direct-to-brand go-to-market angle can bypass traditional distributors.
For Investors and Strategic Acquirers: Consolidation pressure builds where high capital expenditure for furnace relines challenges smaller producers. Long-term viability over the next decade favors entities with diversified manufacturing capabilities and strong sustainability credentials. Target mid-sized, specialized glass manufacturers with expertise in high-value segments like pharmaceutical packaging or advanced digital printing. The signal to watch is the adoption rate of all-electric furnace technology, indicating decarbonization commitment.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in All-Electric Furnace Technology | Reduces reliance on fossil fuels, aligning with EU Emissions Trading System targets. |
| Expand Cullet Processing Capabilities | Secures consistent supply of recycled glass to meet brand owner recycled content goals. |
| Acquire Digital Printing Specialists | Enables late-stage customization and personalized packaging for premium brands. |
| Form Strategic Partnerships with Biopharma | Addresses growing demand for specialized, regulatory-compliant borosilicate glass vials. |
| Optimize Logistics Networks | Mitigates high transportation costs associated with the weight and fragility of glass containers. |
Research Approach
Direct dialogue with glass manufacturers, procurement leads at beverage and pharmaceutical companies, and recycling infrastructure operators provided qualitative grounding. This primary research was validated against secondary sources including trade association reports, regulatory filings with the US EPA and China's MEE, and financial disclosures. A robust triangulation approach combined bottom-up market sizing with top-down validation.
Market volume and value outputs were generated using a proprietary analytical framework across the analysis window. Segmentation dimensions modeled included product type, application, end-user industry, and distribution channel, alongside regional adoption patterns. Compound Annual Growth Rates were derived from historical data trends and projected future demand drivers, incorporating inputs like beverage consumption growth and pharmaceutical R&D pipelines.
Underlying measurement precision varies by segment; the beverage and pharmaceutical sectors carry tighter precision than others due to established reporting. Forecasts reflect assumptions regarding energy costs and regulatory enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Netherlands Container Glass Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
Cosmetic and Perfume Glass Bottle Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Italy Container Glass Market
Glass Packaging
Thin Wall Glass Container Market
Glass Packaging
Asia - Pacific Glass Bottles and Containers Market
Glass Packaging
China Glass Container Packaging Market
Glass Packaging
United Kingdom (UK) Glass Bottles and Containers Market
Glass Packaging
Germany Glass Packaging Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Egypt Glass Packaging Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
Nigeria Container Glass Market
Glass Packaging
Mexico Glass Packaging Market