
 Beverage Cups Market | 2026-2036
Beverage Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Cups Market Outlook
The EU Single-Use Plastics Directive is restructuring material procurement across European foodservice channels, compelling converters to certify compostable fiber formulations. Dart Container leverages its captive resin and forming operations to sustain cost leadership in insulated foam alternatives. Huhtamaki anchors its European position through molded-fiber capacity investments aligned with the EU Green Deal packaging targets. Georgia-Pacific competes aggressively in the North American paper cup segment, controlling integrated pulp supply from Southeastern US mills.
Beverage cups are cylindrical containers engineered from paperboard laminates, extruded polystyrene, polypropylene, or borosilicate glass, designed to maintain thermal stability and prevent liquid leakage across temperatures from near-freezing to boiling. Their primary commercial purpose is to enable safe, portable consumption of hot and cold drinks in away-from-home settings. Paper cups currently occupy the largest value share due to brand-owner sustainability commitments, though reusable formats are gaining traction as quick-service operators test deposit-return schemes in European cities. Plastic cups still dominate large-event and stadium channels where durability and cost thresholds favor polypropylene over fiber. Foam cups retain residual demand in US institutional settings but face accelerating displacement from municipal bans and corporate procurement exclusions.
The US FDA maintains material contact standards for food-service polymers, while the EPA tracks landfill diversion rates that indirectly pressure municipal cup procurement. REACH and the EU Packaging and Packaging Waste Regulation impose substance restrictions and extended producer obligations across European supply chains. China's SAMR enforces GB standards for food-contact plastics and paper, with provincial environmental bureaus adding local single-use restrictions in Shanghai and Beijing. Stakeholders must monitor how divergent national timelines for plastic phase-outs reshape cross-border manufacturing footprints and raw-material hedging strategies.
Market Dynamics
The EU Single-Use Plastics Directive is restructuring material procurement across European foodservice channels, compelling converters to certify compostable fiber formulations and redirecting billions of units away from conventional polymers.
Growth Catalysts
- Quick-service cold-drink expansion:US fast-food operators are scaling iced-beverage programs, driving cup volume through expanded fountain and specialty-drink menus.
- REACH substance restrictions:European chemical regulations are accelerating substitution of perfluorinated coatings in paper cups, opening demand for barrier-technology innovation.
- Urban café chain density:Coffee shop proliferation in Chinese and Indian metropolitan areas is concentrating organized demand for branded disposable formats.
Market Restraints
- Pulp cost volatility:Northern European and North American softwood fiber markets expose converters to input price swings that compress margin on paper cup lines.
- Resin supply concentration:Global polystyrene production clusters in Gulf Coast petrochemical corridors create geographic vulnerability for foam cup manufacturers.
- Performance ceiling of molded fiber:Current aqueous-barrier formulations face technical limitations in holding carbonated beverages beyond 30 minutes without structural degradation.
Strategic Opportunities
- Deposit-return infrastructure:Scandinavian and German municipalities are piloting reusable cup schemes that create service-revenue models beyond unit sales.
- Digital printing convergence:Integration of inkjet decoration with inline forming equipment enables mass-customization for regional beverage promotions.
- Stadium and event channels:Large-venue operators are seeking durable polypropylene alternatives to fiber for multi-hour use cycles in outdoor conditions.
Industry Challenges
- Compostable certification timelines:TÜV and BPI validation processes for new fiber-barrier formulations extend 18-24 months, delaying commercialization.
- Legacy equipment retrofit costs:Converters face capex burdens adapting forming lines originally built for foam to handle thinner-gauge fiber substrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Cups Market |
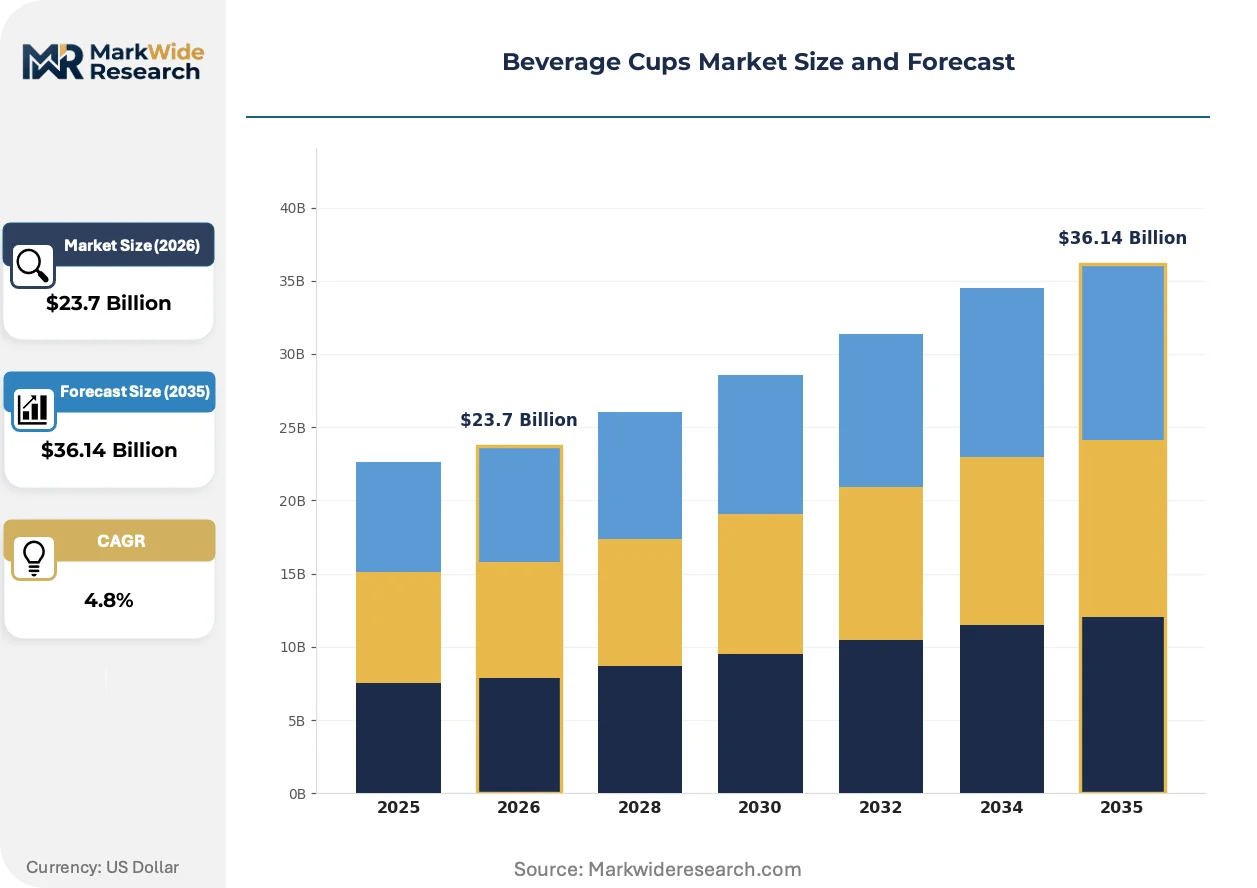
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Cups, Plastic Cups, Foam Cups, Glass Cups Usage Type: Disposable, Reusable, Single-Use, Multi-Use Capacity: Small, Medium, Large, Extra Large End User: Restaurants, Cafes, Events, Retail |
| Companies Covered | Dart Container, Huhtamaki, Georgia-Pacific, Berry Global, Pactiv Evergreen, Graphic Packaging International, Genpak, Solo Cup, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Cups Market Strategic Shifts
Material science breakthroughs and regulatory phase-outs are converging to reshape competitive positioning in beverage cup manufacturing, with automation and certification emerging as decisive capability differentiators.
Water-based barrier coatings are automating the transition from polyethylene-lined paper to repulpable single-wall constructions. Quick-service operators in the United Kingdom and Netherlands are qualifying these formats for hot-fill applications at accelerated pace. The technology is automating line-speed parity between sustainable and conventional substrates, removing throughput penalties that previously constrained fiber adoption.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling reformulation of oil-resistant paper coatings across European supply chains. Converter R&D spending has pivoted toward silicone and clay-based alternatives that maintain grease-barrier performance. The regulation is hitting ready-to-eat food pairing applications hardest, where fiber cups must resist hot-oil penetration from fried items.
Direct-to-store distributor consolidation is compressing the number of stocking decision-makers controlling cup procurement for independent foodservice accounts. Broadline distributors are replacing fragmented local supply relationships with private-label cup programs under national contracts. This pattern is most pronounced in the US Southeast, where regional distributor mergers have concentrated buyer power across quick-service and institutional channels.
Beverage Cups Market Segmentation
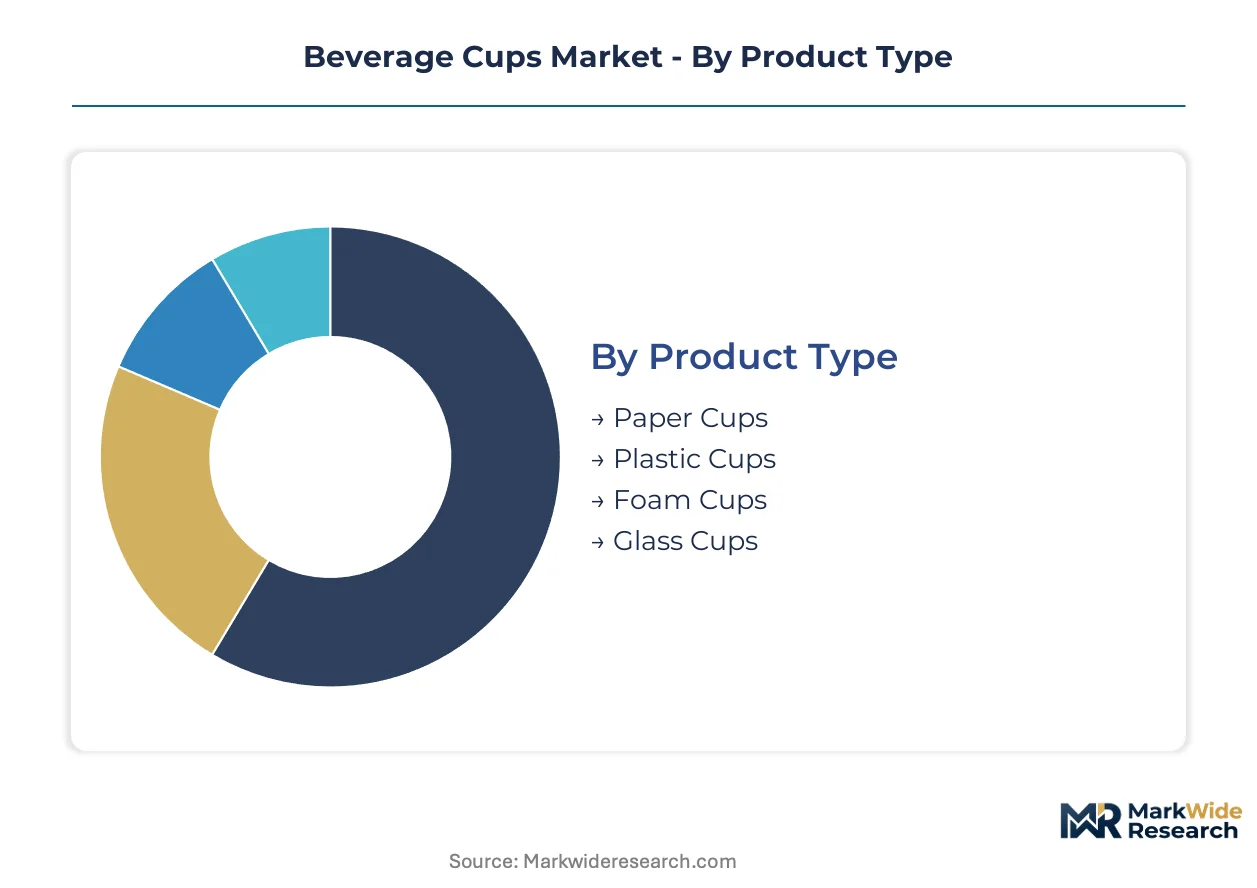
Segmentation in beverage cups tracks how thermal performance requirements, disposal infrastructure, and branding economics split demand across material formats. Buyers select substrates based on temperature range, single-use mandates, and cost-per-impression for printed graphics.
Product Type:
Converters differentiate buyers in this category by their tolerance for unit cost versus sustainability certification and thermal insulation needs.
- Paper Cups:Multi-layer paperboard constructions with PE or aqueous barrier coatings dominate quick-service hot-drink applications. European quick-service operators are accelerating qualification of repulpable barrier formulations to meet EU Single-Use Plastics Directive timelines.
- Plastic Cups:Injection-molded polypropylene and PET formats deliver clarity and durability for iced beverages and carbonated drinks. Stadium and outdoor event channels in the United States favor these formats for multi-hour use cycles where fiber degrades.
- Foam Cups:Extruded polystyrene provides superior thermal insulation at lowest unit cost. Municipal bans across California, New York, and Oregon are compressing addressable market for this substrate.
- Glass Cups:Borosilicate and soda-lime constructions serve sit-down café and dine-in restaurant segments. Deposit-return schemes in Scandinavian cities are piloting standardized glass formats for reusable loop systems.
Volume sits with paper formats; growth tilts toward plastic alternatives for cold-drink expansion.
Usage Type:
Regulatory phase-outs and infrastructure investments are re-sorting buyers by their access to composting facilities, washing stations, or landfill diversion programs.
- Disposable:Single-serve formats designed for immediate discard after one use. Quick-service restaurant chains in India and China are scaling disposable cup procurement to match café chain density growth in metropolitan areas.
- Reusable:Durable constructions engineered for hundreds of wash cycles with standardized dimensions for interoperability. German and Swedish municipalities are mandating reusable cup availability at large events through deposit-return infrastructure investments.
- Single-Use:Purpose-built for one consumption occasion without washing logistics. REACH Annex XVII restrictions on perfluorinated coatings are forcing reformulation of oil-resistant single-use paper formats across European supply chains.
- Multi-Use:Hybrid designs allowing limited reuse before disposal, common in office and institutional settings. Corporate procurement policies in the United States are excluding multi-use foam formats from approved vendor lists.
Disposable formats command current volume; reusable systems are climbing the fastest as regulatory mandates expand.
Capacity:
Portion economics and beverage category mix determine buyer selection across size tiers, with fountain drink programs and specialty coffee driving divergence.
- Small:Typically 8-12 ounce formats for espresso-based drinks and children's portions. Italian and Spanish café cultures concentrate demand for small-capacity paper cups in premium hot-drink applications.
- Medium:16-20 ounce standard for drip coffee and fountain beverages. US quick-service cold-drink expansion is pushing medium-format plastic cup volume through expanded specialty beverage menus.
- Large:24-32 ounce constructions for iced beverages and shared servings. Convenience store chains in Japan and South Korea favor large-format plastic cups for frozen drink programs.
- Extra Large:40+ ounce formats for theater, stadium, and family-size fountain applications. Sports venue operators in Texas and Florida are qualifying extra-large polypropylene cups for extended outdoor use.
Medium formats dominate unit economics; extra-large capacities are gaining share fastest through large-venue channel expansion.
End User:
Operational scale, branding requirements, and disposal logistics separate procurement patterns across institutional buyer types.
- Restaurants:Full-service and quick-service operators with high-volume, consistent demand for branded disposable formats. Chains in the United Kingdom are consolidating procurement under broadline distributor private-label programs.
- Cafes:Coffee-focused retailers emphasizing premium aesthetics and sustainability credentials. Urban café density in Shanghai and Beijing is concentrating organized demand for certified compostable fiber cups.
- Events:Temporary venues requiring durable, low-cost formats for peak-load consumption. Outdoor music festivals in Germany are piloting reusable cup deposit schemes to eliminate single-use waste streams.
- Retail:Grocery and convenience stores selling beverage cups as standalone products or fountain accompaniments. Convenience store operators in the US Southeast are shifting from foam to paper formats under corporate sustainability mandates.
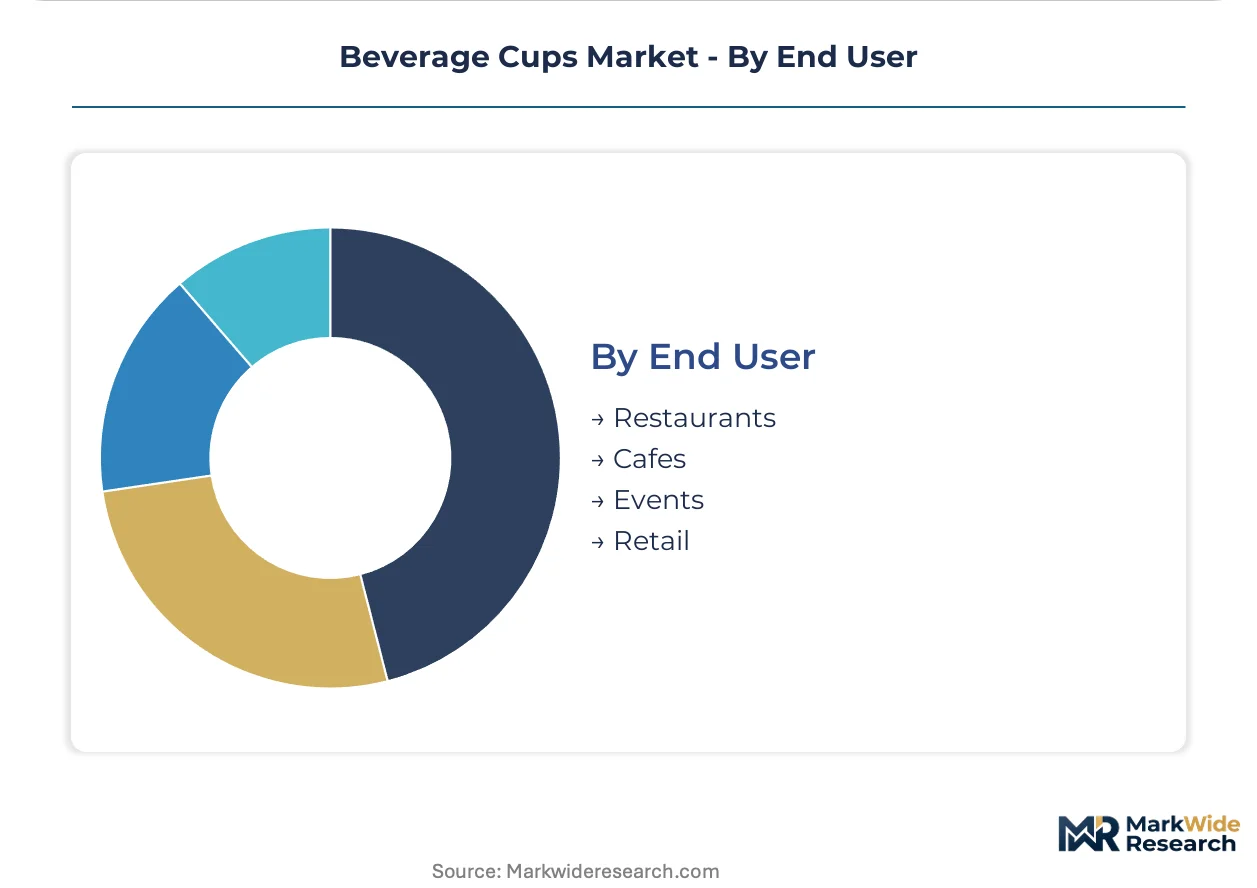
Restaurant channels anchor current procurement volume; café segments show the steepest expansion trajectory through urban retail density growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's café corridor concentrates Asia-Pacific cup demand through organized retail expansion and cold-drink program scaling by international chains.
United States
Quick-service cold-drink expansion drives cup volume through expanded fountain menus. The FDA maintains material contact standards for food-service polymers while the EPA tracks landfill diversion rates. Texas and Florida sports venue operators qualify extra-large polypropylene cups for extended outdoor use cycles.
Germany
Scandinavian-style deposit-return infrastructure creates service-revenue models beyond unit sales. REACH Annex XVII restrictions on perfluorinated coatings compel barrier-technology reformulation. Berlin and Hamburg municipalities mandate reusable cup availability at large events through dedicated infrastructure investments.
China
Urban café chain density concentrates organized demand for branded disposable formats. SAMR enforces GB standards for food-contact plastics and paper with provincial environmental bureaus adding local single-use restrictions. Shanghai and Beijing municipal governments impose additional single-use plastic limitations on foodservice packaging.
India
Metropolitan café chain expansion drives procurement scaling for branded disposable formats. FSSAI regulates food-contact materials with state-level environmental authorities implementing plastic phase-out schedules. Mumbai and Delhi organized retail corridors anchor demand concentration for quick-service beverage packaging.
United Kingdom
Broadline distributor consolidation compresses stocking decision-makers controlling cup procurement for independent foodservice accounts. The UK implements EU-aligned packaging waste regulations with extended producer responsibility schemes. London and Southeast England quick-service operators accelerate qualification of repulpable barrier formulations.
Beverage Cups Market Competitive Environment
Premium-margin players sit above commodity-margin players across material certification tiers and integrated supply chain control. The vendor base spans vertically integrated pulp-to-cup converters, specialized barrier-coating technology licensors, and regional forming equipment operators. Three archetypes dominate: captive resin producers leveraging backward integration into petrochemical feedstocks, fiber specialists investing in molded-fiber capacity aligned with regulatory phase-outs, and diversified packaging conglomerates cross-selling cup formats through broadline distribution partnerships. Competitive moves concentrate on M&A for barrier-technology access and geographic capacity expansion targeting regulatory-driven material substitution windows.
Among North American integrated packaging groups, Dart Container, Georgia-Pacific, and Pactiv Evergreen exemplify distinct strategic positioning archetypes. Dart Container occupies a position representing captive resin and forming operations sustaining cost leadership in insulated alternatives. Georgia-Pacific anchors the paper cup segment through integrated pulp supply control from Southeastern US mill assets. Pactiv Evergreen sits within the diversified foodservice packaging tier with cross-category manufacturing breadth enabling distributor relationship leverage.
| Leading Market Players |
|---|
| Dart Container |
| Huhtamaki |
| Georgia-Pacific |
| Berry Global |
| Pactiv Evergreen |
| Graphic Packaging International |
| Genpak |
| Solo Cup |
| WestRock Company |
| Others |
Value Chain & Pricing Dynamics
Softwood pulp costs transmit from Northern European and North American timber markets through paper cup converters to quick-service operators, with fiber price volatility compressing margins on standard-grade formats while certified compostable lines command premium positioning.
Pricing Analysis
Throughput-linked pricing for high-volume quick-service contracts anchors value capture in this market. Three-tier pricing structure across premium, standard, and economy levels separates certified compostable fiber cups with BPI validation from conventional PE-lined formats and residual foam alternatives. Price differentiation hinges on certification grade and volume scale, with national chain procurement leveraging multi-year offtake commitments. Cost compression in economy foam tiers is intensifying because municipal bans are shrinking addressable demand. Independent foodservice accounts show highest price sensitivity; stadium and event operators demonstrate lowest sensitivity due to durability requirements.
Supply Chain Analysis
Compostable certification timelines from TÜV and BPI gate supplier qualification and extend commercialization cycles. Manufacturing concentrates in the United States, China, and Finland, with fiber sourcing anchored in Southeastern US mill assets and Nordic softwood corridors. Raw material inputs draw from bleached kraft pulp, polystyrene resin from Gulf Coast petrochemical clusters, and aqueous barrier coating formulations. Single-source vulnerability runs through concentrated polystyrene production corridors exposed to hurricane disruption. Distribution runs through broadline foodservice distributors consolidating regional relationships under national private-label programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around fiber-based formats as EU regulatory phase-outs and US municipal bans force foam-dependent converters into distressed repositioning or exit.
For Market Incumbents: Acquire aqueous barrier coating technology specialists to secure qualification pipelines for compostable fiber formats ahead of REACH Annex XVII enforcement. Integrate molded-fiber capacity in Poland or Germany to serve EU Single-Use Plastics Directive demand windows. Channel control through exclusive broadline distributor partnerships defends share against private-label substitution. For New Entrants and Emerging Players: Digital printing convergence with inline forming equipment offers technology-first entry into regional beverage promotion markets underserved by national converters. White-space targets include Scandinavian reusable cup deposit-return infrastructure services and Indian metropolitan café chain branded format procurement. Direct-to-store distributor relationships in the US Southeast provide the most penetrable go-to-market angle against consolidated national programs. For Investors and Strategic Acquirers: Distressed-cycle entries favor foam-dependent regional converters in California and New York facing municipal ban compression but holding captive customer relationships. Long-term viability centers on fiber-format transition execution capability rather than legacy asset value. Watch TÜV certification backlog clearance rates as the inflection indicator for compostable supply capacity absorption.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Technology Acquisition | Secures aqueous coating IP needed for EU compostable certification timelines. |
| Molded-Fiber Capacity Expansion | Aligns production assets with EU Green Deal packaging targets and single-use plastic phase-outs. |
| Deposit-Return Infrastructure Partnership | Captures service revenue models beyond unit sales in German and Swedish municipal pilots. |
| Digital Printing Integration | Enables mass-customization for regional beverage promotions at line-speed parity. |
| Broadline Distributor Consolidation | Concentrates buyer power and compresses stocking decision-makers for independent accounts. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving cup converter plant managers, quick-service procurement directors, broadline distributor category buyers, and aqueous barrier coating R&D leads. FDA material contact standards, EPA landfill diversion tracking, REACH Annex XVII substance restrictions, and SAMR GB enforcement records provided regulatory boundary conditions. Bottom-up shipment data from forming equipment operators and top-down pulp consumption metrics triangulated volume estimates.
Reconciliation of production capacity databases against end-user procurement surveys generated volume and value outputs across the projection horizon. Segmentation dimensions modeled include material format, usage type, capacity tier, and end-user channel, with additional granularity on certification status for compostable fiber lines. CAGRs derived from trend extrapolation of regulatory-driven material substitution rates and quick-service cold-drink program expansion curves, incorporating pulp futures pricing and resin supply concentration risk factors.
Several conditions sit outside the modeled scope, including abrupt shifts in municipal ban enforcement timelines, breakthroughs in biodegradable polymer cost parity, and major hurricane disruptions to Gulf Coast resin production. Forecasts reflect assumptions about certification timeline stability and distributor consolidation pace. A model refresh is warranted upon material change in EU Packaging and Packaging Waste Regulation implementation schedules or TÜV/BPI validation throughput capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Middle East and Africa Soft Drinks Packaging Market
Beverage Packaging
Pop-Up Pourer Market
Beverage Packaging
Cup Filler Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
Heavy Wall Bottles Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Fruit Juice Packaging Market
Beverage Packaging
Twin Neck Bottles Market
Beverage Packaging
Vending Cups Market
Beverage Packaging
Pouring Spout Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Cold Beverage Cups Market
Beverage Packaging
Bottle Shippers Market
Beverage Packaging
French Square Bottle Market
Beverage Packaging
Disposable Tea Flask Market