
 North America Beverage Packaging Market | 2026-2036
North America Beverage Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Beverage Packaging Market Analytics
A capital-intensity divergence between blow-molding specialists and legacy glass manufacturers is rotating competitive dynamics across the North America Beverage Packaging Market. Amcor leverages its integrated resin-to-bottle operations to secure long-term supply contracts with carbonated soft drink bottlers. Ball Corporation dominates aluminum can production, sustaining capacity investments that anchor its position with craft breweries and energy drink brands.
North America Beverage Packaging encompasses the engineered containment, preservation, and distribution systems for liquid consumables, typically involving barrier-coated substrates, controlled atmosphere sealing, and fill-line compatibility specifications ranging from ambient to aseptic processing conditions. Plastic bottles lead volume throughput across the region, though aluminum cans capture expanding share as breweries and seltzer brands prioritize recyclability and shelf differentiation. Paperboard cartons remain concentrated in dairy and juice applications, where Tetra Packs sustain premium positioning through extended shelf-life performance.
The US FDA governs food-contact material safety, while the EPA administers extended producer responsibility frameworks that shape recycling infrastructure investments across the region. State-level bottle bill programs in California, New York, and Michigan create fragmented compliance obligations that packaging suppliers must navigate. Industry stakeholders should monitor how California's SB 54 implementation timeline reshapes material specifications and whether Ontario's Blue Box transition accelerates similar provincial mandates across Canada.
Market Dynamics
California's SB 54 implementation timeline is compressing material specifications across the North America Beverage Packaging Market, forcing converters to accelerate recycled content integration ahead of statutory deadlines.
Growth Catalysts
- State Bottle Deposit Expansion:New York and Michigan are tightening container recovery mandates, creating pull-through demand for rPET and aluminum formats that qualify for deposit-redemption streams.
- Functional Beverage Proliferation:Wellness-oriented brands are expanding packaging orders for barrier-coated bottles that preserve probiotic and adaptogenic ingredient stability through extended distribution cycles.
- Southeast Bottling Cluster Concentration:Georgia and Texas corridor facilities are scaling canning and blow-molding capacity to serve population-dense eastern seaboard markets with reduced freight radius.
Market Restraints
- Resin Price Volatility:Blow-molding specialists face margin compression from ethylene and propylene feedstock swings that track crude oil and natural gas liquid benchmarks.
- Aluminum Sheet Supply Concentration:Domestic can sheet production concentrates among three primary rolling mills, creating bottleneck risk for craft brewery and seltzer brand expansion plans.
- Mechanical Recycling Contamination:Multi-layer barrier films and full-body shrink sleeves degrade rPET bale quality, limiting closed-loop supply availability for food-contact applications.
Strategic Opportunities
- Canadian Provincial EPR Acceleration:Ontario's Blue Box transition to full producer responsibility creates template for Quebec and British Columbia mandates that favor domestic converter investment.
- Chemical Recycling Scale-Up:Pyrolysis and depolymerization partnerships between resin suppliers and packaging converters promise food-grade rPET volumes beyond mechanical processing limits.
- Aseptic Carton Regional Gap:Underpenetrated plant-based milk and functional juice categories in the US Mountain West present white space for Tetra Pak and SIG Combibloc format expansion.
Industry Challenges
- Hot-Runner Mold Engineering Talent Scarcity:Complex multi-cavity blow-mold tooling requires specialized technicians that command premium wages in the US Southeast manufacturing belt.
- Fill-Line Retrofit Coordination:Lightweighting initiatives and material transitions demand synchronized downtime with bottler operations, compressing implementation windows and raising project risk.
- Recycled Content Certification Lag:Third-party chain-of-custody verification for ocean-bound and post-consumer plastics creates procurement delays for brands targeting 2025 sustainability commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Beverage Packaging Market |
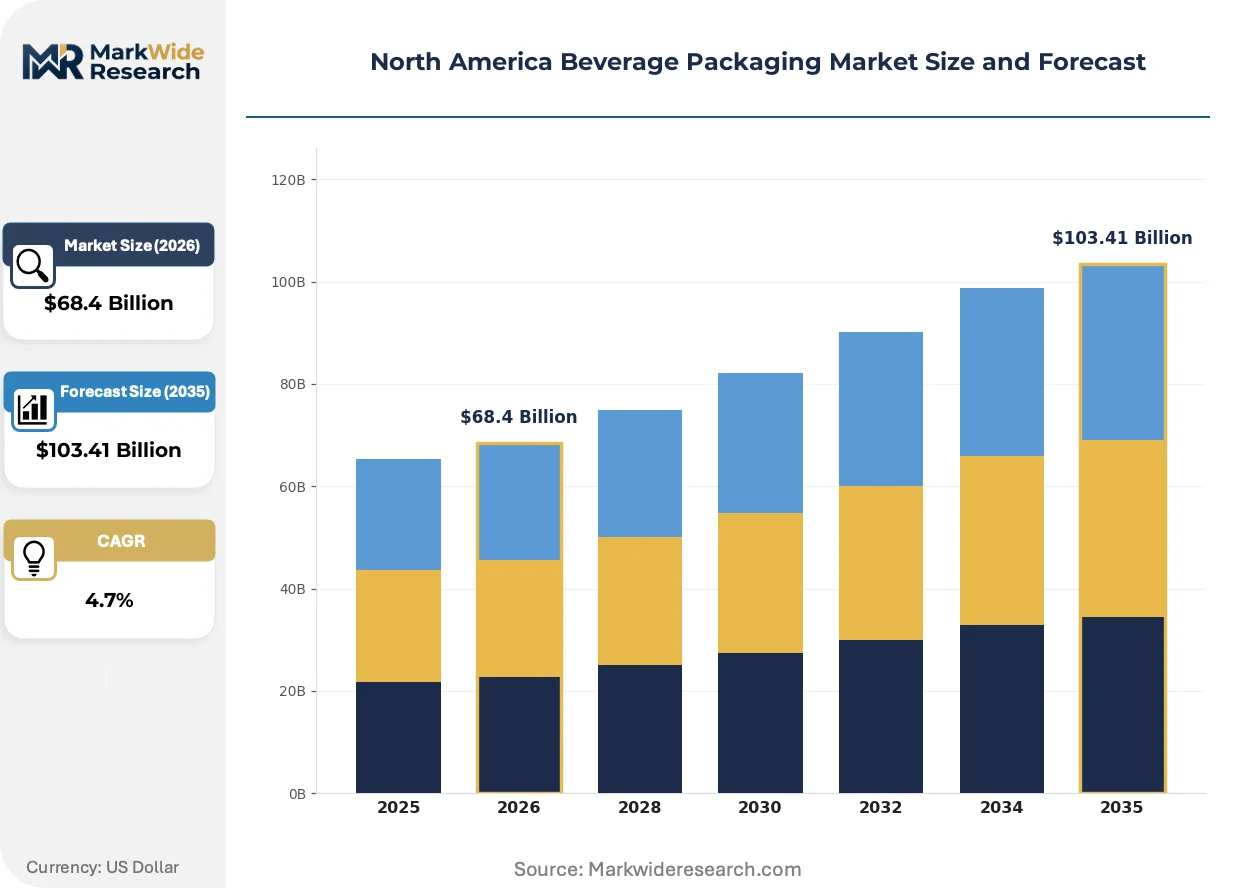
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Cans, Pouches, Tetra Packs Material: Plastic, Glass, Aluminum, Paperboard End User: Non-Alcoholic Beverages, Alcoholic Beverages, Functional Drinks, Soft Drinks Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Distributors |
| Companies Covered | Berry Global Group, Owens-Illinois, Amcor, WestRock Company, Mondi Group, Ball Corporation, Tetra Laval, Silgan Holdings, Crown Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Beverage Packaging Market Evolving Landscape
Material science breakthroughs and regulatory compliance architectures are restructuring competitive advantage across container formats, with sustainability credentials now functioning as technical specifications rather than marketing overlays.
Mono-material polyethylene terephthalate bottles with built-in oxygen scavenger additives are displacing multi-layer constructions in premium juice and ready-to-drink coffee segments. Mid-sized regional dairies and cold-brew brands are adopting these formats to maintain shelf stability without aluminum foil laminates that complicate mechanical recycling streams. The shift is compressing demand for EVOH and nylon barrier layers while elevating resin purity standards.
The US EPA's advancing extended producer responsibility frameworks are mandating post-consumer recycled minimums that vary by container type and state jurisdiction. California's SB 54 requires 25% recycled plastic in beverage bottles by 2025, with escalating thresholds through 2030, forcing converters to secure offtake agreements with mechanical and advanced recyclers ahead of compliance deadlines. Juice and dairy carton suppliers face parallel pressure as the state evaluates paperboard recovery rate benchmarks.
Direct-to-store distribution models are shortening order cycles and compressing batch size minimums for regional beverage brands. Craft breweries and functional drink startups are bypassing traditional distributor networks, placing smaller, more frequent packaging orders that favor digital printing and quick-changeover canning lines. This pattern is most visible in Colorado and Pacific Northwest markets where taproom-to-retail vertical integration concentrates brand ownership.
North America Beverage Packaging Market Segmentation
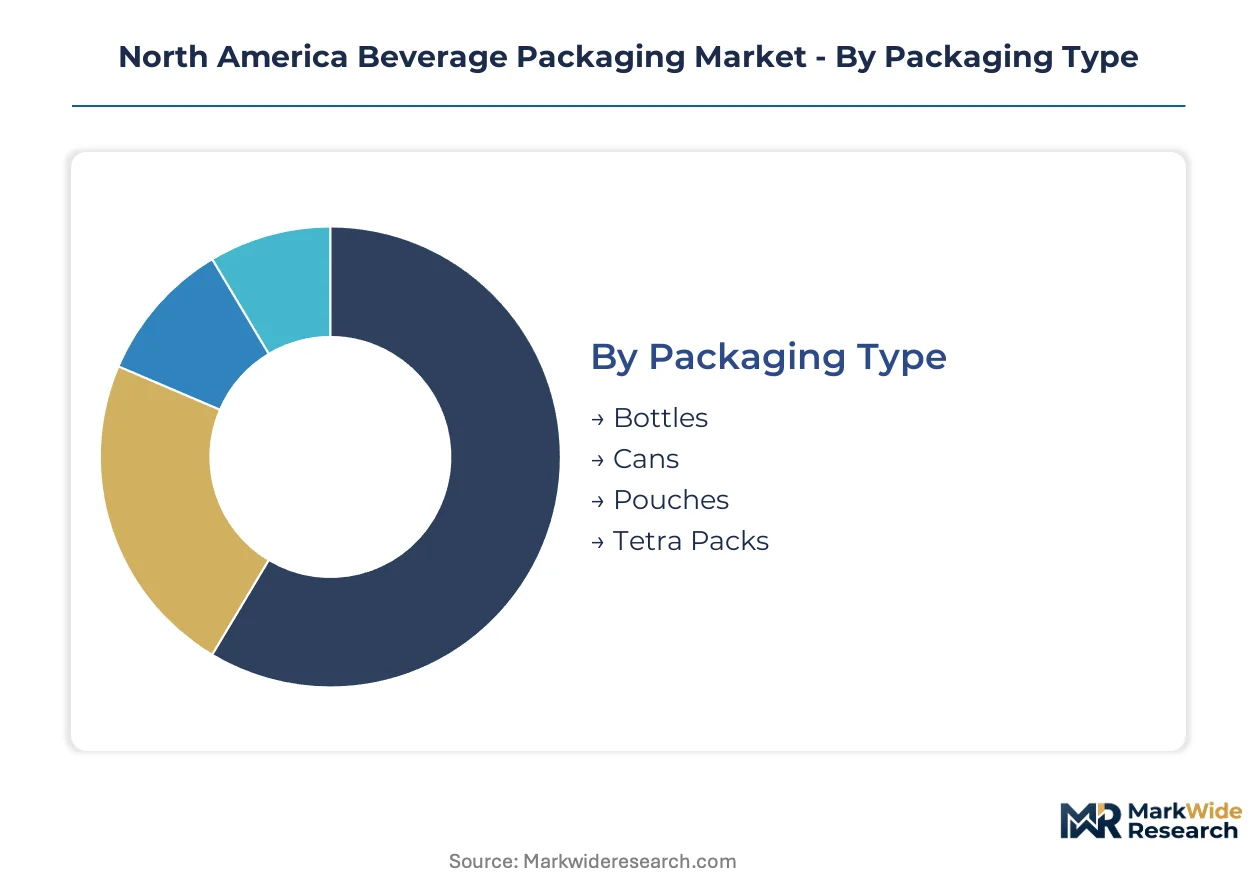
Packaging format selection in North America Beverage Packaging hinges on fill-line compatibility, shelf-life requirements, and state-level deposit law compliance. Material specifications increasingly differentiate between mechanical recycling eligibility and advanced recycling feedstock acceptance.
Packaging Type:
California's SB 54 mandates diverge by container format, with bottles facing recycled content minimums that cans already satisfy through existing aluminum recovery streams.
- Bottles:PET blow-molded constructions dominate carbonated soft drink and water applications, with oxygen scavenger additives displacing multi-layer barriers. Demand concentrates in the US Southeast bottling corridor where Georgia and Texas facilities serve eastern seaboard markets with compressed freight radius.
- Cans:Two-piece aluminum draw-and-wall-iron construction captures expanding share from craft breweries and hard seltzer brands prioritizing infinite recyclability claims. Supply concentrates among three domestic rolling mills, creating procurement bottlenecks for regional brand expansion.
- Pouches:Flexible laminated structures with fitment closures serve single-serve juice and children's beverage segments where portability outweighs recycling complexity.
- Tetra Packs:Aseptic paperboard cartons with aluminum foil barriers maintain premium positioning in extended shelf-life dairy and plant-based milk categories.
Established volume favors bottles; emerging adoption favors cans.
Material:
Cost tier stratification separates commodity resins from specialty substrates requiring dedicated recovery infrastructure.
- Plastic:PET and HDPE resins lead throughput, with rPET food-contact certification delays constraining brand sustainability timelines. Mechanical recycling contamination from full-body shrink sleeves degrades bale quality for closed-loop supply.
- Aluminum:Can sheet and bottle stock alloys command premium pricing against resin volatility, with domestic smelter capacity anchoring supply security for major beverage portfolios.
- Glass:Flint and amber soda-lime compositions retain share in premium beer and spirits segments where heritage aesthetics justify weight and fragility trade-offs.
- Paperboard:Liquid packaging board with polyethylene extrusion layers sustains dairy and juice carton demand despite limited curbside recovery rates outside deposit states.
Commodity resin volumes dominate; aluminum climbs fastest on recyclability credentials.
End User:
Application requirements dictate barrier specifications, with functional ingredients demanding oxygen and light protection beyond conventional beverage needs.
- Non-Alcoholic Beverages:Water, juice, and ready-to-drink coffee segments drive high-volume PET bottle demand with lightweighting targets compressing gram weights per container.
- Alcoholic Beverages:Beer and spirits packaging splits between aluminum cans for craft distribution and glass for premium positioning, with canning line investments accelerating in Mountain West taproom markets.
- Functional Drinks:Probiotic and adaptogenic formulations require barrier-coated bottles preserving ingredient stability through temperature-variable distribution cycles.
- Soft Drinks:Carbonated formulations maintain PET and aluminum parity, with fountain syrup-to-bottle ratios influencing converter contract structures.
Mainstream soft drinks anchor volume; functional drinks gain share fastest on wellness positioning.
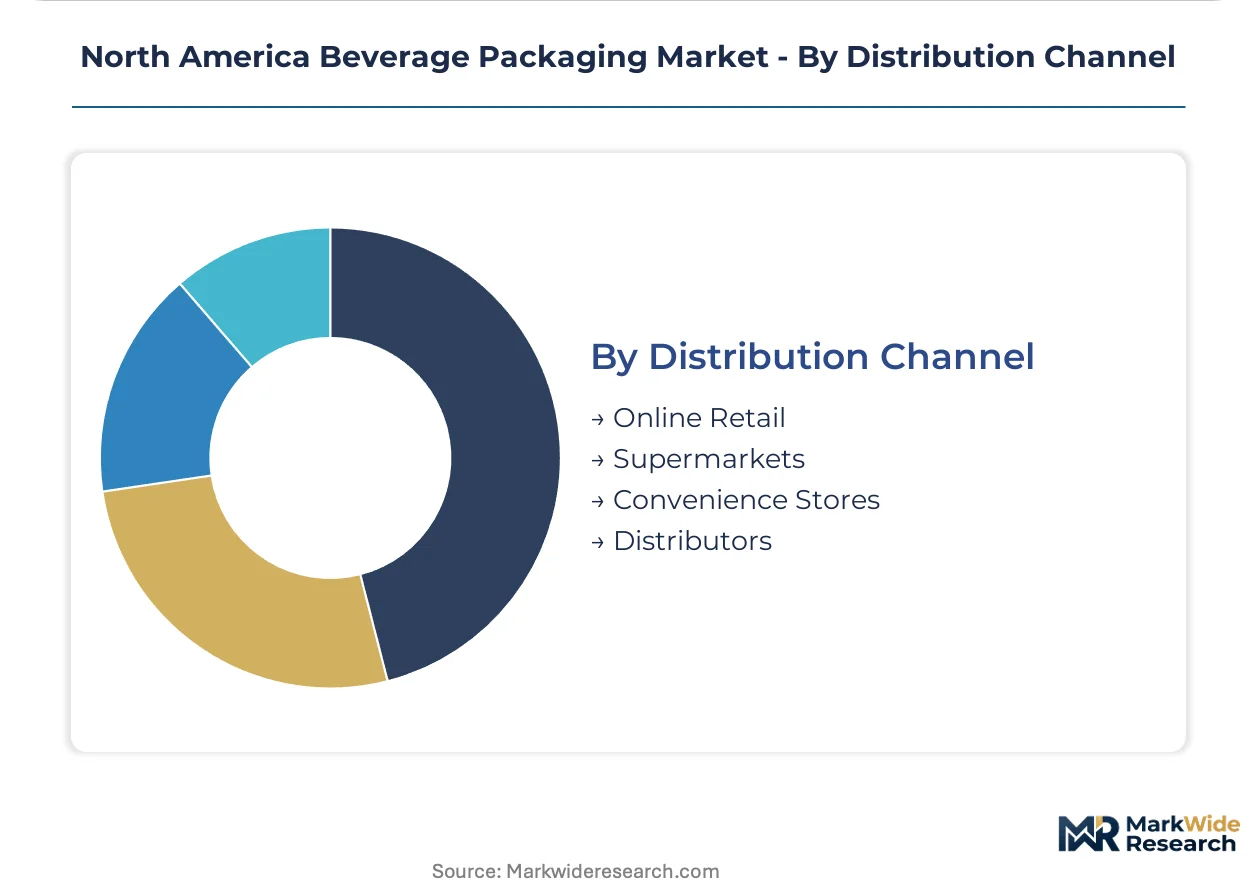
Distribution Channel:
Customer type fragmentation separates high-velocity retail from direct-to-store models compressing batch minimums.
- Online Retail:E-commerce beverage sales require corrugated shipper compatibility and damage-resistant primary packaging, with Amazon Frustration-Free certification influencing structural design.
- Supermarkets:Mass retail shelf sets drive standardized pallet configurations and retail-ready secondary packaging for efficient stocking.
- Convenience Stores:Cold vault single-serve demand favors 20-ounce PET contour bottles and slim 12-ounce cans with high-visibility graphics.
- Distributors:Traditional three-tier beverage distribution maintains bulk packaging formats for on-premise accounts and independent retailers.
Supermarket volume retains dominance; online retail expands most quickly on direct-to-consumer brand launches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward the US Southeast, where Georgia and Texas bottling clusters compress freight radius to eastern seaboard population corridors. Canadian converters face margin pressure from Ontario's Blue Box transition to full producer responsibility. Mexican border-state facilities capture cross-border canning demand from US craft brewery expansion.
United States
California's SB 54 mandates 25% recycled plastic content by 2025, with escalating thresholds through 2030. The US FDA governs food-contact material safety while state-level bottle deposit laws in New York and Michigan tighten recovery requirements. Georgia anchors the Southeast bottling corridor where blow-molding and canning capacity scales to serve Florida and Atlantic Coast markets.
Canada
Ontario's Blue Box transition shifts full extended producer responsibility onto packaging suppliers by 2026. Health Canada administers food-contact safety parallel to US FDA frameworks. Quebec and British Columbia monitor Ontario's implementation for provincial mandate templates that would reshape converter investment patterns across the Prairie Provinces.
Mexico
Nuevo León and Jalisco bottling facilities supply carbonated soft drink and beer demand throughout northern Mexico and cross-border US markets. The country's environmental regulator advances packaging waste frameworks that track California's SB 54 trajectory. Baja California canning lines serve San Diego-Tijuana metropolitan demand with compressed logistics costs.
North America Beverage Packaging Market Competitive Landscape
Concentration sits with integrated resin-to-bottle operators and aluminum can sheet specialists who anchor long-term supply contracts. The vendor base spans three functional tiers: multinational converters with captive resin supply, regional blow-molding specialists serving craft beverage accounts, and paperboard carton licensors with aseptic technology platforms. Dominant competitive moves include backward integration into recycled feedstock streams and capacity expansion in the US Southeast manufacturing belt.
Within the integrated converter tier, Amcor and Ball Corporation exemplify scale-driven positioning. Amcor occupies a position among resin-integrated bottle suppliers. Ball Corporation anchors aluminum can production capacity. Berry Global Group sits within the diversified packaging archetype with multi-material portfolio breadth.
| Leading Market Players |
|---|
| Berry Global Group |
| Owens-Illinois |
| Amcor |
| WestRock Company |
| Mondi Group |
| Ball Corporation |
| Tetra Laval |
| Silgan Holdings |
| Crown Holdings |
| Others |
Value Network & Pricing Analysis
rPET substitution for virgin PET resin simultaneously redraws procurement geography across the US Southeast and compresses margin structures for blow-molding specialists tethered to volatile ethylene feedstock benchmarks. California's SB 54 mandates accelerate this shift by attaching compliance premiums to recycled content sourcing that mechanical recyclers in Georgia and Texas struggle to fulfill at scale.
Pricing Analysis
The customization-premium spread separates configured-to-order barrier-coated bottles for functional beverage brands from commodity PET water bottles sold on spot resin indices. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade for food-contact rPET and geographic delivery cost to bottling clusters. Pricing pressure stems from aluminum sheet supply concentration among three domestic rolling mills serving craft brewery expansion. Regional brand owners exhibit highest price sensitivity; multinational soft drink portfolios absorb premiums through long-term offtake contracts.
Supply Chain Analysis
Domestic can sheet production concentrates among rolling mills in the United States, with secondary supply nodes in Canada and Mexico serving cross-border demand. Raw material flows draw from bauxite refining circuits, secondary aluminum scrap streams, and alloying element suppliers. Tariff exposure on Canadian aluminum imports creates procurement volatility for converters with integrated can-making operations. Distribution runs through three-tier beverage networks anchored in Georgia and Texas corridor facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with direct-to-store distribution models that compress batch minimums and create niches for regional converters serving craft beverage and functional drink startups. Wellness-oriented brand proliferation fragments demand across oxygen-scavenger PET, aseptic cartons, and aluminum cans with quick-changeover requirements.
For Market Incumbents: Compound defensive positioning through backward integration into chemical recycling feedstock streams and capacity addition in the US Southeast manufacturing belt. Secure long-term rPET offtake agreements before California's SB 54 compliance deadlines tighten. Threat substitution from mono-material barrier technologies displaces multi-layer film demand; lever vertical integration to preserve margin structures. For New Entrants and Emerging Players: FDA food-contact certification fast-track for pyrolysis-derived rPET creates entry path into premium juice and ready-to-drink coffee segments. White space concentrates in the US Mountain West aseptic carton gap for plant-based milk categories. Go-to-market angle targets direct-to-store craft brewery accounts bypassing traditional distributor networks in Colorado and Pacific Northwest markets. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors resin-integrated converters with captive recycled feedstock supply. Long-term viability hinges on compliance infrastructure for state-level bottle deposit expansion and extended producer responsibility frameworks. Acquisition target archetype: regional blow-molding specialists with Southeast corridor location and quick-changeover tooling capabilities. Signal to watch: Ontario Blue Box transition template adoption across Quebec and British Columbia provincial mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chemical Recycling | Pyrolysis partnerships with resin suppliers secure food-grade rPET volumes beyond mechanical processing limits. |
| Southeast Corridor Capacity Expansion | Georgia and Texas facilities compress freight radius to Atlantic Coast population corridors. |
| Direct-to-Store Distribution Partnership | Taproom-to-retail vertical integration in Colorado and Pacific Northwest markets shortens order cycles. |
| Mono-Material Barrier Certification | Oxygen scavenger PET additives displace EVOH laminates and simplify mechanical recycling eligibility. |
| Provincial EPR Compliance Infrastructure | Ontario Blue Box transition readiness positions converters for Quebec and British Columbia mandate replication. |
Research Methodology
A spread of perspectives from blow-molding plant managers, beverage brand procurement leads, aluminum rolling mill technical directors, state environmental regulator policy staff, and retail category buyers converged on the working assumptions underlying volume and value estimates. Primary fieldwork combined structured interviews with secondary validation through US EPA extended producer responsibility filings, state bottle bill program databases, SEC 10-K disclosures from packaging converters, and American Chemistry Council resin production statistics. Bottom-up capacity utilization data triangulated against top-down beverage consumption trends.
Segmentation dimensions modeled include packaging format, material substrate, end-use application, and distribution channel complexity across the projection horizon. CAGRs were derived from slope analysis of historical volume trajectories adjusted for regulatory compliance deadlines and capacity expansion announcements. Industry-specific forecast inputs incorporated fill-line retrofit coordination timelines and recycled content certification lag estimates from third-party chain-of-custody verifiers.
Decision-makers should treat outputs as directional under assumptions of SB 54 implementation adherence and mechanical recycling contamination rates; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as chemical recycling scale-up economics and provincial EPR mandate adoption patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Europe Soft Drinks Packaging Market
Beverage Packaging
Tumblers Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
United States Aluminum Beverage Cans Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Foamer Bottle Market
Beverage Packaging
Juice Packaging Market
Beverage Packaging
Media Bottles Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Foldable Bottles Market
Beverage Packaging
Water Cooler Market