
 Beverage Aluminum Cans Market | 2026-2036
Beverage Aluminum Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Aluminum Cans Market Outlook
The EU Green Deal is pivoting European beverage brands toward infinitely recyclable aluminum formats, forcing converters to retool lines for lighter-weight specifications. Ball Corporation leverages its integrated recycling infrastructure to secure input cost advantages across North American filling corridors. Crown Holdings anchors European supply through its dedicated beverage can plants in Spain and Germany. Ardagh Group competes on specialty shaping capabilities that serve premium sparkling water and craft beer portfolios.
Beverage aluminum cans are cylindrical containers fabricated from aluminum alloy sheets, typically featuring a drawn-and-ironed body with a separate domed lid seamed under pressure; wall thickness ranges from 0.097 mm to 0.115 mm depending on internal carbonation pressure requirements, and they serve as the dominant single-serve packaging format for carbonated and non-carbonated drinks. Standard Cans dominate volume across mass-market soft drinks and mainstream beer, while Specialty Cans command margin premiums through embossed textures and custom geometries for premium positioning. Slim Cans sustain the fastest expansion trajectory, driven by energy drink brands and reduced-portion sparkling beverages targeting younger demographics.
The EPA oversees emissions compliance at U.S. smelting and coating facilities, while the EU F-Gas Regulation constrains fluorinated greenhouse gas use in can manufacturing heat treatments, and ISO 9001 quality certifications shape supplier qualification thresholds for multinational beverage bottlers. Regulatory stringency on embodied carbon and recycled content verification will determine which converters retain preferred-supplier status with Coca-Cola, PepsiCo, and AB InBev procurement teams.
Market Dynamics
Lightweighting mandates from the EU Green Deal and parallel state-level recycling laws are forcing converters to reengineer can-body specifications below 0.100 mm wall thickness, compressing legacy equipment lifecycles and accelerating capital rotation across the supply base.
Growth Catalysts
- EU F-Gas Regulation:Fluorinated gas restrictions on heat-treatment processes are pushing converters toward electric annealing lines, creating first-mover advantages for facilities with upgraded infrastructure.
- Energy drink brands:Slim can formats are capturing shelf space in convenience retail, with younger demographics driving volume premiums for 250 ml and 200 ml variants.
- São Paulo manufacturing corridor:Brazil's southeastern cluster offers integrated bauxite-to-can supply chains that reduce logistics costs for export-oriented beverage brands.
Market Restraints
- Primary aluminum volatility:LME price swings above fifteen percent annually compress converter margins and complicate long-term supply agreements with bottlers.
- Smelter concentration:Gulf Coast and Quebec smelting capacity bottlenecks create input scarcity during peak summer demand windows.
- Steel can substitution:Two-piece steel formats retain cost advantages in ambient-stable juice and dairy segments, limiting aluminum penetration in non-carbonated categories.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for advanced manufacturing are attracting can-body line investments to serve domestic soft-drink and beer growth.
- Digital printing convergence:High-speed inkjet decoration enables batch sizes below ten thousand units, unlocking craft brewery and limited-edition sparkling water contracts.
- Deposit-return schemes:Extended producer responsibility frameworks in Germany and Scandinavia are mandating closed-loop collection infrastructure that secures scrap supply for integrated recyclers.
Industry Challenges
- Thin-wall metallurgy expertise:Alloy formulation for sub-0.100 mm bodies requires rare materials engineering talent that concentrates at legacy European and Japanese research centers.
- ISO 9001 recertification timelines:Multinational bottlers are compressing supplier audit cycles to eighteen months, straining quality documentation systems at mid-tier converters.
- Legacy seaming equipment integration:Retrofitting older lines for lighter-weight specifications demands six-to-nine month downtime windows that conflict with seasonal production peaks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Aluminum Cans Market |
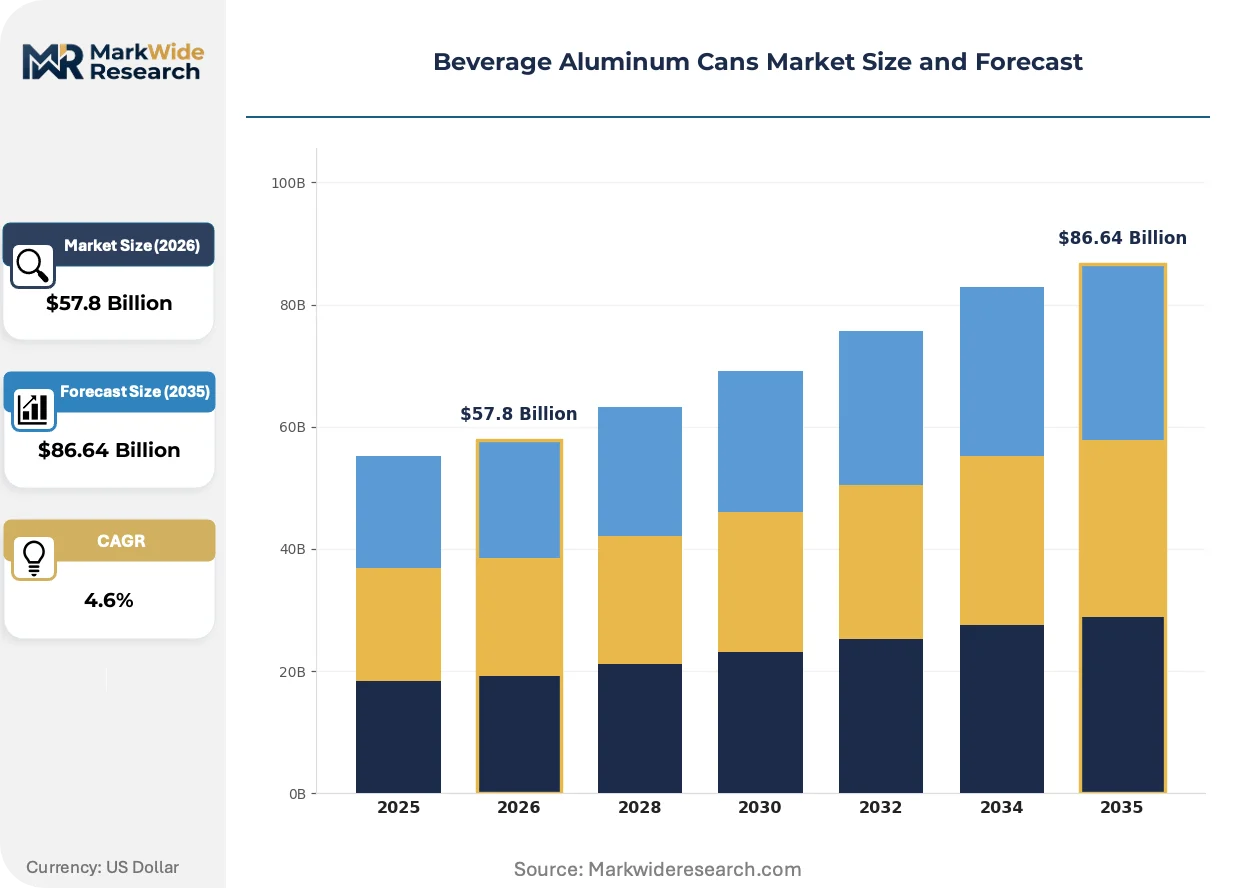
| Market Size in 2026 | $57.8 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cans, Specialty Cans, Slim Cans, Tall Cans End User: Soft Drinks, Alcoholic Beverages, Energy Drinks, Juices Size: 250 ml, 330 ml, 500 ml, 1 L Distribution Channel: Retail Stores, E-commerce, Wholesale, On-trade |
| Companies Covered | Ball Corporation, Crown Holdings, Ardagh Group, Silgan Containers, CAN-PACK, Toyo Seikan, CPMC Holdings, Kian Joo Can Factory Berhad, Novelis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Aluminum Cans Market Strategic Shifts
Digital decoration and alloy engineering are converging to transform how beverage brands differentiate shelf presence while meeting circular economy mandates. These shifts are compressing product development cycles and reconfiguring converter-bottler contractual relationships.
High-definition inkjet printing is integrating directly into can-body manufacturing lines, enabling photorealistic imagery and variable data serialization at speeds matching traditional offset coating. Premium sparkling water and craft beer portfolios are adopting this capability within twelve-to-eighteen month equipment payback periods. The technology is integrating brand localization strategies that previously required separate label application or shrink-sleeve addition.
The EU Green Deal's embodied carbon verification requirements are mandating mass-balance accounting for recycled content claims across beverage packaging supply chains. Converters must now document scrap provenance through smelting, rolling, and coating stages to retain preferred-supplier status with multinational bottlers. European filling corridors face the steepest compliance burden, with German and Spanish facilities piloting blockchain-tracked material passports.
Direct-to-retail procurement models are consolidating formerly fragmented distributor networks, with large-format beverage brands negotiating multi-year volume commitments that bypass traditional can-and-end merchant intermediaries. This channel compression is most visible in North American energy drink and hard seltzer segments, where brand-owned filling lines are capturing twenty-five to thirty percent of regional can demand. Smaller craft breweries remain dependent on merchant distributor relationships, creating a bifurcated sourcing landscape.
Beverage Aluminum Cans Market Segmentation
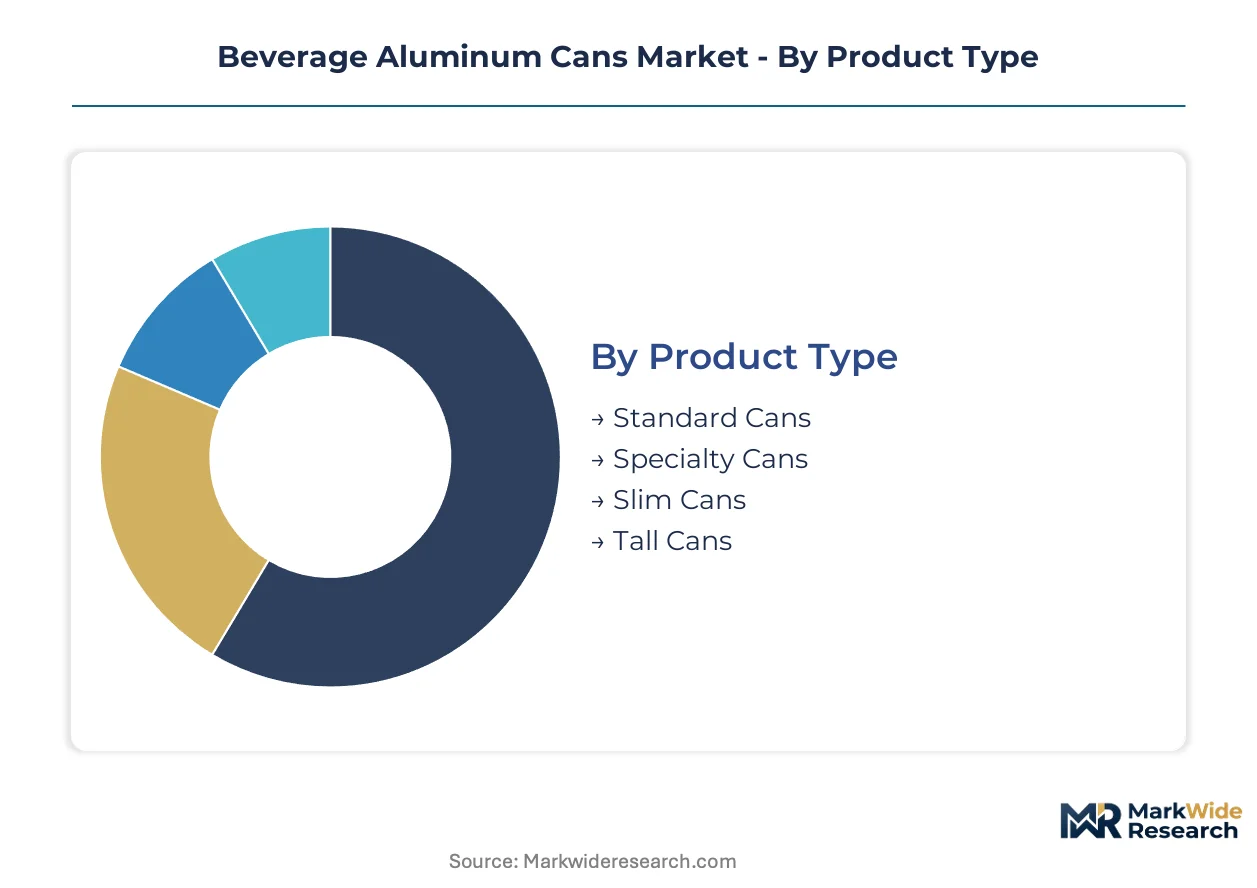
Equipment refresh cycles and lightweighting mandates are fragmenting converter capabilities across product formats. End-user procurement consolidation is compressing SKU diversity while premium positioning demands expand specialty and slim variants.
Product Type:
Converter line upgrades for sub-0.100 mm wall specifications are forcing segment-specific capital allocation decisions.
- Standard Cans:Two-piece drawn-and-ironed bodies with 0.097-0.115 mm wall thickness serve mass-market carbonated soft drinks and mainstream lager. Volume concentrates in Brazil's São Paulo corridor where integrated bauxite-to-can supply chains serve export-oriented bottlers.
- Specialty Cans:Embossed textures and custom geometries command margin premiums through differentiated shelf presence. European premium sparkling water and craft beer portfolios drive specifications requiring Ball Corporation and Crown Holdings to maintain dedicated shaping tool inventories.
- Slim Cans:200-250 ml formats target reduced-portion positioning.
- Tall Cans:Extended aspect ratios serve single-serve wine and ready-to-drink cocktails.
Volume placements concentrate in Standard Cans; the faster expansion belongs to Slim Cans.
End User:
Procurement consolidation among multinational bottlers is reshaping segment-level contract structures.
- Soft Drinks:Coca-Cola and PepsiCo procurement teams mandate ISO 9001 certification and embodied carbon documentation. EU Green Deal mass-balance requirements are forcing converters to pilot blockchain-tracked material passports at German and Spanish filling corridors.
- Alcoholic Beverages:AB InBev and craft brewery demand bifurcates sourcing patterns. North American craft scaling favors aluminum portability while Brazilian integrated supply serves mainstream beer export volumes.
- Energy Drinks:Brand-owned filling lines capture regional can demand through direct-to-retail procurement.
- Juices:Ambient-stable segments face steel can substitution pressure limiting aluminum penetration.
Soft Drinks anchor procurement volume; Energy Drinks are climbing the fastest on slim format adoption.
Size:
Portion-control trends and retail shelf economics are compressing format ranges toward mid-volume specifications.
- 330 ml:The mainstream single-serve specification dominates European and North American convenience retail. EU F-Gas Regulation compliance costs for heat-treatment processes are passed through most efficiently at this volume scale.
- 500 ml:The multi-serve and sharing format commands presence in Brazilian on-trade channels. São Paulo manufacturing cluster logistics favor this specification for domestic beer distribution.
- 250 ml:Reduced-portion positioning for premium categories.
- 1 L:Family and party-size applications.
330 ml specifications dominate placement counts; 250 ml variants gain share fastest on energy drink proliferation.
Distribution Channel:
Channel compression is eliminating traditional merchant intermediaries in high-volume segments while fragmenting craft access routes.
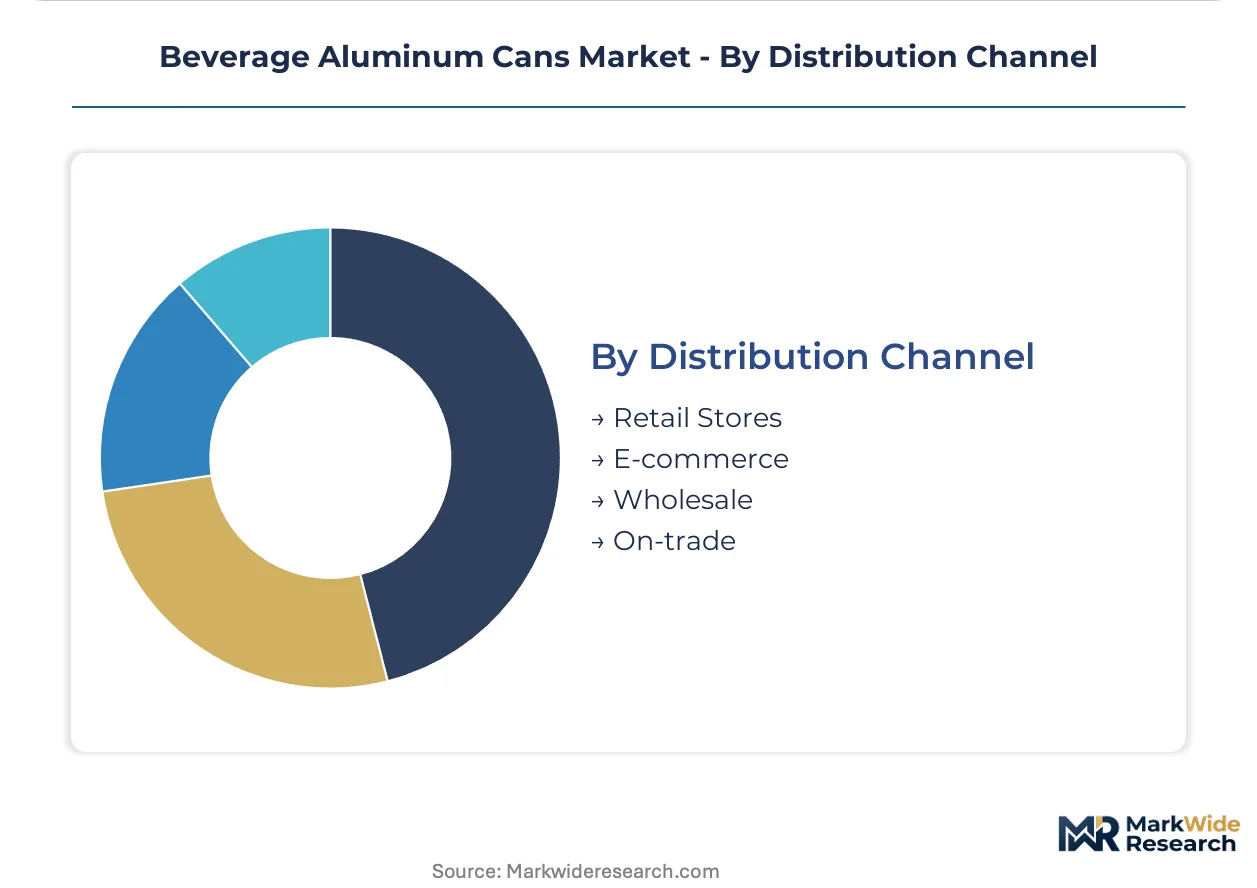
- Retail Stores:Large-format beverage brands negotiate multi-year volume commitments bypassing can-and-end merchants. North American hard seltzer and energy drink segments show twenty-five to thirty percent channel capture through direct procurement.
- On-trade:Bars and restaurants demand smaller batch flexibility and rapid replenishment. Digital printing convergence enables batch sizes below ten thousand units, unlocking converter contracts with craft brewery portfolios.
- E-commerce:Direct-to-consumer fulfillment requires damage-resistant packaging specifications.
- Wholesale:Traditional distributor networks serve remaining fragmented demand.
Retail Stores concentrate procurement volume; On-trade is expanding most quickly on digital printing enablement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors the most concentrated beverage aluminum can manufacturing corridor outside Asia, with integrated bauxite-to-can supply chains serving export-oriented Latin American bottlers.
United States
Energy drink brands and hard seltzer portfolios drive slim can demand through direct-to-retail procurement models. EPA emissions compliance at Gulf Coast smelting facilities constrains peak summer input availability. Chicago-Milwaukee filling corridors concentrate converter capacity for Midwestern soft-drink distribution networks.
Germany
Premium sparkling water and craft beer portfolios command specialty can specifications with embossed textures. EU F-Gas Regulation mandates electric annealing line upgrades at heat-treatment facilities. Bavarian filling corridors pilot blockchain-tracked material passports for mass-balance recycled content verification.
Brazil
Mainstream beer export volumes sustain demand for 500 ml multi-serve formats across domestic on-trade channels. ANVISA packaging standards align with EU circular economy benchmarks for beverage contact materials. Minas Gerais bauxite deposits feed integrated smelting-to-can-body supply chains serving Atlantic port exports.
China
Domestic soft-drink growth attracts can-body line investments under advanced manufacturing incentive programs. SAMR food contact material regulations enforce aluminum purity thresholds for carbonated beverage packaging. Yangtze River Delta rolling mills supply drawn-and-ironed body stock to filling corridors in Jiangsu and Zhejiang provinces.
India
Production-linked incentive schemes for advanced manufacturing draw converter investments targeting domestic beer and soft-drink expansion. BIS quality certification requirements shape supplier qualification thresholds for multinational bottler procurement teams. Maharashtra and Gujarat industrial corridors concentrate emerging can-coating and printing capacity.
Beverage Aluminum Cans Market Competitive Environment
The competitive structure tilts toward integrated multinationals with captive recycling infrastructure. Three global converters control the majority of North American and European filling corridor supply through dedicated beverage can plants. Strategic archetypes separate integrated recyclers with smelter relationships, specialty shaping specialists serving premium portfolios, and regional fabricators competing on logistics proximity. Capacity expansion and lightweighting technology licensing represent the dominant competitive moves as converters retool for sub-0.100 mm wall specifications.
Among integrated North American operators, Ball Corporation exemplifies the recycler-integrated archetype through smelting and rolling assets that secure input cost advantages. Crown Holdings anchors European supply positioning through dedicated beverage facilities in Spain and Germany. Ardagh Group occupies the specialty shaping tier, serving premium sparkling water and craft beer portfolios through custom geometry capabilities.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings |
| Ardagh Group |
| Silgan Containers |
| CAN-PACK |
| Toyo Seikan |
| CPMC Holdings |
| Kian Joo Can Factory Berhad |
| Novelis |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up converter specialists have consolidated mid-tier fabrication assets across North American and European filling corridors, tightening working-capital discipline and compressing payment terms to raw-material suppliers while passing through LME-linked aluminum volatility via indexed contract structures.
Pricing Analysis
Value-based pricing anchors on throughput guarantees at brand-owned filling lines, with converters securing multi-year offtake commitments from Coca-Cola and PepsiCo procurement teams that embed volume-scale rebates and ISO 9001 certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates specialty-shaped cans with embossed textures from mass-market drawn-and-ironed bodies. Pricing pressure stems from lightweighting mandates below 0.100 mm wall thickness that accelerate equipment depreciation. Craft breweries exhibit highest price sensitivity due to batch-size fragmentation, while energy drink brands absorb premiums for slim-can format exclusivity.
Supply Chain Analysis
EU Green Deal domestic-content mandates for recycled aluminum provenance are reshaping sourcing patterns, forcing converters to document scrap mass-balance through blockchain-tracked material passports. Supply concentrates in Brazil, Germany, and the United States, with Minas Gerais bauxite deposits feeding integrated smelting-to-can-body chains. Primary aluminum ingot, magnesium alloying additives, and epoxy-phenolic interior coatings constitute critical input dependencies. Single-source vulnerability runs through Gulf Coast and Quebec smelting capacity bottlenecks during peak summer demand windows. Distribution runs through direct-to-retail procurement models that displace traditional can-and-end merchant intermediaries in high-volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The beverage aluminum can market sits in a technology-transition phase as digital inkjet decoration displaces traditional offset coating lines, compressing equipment payback periods and reconfiguring converter-bottler contractual relationships.
For Market Incumbents: Lock in captive recycling infrastructure through backward integration into smelting and rolling assets that secure input cost advantages against LME volatility. Accelerate electric annealing line upgrades to capture EU F-Gas Regulation compliance premiums before legacy heat-treatment facilities face forced obsolescence. Defend market position by embedding blockchain-tracked material passports that satisfy multinational bottler procurement requirements for embodied carbon verification.
For New Entrants and Emerging Players: Digital printing convergence serves as the technology-first wedge, enabling batch sizes below ten thousand units that unlock craft brewery and limited-edition sparkling water contracts previously inaccessible to high-volume converters. Target India's Maharashtra and Gujarat industrial corridors where PLI scheme incentives reduce capital barriers for can-coating and printing capacity investments. Pursue on-trade channel partnerships with bars and restaurants demanding rapid replenishment and smaller batch flexibility.
For Investors and Strategic Acquirers: Ball Corporation's integrated recycling infrastructure expansion is the leading indicator that smelter-relationship assets will command acquisition premiums across the analysis window. Long-term viability favors converters with demonstrated lightweighting metallurgy expertise and mass-balance accounting capabilities. Target mid-tier European fabricators with specialty shaping tool inventories serving premium sparkling water portfolios. Watch for EU Green Deal enforcement actions against non-compliant heat-treatment facilities as the inflection signal for accelerated industry consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Annealing Line Upgrade | EU F-Gas Regulation compliance secures preferred-supplier status with German and Spanish bottlers. |
| Blockchain Material Passport Pilot | Mass-balance documentation satisfies Coca-Cola and PepsiCo embodied carbon procurement mandates. |
| Slim Can Format Capacity Addition | 250 ml and 200 ml variants capture energy drink volume premiums from younger demographics. |
| Specialty Shaping Tool Investment | Embossed textures and custom geometries command margin premiums in premium sparkling water. |
| Direct-to-Retail Procurement Model | Bypassing merchant intermediaries captures twenty-five to thirty percent of North American hard seltzer demand. |
Study Parameters
Document review covered trade association filings, customs records, and SEC disclosures from publicly traded converters, complemented by interviews with plant managers at beverage can fabrication facilities, procurement leads at multinational bottlers, technical R&D directors specializing in alloy formulation, and channel sales heads at can-and-end distributors. Secondary validation drew from EPA emissions databases, EU F-Gas Regulation implementation reports, and ISO 9001 certification registries. Bottom-up and top-down triangulation cross-checked production capacity estimates against fill-volume projections from beverage brand annual reports.
Segment-level outputs across product type, end user, size, and distribution channel dimensions were modeled through the projection horizon, with CAGRs derived from elasticity-adjusted demand curves and capacity expansion announcements. Primary aluminum price volatility, lightweighting technology adoption curves, and deposit-return scheme implementation timelines served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical disruptions to bauxite supply corridors, unanticipated regulatory acceleration of embodied carbon thresholds, and breakthrough substitution technologies in alternative packaging formats. Forecasts reflect documented assumptions regarding equipment refresh cycles and recycling infrastructure investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
Zippered Bottle Suit Market
Beverage Packaging
Europe Soft Drinks Packaging Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
Middle East and Africa Soft Drinks Packaging Market
Beverage Packaging
Insulated Cup Sleeves Market
Beverage Packaging
Drink Hoses Market
Beverage Packaging
Disposable Tea Flask Market
Beverage Packaging
Cup Filler Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Foldable Bottles Market
Beverage Packaging
Dual Chamber Dispensing Bottles Market
Beverage Packaging
Indonesia Plastic Bottles Market
Beverage Packaging
Europe Beverage Container Market
Beverage Packaging
Asia Pacific Beverage Packaging Market
Beverage Packaging
Cold Beverage Cups Market