
 US Beverage Packaging Market | 2026-2036
US Beverage Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
US Beverage Packaging Market Analytics
Buyer concentration among craft beverage producers is broadening as regional microbreweries and functional drink startups multiply across the US, fragmenting what was once a Big Three soft drink procurement oligopoly. Ball Corporation leverages its aluminum can capacity to dominate the craft beer canning surge across Colorado and the Pacific Northwest. Crown Holdings Inc. sustains its position through metal closure specialization that serves both legacy soda brands and emerging sparkling water lines. Amcor plc anchors the flexible pouch segment for sports nutrition and ready-to-drink cocktails, competing on barrier film technology.
US beverage packaging encompasses the design, fabrication, and decoration of primary and secondary containers for liquid consumer products, including aluminum cans with internal epoxy phenolic linings rated to 90 psi burst pressure, glass bottles with controlled thermal shock resistance, and multilayer PET structures incorporating oxygen scavenger layers to extend shelf life. Its commercial purpose centers on preserving product integrity, enabling brand differentiation through graphic surface area, and facilitating efficient distribution through stackable, pallet-compatible geometries. Aluminum cans command the fastest volume growth trajectory driven by carbonated water and alcoholic seltzer proliferation, while glass bottles retain premium positioning in wine and spirits where tactile weight signals quality. Plastic bottles face structural headwinds from municipal recycling contamination thresholds and brand-led lightweighting mandates, concentrating margin pools in rPET sourcing and mechanical recycling infrastructure.
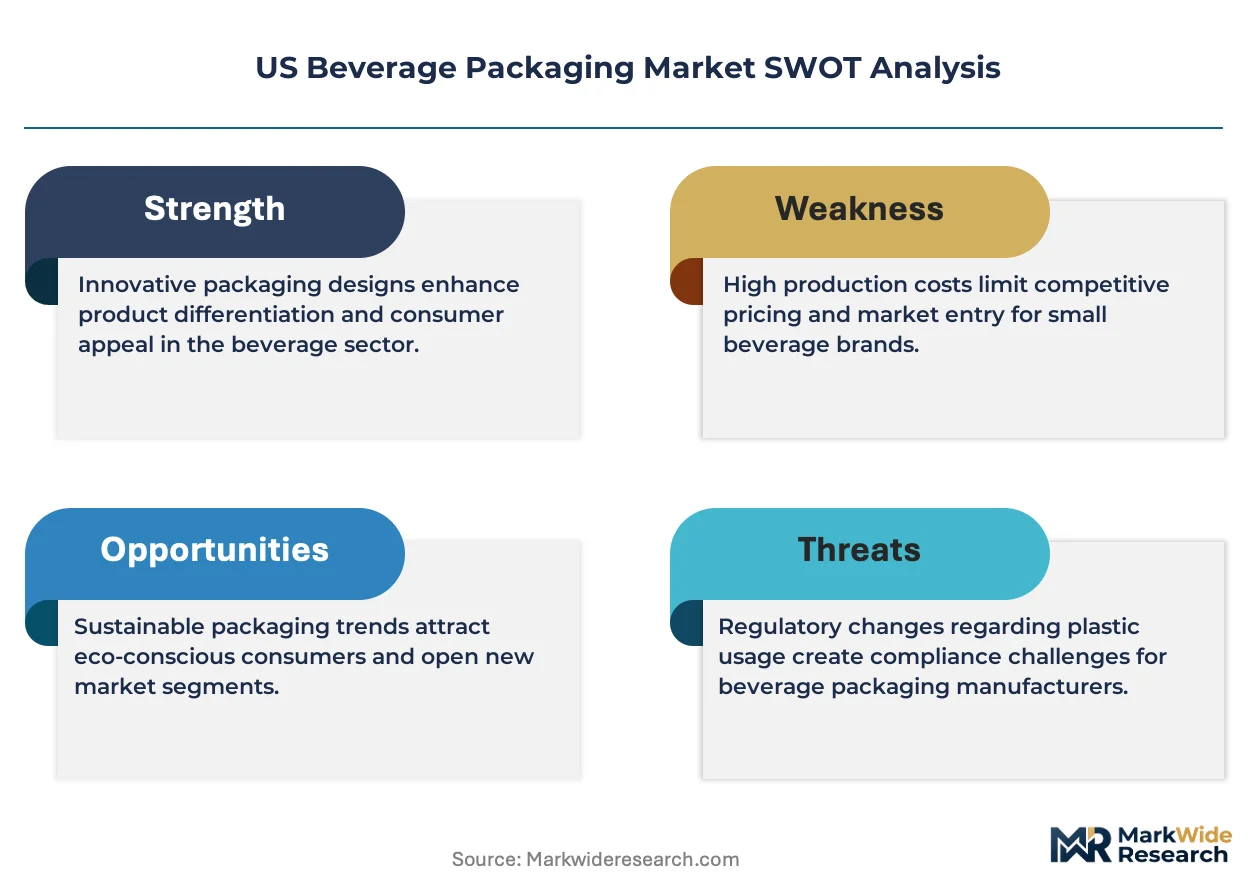
The FDA governs food contact notifications for novel packaging substrates and adjuvants, while the EPA regulates volatile organic compound emissions from can coating operations and flexographic printing facilities. California's SB 54 and Oregon's Plastic Pollution and Recycling Modernization Act impose extended producer responsibility fees that directly alter material economics for PET and multilayer flexible formats. State-level deposit return systems in Maine, Oregon, and Michigan create divergent post-consumer collection economics that packaging strategists must model against national SKU rationalization goals. Stakeholders should monitor how the interplay between federal food safety preemption and state environmental legislation reshapes permissible material portfolios and regional manufacturing footprints.
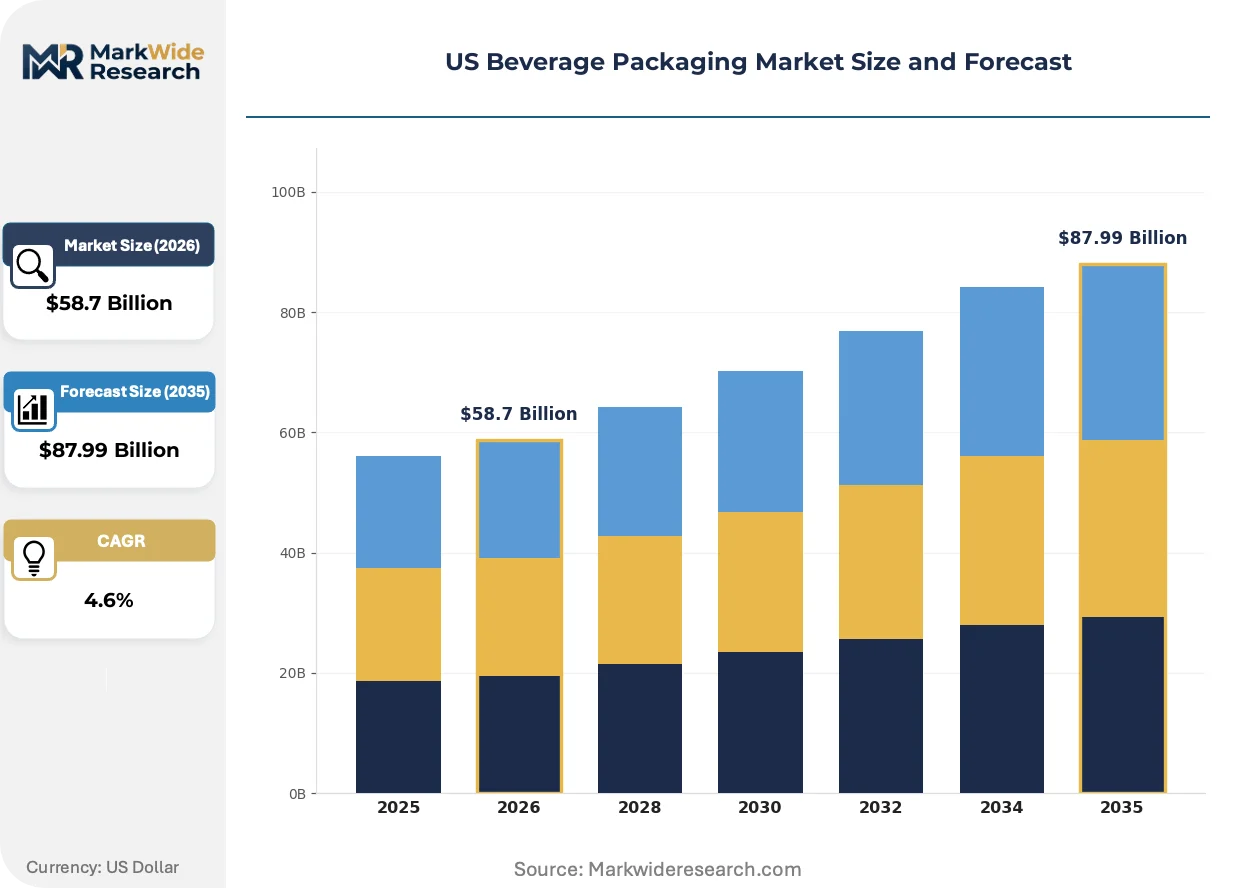
Market Dynamics
State-level extended producer responsibility mandates in California and Oregon are forcing material portfolio reconfigurations that cascade through national supply chains, compelling converters to regionalize production footprints and dual-track compliance systems.
Growth Catalysts
- Aluminum Can Surge:Carbonated water and alcoholic seltzer proliferation across Pacific Coast microbreweries and functional drink startups is pulling capacity investments toward lightweight, infinitely recyclable metal formats.
- SB 54 Implementation:California's extended producer responsibility law creates compliance-driven demand for post-consumer recycled content verification systems and mechanical recycling infrastructure partnerships.
- Craft Beverage Fragmentation:Regional microbreweries and specialty coffee roasters in Colorado and the Pacific Northwest are broadening SKU diversity and shortening production runs, expanding addressable packaging format requirements.
Market Restraints
- rPET Supply Concentration:Mechanical recycling infrastructure bottlenecks in the Southwest concentrate virgin resin dependency and expose converters to petroleum feedstock volatility.
- Multilayer Flexible Technical Lock-in:Oxygen scavenger layers and barrier film laminations in sports nutrition pouches resist mechanical recycling streams, creating end-of-life liability under Oregon's Plastic Pollution and Recycling Modernization Act.
- Deposit Return System Fragmentation:Divergent post-consumer collection economics across Maine, Oregon, and Michigan complicate national SKU rationalization and reverse logistics modeling.
Strategic Opportunities
- Southwest Population Corridors:Arizona and Texas metropolitan growth intersects with municipal sustainability mandates, creating concentrated demand for lightweight aluminum and refillable bottle systems.
- Ready-to-Drink Cocktail Pouch Expansion:Barrier film technology convergence with aseptic filling protocols opens shelf-stable, portable formats previously confined to glass and cans.
- FDA Food Contact Notification Pathways:Novel substrate approvals for bio-based liners and mineral-filled resins offer first-mover positioning in next-generation can and bottle interiors.
Industry Challenges
- Epoxy Phenolic Lining Chemist Talent Scarcity:Internal coating formulation expertise for 90 psi burst-pressure aluminum cans concentrates among legacy suppliers, constraining new entrant scale-up timelines.
- Flexographic VOC Abatement Capex Burden:EPA emissions regulations for printing facilities require thermal oxidizer investments that compress margins for mid-volume decoration operations.
- Dual-Track Compliance System Integration:Parallel federal food safety preemption and state environmental legislation create conflicting material specifications that fragment production scheduling and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Beverage Packaging Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $87.99 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Cans, Tetra Packs, Pouches Material: Plastic, Glass, Aluminum, Paper End User: Soft Drinks, Alcoholic Beverages, Juices, Bottled Water Size: Small, Medium, Large, Extra Large |
| Companies Covered | Ball Corporation, Crown Holdings Inc., Owens-Illinois Inc., Ardagh Group, Amcor plc, Silgan Containers Inc., Berry Global Inc., Sonoco Products Company, WestRock Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Beverage Packaging Market Evolving Landscape
Active and intelligent packaging systems alongside circular material flows are compressing traditional shelf-life and branding paradigms, forcing converters to integrate digital traceability and closed-loop recovery into core product architectures.
Digital printing with UV-curable inks and variable data capabilities is modularizing short-run decoration economics for craft beverage producers. Regional microbreweries in the Pacific Northwest adopt these systems to compress minimum order quantities from hundreds of thousands to tens of thousands of units. This technology is modularizing the barrier between mass-market scale efficiencies and hyper-local brand differentiation, enabling SKU proliferation without plate-changeover penalties.
California's SB 54 and Oregon's Plastic Pollution and Recycling Modernization Act mandate post-consumer recycled content thresholds and extended producer responsibility fees that directly alter PET and flexible film economics. Converters face compliance-driven material sourcing requirements that privilege domestic mechanical recyclers over virgin resin suppliers. The multilayer flexible segment bears the steepest adaptation burden, as barrier film complexity resists current sortation and reprocessing infrastructure.
Direct-to-procurement platforms and vertically integrated co-packing networks are compressing traditional distributor intermediation in the craft beer channel. Regional microbreweries in Colorado and the Pacific Northwest now source primary packaging through digital marketplaces that aggregate converter capacity and transparent pricing. This disintermediation concentrates buying power among mid-volume producers and forces legacy suppliers to unbundle decoration and logistics services previously embedded in long-term contracts.
US Beverage Packaging Market Segmentation
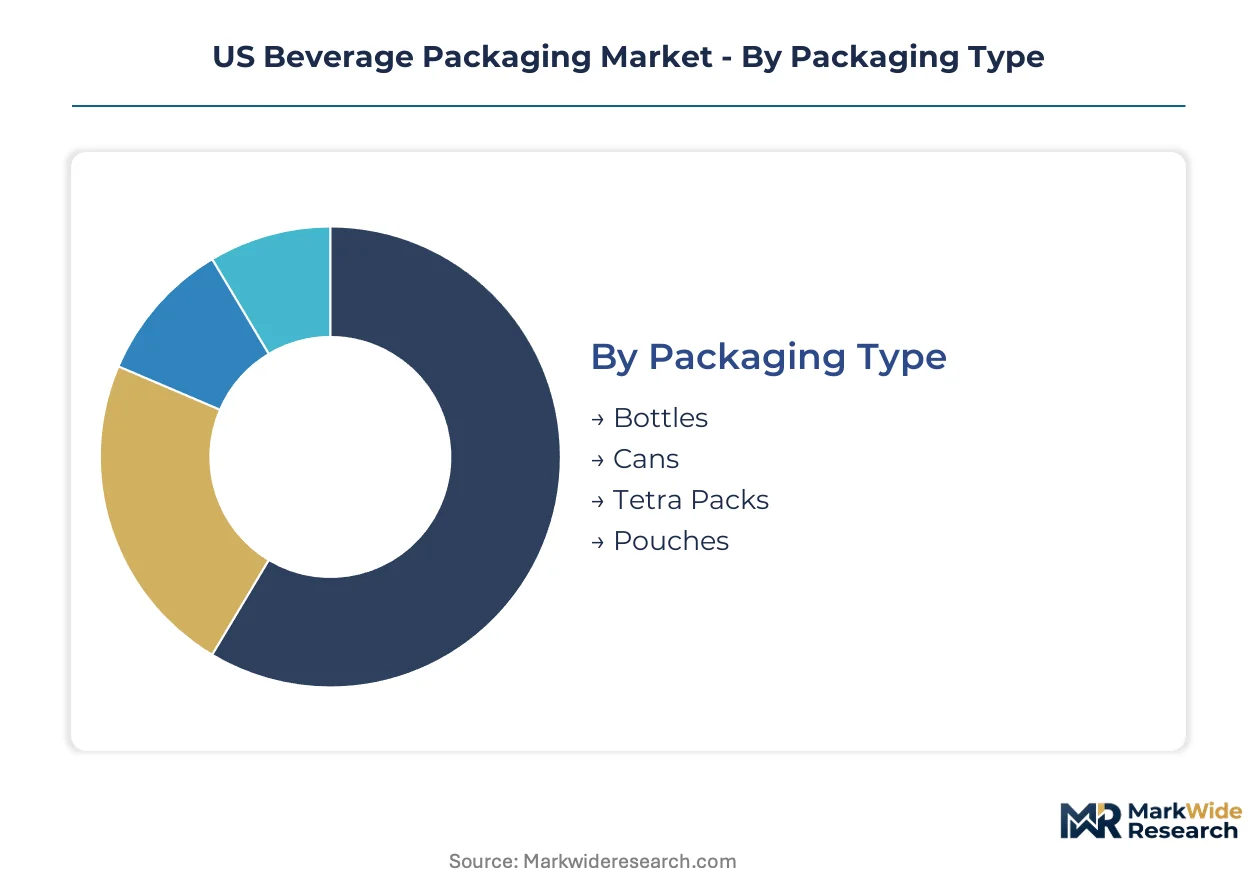
US beverage packaging segmentation reveals how supply concentration, regulatory pressure, and end-use fragmentation create divergent margin pools across formats. Understanding these fault lines exposes where converters must prioritize capacity investments versus where commoditization threatens returns.
Packaging Type:
Converter capacity concentrates most acutely in aluminum can lines across the Pacific Northwest and Southwest, while flexible pouch systems remain bottlenecked by barrier film expertise.
- Bottles:PET structures with oxygen scavenger layers dominate carbonated soft drinks and still water, though municipal recycling contamination thresholds in California and Oregon compress post-consumer resin economics. Glass bottles retain premium positioning in wine and spirits where tactile weight signals quality, particularly among Napa Valley and Willamette Valley producers facing extended producer responsibility fee structures.
- Cans:Internal epoxy phenolic linings rated to 90 psi burst pressure enable carbonated water and alcoholic seltzer proliferation across Colorado microbreweries and Pacific Northwest craft operations. This format commands the steepest capacity expansion trajectory as Ball Corporation and Crown Holdings concentrate aluminum rolling and coating investments near population growth corridors.
- Tetra Packs:Aseptic carton systems serve shelf-stable juices and plant-based milks through laminated paperboard-barrier film composites, constrained by limited domestic repulping infrastructure.
- Pouches:Multilayer flexible formats with metallized or coextruded barriers package sports nutrition and ready-to-drink cocktails, facing end-of-life liability under Oregon's Plastic Pollution and Recycling Modernization Act.
Today's leader: Cans. Tomorrow's challenger: Pouches.
Material:
Cost tier stratification separates virgin resin dependence from mechanical recycling premiums, with aluminum commanding mid-tier positioning between commodity plastics and premium glass.
- Plastic:PET and HDPE structures face structural headwinds from SB 54 recycled content mandates and lightweighting imperatives, concentrating margin pools in rPET sourcing partnerships with Southwest mechanical recyclers. Virgin resin dependency exposes converters to petroleum feedstock volatility.
- Glass:Controlled thermal shock resistance specifications serve wine, spirits, and premium craft beer segments where brand equity justifies weight and fragility trade-offs, particularly among heritage producers in Kentucky bourbon corridors and California wine country.
- Aluminum:Infinitely recyclable metal formats align with municipal sustainability mandates across Arizona and Texas metropolitan growth zones, though coating chemist talent scarcity constrains new entrant scale-up.
- Paper:Liquid packaging board and molded fiber formats expand in water and juice segments as fiber-based alternatives to plastic, limited by moisture barrier performance and FDA food contact notification requirements for novel substrates.
Plastic retains volume dominance. Aluminum gains share fastest on sustainability positioning.
End User:
Customer type fragmentation between legacy oligopoly brands and proliferating craft producers reshapes order economics and decoration technology requirements.
- Soft Drinks:The Big Three procurement oligopoly demands high-volume, standardized formats with flexographic decoration, though digital printing adoption compresses minimum order quantities for regional challenger brands.
- Alcoholic Beverages:Craft breweries and hard seltzer startups across Colorado and the Pacific Northwest drive SKU proliferation and short-run flexibility requirements, fragmenting what was once concentrated can procurement.
- Juices:Aseptic and high-pressure processing protocols favor multilayer cartons and PET bottles with barrier enhancements, concentrated in Florida and California production corridors.
- Bottled Water:Lightweighting mandates and rPET integration targets dominate this most commoditized segment, with Southwest population growth driving regional spring and purified water capacity.
Alcoholic beverages command premium pricing. Bottled water faces steepest cost compression.
Size:
Volume tier alignment with consumption occasion and channel format creates distinct equipment and logistics footprints across the size spectrum.
- Small:Single-serve formats for convenience and on-premise consumption concentrate in airport, stadium, and hospitality channels, requiring specialized filling line changeover capabilities.
- Medium:Standard retail multiples dominate grocery and convenience store distribution, optimizing pallet cube efficiency and shelf-facing economics.
- Large:Family and multi-serve formats serve club store and value-oriented retail, with lightweighting imperatives most acute given material cost exposure.
- Extra Large:Bulk and foodservice formats for restaurants, catering, and institutional buyers demand reinforced structural integrity and specialized handling equipment.
Medium formats anchor volume. Small formats expand on portability trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coating chemist talent concentrates in legacy industrial corridors, anchoring regional capacity for epoxy phenolic lining formulations and high-pressure aluminum can production.
Pacific Northwest
Craft brewery proliferation across Oregon and Washington pulls aluminum can demand while Oregon's Plastic Pollution and Recycling Modernization Act imposes extended producer responsibility fees on multilayer flexible formats. Ball Corporation concentrates coating investments near Portland to serve carbonated water and alcoholic seltzer startups.
Southwest
Metropolitan growth in Phoenix and Dallas intersects with municipal sustainability mandates, concentrating demand for lightweight aluminum and refillable bottle systems. Texas and Arizona deposit return system proposals remain stalled in legislature, preserving virgin resin dependency for PET converters. Crown Holdings anchors metal closure capacity near Houston to serve both legacy soda brands and emerging sparkling water lines.
California
SB 54 recycled content mandates reshape material economics for PET and flexible film converters across Los Angeles and Central Valley production zones. Napa Valley wine producers face extended producer responsibility fee structures that privilege glass bottle recovery. Amcor plc positions barrier film technology investments near Sacramento to serve ready-to-drink cocktail pouch expansion.
Colorado
Regional microbrewery density in Denver and Boulder drives SKU proliferation and short-run flexibility requirements for aluminum can procurement. State-level deposit return system mechanics diverge from Oregon and California models, complicating national converter compliance scheduling. Owens-Illinois sustains glass bottle capacity near Fort Collins for craft beer premium positioning.
Midwest
Legacy can coating expertise concentrates in Ohio and Indiana industrial corridors, constraining new entrant scale-up timelines for 90 psi burst-pressure aluminum formats. EPA volatile organic compound emissions regulations for flexographic printing facilities impose thermal oxidizer capex burdens on mid-volume decoration operations. Ardagh Group anchors metal packaging investments near Chicago to serve Big Three soft drink procurement oligopoly.
US Beverage Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material categories, creating tiered competitive dynamics. The vendor base stratifies between integrated metal packaging conglomerates, flexible film specialists, and glass container heritage players. Three archetypes dominate: aluminum can capacity aggregators, barrier film technology licensors, and decoration-integrated converters. Capacity expansion and strategic partnerships constitute the dominant competitive moves as converters respond to state-level extended producer responsibility mandates.
Among metal packaging specialists, Ball Corporation and Crown Holdings exemplify the aluminum can capacity aggregator archetype, while Amcor plc occupies a position within the barrier film technology tier. These three anchors represent contrasting strategic postures: metal-focused scale concentration versus flexible substrate specialization. Ball Corporation and Crown Holdings sit within the legacy industrial corridor talent concentration, while Amcor plc anchors the multilayer flexible segment where oxygen scavenger layers resist mechanical recycling streams. Their collective positioning illustrates how material portfolio breadth versus depth shapes competitive responses to California SB 54 and Oregon Plastic Pollution and Recycling Modernization Act compliance burdens.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings Inc. |
| Owens-Illinois Inc. |
| Ardagh Group |
| Amcor plc |
| Silgan Containers Inc. |
| Berry Global Inc. |
| Sonoco Products Company |
| WestRock Company |
| Others |
Value Network & Pricing Analysis
Epoxy phenolic resin formulations for aluminum can internal linings flow from petrochemical feedstock through three distinct pricing tiers before reaching Colorado microbreweries and Pacific Northwest seltzer startups. Virgin resin contracts anchor the premium tier, post-consumer recycled content verification systems command mid-tier positioning under California SB 54 compliance mandates, and spot-market aluminum ingot purchases serve volume-committed legacy soda brands.
Pricing Analysis
Bundled decoration-logistics contracts versus unbundled component sourcing splits the market between legacy soft drink procurement oligopolies and fragmented craft beverage producers. Three-tier pricing structure across premium, standard, and economy levels aligns with barrier film complexity, FDA food contact notification tier, and volume scale. Cost compression in the flexible pouch segment intensifies because Oregon's Plastic Pollution and Recycling Modernization Act imposes end-of-life liability fees. Craft breweries exhibit highest price sensitivity due to SKU proliferation and short-run economics, while wine and spirits producers accept premium positioning for tactile glass weight.
Supply Chain Analysis
Aluminum rolling and coating capacity rests on domestic smelter output from Kentucky and Indiana industrial corridors, Canadian primary aluminum imports, and Mexican secondary reprocessing streams. Virgin PET resin, epoxy phenolic coating chemicals, and metallized barrier films constitute critical input dependencies. Single-source vulnerability concentrates in legacy can coating chemist expertise clustered near Ohio and Indiana. Distribution runs through vertically integrated converter networks serving Big Three soft drink brands alongside digital procurement platforms aggregating capacity for regional microbreweries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US beverage packaging market represents a late-cycle quality story as carbonated water and alcoholic seltzer proliferation pulls demand toward infinitely recyclable aluminum formats with premium specifications. Craft beverage fragmentation and state-level extended producer responsibility mandates reward converters with compliance-ready material portfolios and short-run flexibility.
For Market Incumbents: Anchor aluminum can capacity investments near Phoenix and Dallas metropolitan growth corridors to capture Southwest sustainability mandate convergence. Defend position against digital procurement platform disintermediation by unbundling decoration services previously embedded in long-term contracts. Prioritize backward integration into post-consumer recycled content verification systems to meet California SB 54 thresholds. For New Entrants and Emerging Players: Launch via direct-to-procurement digital marketplaces serving Colorado and Pacific Northwest craft brewery density. Target the ready-to-drink cocktail pouch expansion segment where barrier film technology convergence with aseptic filling protocols opens shelf-stable formats. Pursue white-space in bio-based liner FDA food contact notification pathways for first-mover positioning in next-generation can interiors. For Investors and Strategic Acquirers: Consolidation pressure builds where coating chemist talent scarcity constrains new entrant scale-up timelines for 90 psi burst-pressure aluminum formats. Mid-cap flexible film specialists with oxygen scavenger layer expertise offer acquisition appeal as Oregon's Plastic Pollution and Recycling Modernization Act reshapes end-of-life economics. Watch for inflection signals in Texas and Arizona deposit return system legislative advancement that would alter virgin resin dependency calculations.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Ball Corporation concentrates coating investments near Portland to serve carbonated water startups. |
| Backward Integration | Crown Holdings anchors metal closure capacity near Houston to control aluminum rolling inputs. |
| Sustainability Repositioning | Amcor plc positions barrier film investments near Sacramento for SB 54 compliance-ready formats. |
| Direct-to-Consumer Launch | Digital procurement platforms compress minimum order quantities for Pacific Northwest microbreweries. |
| Long-term Supply Agreement | Legacy soda brands lock in flexographic decoration capacity through multi-year converter contracts. |
Research Methodology
Direct dialogue with plant managers at aluminum can coating facilities, procurement leads at craft beverage startups, distribution channel partners in the Southwest, and technical R&D directors at barrier film specialists grounded qualitative insights. Secondary validation drew from FDA food contact substance notification databases, EPA volatile organic compound emissions filings, California SB 54 implementation records, and Oregon Department of Environmental Quality recycling modernization reports. Bottom-up craft brewery demand modeling and top-down aluminum capacity assessments were triangulated against state-level extended producer responsibility fee structures.
Segment-level projections across packaging type, material, end user, and size dimensions were generated through the analytical framework across the analysis window. CAGRs were derived from aluminum can volume trajectories, PET lightweighting mandates, and flexible pouch regulatory headwinds. Forecast inputs incorporated population growth corridors in Arizona and Texas, municipal sustainability mandate adoption curves, and digital printing technology penetration rates among regional microbreweries.
Several conditions sit outside the modeled scope, including federal preemption challenges to state extended producer responsibility laws, breakthrough bio-based barrier film commercialization timelines, and macroeconomic aluminum commodity price volatility. Forecasts reflect assumptions about mechanical recycling infrastructure buildout rates and deposit return system legislative momentum. A small set of named triggers warrants ongoing watch: FDA novel substrate approval pathways, Texas deposit return system legislative advancement, and epoxy phenolic coating chemist labor market tightness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Drink Can Market
Beverage Packaging
Disposable Water Bottle Market
Beverage Packaging
Aluminium Cup Market
Beverage Packaging
US Soft Drinks Packaging Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
United States Aluminum Beverage Cans Market
Beverage Packaging
Beverage Packaging Machine Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
Tumblers Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Bottled Water Packaging Market
Beverage Packaging
Disposable Tea Flask Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Graduated Sample Bottle Market
Beverage Packaging
Pouring Spout Market