
 Vending Cups Market | 2026-2036
Vending Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Vending Cups Market Outlook
Chinese molded fiber production capacity is decoupling from traditional plastic cup supply chains as converters retool for compostable formats. Huhtamaki Oyj leverages its European thermoforming infrastructure to anchor biodegradable output for institutional clients. Dart Container Corporation sustains North American foam cup dominance through backward integration into resin compounding. Georgia-Pacific competes aggressively in paper-based alternatives, extending its pulp-to-cup manufacturing control across the southeastern United States.
Vending cups are single-serve beverage containers engineered from thermoformed plastic, extruded polystyrene foam, or molded pulp fiber, typically ranging from 6 to 20 ounces in calibrated volume for automated dispensing equipment. These vessels function as hygienic, standardized interfaces between beverage preparation systems and end consumers in high-traffic commercial environments. The material dimension reveals paper and compostable substrates capturing procurement preference as plastic and foam face regulatory headwinds across multiple jurisdictions. Within end-user categories, offices and schools generate recurring volume through contracted refreshment services, while malls and gyms produce episodic, transaction-driven demand with lower switching costs.
The FDA governs food-contact substance compliance for U.S. vending cup manufacturers, while the EU Single-Use Plastics Directive mandates extended producer responsibility schemes and consumption reduction targets across member states. China's SAMR enforces GB standards for food packaging materials, creating a fragmented compliance landscape for exporters serving multiple regulatory regimes. Stakeholders must monitor evolving state-level plastic bans in the United States and pending revisions to the EU Packaging and Packaging Waste Regulation, as these frameworks will determine which material technologies secure long-term procurement contracts.
Market Dynamics
The EU Single-Use Plastics Directive is forcing material transitions across vending cup supply chains as converters retool manufacturing lines away from polystyrene foam and conventional plastics toward molded fiber and compostable substrates.
Growth Catalysts
- Corporate refreshment services:Contracted beverage programs in office complexes generate recurring procurement volumes with predictable replacement cycles. These accounts prioritize standardized cup formats compatible with multi-vendor equipment fleets.
- Extended producer responsibility schemes:The EU Packaging and Packaging Waste Regulation mandates fee structures that favor recyclable and compostable materials, redirecting R&D investment toward fiber-based alternatives.
- Molded fiber technology maturation:Advances in thermoforming precision and barrier coating durability enable pulp-based cups to match plastic performance for hot beverage applications previously dominated by foam.
Market Restraints
- Resin price volatility:Polystyrene and polypropylene input costs fluctuate with petrochemical feedstock markets, compressing margins for manufacturers without backward integration into resin compounding.
- Composting infrastructure gaps:Industrial composting facility coverage remains sparse in the United States outside California and the Pacific Northwest, limiting the practical end-of-life advantage for certified biodegradable cups.
- Equipment retrofit requirements:Legacy vending machines calibrated for rigid plastic or foam cups require sensor and dispensing mechanism adjustments to handle compliant alternatives without jamming or misfeed.
Strategic Opportunities
- German institutional procurement:Public sector catering contracts in Germany now mandate plastic-free serviceware, creating dedicated demand channels for certified compostable cup suppliers.
- Closed-loop campus programs:Universities in the United Kingdom are piloting cup-as-a-service models with deposit-return systems, embedding vending cups into circular economy infrastructure.
- Barrier coating chemistry convergence:Integration of bio-based moisture barriers with traditional paperboard forming is expanding the temperature and shelf-life performance envelope for paper cups.
Industry Challenges
- Certification timeline compression:BPI and TÜV OK compost certifications require 180-day industrial composting validation cycles that delay product launches and freeze working capital in inventory.
- Legacy equipment compatibility:Vending machine fleets average 12-15 year replacement cycles, forcing cup manufacturers to maintain dual-format production lines during prolonged transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vending Cups Market |
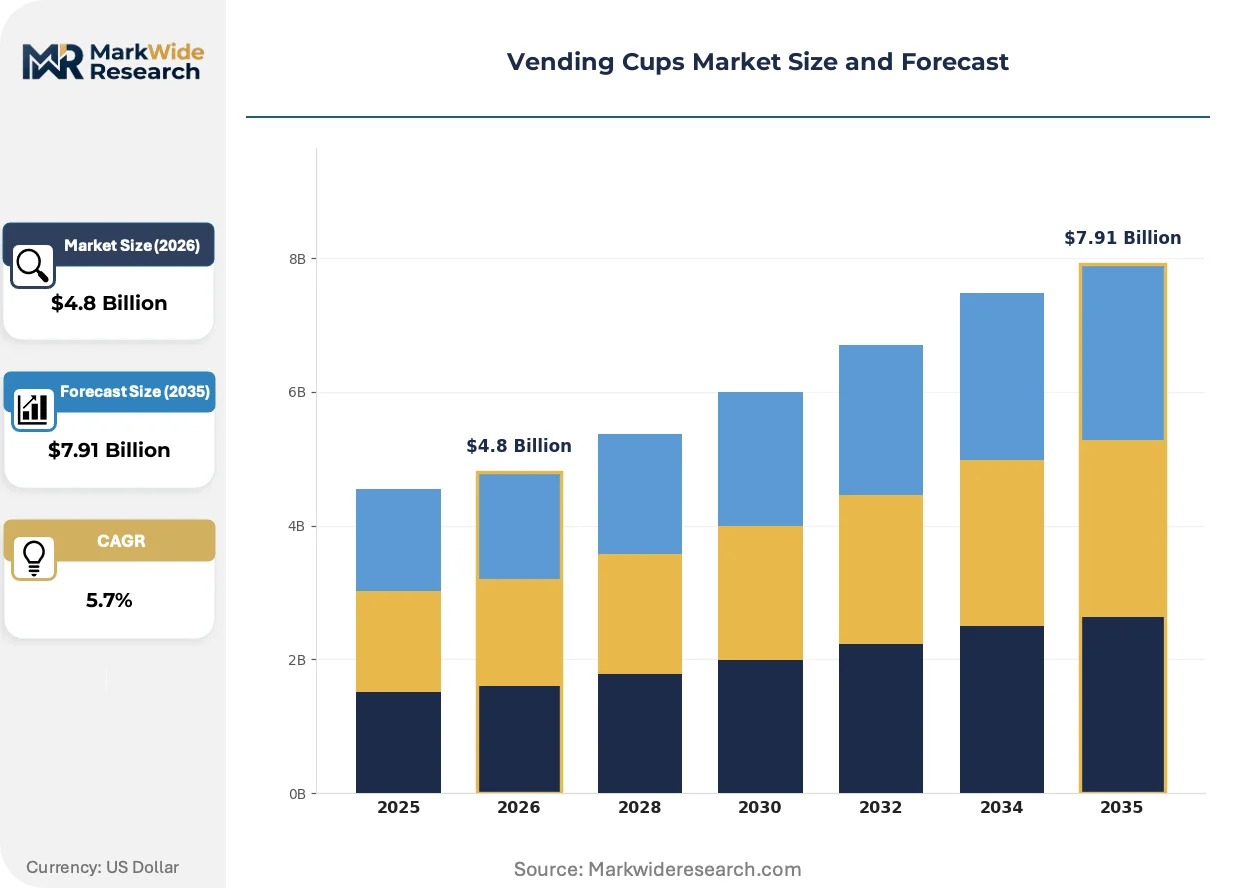
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Compostable, Biodegradable Material: Plastic, Paper, Foam, Glass Size: Small, Medium, Large, Extra Large End User: Offices, Schools, Malls, Gyms |
| Companies Covered | Dart Container Corporation, Huhtamaki Oyj, Georgia-Pacific, Berry Global Inc., International Paper Company, Pactiv Evergreen Inc., Greiner Packaging International GmbH, Coveris Holdings S.A., Graphic Packaging International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vending Cups Market Strategic Shifts
Active material substitution is compressing traditional supply chain relationships as converters, brand owners, and waste managers negotiate new value recovery mechanisms for single-use beverage containers.
PLA-lined paperboard is expanding into hot beverage applications previously reserved for foam and conventional plastic. Quick-service restaurants and institutional cafeterias in France and the Netherlands are adopting these formats for coffee and tea service. The technology is expanding into vending channels as equipment manufacturers release modular retrofit kits for temperature-stable dispensing.
REACH restrictions on microplastics are accelerating the phase-out of conventional plastic linings in paper cups across European supply chains. Chemical manufacturers face registration burdens for fluorinated barrier coatings previously standard in the industry. Hot beverage vending operators in Germany and Scandinavia are now specifying explicitly PFAS-free cup certifications in tender documents.
Buyer consolidation among facility management firms is compressing supplier rosters and extending contract durations. Sodexo, Compass, and Aramark are centralizing cup procurement across national and regional accounts, displacing fragmented local distributor relationships. This pattern is most visible in the United Kingdom and Ireland where three firms control over sixty percent of outsourced workplace catering contracts.
Vending Cups Market Segmentation
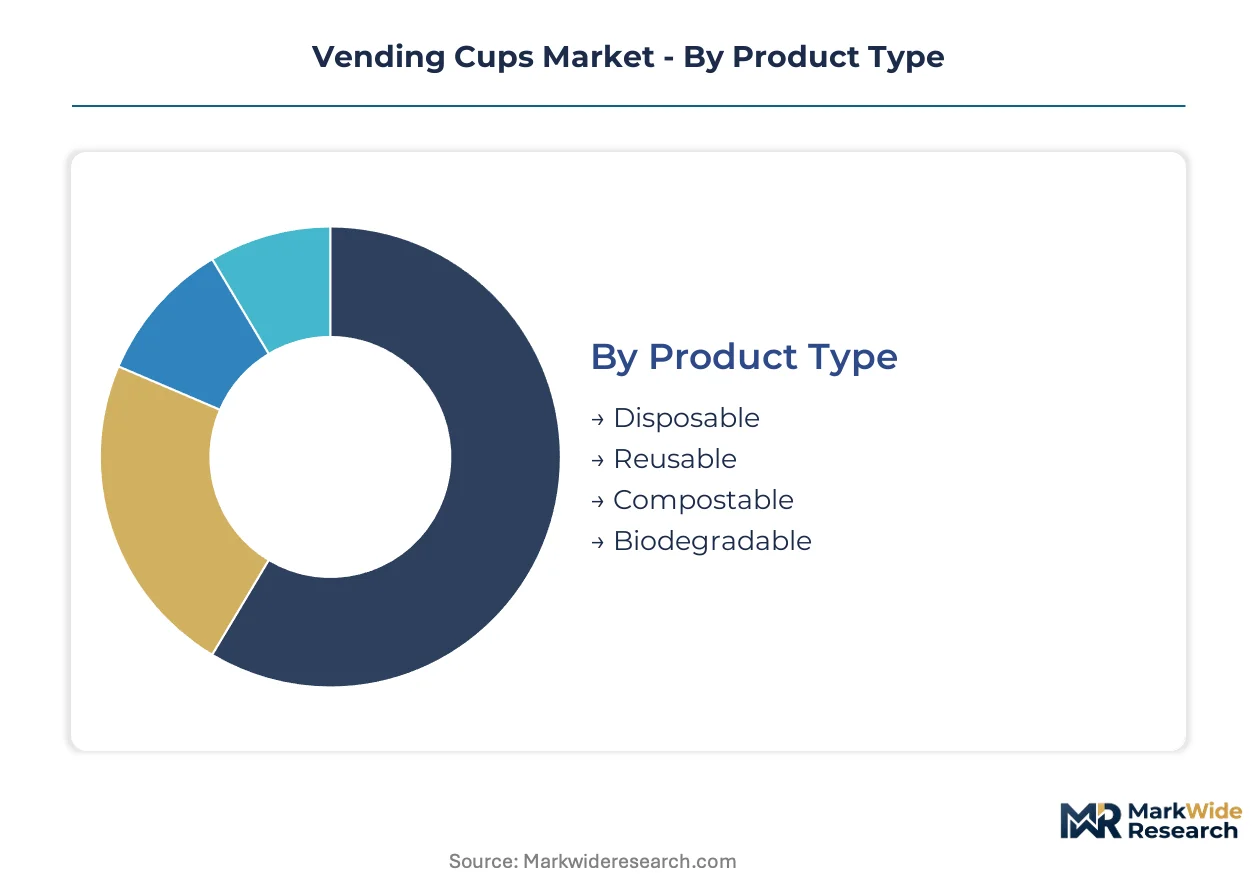
Material choices in vending cups determine equipment compatibility, regulatory compliance exposure, and end-of-life recovery pathways. Procurement managers segment demand across these dimensions to match cup specifications with dispensing infrastructure, beverage temperature profiles, and waste management constraints.
Product Type:
Capital intensity varies sharply across formats, with compostable lines requiring dedicated thermoforming and coating investments that disposable plastic lines avoid.
- Disposable:Conventional single-use formats dominate installed equipment bases through standardized rim diameters and rigidity profiles. Offices in Germany and France generate recurring volume through contracted refreshment services that prioritize supply security over material innovation.
- Compostable:Certified biodegradable substrates command premium positioning where industrial composting infrastructure exists. Demand concentrates in Dutch and Belgian institutional catering contracts mandated by extended producer responsibility schemes under EU Packaging and Packaging Waste Regulation frameworks.
- Reusable:Deposit-return cup systems require reverse logistics infrastructure and washing equipment capital. UK universities pilot closed-loop campus programs embedding these formats into circular economy procurement specifications.
- Biodegradable:Non-certified breakdown claims face tightening scrutiny from ECHA microplastics restrictions. Limited penetration outside markets with explicit certification waivers.
Most installed capacity flows through Disposable formats. Expansion is steepest in Compostable lines.
Material:
Cost tier stratification separates premium fiber-based substrates from commodity resin and foam alternatives.
- Plastic:Thermoformed polypropylene and PET deliver calibrated rigidity for high-speed dispensing mechanisms. Legacy vending fleets across US office parks and Midwest manufacturing facilities maintain procurement preference for proven performance.
- Paper:PLA-lined paperboard expands into hot beverage applications previously reserved for foam. Quick-service channels in France and Netherlands adopt these formats as REACH restrictions accelerate phase-out of conventional plastic linings.
- Foam:Extruded polystyrene retains cost advantage in North American markets despite regulatory pressure. Dart Container's backward integration into resin compounding sustains margin position against substrate substitution.
- Glass:Reusable glass formats occupy niche premium positioning in European workplace catering with deposit infrastructure. Minimal vending channel penetration due to weight and breakage constraints.
Paper material adoption climbs fastest in European supply chains. Plastic retains volume concentration in North American equipment fleets.
Size:
Application-driven demand clusters around specific volume calibrations tied to beverage categories and consumption occasions.
- Medium:8-12 ounce formats match standard coffee and tea serving sizes across office refreshment programs. German facility management firms centralize procurement around this specification for equipment fleet standardization.
- Large:16-20 ounce capacities serve extended consumption occasions in gyms and transportation hubs. UK rail station vending operators specify these formats for commuter morning coffee procurement.
- Small:6-7 ounce espresso and specialty beverage formats concentrate in Italian and Spanish workplace catering with established coffee culture infrastructure.
- Extra Large:24+ ounce formats align with fountain beverage and iced coffee demand in US mall and cinema vending locations. Limited European adoption due to portion regulation trends.
Medium size commands the broadest equipment compatibility. Large format expansion tracks gym and transit hub vending installation growth.
End User:
Customer type determines contract structure, with recurring institutional accounts contrasting against transactional episodic demand.
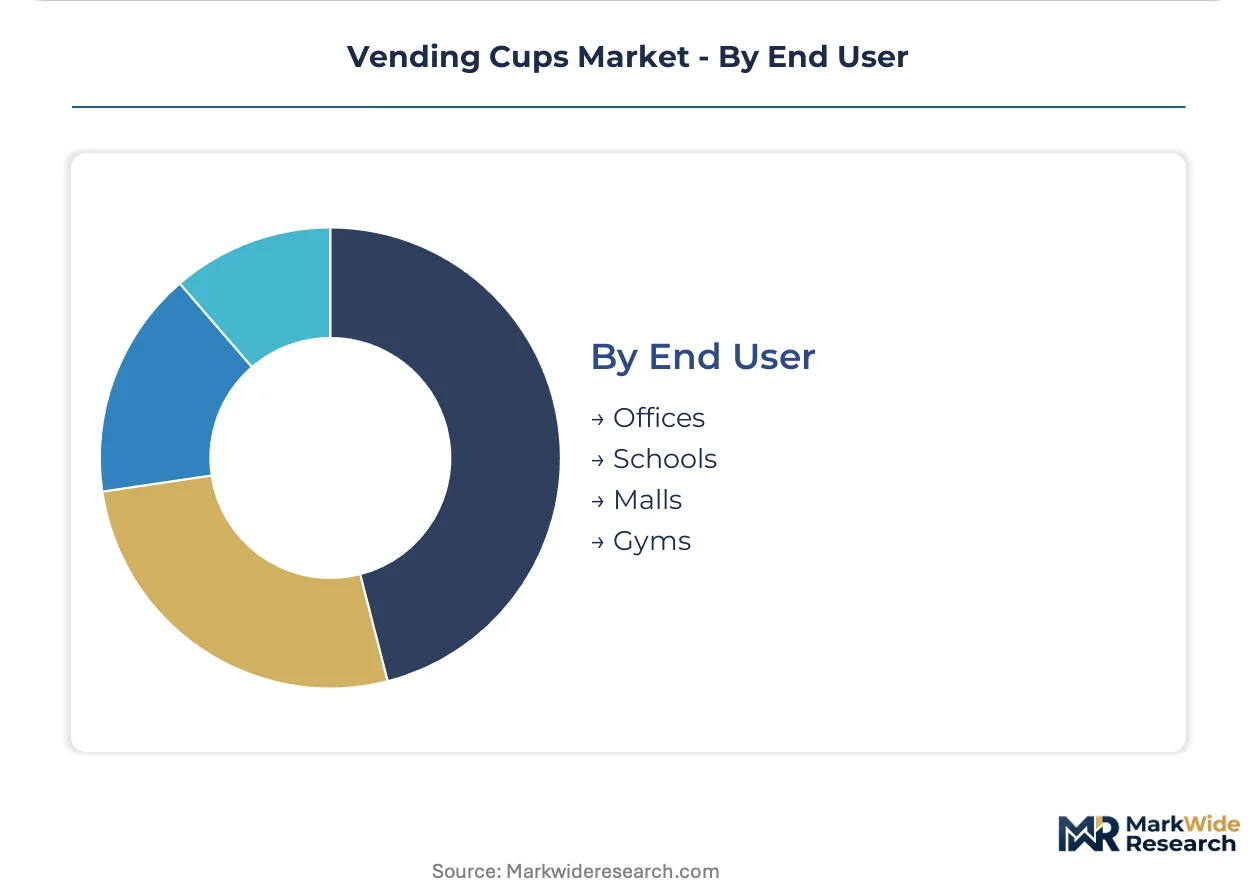
- Offices:Contracted refreshment services generate predictable replacement cycles with standardized format requirements. Sodexo, Compass, and Aramark consolidate procurement across national accounts in UK and Ireland markets.
- Schools:K-12 and university catering programs face divergent procurement constraints. US K-12 districts prioritize cost minimization while UK higher education pilots circular cup-as-a-service models.
- Malls:High-traffic retail environments produce volume spikes with lower switching costs and price sensitivity. Equipment retrofit requirements complicate material transitions during peak replacement cycles.
- Gyms:Health-conscious positioning drives preference for compostable and paper-based alternatives in premium fitness chains. California and Pacific Northwest markets lead substrate substitution due to regional composting infrastructure availability.
Office end users anchor procurement volume concentration. Gym segment expansion tracks fastest as wellness positioning drives material upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's institutional procurement mandates outpace United States office refreshment volume, while China's molded fiber capacity expansion reshapes material flows across Pacific supply chains.
Germany
Public sector catering contracts now mandate plastic-free serviceware, creating dedicated demand channels for certified compostable cup suppliers. The EU Single-Use Plastics Directive enforces extended producer responsibility schemes with fee structures favoring fiber-based alternatives. Bavarian packaging converters are retooling thermoforming lines to serve institutional clients across the DACH region.
United States
Corporate office refreshment services generate recurring procurement volumes with predictable replacement cycles for standardized cup formats. FDA food-contact substance compliance governs domestic manufacturing while state-level plastic bans create fragmented regulatory patchworks. Southeast pulp-to-cup manufacturing clusters in Georgia and Alabama extend integrated production control across institutional supply chains.
China
Molded fiber production capacity is decoupling from traditional plastic cup supply chains as converters retool for compostable formats. SAMR-enforced GB standards for food packaging materials create compliance burdens for export-oriented manufacturers. Yangtze River Delta thermoforming hubs are redirecting capacity toward biodegradable substrates for European institutional buyers.
United Kingdom
Facility management consolidation has concentrated procurement among three firms controlling over sixty percent of outsourced workplace catering contracts. Pending revisions to the EU Packaging and Packaging Waste Regulation will determine long-term material technology adoption. UK universities are piloting cup-as-a-service models with deposit-return systems embedding vending cups into circular economy infrastructure.
France
Quick-service restaurant and institutional cafeteria adoption of PLA-lined paperboard is accelerating phase-out of conventional plastic linings. REACH restrictions on microplastics and fluorinated barrier coatings are reshaping chemical supplier relationships. Paris-based catering operators now specify explicitly PFAS-free cup certifications in tender documentation for hot beverage vending programs.
Vending Cups Market Competitive Environment
North American producers anchor one tier; European specialists hold differentiated positions in fiber-based and compostable formats. The vendor base clusters around three strategic archetypes: integrated pulp-to-cup manufacturers, resin-compounding foam specialists, and thermoforming converters with barrier coating capabilities. Competitive moves concentrate on capacity retooling for biodegradable substrates and strategic partnerships with facility management consolidators.
Within the integrated manufacturing tier, Dart Container Corporation and Georgia-Pacific exemplify divergent material strategies—one sustaining resin-compounding advantages, the other extending pulp-based production control. Huhtamaki Oyj occupies a position bridging European thermoforming infrastructure with institutional biodegradable output. These three anchors represent the structural split between foam retention, paper expansion, and compostable conversion that defines current competitive positioning.
| Leading Market Players |
|---|
| Dart Container Corporation |
| Huhtamaki Oyj |
| Georgia-Pacific |
| Berry Global Inc. |
| International Paper Company |
| Pactiv Evergreen Inc. |
| Greiner Packaging International GmbH |
| Coveris Holdings S.A. |
| Graphic Packaging International LLC |
| Others |
Value Chain & Pricing Dynamics
Facility management consolidators in the United Kingdom and Ireland anchor procurement volume concentration, translating buyer scale into contract-based long-term offtake pricing with standardized format premiums. This concentration compresses margin capture for converters lacking backward integration into pulp or resin production.
Pricing Analysis
Capacity additions in China's Yangtze River Delta thermoforming hubs are reshaping price floors for molded fiber substrates as converters retool for European institutional buyers. Three-tier pricing structure across certified compostable, PLA-lined paperboard, and conventional plastic tiers separates premium fiber-based formats from commodity foam alternatives. Cost compression in polystyrene resin tiers is intensifying because Dart Container's captive compounding operations sustain margin position against substrate substitution. US K-12 school districts exhibit highest price sensitivity due to budget-constrained procurement, while German public sector catering contracts show lowest sensitivity given plastic-free mandate compliance requirements.
Supply Chain Analysis
Pulp fiber supply rests on southeastern United States timberland operations and Nordic bleached kraft producers, with thermoforming equipment concentrated in Germany, China, and the Netherlands. Raw material dependencies include food-grade polystyrene resin, PLA biopolymer from NatureWorks and TotalEnergies Corbion facilities, and aqueous barrier coatings subject to REACH fluorination restrictions. Single-source vulnerability concentrates in PLA supply given limited global production capacity against accelerating European demand. Distribution runs through facility management consolidators Sodexo, Compass, and Aramark, displacing fragmented local distributor relationships across national catering accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's expanding molded fiber capacity and Europe's regulatory-mandated material transitions, with cost differentials in barrier coating chemistry and composting infrastructure access driving margin dispersion.
For Market Incumbents: Deepen backward integration into pulp supply to defend margin position against Georgia-Pacific's southeastern timberland control, while accelerating BPI certification timelines to preempt TÜV OK validation bottlenecks freezing working capital. Prioritize equipment retrofit partnerships with vending OEMs to lock in format standardization before 12-15 year replacement cycles complete. For New Entrants and Emerging Players: US gym chains with wellness-positioned procurement represent the most penetrable buyer archetype given compostable preference and Pacific Northwest composting infrastructure availability. Target California and Pacific Northwest markets with certified fiber-based formats, leveraging regional composting facility coverage absent in Midwest and Southeast markets. Pursue direct relationships with premium fitness operators bypassing consolidated facility management channels. For Investors and Strategic Acquirers: Packaging converters with thermoforming infrastructure and barrier coating capabilities are the most active acquirer in this space, seeking molded fiber technology access for EU institutional contract qualification. Long-term viability hinges on composting infrastructure buildout pace relative to certification mandate expansion. Monitor industrial composting facility permitting acceleration in US coastal states as inflection indicator for biodegradable cup demand realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Georgia-Pacific's timberland control secures cost position against resin volatility. |
| Composting Infrastructure Partnership | UK university deposit-return pilots embed cups into circular economy procurement. |
| Barrier Coating Chemistry Convergence | Bio-based moisture barriers expand temperature performance for Huhtamaki's European output. |
| Equipment Retrofit Kit Development | Modular dispensing adaptations unlock PLA-lined paperboard for legacy vending fleets. |
| Certification Acceleration Investment | BPI and TÜV OK validation compression reduces working capital freeze in inventory. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at thermoforming converters, procurement leads at facility management firms, distribution channel partners, and technical R&D directors in barrier coating chemistry with secondary validation against customs trade data, EU Packaging and Packaging Waste Regulation filings, SEC 10-K disclosures, and composting facility permitting databases. Bottom-up volume modeling and top-down market sizing triangulated across these sources.
Segment-weighting applied material type, end-user category, and geographic regulatory cluster dimensions across the projection horizon, with CAGRs derived from installed equipment base turnover rates and mandated material transition timelines. Forecast inputs incorporated EU Single-Use Plastics Directive enforcement schedules and industrial composting facility coverage expansion trajectories.
Underlying measurement precision varies by segment; compostable and reusable categories carry tighter precision than biodegradable given certification standardization, while forecasts reflect assumptions on regulatory enforcement consistency and infrastructure buildout pace. A small set of triggers—REACH fluorination restriction expansion, state-level US plastic ban adoption, and PLA production capacity additions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Bullet Bottles Market
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Indonesia Plastic Bottles Market
Beverage Packaging
Self-Chilling Can Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
North America Soft Drinks Packaging Market
Beverage Packaging
French Square Bottle Market
Beverage Packaging
Bottled Water Packaging Market
Beverage Packaging
Media Bottles Market
Beverage Packaging
Ice Transport Buckets Market
Beverage Packaging
North America Beverage Packaging Market
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Cup Filler Market
Beverage Packaging
Bottle Shippers Market