
 Multicomponent Bottle Market | 2026-2036
Multicomponent Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Multicomponent Bottle Market Analytics
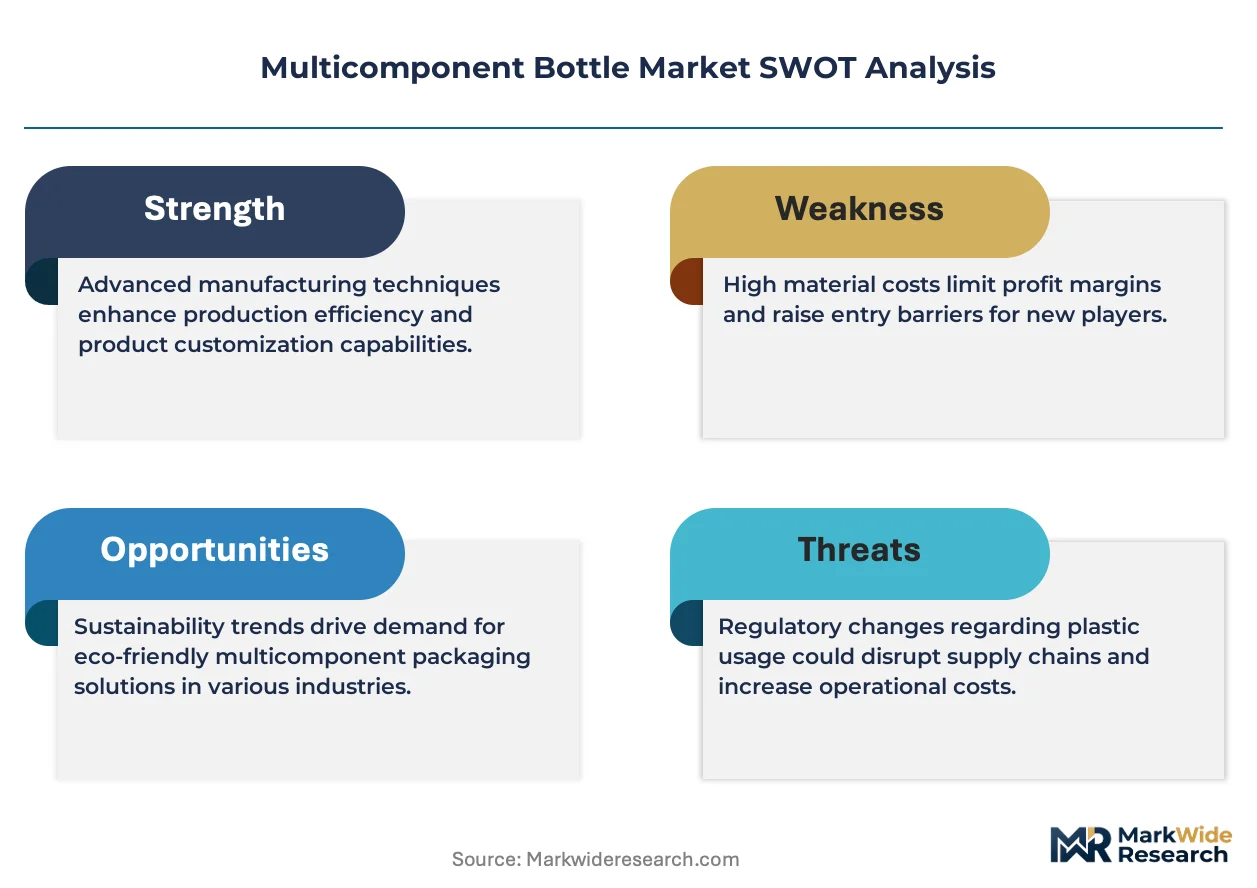
REACH compliance is rebalancing the cost-of-entry calculus for European multicomponent bottle suppliers, forcing reformulation of adhesives and barrier coatings. Amcor plc leverages its integrated film-to-bottle manufacturing network to sustain cost advantages across pharmaceutical and personal care accounts. Gerresheimer AG anchors its competitive position through specialized glass-plastic hybrid competence for high-value drug delivery systems. Berry Global Group, Inc. competes on scale, operating one of the broadest thermoforming and injection molding footprints in North America.
A multicomponent bottle combines two or more distinct materials, typically a primary vessel wall of polyethylene terephthalate or borosilicate glass bonded to a secondary functional layer such as ethylene vinyl alcohol or metallized film, assembled through co-injection molding, insert molding, or adhesive lamination to achieve oxygen barrier, UV protection, or controlled dispensing. Plastic material types dominate current volume owing to cost efficiency and design flexibility, though composite constructions are gaining fastest in pharmaceutical end uses where moisture and light sensitivity command premium positioning. Small volume capacity segments lead in pharmaceutical applications, while medium and large formats anchor beverage and household product demand with established margin pools.
The European Chemicals Agency enforces substance restrictions under REACH that directly limit certain colorants and plasticizers in food-contact and cosmetic multicomponent bottles, while the FDA maintains extractables and leachables testing protocols that govern pharmaceutical bottle approval timelines in the United States. Germany's Federal Institute for Risk Assessment coordinates with ECHA on migration limit harmonization, creating a dual compliance burden for suppliers serving both markets. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to regionalize formulation platforms or pursue universal material certifications that bridge regulatory jurisdictions.
Market Dynamics
The EU Single-Use Plastics Directive is forcing material transitions across European multicomponent bottle supply chains, compelling suppliers to requalify barrier adhesives and secondary layers for recycled content integration while maintaining pharmaceutical-grade performance standards.
Growth Catalysts
- REACH substance restrictions:ECHA enforcement is accelerating reformulation of barrier coatings and colorants, creating competitive separation for compliant suppliers in cosmetic and food-contact segments.
- Paris-Saclay cosmetics corridor:Concentrated demand from French premium skincare manufacturers is pulling specialized glass-plastic hybrid capacity toward high-value drug delivery and personal care applications.
- Co-injection molding advancement:Process refinements enabling thinner EVOH barrier layers are reducing material intensity while preserving oxygen transmission specifications for sensitive formulations.
Market Restraints
- Recycled PET feedstock volatility:Collection infrastructure gaps and quality inconsistency in European rPET supply are inflating input costs and constraining scale-up of sustainable multicomponent constructions.
- German Federal Institute for Risk Assessment migration limits:Dual compliance burden with BfR and FDA extractables protocols extends qualification timelines and raises technical documentation costs for cross-Atlantic suppliers.
- Glass-plastic hybrid technical ceiling:Thermal expansion coefficient mismatches between borosilicate and polypropylene layers limit sterilization cycle durability in high-value pharmaceutical applications.
Strategic Opportunities
- Extended producer responsibility frameworks:Emerging EPR schemes in France and Germany are creating first-mover advantages for suppliers with closed-loop collection infrastructure and design-for-recycling capabilities.
- Small-volume pharmaceutical formats:Underpenetrated biologics and orphan drug packaging in European markets presents white space for specialized barrier and controlled-dispensing solutions.
- Metallized film-EVOH convergence:Hybrid oxygen and UV barrier technologies are opening premium positioning in light-sensitive nutraceutical and cosmetic segments previously served by amber glass.
Industry Challenges
- Adhesive lamination technician scarcity:Specialized workforce gaps in co-extrusion and insert molding operations are constraining capacity expansion and elevating training costs for European converters.
- ISO 15378 certification timelines:Pharmaceutical primary packaging quality management system audits are extending 6-12 months, delaying market entry for new multicomponent constructions.
- Legacy thermoforming asset integration:Retrofitting established injection molding footprints for multilayer co-injection requires substantial capital redeployment and process validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multicomponent Bottle Market |
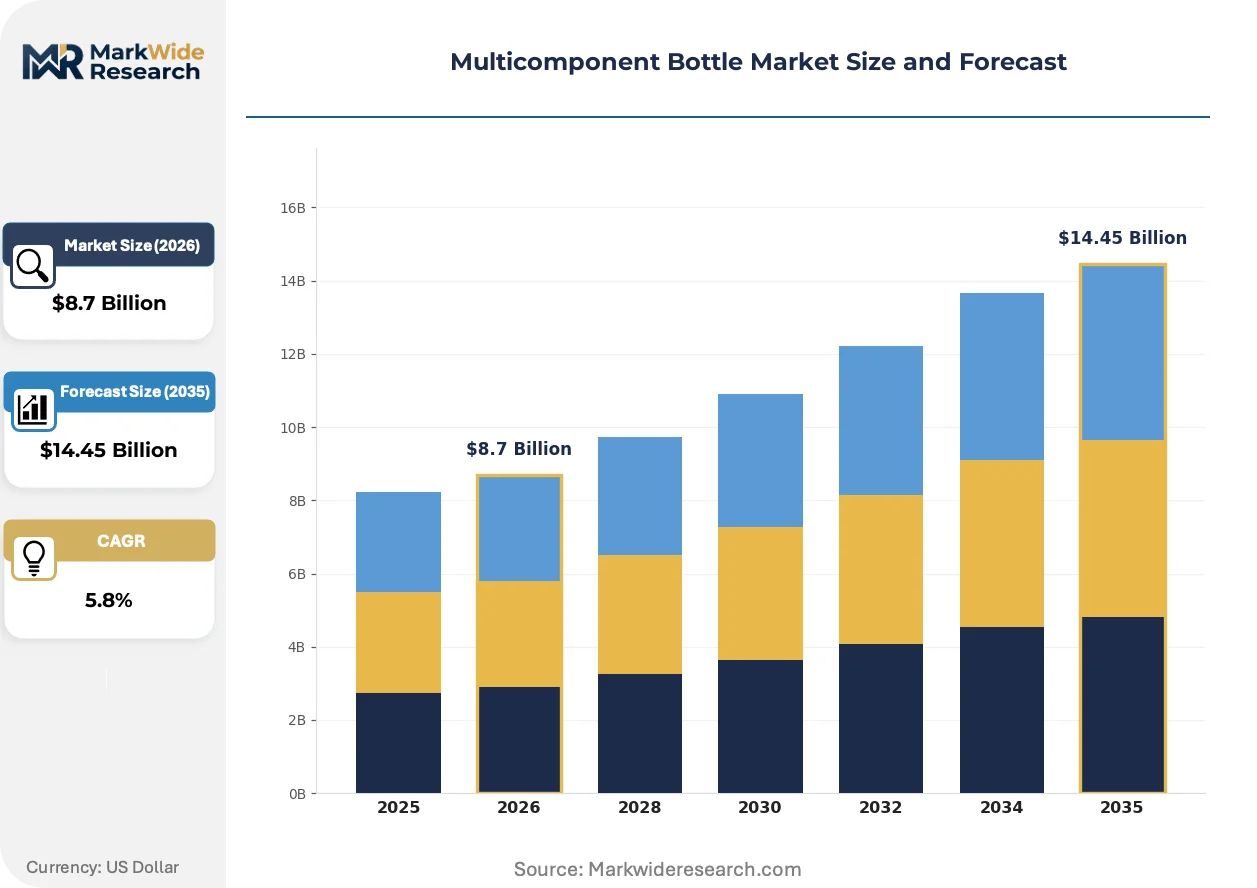
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Plastic, Metal, Composite Closure Type: Screw Cap, Snap On, Cork, Piston End User: Beverage, Pharmaceuticals, Personal Care, Household Products Volume Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Amcor plc, Gerresheimer AG, ALPLA Werke Alwin Lehner GmbH & Co KG, Berry Global Group, Inc., Silgan Holdings Inc., AptarGroup, Inc., Greif, Inc., Stevanato Group S.p.A., West Pharmaceutical Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multicomponent Bottle Market Evolving Landscape
Active barrier technologies and circular material platforms are restructuring competitive positioning in multicomponent bottle manufacturing, with regulatory compliance and end-use performance requirements driving convergence between previously distinct material science domains.
Ethylene vinyl alcohol copolymer is integrating with bio-based feedstocks to maintain oxygen barrier performance while reducing fossil-derived content. Pharmaceutical and personal care formulators in Germany and France are qualifying these constructions at accelerated pace. This integration is compressing the cost premium between conventional and sustainable barrier layers, forcing mid-tier suppliers to accelerate material platform transitions or cede premium accounts.
REACH Annex XVII substance restrictions are tightening migration limits for plasticizers and colorants in food-contact and cosmetic applications. European converters are reformulating adhesive systems and secondary layers to maintain compliance while preserving bond strength and barrier integrity. Personal care segments serving the Paris-Saclay manufacturing corridor are absorbing the highest compliance costs, with some suppliers regionalizing formulation platforms rather than pursuing universal certifications.
Brand procurement of multicomponent bottles is consolidating toward integrated film-to-bottle manufacturers capable of delivering certified recycled content with documented chain-of-custody. Direct sourcing relationships are displacing distributor-mediated transactions in premium skincare and pharmaceutical verticals. This concentration is most visible in Germany, where personal care brands are qualifying single-source suppliers for entire premium product lines to reduce compliance verification burden.
Multicomponent Bottle Market Segmentation
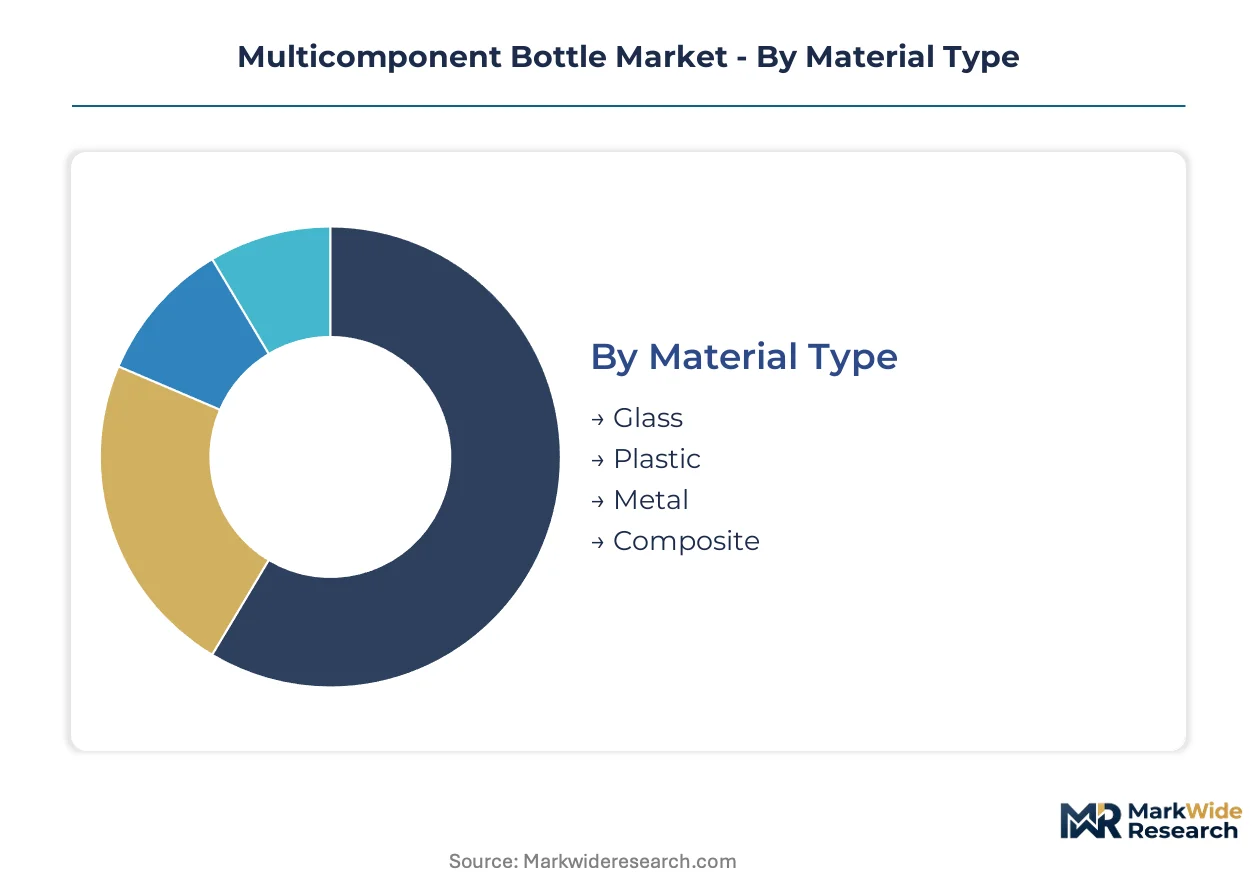
Material composition and closure mechanics determine barrier performance, regulatory pathway, and manufacturing economics for multicomponent bottle procurement. End-use specifications and volume requirements further stratify supplier capabilities across pharmaceutical, cosmetic, and beverage verticals.
Material Type:
Buyers select base materials based on oxygen transmission requirements, sterilization compatibility, and recycled content mandates under ECHA substance restrictions.
- Glass:Borosilicate constructions deliver near-zero oxygen permeability and thermal shock resistance for high-value drug delivery systems. Demand concentrates in France's Paris-Saclay cosmetics corridor where premium skincare brands specify glass-plastic hybrids for UV-sensitive formulations.
- Plastic:PET and polypropylene multilayer constructions dominate volume through co-injection molding scalability and design flexibility. German personal care brands are accelerating procurement of rPET-integrated barriers to meet EU Single-Use Plastics Directive thresholds.
- Metal:Aluminum-laminated constructions provide absolute light and gas barriers for oxygen-sensitive nutraceuticals.
- Composite:Glass-polymer and film-EVOH hybrids command premium positioning where single-material performance falls short.
Volume sits with Plastic; growth tilts toward Composite.
Closure Type:
Sealing mechanism selection hinges on dispensing precision, child-resistance mandates, and line speed compatibility.
- Screw Cap:Threaded polypropylene closures with induction seals dominate pharmaceutical and beverage applications requiring resealability and tamper evidence.
- Snap On:Press-fit designs accelerate household product filling lines and reduce cap application torque variability.
- Cork:Natural and synthetic cork composites persist in premium wine and spirits where oxygen ingress control follows defined maturation curves.
- Piston:Airless pump mechanisms with sliding piston seals are climbing fastest in cosmetic airless packaging for preservative-free formulations.
Standardization favors Screw Cap; dispensing innovation favors Piston.
End User:
Regulatory intensity and performance specifications create distinct procurement patterns across consumption categories.
- Beverage:Carbonated and still drinks drive high-throughput demand for EVOH-barrier PET with recycled content integration.
- Pharmaceuticals:Extractables and leachables protocols under FDA and EMA guidelines extend qualification timelines for primary packaging. Small-volume formats for biologics and orphan drugs are expanding most quickly as specialty drug pipelines mature.
- Personal Care:Premium skincare lines in Germany are consolidating supplier relationships to reduce REACH compliance verification burden.
- Household Products:Bleach and solvent containers prioritize chemical resistance and child-resistant closure integration over barrier sophistication.
Procurement scale concentrates in Beverage; margin expansion concentrates in Pharmaceuticals.
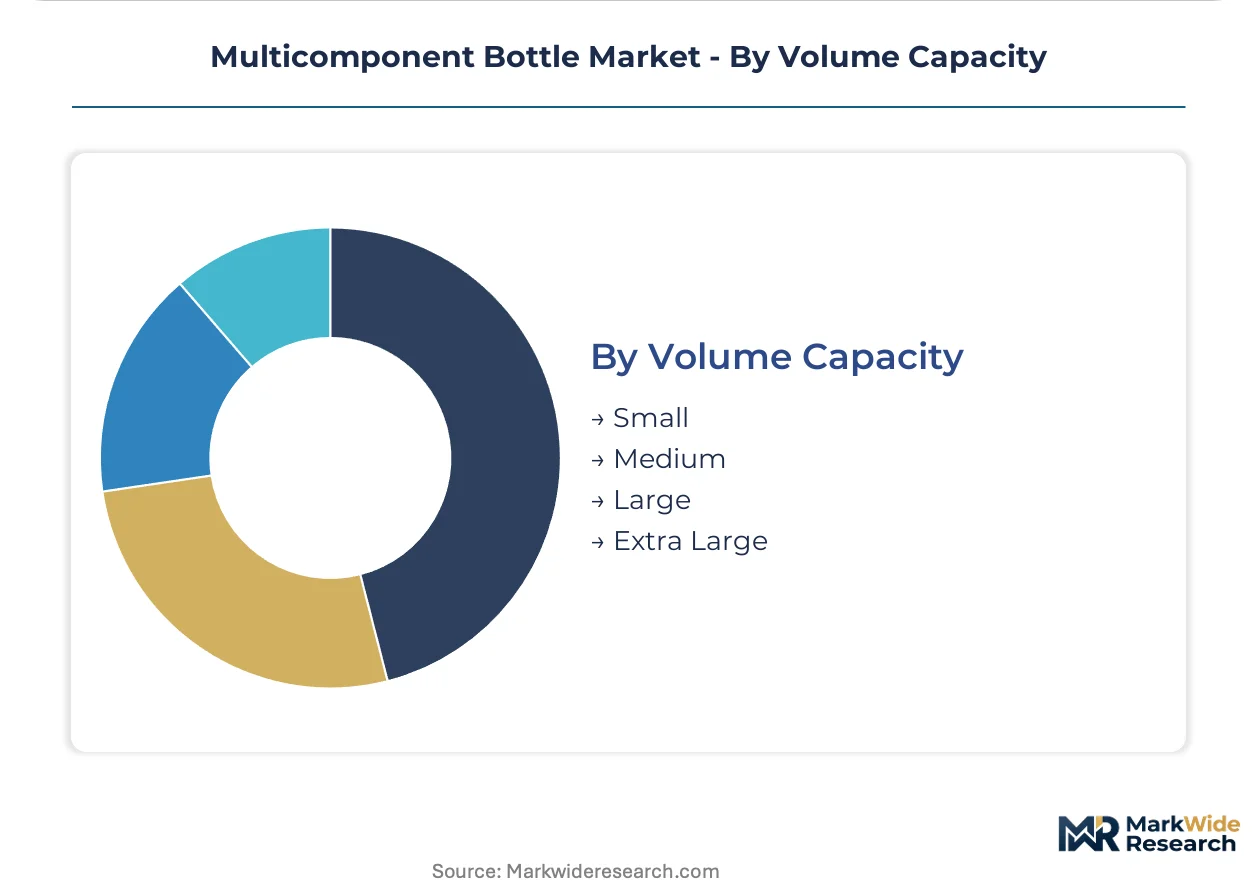
Volume Capacity:
Format sizing aligns with dosing regimens, retail channel requirements, and consumption occasion patterns.
- Small:Sub-50ml formats serve pharmaceutical unit-dose and travel-size cosmetic segments where portability and precise dispensing command premium positioning.
- Medium:100-500ml containers anchor mass-market beverage and personal care demand with established filling infrastructure and distribution economics.
- Large:Family-size household product and beverage formats optimize per-unit packaging cost through scale economies.
- Extra Large:Institutional and refill applications concentrate in commercial cleaning and food service verticals.
Unit economics favor Medium; specialty positioning favors Small.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris-Saclay's cosmetics manufacturing corridor concentrates premium skincare packaging demand, while Germany's personal care brands accelerate multicomponent bottle procurement under EU Single-Use Plastics Directive compliance timelines.
Germany
Federal Institute for Risk Assessment migration limits are extending qualification timelines for cross-Atlantic suppliers. REACH Annex XVII substance restrictions compel reformulation of barrier adhesives and colorants. Personal care brands in Hamburg and Berlin are consolidating supplier relationships to reduce compliance verification burden for premium skincare lines.
France
ANSM enforcement of pharmaceutical packaging standards intersects with ECHA substance restrictions to create dual regulatory pressure. The Paris-Saclay cosmetics corridor pulls specialized glass-plastic hybrid capacity toward high-value drug delivery applications. Île-de-France manufacturers are regionalizing formulation platforms rather than pursuing universal certifications.
United States
FDA extractables and leachables testing protocols govern pharmaceutical bottle approval timelines for European suppliers entering the market. Extended producer responsibility frameworks in California and New York are creating demand for closed-loop collection infrastructure. Midwest thermoforming operations are retrofitting established injection molding footprints for multilayer co-injection capacity.
Italy
Lombardy-based converters face adhesive lamination technician scarcity constraining capacity expansion. CE marking requirements for medical device packaging intersect with pharmaceutical-grade performance standards. Milan's industrial corridor hosts specialized operations serving orphan drug and biologics packaging segments.
Switzerland
Swissmedic pharmaceutical packaging regulations maintain stringent quality management system requirements. Basel's pharmaceutical cluster drives demand for small-volume formats with specialized barrier and controlled-dispensing solutions. Swiss converters leverage proximity to German and French markets to serve cross-border premium accounts.
Multicomponent Bottle Market Competitive Landscape
European producers anchor the compliance-intensive tier; North American specialists hold scale advantages in high-throughput beverage and household segments. The vendor base stratifies across integrated film-to-bottle manufacturers, specialized glass-plastic hybrid fabricators, and broad thermoforming operators. Three archetypes dominate: integrated multilayer converters with captive resin compounding, pharmaceutical-grade specialists with ISO 15378 certification, and scale-driven commodity producers. Competitive moves concentrate on backward integration into recycled PET feedstock sourcing and technology licensing for co-injection molding process refinements.
Within the integrated converter tier, Amcor plc and Berry Global Group, Inc. occupy positions exemplifying film-to-bottle manufacturing network advantages. Among pharmaceutical-grade specialists, Gerresheimer AG represents the glass-plastic hybrid competence archetype for high-value drug delivery systems. These three companies anchor the competitive structure, with Amcor and Berry exemplifying scale-driven positioning across personal care and beverage verticals, while Gerresheimer sits within the premium-tier vector serving regulatory-intensive pharmaceutical accounts.
| Leading Market Players |
|---|
| Amcor plc |
| Gerresheimer AG |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Berry Global Group, Inc. |
| Silgan Holdings Inc. |
| AptarGroup, Inc. |
| Greif, Inc. |
| Stevanato Group S.p.A. |
| West Pharmaceutical Services, Inc. |
| Others |
Value Network & Pricing Analysis
Recycled PET feedstock costs cascade through multicomponent bottle pricing tiers, with rPET-integrated barrier layers commanding premiums over virgin-material alternatives as EU Single-Use Plastics Directive thresholds tighten procurement specifications across German personal care brands.
Pricing Analysis
Short lead-time premiums separate pharmaceutical-grade suppliers from commodity converters in the multicomponent bottle market, with ISO 15378-certified manufacturers extracting price advantages for accelerated qualification timelines. Pricing stratifies across premium, standard, and economy tiers based on barrier performance certification and volume scale commitments. Cost compression in medium-format beverage segments is intensifying because rPET feedstock volatility inflates input costs for sustainable constructions. Small-volume pharmaceutical buyers show lowest price sensitivity, prioritizing extractables documentation and sterilization compatibility over unit economics.
Supply Chain Analysis
Reverse-logistics flows for post-industrial scrap and post-consumer collection are emerging as competitive differentiators under extended producer responsibility frameworks in France and Germany. Manufacturing gravity centers on Germany, France, and Italy, with Lombardy-based converters facing adhesive lamination technician scarcity. The supply chain draws from EVOH resin, metallized film substrates, and borosilicate glass tubing as critical inputs. Single-source vulnerability in European rPET collection infrastructure poses structural risk. Distribution runs through direct sourcing relationships displacing distributor-mediated transactions in premium skincare and pharmaceutical verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multicomponent bottle market is becoming a vertical-integration race, with backward control over recycled feedstock sourcing and captive barrier film compounding determining margin sustainability.
For Market Incumbents: Anticipate REACH Annex XVII expansion by pre-qualifying bio-based EVOH alternatives and regionalizing formulation platforms to reduce dual-compliance burden with BfR and FDA protocols. Lock in long-term rPET supply agreements before collection infrastructure gaps widen feedstock cost spreads. Defensive consolidation through ISO 15378 certification investment protects pharmaceutical account retention against emerging glass-plastic hybrid specialists. For New Entrants and Emerging Players: Enter via orphan drug and biologics packaging white space in Swiss and Italian markets, where small-volume format demand outpaces specialized barrier capacity. Target Paris-Saclay cosmetics corridor accounts with metallized film-EVOH hybrid constructions for UV-sensitive premium skincare. Pursue co-injection molding technology licensing as primary go-to-market angle rather than capital-heavy asset acquisition. For Investors and Strategic Acquirers: First-mover EPR scheme participation in France and Germany is the leading indicator that closed-loop collection infrastructure will separate viable acquisition targets from stranded asset risks. Five-to-ten year viability favors integrated film-to-bottle manufacturers with documented chain-of-custody capabilities over standalone converters dependent on spot resin markets. Watch for adhesive lamination technician training program announcements as workforce development signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Sourcing | Captive feedstock supply insulates margin compression from collection infrastructure volatility under EU directive timelines. |
| Co-injection Molding Process Licensing | Technology transfer agreements accelerate capacity deployment without greenfield capital cycles for European converters. |
| ISO 15378 Certification Investment | Pharmaceutical quality management system accreditation extends addressable market into biologics and orphan drug packaging. |
| Regional Formulation Platform Development | BfR-REACH harmonized constructions reduce dual-compliance documentation burden for cross-Atlantic supplier accounts. |
| Extended Producer Responsibility Partnership | Closed-loop collection infrastructure creates defensible positioning under emerging French and German EPR frameworks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with packaging procurement managers at German personal care brands, pharmaceutical quality assurance directors, Italian converter operations heads, and French cosmetics supply chain leads. ECHA substance restriction databases, FDA extractables guidance documents, BfR migration limit notifications, and EU Single-Use Plastics Directive implementation reports provided regulatory trajectory validation. Bottom-up capacity assessments across Paris-Saclay and Lombardy manufacturing corridors were triangulated against top-down demand modeling from beverage, pharmaceutical, and personal care end-use segments.
Data-stream reconciliation across material type, closure mechanism, end-use vertical, volume capacity, and geographic production cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate convergence analysis incorporating co-injection molding adoption curves, REACH compliance cost absorption patterns, and rPET feedstock availability assumptions. Pharmaceutical pipeline maturation for biologics and orphan drugs, alongside EPR scheme rollout schedules in France and Germany, informed sector-specific trajectory adjustments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REACH substance restriction expansion or rPET collection infrastructure investment shortfalls. Forecasts reflect documented assumptions regarding regulatory implementation timelines and material substitution elasticity. Material deviation in ECHA enforcement intensity, BfR-FDA protocol harmonization progress, or EU directive recycled content threshold adjustments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Bamboo Cups Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Foldable Bottles Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Global Beverage Container Market
Beverage Packaging
North America Soft Drinks Packaging Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Graduated Sample Bottle Market
Beverage Packaging
Cup Sleeves Market
Beverage Packaging
Soft Drinks Packaging Market
Beverage Packaging
Beverage Cans Market
Beverage Packaging
Insulated Cup Sleeves Market