
 Sugarcane Bottles Market | 2026-2036
Sugarcane Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Sugarcane Bottles Market Analytics
Subscription-based packaging-as-a-service is repositioning how bottle suppliers monetize relationships with beverage and personal care brands. LYSPACKAGING leverages its European manufacturing base to sustain long-term supply contracts with carbon-conscious retailers. Berry Global anchors North American volume through its extensive blow-molding infrastructure and food-grade certification portfolio. BioPak differentiates by dominating the Australasian hospitality channel with compostable collection systems tied to its bottle offerings.
Sugarcane bottles are containers manufactured from polyethylene derived from bioethanol, typically comprising a plant-based content threshold that meets ASTM D6866 carbon-14 verification standards for renewable material claims. These vessels serve primarily as drop-in replacements for fossil-based PET in liquid packaging applications requiring barrier properties and mechanical durability comparable to conventional plastics. Recyclable bottles currently occupy the largest share of product-type revenue, though biodegradable variants are capturing premium positioning in European personal care segments where industrial composting infrastructure exists. The 500 ml capacity leads beverage deployments, while 1 L formats are gaining traction in household cleaning channels as refill-model adoption spreads.
The US FDA maintains food-contact substance notification requirements for bio-based packaging migrants, while the EU REACH framework governs chemical safety across imported sugarcane-derived resins. Brazil's ANVISA aligns pharmaceutical and cosmetic packaging standards with Mercosur technical regulations, creating a unified compliance pathway for regional exporters. Stakeholders must monitor evolving extended producer responsibility schemes, as these frameworks increasingly assign collection and recycling cost liability directly to packaging originators rather than downstream brand owners.
Market Dynamics
The EU Single-Use Plastics Directive is compressing demand migration from fossil-based PET toward bio-derived polyethylene, with beverage brands accelerating procurement timelines to preempt compliance deadlines and carbon disclosure mandates.
Growth Catalysts
- REACH chemical safety alignment:ECHA's streamlined substance notification for bio-based resins reduces regulatory friction for European importers, accelerating material qualification cycles for personal care packaging.
- Beverage sector procurement mandates:Carbon-neutral pledges by multinational drink brands are converting virgin PET volume to sugarcane-derived alternatives, with refill-model adoption amplifying bottle throughput requirements.
- Brazilian feedstock concentration:Domestic sugarcane ethanol availability supports integrated biopolymer production, yielding cost-competitive resin supply for regional exporters serving Mercosur markets.
Market Restraints
- Ethanol price volatility:Sugarcane crop yields tied to Brazilian rainfall patterns create input cost instability, compressing margin predictability for resin converters.
- Industrial composting infrastructure gaps:Biodegradable bottle variants require specialized collection systems absent in most North American and Asian municipalities, limiting addressable market for premium formats.
- Mechanical recycling incompatibility:Current PET stream sorting equipment cannot distinguish bio-based from fossil-based polyethylene, creating contamination risk that depresses post-consumer resin values.
Strategic Opportunities
- Household cleaning refill channels:Concentrate-to-dilute models in European retail are expanding 1 L format demand, with private-label brands seeking dedicated bio-based packaging supply agreements.
- Extended Producer Responsibility schemes:France's Citeo and Germany's Duales System Deutschland are assigning collection cost liability upstream, creating service-revenue potential for integrated bottle producers.
- Barrier coating convergence:Plasma-enhanced chemical vapor deposition applied to sugarcane PE is extending shelf-life performance into sensitive beverage categories previously reserved for multilayer fossil structures.
Industry Challenges
- ASTM D6866 certification timelines:Carbon-14 verification for renewable content claims requires 4-6 week laboratory turnaround, delaying product launches and contract finalizations.
- Blow-molding equipment retrofit costs:Legacy PET production lines require screw and barrel modifications to process bio-based polyethylene viscosity profiles, demanding capital deployment that mid-scale converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugarcane Bottles Market |
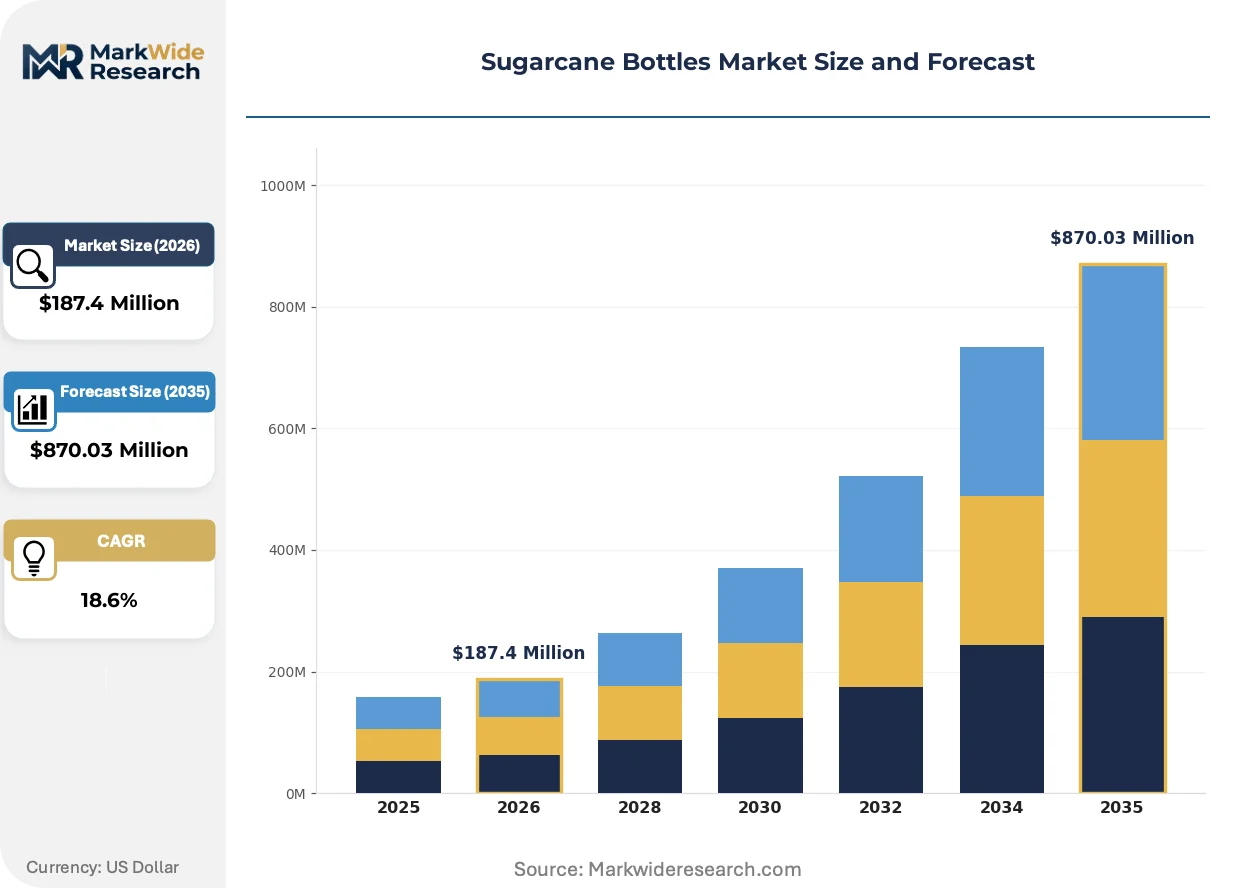
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recyclable Bottles, Biodegradable Bottles, Composite Bottles, Single-Use Bottles End Use Industry: Beverage, Food Packaging, Personal Care, Household Cleaning Capacity: 250 ml, 500 ml, 1 L, 2 L Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Worthy, LYSPACKAGING, Berry Global, Reyoung Corp., SHENZHEN UNIQUE PACK CO., LTD., BioPak, BE O Lifestyle, The Natural Bottle, Bottle Up, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugarcane Bottles Market Evolving Landscape
Material science advances and regulatory compliance automation are converging to reshape competitive positioning in bio-based packaging, with digitization of supply chain traceability emerging as a distinct capability differentiator.
Near-infrared spectroscopy integrated with robotic sorting arms is automating separation of bio-based polyethylene from fossil streams at materials recovery facilities, enabling beverage brands to claim closed-loop recycling rates without manual sorting labor. European waste management operators in the Netherlands and Belgium are piloting these systems at commercial scale. The technology is compressing cost premiums for certified circular packaging by reducing contamination penalties.
REACH Annex XVII restrictions on intentionally added microplastics are compelling personal care brands to eliminate fossil-based glitter and exfoliant beads, with sugarcane-derived carrier resins capturing reformulation volume. ECHA's 2023 guidance clarified bio-based polymer exemptions, accelerating substitution timelines. Cosmetic contract manufacturers in France and Germany are requalifying primary packaging to maintain EU market access.
Subscription-based packaging-as-a-service contracts are displacing traditional spot purchasing in carbon-conscious retail channels, with beverage brands outsourcing bottle supply, collection, and sanitation to specialized operators. Australasian hospitality groups are piloting these arrangements for event catering. The model concentrates volume with integrated producers capable of closed-loop logistics execution.
Sugarcane Bottles Market Segmentation
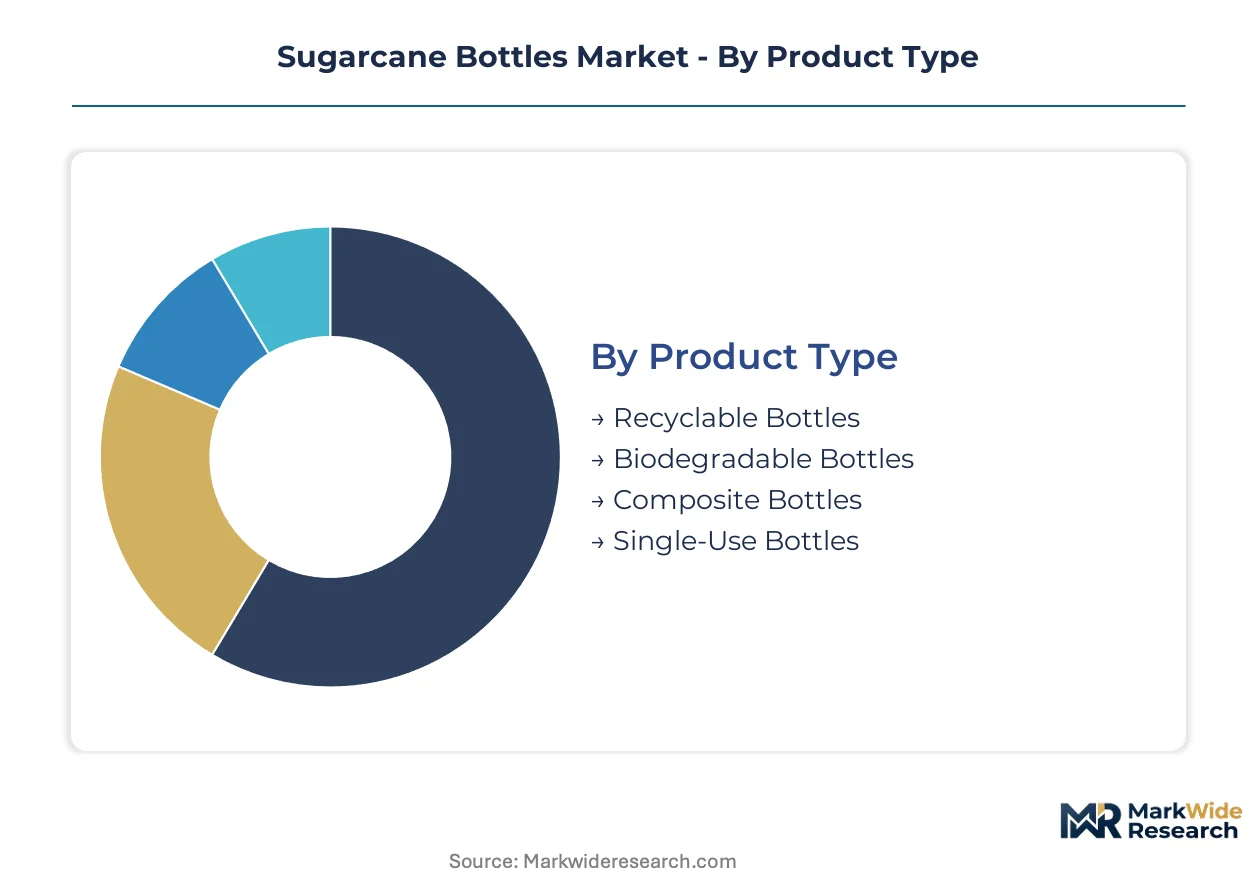
Sugarcane bottle procurement patterns diverge sharply across product formats and end-use specifications, with sustainability certifications and refill-model compatibility driving vendor selection criteria. Understanding these segment boundaries clarifies where resin converters should prioritize capacity investments versus where commodity positioning suffices.
Product Type:
Upgrade cycles from conventional PET vary by biodegradability claims and recycling stream compatibility, with brands reassessing formats as EPR schemes assign collection liability upstream.
- Recyclable Bottles:These vessels maintain mechanical properties identical to fossil-based PET, enabling drop-in replacement without blow-molding equipment modification. Beverage brands in Germany and the Netherlands favor this format for its compatibility with existing deposit-return infrastructure and lower unit premiums versus biodegradable alternatives.
- Biodegradable Bottles:Formulated with PLA or PHA blends certified to industrial composting standards, these containers serve personal care brands seeking to eliminate fossil-derived microplastics under REACH Annex XVII. French and Italian cosmetic manufacturers are the primary demand concentration, though infrastructure gaps in most municipalities constrain addressable volume.
- Composite Bottles:Multilayer structures combining sugarcane PE with barrier coatings extend shelf-life for sensitive beverages.
- Single-Use Bottles:Thin-walled formats for event catering and hospitality channels prioritize cost minimization over durability.
Recyclable bottles sit at the top of the volume ranking, with biodegradable bottles climbing the fastest as personal care brands accelerate reformulation timelines.
End Use Industry:
Customer procurement sophistication spans from price-sensitive commodity buyers to sustainability-mandated corporate purchasers, reshaping how suppliers structure service offerings.
- Beverage:Carbonated soft drink and bottled water brands command the largest absolute volume, with refill-model adoption amplifying bottle throughput requirements. Coca-Cola and PepsiCo procurement mandates are converting virgin PET commitments to bio-based alternatives, though barrier performance limitations exclude some sensitive categories.
- Personal Care:Shampoo and conditioner brands seek sugarcane-derived packaging to substantiate clean beauty claims. L'Oréal and Unilever sustainability targets are requalifying primary packaging specifications across European manufacturing facilities.
- Food Packaging:Edible oil and sauce applications require oxygen barrier properties.
- Household Cleaning:Concentrate-to-dilute refill models are expanding format demand.
Beverage applications dominate current procurement volume, with household cleaning representing the steepest expansion trajectory as European retailers adopt circular refill stations.
Capacity:
Format selection tracks consumption occasion fragmentation, with on-the-go portability clashing against household bulk purchasing economics.
- 500 ml:The standard single-serve beverage format balances portability with production efficiency, dominating vending machine and convenience channel deployments. Brazilian ethanol-to-resin integrated producers optimize for this specification given tooling amortization across high-volume runs.
- 1 L:Household cleaning concentrates and personal care refills favor this intermediate scale, with European private-label brands negotiating dedicated supply agreements for circular refill programs.
- 250 ml:Premium cosmetic and travel-size applications command format premiums.
- 2 L:Family-size beverage and bulk cleaning product formats.
500 ml formats anchor production volume, with 1 L variants gaining share fastest as refill infrastructure spreads across French and German retail networks.
Distribution Channel:
Channel selection determines margin capture versus volume scale, with direct relationships enabling packaging-as-a-service monetization.
- Supermarkets:Mass-market beverage and food packaging volume concentrates here, with Carrefour and Tesco sustainability scorecards influencing supplier qualification. Private-label penetration in European retail creates consolidated procurement leverage that compresses resin converter margins.
- Direct Sales:Integrated producers bypass distributors to capture service revenue from closed-loop collection and sanitation logistics. Australasian hospitality groups are piloting these arrangements for event catering contracts.
- Online Retail:Niche premium and subscription-box formats.
- Specialty Stores:Organic and zero-waste retail channels.
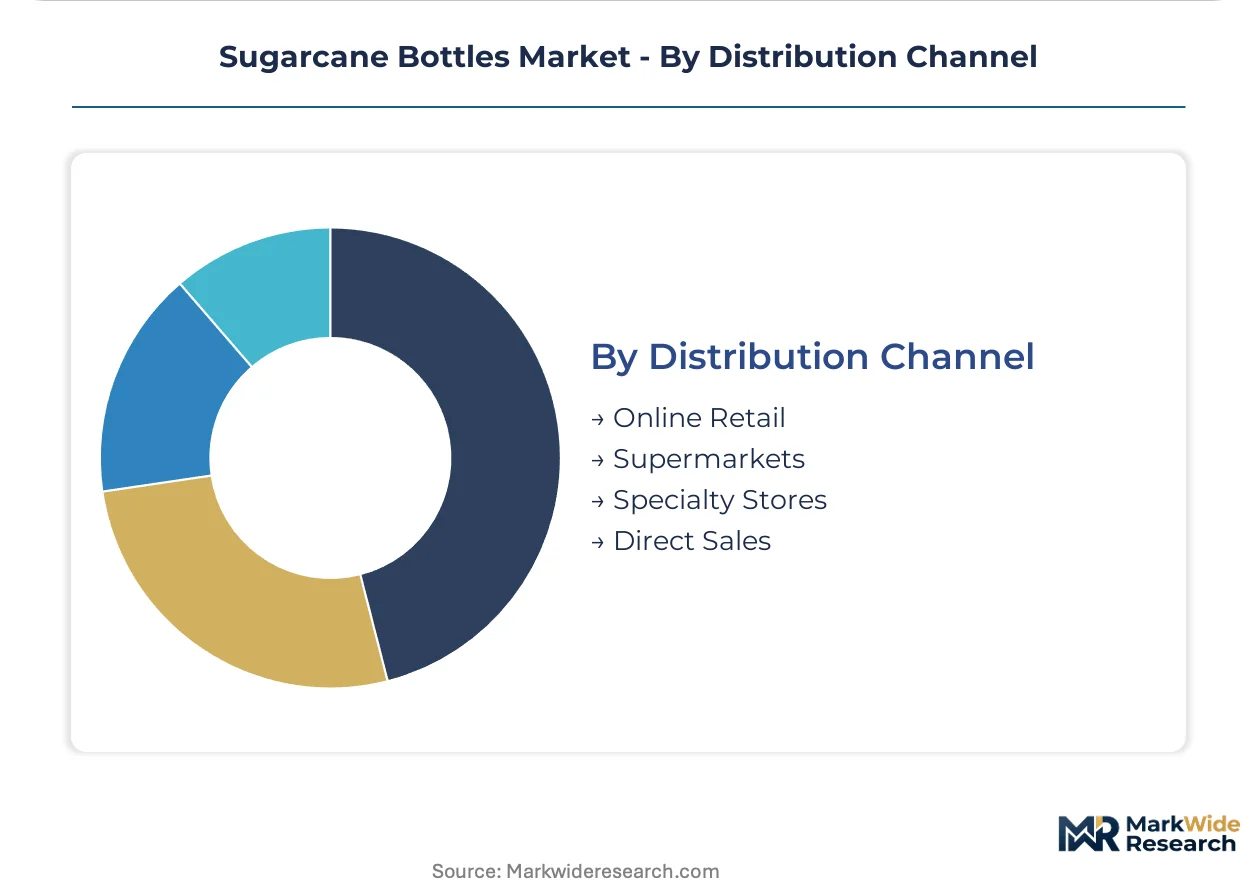
Supermarkets command the largest throughput, with direct sales expanding most quickly as EPR schemes restructure liability allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands integrated biopolymer production while Germany drives regulatory stringency, creating divergent competitive advantages across the value chain.
Brazil
Domestic sugarcane ethanol availability anchors resin cost competitiveness for Mercosur exporters. ANVISA aligns pharmaceutical packaging standards with regional technical regulations, streamlining cross-border approvals. São Paulo state hosts clustered biopolymer production facilities serving beverage brands throughout Latin America.
Germany
Duales System Deutschland assigns upstream collection liability, forcing packaging-as-a-service adoption among resin converters. ECHA's REACH Annex XVII microplastic restrictions accelerate personal care brand reformulation toward bio-based carriers. North Rhine-Westphalia concentrates blow-molding infrastructure retrofitted for bio-polyethylene processing.
United States
FDA food-contact notification requirements shape resin qualification timelines for beverage applications. Berry Global leverages extensive domestic blow-molding capacity to anchor North American volume. Midwest manufacturing corridors host retrofitted production lines serving carbon-neutral procurement mandates from multinational drink brands.
France
Citeo extended producer responsibility schemes restructure cost allocation toward packaging originators. REACH compliance automation reduces qualification friction for cosmetic contract manufacturers. The Paris basin clusters personal care packaging demand as L'Oréal and Unilever accelerate sustainability target timelines.
Australia
Hospitality sector procurement concentrates demand for compostable bottle formats at commercial scale. BioPak dominates channel relationships through integrated collection system offerings. Sydney and Melbourne metropolitan areas pilot subscription-based packaging-as-a-service contracts for event catering applications.
Sugarcane Bottles Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated producers capturing service revenue while commodity converters compete on unit economics. The vendor base organizes around three strategic archetypes: feedstock-integrated biopolymer producers, regional blow-molding specialists, and closed-loop logistics operators. Capacity expansion and strategic partnerships dominate competitive moves as players seek to secure long-term supply contracts from carbon-conscious retailers.
Among Asia-Pacific fabricators, SHENZHEN UNIQUE PACK CO., LTD. and Reyoung Corp. occupy positions within the contract manufacturing tier, supplying standardized formats to brand owners seeking cost-competitive bio-based alternatives. LYSPACKAGING anchors European demand through its manufacturing base and sustained supply relationships with sustainability-mandated retailers. These three exemplify how geographic proximity to demand clusters and regulatory alignment shape competitive positioning in a market where certification timelines and equipment retrofit costs create barriers for mid-scale entrants.
| Leading Market Players |
|---|
| Worthy |
| LYSPACKAGING |
| Berry Global |
| Reyoung Corp. |
| SHENZHEN UNIQUE PACK CO., LTD. |
| BioPak |
| BE O Lifestyle |
| The Natural Bottle |
| Bottle Up |
| Others |
Value Network & Pricing Analysis
Carbon-conscious beverage brand procurement teams concentrate volume with integrated producers, anchoring contract-based long-term offtake as the dominant pricing model across Brazilian and European supply corridors.
Pricing Analysis
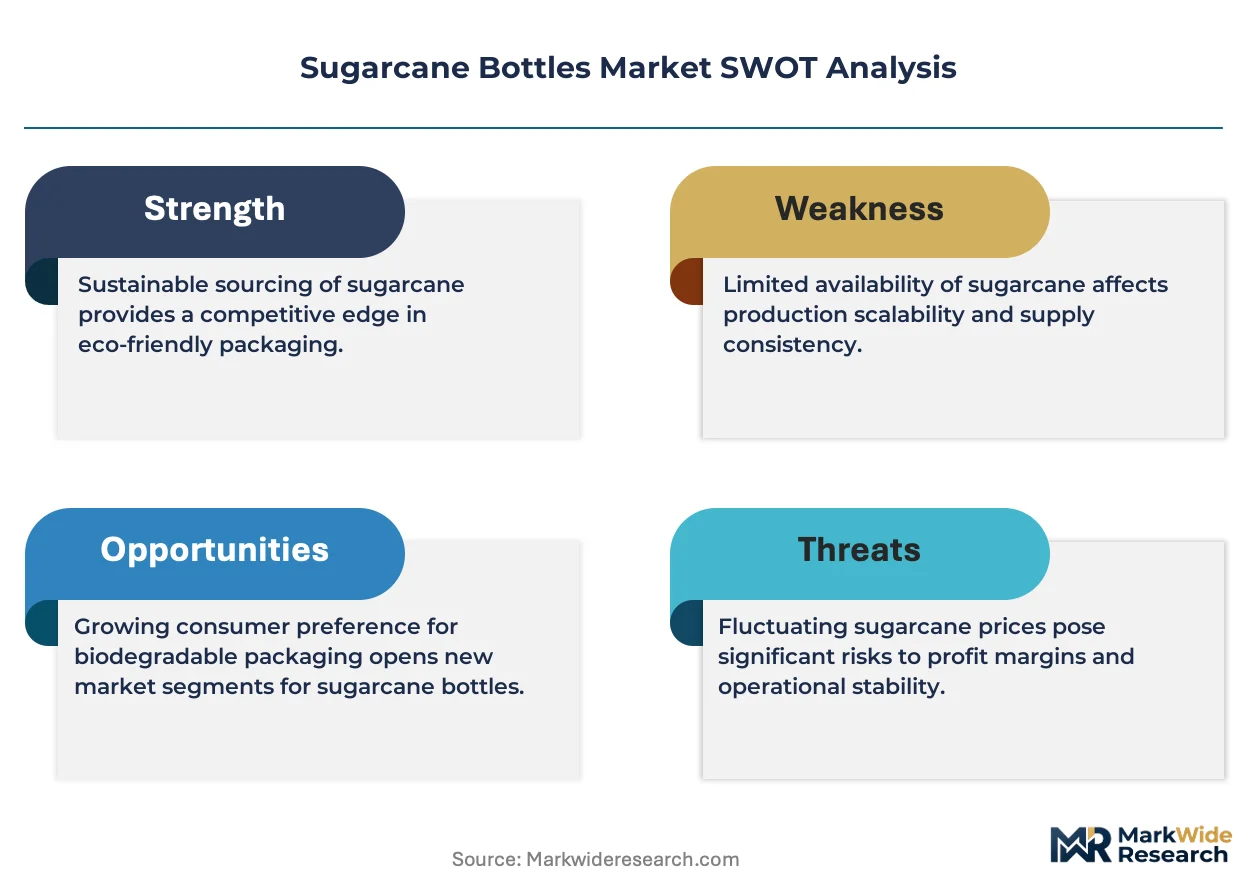
Capacity additions in Brazil are reshaping price floors for sugarcane-derived resin, compressing premiums against fossil-based PET. Three-tier pricing structure across premium, standard, and economy levels separates ASTM D6866-certified volumes from uncertified commodity grades and private-label contract tiers. Price differentiation hinges on certification turnaround speed and volume scale, with multinational drink brands least price-sensitive due to carbon-neutral pledge deadlines. Cost compression in mid-tier segments is intensifying as São Paulo biopolymer clusters expand output.
Supply Chain Analysis
Regional distribution centers in São Paulo state, North Rhine-Westphalia, and the US Midwest form hub-and-spoke patterns feeding blow-molding converters. Supply concentrates in Brazil, Germany, and the United States, with resin production drawing from sugarcane ethanol, bio-polyethylene feedstock, and barrier coating chemistries. Single-source vulnerability runs through Brazilian rainfall-dependent crop yields. Distribution runs through closed-loop logistics operators capturing service revenue under extended producer responsibility schemes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in certified premium tiers and integrated collection-service bundles, with ASTM D6866 verification speed emerging as a cost-down driver for contract winners.
For Market Incumbents: To counter mechanical recycling incompatibility risks, Berry Global and LYSPACKAGING should deepen backward integration into bio-polyethylene resin production and accelerate near-infrared spectroscopy pilot deployments at European materials recovery facilities. Certification investment in automated carbon-14 verification represents the critical lever for compressing product launch timelines. For New Entrants and Emerging Players: Begin with household cleaning refill channels in French and German retail networks, where circular infrastructure spreads fastest and private-label procurement lacks dedicated bio-based supply agreements. Compostable collection system bundling offers the most penetrable go-to-market angle against established beverage-focused incumbents. For Investors and Strategic Acquirers: Beverage brand procurement divisions are the most active acquirer in this space, seeking captive packaging supply to secure carbon-neutral pledge fulfillment. Long-term viability rests on feedstock-integrated producers with closed-loop logistics capabilities. Watch for industrial composting infrastructure buildout in North American municipalities as the inflection indicator for biodegradable format addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Polyethylene Resin | Brazilian ethanol-to-resin producers capture margin from integrated feedstock control. |
| ASTM D6866 Certification Automation | Automated carbon-14 verification compresses laboratory turnaround for contract winners. |
| Closed-Loop Logistics Partnership | Direct sales arrangements with Australasian hospitality groups capture service revenue. |
| Barrier Coating Convergence | Plasma-enhanced chemical vapor deposition extends sugarcane PE into sensitive beverage categories. |
| Extended Producer Responsibility Compliance | Citeo and Duales System Deutschland alignment assigns collection liability upstream to originators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biopolymer plant managers, beverage procurement leads, cosmetic contract manufacturing directors, and waste management operators with secondary validation from customs trade data, ECHA REACH filings, ANVISA regulatory submissions, and SEC 10-K disclosures. Bottom-up resin capacity modeling and top-down beverage brand procurement mandate tracking were cross-referenced for triangulation.
Historical reference periods anchored volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, end-use industry, capacity format, and distribution channel. CAGRs were derived from demand elasticity modeling against regulatory compliance deadlines and carbon disclosure mandate timelines. Forecast inputs incorporated ethanol crop yield volatility patterns and blow-molding equipment retrofit penetration rates.
Several conditions sit outside the modeled scope, including potential revisions to EU Single-Use Plastics Directive enforcement calendars and unanticipated breakthroughs in enzymatic recycling technologies. Forecasts reflect stated assumptions around certification laboratory capacity and municipal composting infrastructure buildout trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Square Media Bottle Market
Beverage Packaging
Tumblers Market
Beverage Packaging
Beveled Bottles Market
Beverage Packaging
Beverage Crates Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Slip Cover Cans Market
Beverage Packaging
Aluminium Cup Market
Beverage Packaging
North America Soft Drinks Packaging Market
Beverage Packaging
Multicomponent Bottle Market
Beverage Packaging
Biotainer Market
Beverage Packaging
Dual Chamber Dispensing Bottles Market
Beverage Packaging
Pop-Up Pourer Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
Water Bottle Racks Market
Beverage Packaging
Beverage Aluminum Cans Market