
 Twist-Off Metal Caps Market | 2026-2036
Twist-Off Metal Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Twist-Off Metal Caps Market Analytics
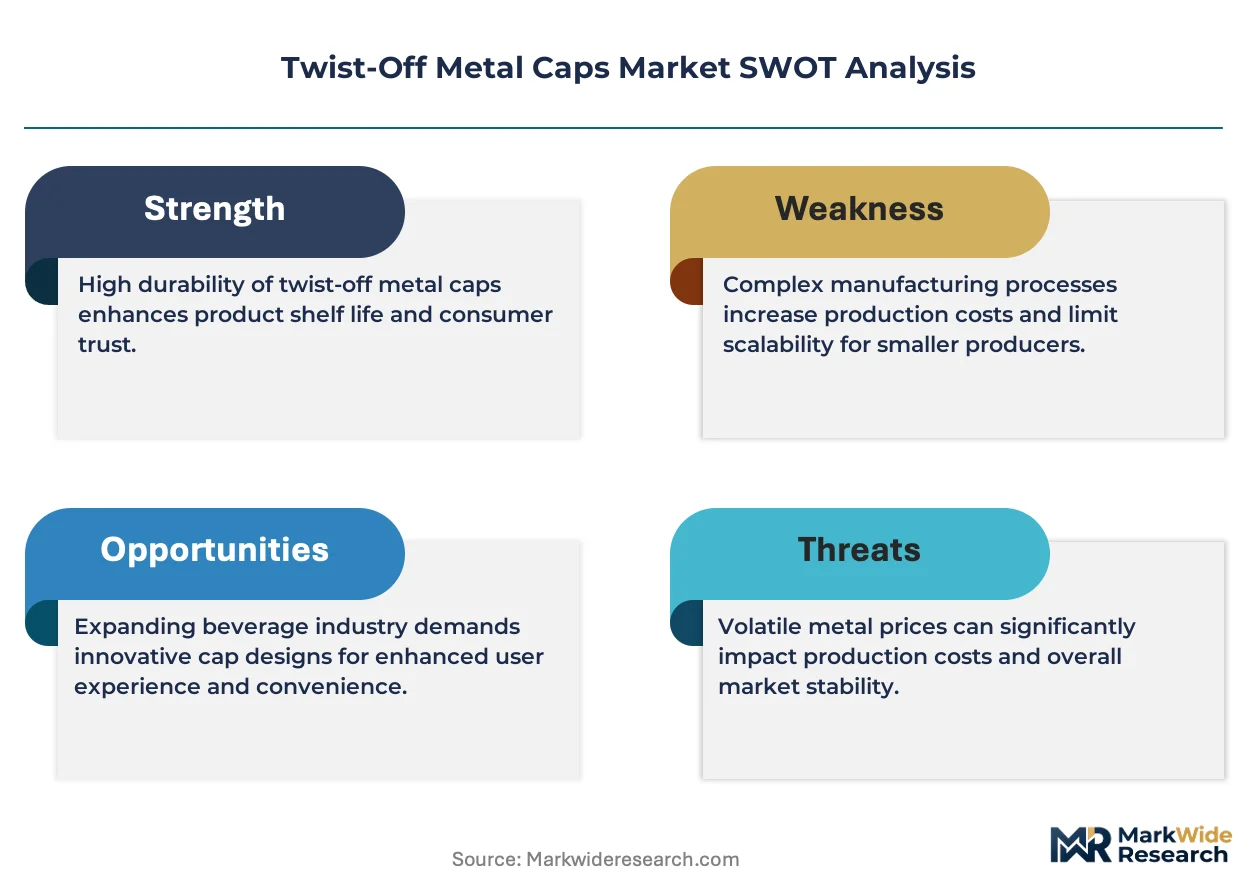
Asset-light leasing models for high-speed capping equipment is rewriting competitive entry dynamics in the twist-off metal caps sector. Crown Holdings leverages its global manufacturing footprint to sustain volume leadership across beverage and food packaging segments. Silgan Holdings anchors its position through backward integration into metal substrate production, controlling cost volatility across aluminum and steel inputs. Tecnocap Group differentiates through specialized coating technologies that extend shelf stability for acidic sauces and carbonated drinks.
Twist-off metal caps are threaded closures manufactured from aluminum, steel, or tin-plated substrates, typically featuring internal liners of PVC-free compounds or pulp-backed seals that create hermetic barriers against oxygen and moisture ingress. These closures serve primarily to preserve product integrity, enable consumer-friendly opening, and support tamper-evident functionality across liquid and semi-solid packaged goods. The beverage end user segment dominates volume consumption, while child-resistant caps command premium positioning in pharmaceutical applications where compliance with poison-prevention standards drives specification rigor. Aluminum material grades are gaining share against steel alternatives as brands prioritize lightweighting and recycling compatibility, though coated metal variants retain niche strength in corrosive product environments.
FDA food contact substance regulations in the United States, EU REACH restrictions on liner compound chemistries, and India's BIS certification requirements for metal packaging collectively elevate compliance costs while screening out subscale producers. These frameworks push manufacturers toward documented traceability systems and third-party migration testing, reshaping supplier qualification protocols for multinational food and pharmaceutical brands. Stakeholders must monitor evolving liner material restrictions and deposit-return scheme expansions, as these policy trajectories will determine which substrate-liner combinations retain market access across major economies.
Market Dynamics
EU F-Gas Regulation and REACH compliance standards are compressing liner material options while aluminum substrate demand accelerates, forcing manufacturers to requalify supply chains for oxygen-barrier performance.
Growth Catalysts
- Deposit-return scheme expansion:Germany's DRS implementation and pending EU-wide harmonization are mandating aluminum-compatible closures, driving substrate conversion from steel in beverage bottling operations.
- Carbonated soft drink bottling:Emerging market bottlers in India and Brazil are expanding twist-off metal cap procurement for ready-to-drink beverages, prioritizing hermetic seal reliability over alternative closure types.
- Pharmaceutical child-resistant compliance:FDA poison-prevention standards and EU MDR requirements are elevating specification rigor for tamper-evident closures in over-the-counter medication packaging.
Market Restraints
- Aluminum ingot price volatility:London Metal Exchange pricing fluctuations for primary aluminum directly compress margin structures for lightweight cap producers.
- Liner compound substitution constraints:ECHA restrictions on PVC-containing compounds limit proven seal technologies, forcing migration to pulp-backed alternatives with unvalidated shelf-life performance.
- Steel substrate concentration:Tin-plated steel production clusters in East Asia create geographic supply risk for corrosion-resistant coated variants used in acidic sauce packaging.
Strategic Opportunities
- India domestic production incentives:PLI scheme allocations for food processing machinery and BIS certification streamlining are accelerating localized cap manufacturing capacity.
- Pharmaceutical serialization integration:Convergence of tamper-evident closures with track-and-trace QR code embedding creates premium positioning for compliance-ready suppliers.
- Direct-to-brewery equipment leasing:Asset-light capping machinery rental models are opening mid-scale craft beverage segments previously locked out by capital barriers.
Industry Challenges
- Migration testing capacity bottleneck:Third-party laboratory qualification for FDA food contact substance documentation faces 16-24 week backlogs, delaying new product launches.
- Legacy steel-to-aluminum line conversion:Existing high-speed capping equipment requires mechanical retrofitting for lighter aluminum substrate handling, demanding capital deployment and downtime coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twist-Off Metal Caps Market |
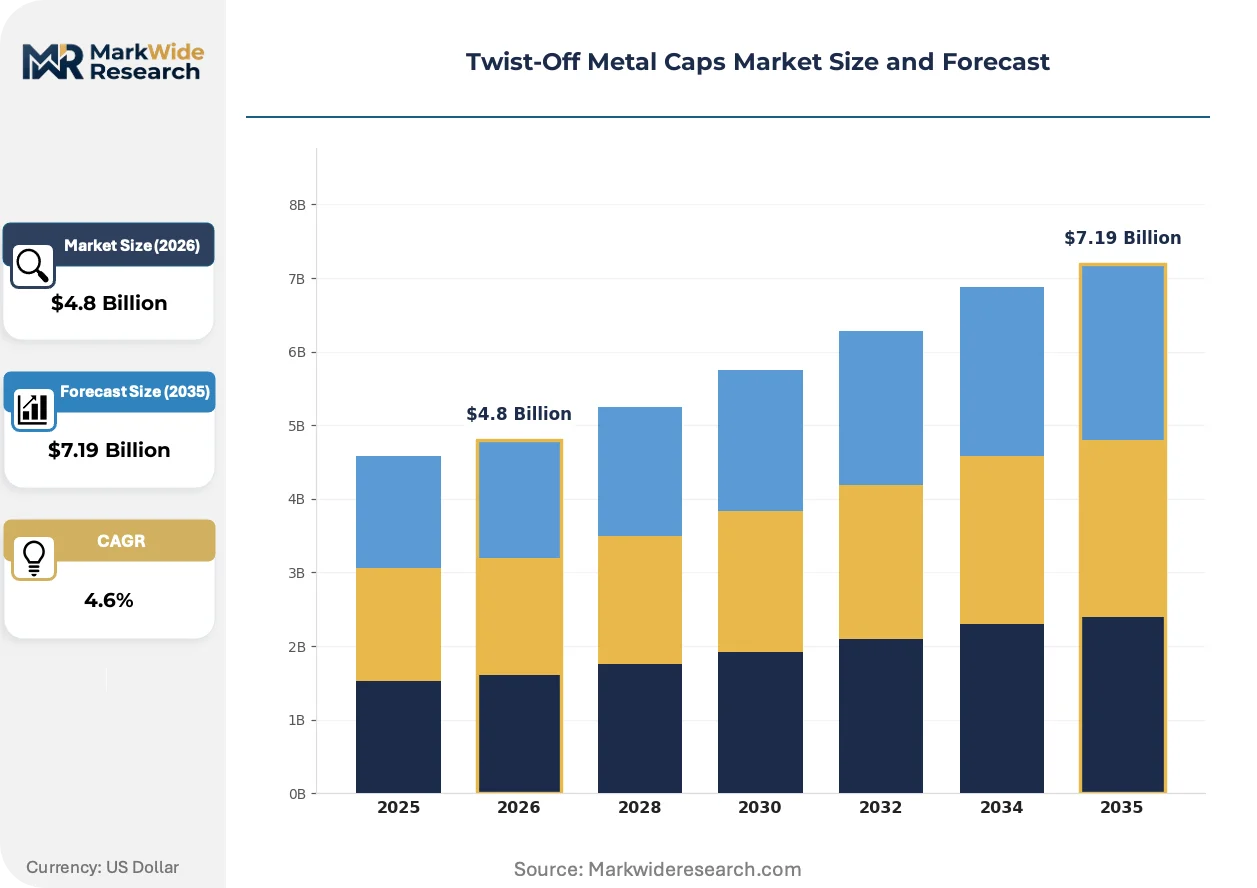
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Caps, Child-Resistant Caps, Easy-Open Caps, Specialty Caps Material: Aluminum, Steel, Tin, Coated Metal End User: Beverage Industry, Food Industry, Pharmaceutical Industry, Cosmetics Industry Application: Non-Alcoholic Beverages, Sauces, Pharmaceuticals, Personal Care Products |
| Companies Covered | Guala Closures Group, Pelliconi & C SpA, Crown Holdings, Tecnocap Group, Closure Systems International, Silgan Holdings, Ardagh Group, Ball Corporation, O.Berk Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twist-Off Metal Caps Market Evolving Landscape
Digital quality assurance and substrate lightweighting are converging to redefine manufacturing economics, while regulatory chemistry restrictions force material science adaptation across the closure value chain.
Sensor-embedded twist-off caps with NFC authentication chips are virtualizing supply chain verification for pharmaceutical and premium beverage applications. European pharmaceutical packagers are piloting these at scale for anti-counterfeiting compliance. This technology is virtualizing the traditional physical tamper-evident feature into a digitally traceable consumer engagement point, compressing the cost premium against holographic labels.
EU REACH Annex XVII restrictions on phthalate plasticizers in liner compounds are eliminating legacy PVC formulations from food contact applications. Manufacturers must reformulate with polyethylene or pulp-based alternatives and resubmit migration testing documentation. Acidic sauce and carbonated drink segments face the steepest requalification burden, with reformulation timelines extending 18-24 months.
Beverage bottlers are consolidating supplier relationships toward full-service closure partners offering integrated capping equipment and technical service. This displaces the historical model of discrete component procurement and separate machinery sourcing. India and Southeast Asia exhibit the most pronounced consolidation, where multinational bottlers are reducing qualified vendor lists from twelve to four suppliers.
Twist-Off Metal Caps Market Segmentation
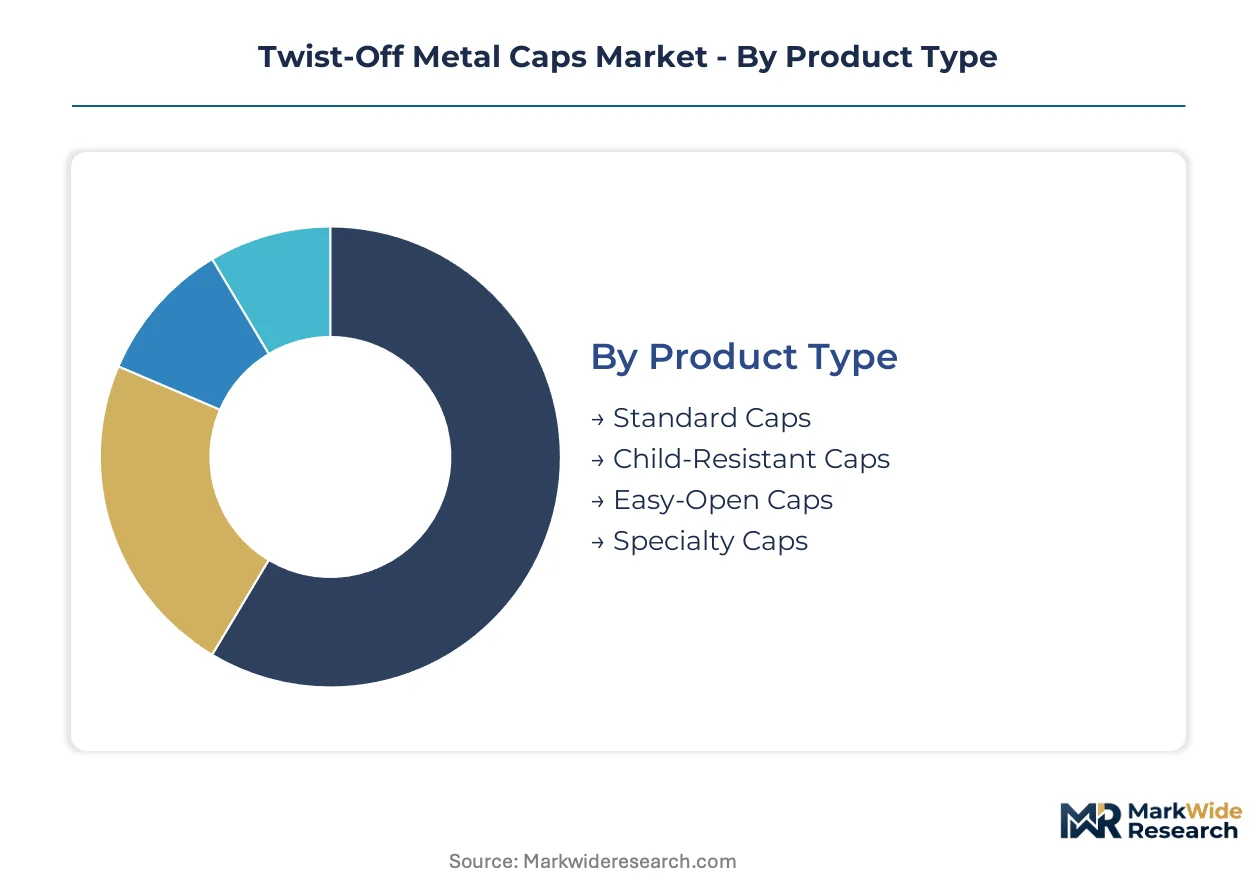
Segmentation in twist-off metal caps determines specification rigor, regulatory burden, and after-sales service intensity. Pharmaceutical and child-resistant variants demand ongoing technical support for compliance documentation, while beverage applications prioritize volume consistency and equipment compatibility.
Product Type:
After-sales service intensity varies sharply across closure types, with regulatory-grade segments requiring migration testing support and equipment calibration programs.
- Standard Caps:Threaded aluminum or steel closures with pulp-backed or PVC-free compound liners for general hermetic sealing. Beverage bottlers in India and Brazil concentrate procurement here, prioritizing lightweight aluminum grades compatible with deposit-return schemes.
- Child-Resistant Caps:Push-and-turn mechanisms with torque-resistant features meeting FDA poison-prevention standards. Pharmaceutical packagers in the United States and EU drive specification rigor, requiring ongoing compliance documentation and third-party testing support.
- Easy-Open Caps:Reduced torque designs with serrated edges for accessibility compliance. Aging population demographics in Japan and Germany expand addressable markets for arthritis-friendly packaging.
- Specialty Caps:Custom-thread profiles and proprietary liner formulations for niche corrosion resistance. Acidic sauce manufacturers specify coated metal variants with extended shelf-life validation.
By volume, Standard Caps leads. By growth pace, Child-Resistant Caps is ahead.
Material:
Cost tier stratification separates premium aluminum from economy steel grades, with coating technologies commanding mid-tier positioning.
- Aluminum:Lightweight substrate with superior recycling compatibility and oxygen barrier performance. Germany's DRS implementation and pending EU-wide harmonization mandate aluminum-compatible closures, forcing substrate conversion from steel in beverage operations.
- Steel:Tin-plated or chrome-coated substrates for corrosion-resistant applications. Acidic sauce packaging retains steel concentration despite lightweighting trends, with production clusters in East Asia creating geographic supply risk.
- Tin:Traditional plating material for food contact safety heritage. Niche preservation in legacy canning equipment compatibility.
- Coated Metal:Epoxy or polymer-coated substrates for aggressive chemical resistance. Specialty pharmaceutical and industrial chemical applications specify these for extended shelf stability.
By volume, Aluminum leads. By expansion trajectory, Coated Metal is climbing the fastest.
End User:
Application maturity determines margin structure, with pharmaceutical compliance requirements sustaining premium pricing against commoditized beverage procurement.
- Beverage Industry:Carbonated soft drink and ready-to-drink bottlers representing the largest volume consumption segment. Emerging market expansion in India and Brazil concentrates procurement growth for hermetic seal reliability.
- Food Industry:Acidic sauce, preserves, and condiment packagers requiring corrosion-resistant coated variants. EU REACH liner restrictions impose reformulation timelines extending 18-24 months for this segment.
- Pharmaceutical Industry:Over-the-counter and prescription medication packaging with FDA and EU MDR compliance mandates. Child-resistant functionality and tamper-evident integration command specification rigor and technical service intensity.
- Cosmetics Industry:Premium personal care and fragrance applications with aesthetic finishing requirements. Smaller addressable market with higher per-unit value concentration.
By volume, Beverage Industry leads. By value concentration, Pharmaceutical Industry is gaining share fastest.
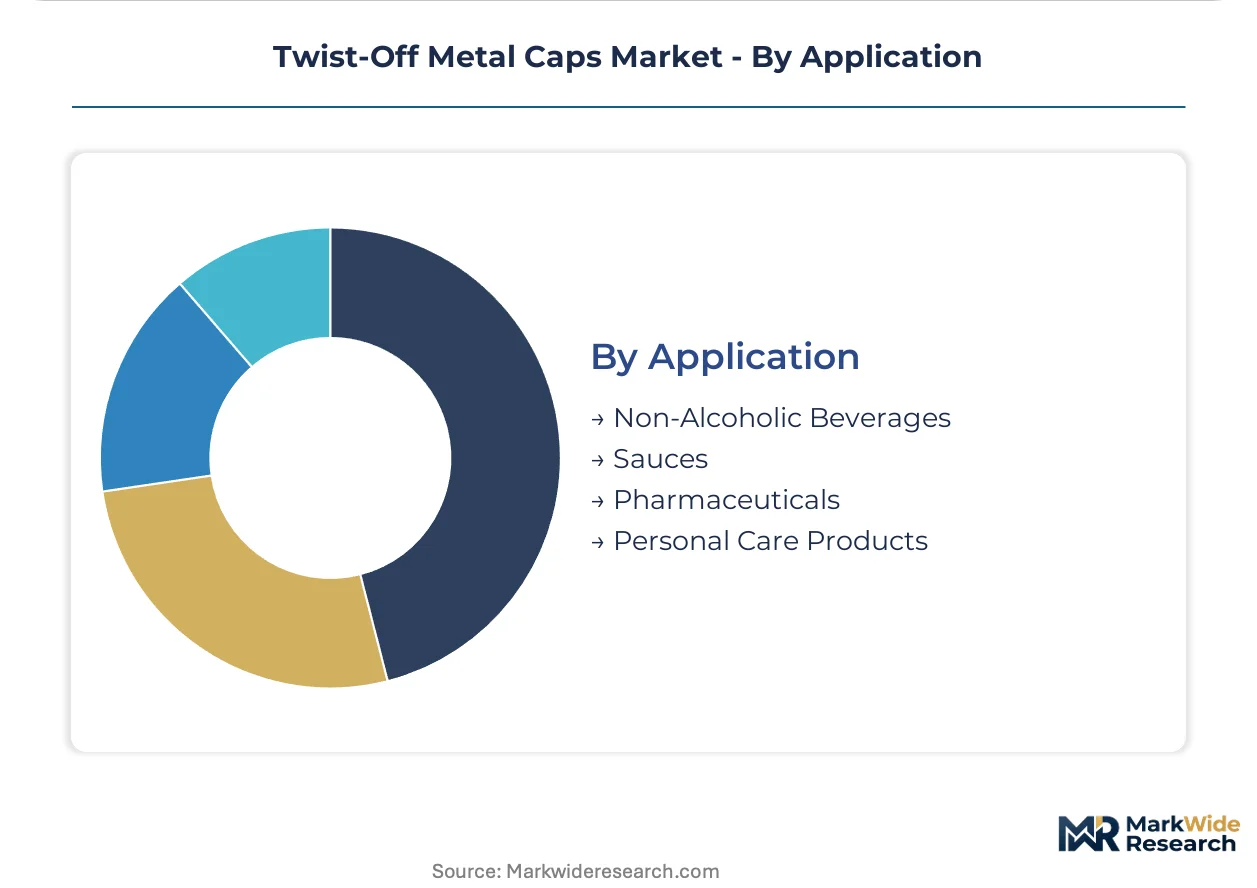
Application:
Customer type differentiation separates multinational bottlers with integrated equipment partnerships from mid-scale producers seeking asset-light leasing models.
- Non-Alcoholic Beverages:Carbonated soft drinks, juices, and functional waters requiring consistent torque performance across high-speed capping lines. Deposit-return scheme expansion in Germany and pending EU harmonization mandate aluminum-compatible substrate specifications.
- Sauces:Tomato-based and acidic condiments demanding corrosion-resistant coated metal or specialized liner formulations. ECHA restrictions on PVC-containing compounds force migration to unvalidated pulp-backed alternatives.
- Pharmaceuticals:Tablet bottles and liquid medications with child-resistant and tamper-evident requirements. FDA food contact substance documentation and serialization integration create premium supplier positioning.
- Personal Care Products:Shampoos, lotions, and cosmetics with aesthetic thread finish and fragrance barrier requirements. Niche volume with higher customization intensity.
By volume, Non-Alcoholic Beverages leads. By compliance-driven growth, Pharmaceuticals is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in twist-off metal caps tilt toward net-importing beverage markets while production clusters serve regional canning industries. Currency-adjusted procurement costs and deposit-return scheme compliance are redirecting sourcing patterns across major economies.
Germany
Beverage bottlers in Bavaria and North Rhine-Westphalia are converting steel capping lines to aluminum-compatible formats ahead of EU-wide deposit-return scheme harmonization. The national packaging regulator enforces strict ECHA REACH compliance for liner compound migration limits. Stuttgart-area machinery integrators are retrofitting high-speed equipment for lightweight substrate handling.
United States
Pharmaceutical packagers in New Jersey and Illinois drive specification rigor for child-resistant closures meeting FDA poison-prevention standards. The federal food contact substance framework mandates documented traceability for liner materials. Chicago-area metal forming clusters are expanding coated metal capacity for acidic sauce applications.
India
Domestic food processing investments in Maharashtra and Gujarat are accelerating localized cap manufacturing under PLI scheme allocations. BIS certification requirements for metal packaging are screening out subscale importers. The Pune-Ahmedabad industrial corridor is attracting multinational beverage bottlers seeking hermetic seal reliability for carbonated soft drinks.
Brazil
Ready-to-drink beverage bottlers in São Paulo state are expanding twist-off metal cap procurement for carbonated soft drink lines. ANVISA pharmaceutical regulations are elevating tamper-evident closure standards for over-the-counter medications. The Campinas packaging cluster is consolidating supplier relationships toward full-service closure partners.
China
Aluminum substrate demand from Guangdong and Zhejiang beverage canning operations is outpacing domestic liner compound reformulation capacity. GB standards for food contact materials are tightening parallel to EU REACH restrictions. The Yangtze River Delta metal packaging corridor is absorbing technology licensing for PVC-free seal alternatives.
Twist-Off Metal Caps Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with substrate and coating technologies. The vendor base organizes around three archetypes: multinational packaging conglomerates with captive closure divisions, dedicated metal closure specialists with backward integration into aluminum substrate production, and regional fabricators serving single-country beverage bottling markets. Competitive moves center on M&A-driven geographic expansion and asset-light equipment leasing partnerships that lower barriers for mid-scale craft beverage entrants.
Within the multinational conglomerate tier, Crown Holdings, Silgan Holdings, and Tecnocap Group exemplify divergent strategic positioning. Crown Holdings occupies a scale-driven position across beverage and food packaging segments through its global manufacturing footprint. Silgan Holdings anchors its competitive posture through upstream control over metal substrate production, mitigating aluminum and steel input cost volatility. Tecnocap Group sits within the specialization tier, differentiated by proprietary coating technologies that address shelf stability requirements for corrosive product environments.
| Leading Market Players |
|---|
| Guala Closures Group |
| Pelliconi & C SpA |
| Crown Holdings |
| Tecnocap Group |
| Closure Systems International |
| Silgan Holdings |
| Ardagh Group |
| Ball Corporation |
| O.Berk Company |
| Others |
Value Network & Pricing Analysis
Aluminum ingot production clusters in East Asia and the Gulf States concentrate upstream substrate supply, anchoring margin capture with integrated smelters while downstream cap fabricators in Germany and the United States absorb London Metal Exchange volatility through contract hedging.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with spot-market adjustments for aluminum substrate. Pricing stratifies across pharmaceutical-grade child-resistant caps, beverage-standard aluminum closures, and economy steel variants for acidic sauces, with certification tier and volume scale as primary differentiation drivers. Cost compression in standard beverage caps is intensifying as Brazilian and Indian bottlers consolidate supplier lists. Pharmaceutical packagers show least price sensitivity due to FDA compliance documentation requirements and migration testing backlogs.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for multinational beverage bottlers, squeezing working capital for mid-tier fabricators. Raw material flows draw from primary aluminum smelters in China, Russia, and the UAE, with tin-plated steel sourcing concentrated in Japan and South Korea. Single-source vulnerability sits with PVC-free liner compound suppliers facing ECHA REACH reformulation deadlines. Distribution runs through direct equipment-integrated partnerships for large bottlers and regional distributors for mid-scale craft beverage entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The twist-off metal caps market operates as a defensive-moat industry where regulatory entrenchment creates structural barriers. Switching costs for pharmaceutical and beverage OEMs are elevated by migration testing documentation and line requalification requirements.
For Market Incumbents: Insulate market position by deepening backward integration into aluminum substrate production to capture margin from LME volatility, and accelerate certification investment for EU REACH-compliant liner compounds ahead of 18-24 month reformulation windows. The threat of asset-light equipment leasing models from emerging entrants demands preemptive channel control through integrated capping machinery partnerships. For New Entrants and Emerging Players: Mid-scale craft beverage bottlers in Southeast Asia and Eastern Europe represent the most penetrable entry point, as these segments are locked out by capital barriers from incumbent direct-sales models. Pharmaceutical serialization integration for track-and-trace compliance offers a second white-space target with premium positioning potential. A go-to-market angle through equipment leasing partnerships with regional machinery distributors bypasses incumbent field service networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed metal packaging specialists in North America and Western Europe that have consolidated regional fabricators but not yet integrated upstream substrate production. The five-to-ten year viability thesis rests on deposit-return scheme expansion and aluminum substrate conversion tailwinds. The signal to watch is BIS certification streamlining in India, which would accelerate localized production and compress import-dependent margin structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Substrate | Crown Holdings and Silgan Holdings already control captive supply, forcing followers to acquire or partner with Gulf smelters. |
| Migration Testing Capacity Expansion | Third-party laboratories in Germany and the United States face 16-24 week backlogs, creating bottleneck for new product launches. |
| Equipment Leasing Partnership Model | Asset-light capping machinery rental opens mid-scale craft beverage segments previously excluded by capital barriers. |
| Pharmaceutical Serialization Integration | QR code embedding convergence with tamper-evident closures commands premium positioning for FDA and EU MDR compliance. |
| India Domestic Manufacturing Buildout | PLI scheme allocations for food processing machinery accelerate localized cap production under BIS certification requirements. |
Research Methodology
A spread of perspectives from beverage procurement directors, pharmaceutical packaging engineers, metal substrate plant managers, and regulatory affairs specialists converged on the working assumptions through structured primary interviews. Secondary validation drew from ECHA REACH substance restrictions, FDA food contact substance documentation, London Metal Exchange pricing data, and BIS certification requirements. Bottom-up segment sizing across material grades, closure types, and end-use applications was triangulated against top-down trade flow analysis for aluminum and steel substrates.
Demand-supply balance modeling across the projection horizon incorporated beverage bottling capacity expansion in India and Brazil, pharmaceutical child-resistant compliance mandates in the United States and EU, and aluminum substrate conversion timelines tied to deposit-return scheme implementation. Segmentation dimensions included material substrate, product type, end-user industry, and geographic regulatory cluster. CAGRs were derived from installed base growth, replacement demand cycles, and penetration rate assumptions for child-resistant and easy-open variants.
Practitioners should monitor ECHA liner compound restriction timelines, LME aluminum price volatility bands, and India PLI scheme allocation announcements for early signals of forecast deviation. Macroeconomic downturns affecting beverage consumption, accelerated EU-wide deposit-return scheme harmonization, or breakthroughs in bio-based closure materials would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Linerless Closures Market
Caps and Closures
Brush Caps Market
Caps and Closures
Cover Caps Market
Caps and Closures
Ring Pull Caps Market
Caps and Closures
France Plastic Caps and Closures Market
Caps and Closures
Shrink Bands Market
Caps and Closures
Snap Cap Vials Market
Caps and Closures
PCR Closures Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
Child Resistant Pipette Closures Market
Caps and Closures
Continuous Thread Metal Cap Market
Caps and Closures
Molded Fiber End Caps Market
Caps and Closures
Japan Plastic Caps and Closures Market
Caps and Closures
Smooth Hinge Caps and Closure Market
Caps and Closures
Side Pour Caps Market
Caps and Closures
Peelable Lid Stock Market