
 Global Automotive Structural Sheet Metal Market | 2026-2036
Global Automotive Structural Sheet Metal Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Structural Sheet Metal Market Intelligence
Value-added component fabrication is rewriting profit allocation away from raw material supply in the automotive structural sheet metal sector. Gestamp Automoción S.A. specializes in this integrated model, delivering complex assemblies to OEMs. ArcelorMittal leverages its scale in advanced high-strength steel, while Novelis Inc. differentiates with its aluminum sheet products for vehicle lightweighting.
Automotive structural sheet metal refers to processed metal sheets, typically 0.5mm to 3.0mm thick, formed into components for a vehicle’s load-bearing frame. Its primary purpose is to provide structural integrity, crash safety, and torsional rigidity for the body-in-white. While steel panels maintain a large share in chassis frames, aluminum sheets are expanding rapidly in body panels to reduce vehicle weight. Stamping constitutes the primary manufacturing stage by volume, though hydroforming commands higher margins for complex parts.
Vehicle lightweighting is directly influenced by emissions regulations, including fuel economy standards from the US EPA and CO2 fleet targets under the EU Green Deal. China's dual carbon goals further promote materials with lower lifecycle emissions, such as recycled aluminum. Consequently, strategic decisions for suppliers revolve around balancing investments in high-strength steel capacity against the advanced forming capabilities required for aluminum alloys.
Market Dynamics
The transition to electric vehicle architectures is the central force defining the market. This shift, driven by emissions regulations like the EU Green Deal, necessitates a fundamental re-evaluation of material selection, favoring high-strength, lightweight metals for battery enclosures and body-in-white structures.
Growth Catalysts
- EV Battery Enclosures:The proliferation of electric vehicles creates a new, high-value application for structural sheet metal, particularly aluminum and AHSS, to protect battery modules while minimizing weight.
- Emissions Regulations:Mandates such as the US EPA's fuel economy standards and the EU's CO2 fleet targets compel automakers to adopt lightweight materials to improve efficiency and reduce emissions.
- Advanced Forming Technologies:The maturation of hydroforming and hot stamping processes allows for the production of more complex and stronger components, expanding the design possibilities for structural engineers.
Market Restraints
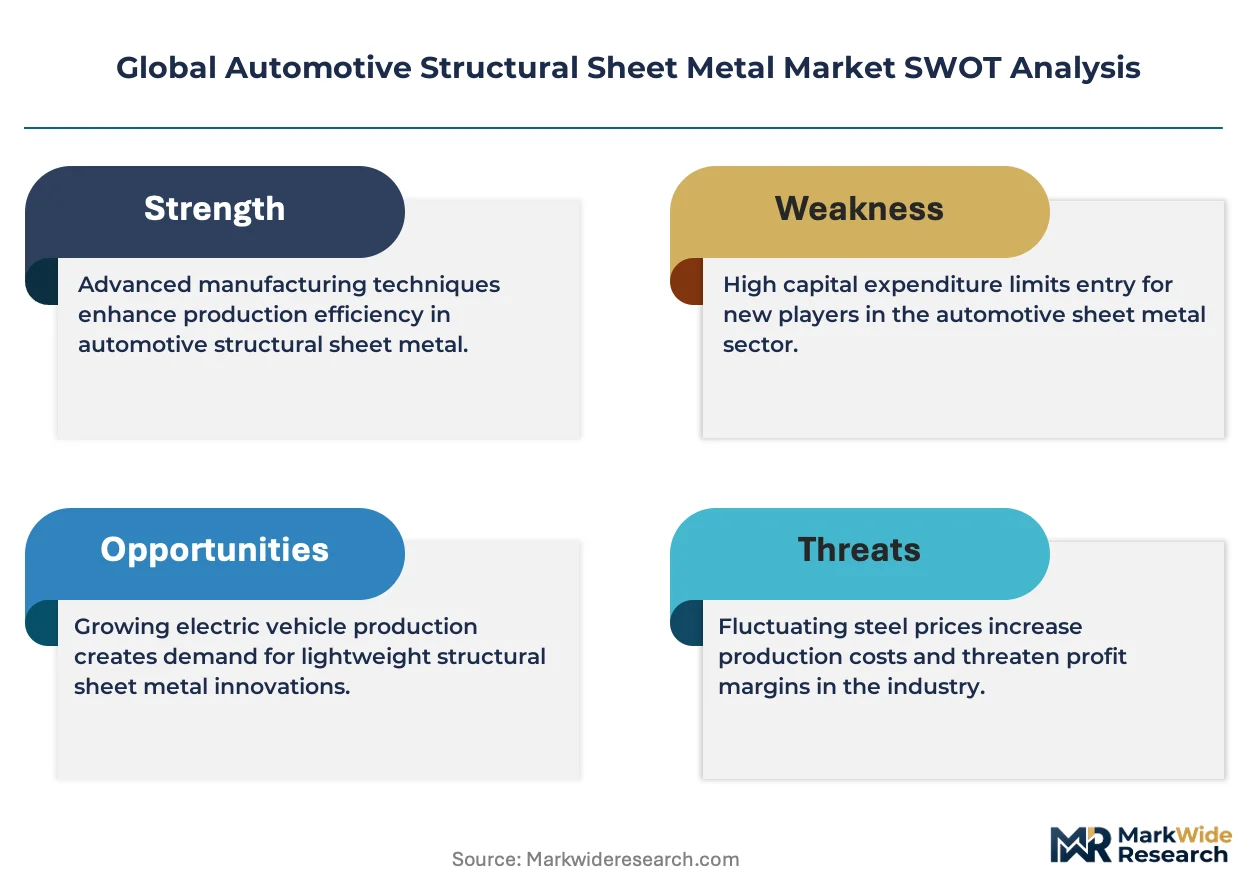
- Input Material Price Volatility:Fluctuations in the commodity prices of aluminum and high-grade steel create significant cost uncertainty for component manufacturers, impacting profitability and long-term contract pricing.
- Dissimilar Material Joining:The technical complexity and cost associated with joining aluminum to steel, including managing galvanic corrosion, restrains the speed of multi-material vehicle body adoption.
- Specialized Tooling Costs:Forming advanced high-strength steels and aluminum alloys requires significant capital investment in specialized dies and presses, creating a high barrier to entry for smaller fabricators.
Strategic Opportunities
- Recycled Aluminum Loops:Establishing closed-loop recycling systems with OEMs for aluminum scrap offers a way to lower lifecycle emissions, meeting criteria under policies like China's dual carbon goals.
- Structural Battery Packs:Designing cell-to-chassis EV architectures where the sheet metal enclosure becomes a primary load-bearing element presents a major opportunity for value-added fabrication.
- Expansion in India:India's growing automotive market and push for local manufacturing under its PLI scheme provide an underpenetrated geography for advanced structural component suppliers.
Industry Challenges
- Skilled Labor Scarcity:A shortage of technicians and engineers with expertise in hydroforming simulation, die maintenance for AHSS, and aluminum welding diagnostics hinders production efficiency and quality control.
- Production Line Rigidity:High capital investment in stamping and forming lines dedicated to specific material types reduces operational flexibility to switch between steel and aluminum based on cost or demand.
- Certification Delays:The lengthy validation and certification cycles required by OEMs for any new material or forming process can delay the introduction of innovative lightweighting solutions by years.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Structural Sheet Metal Market |
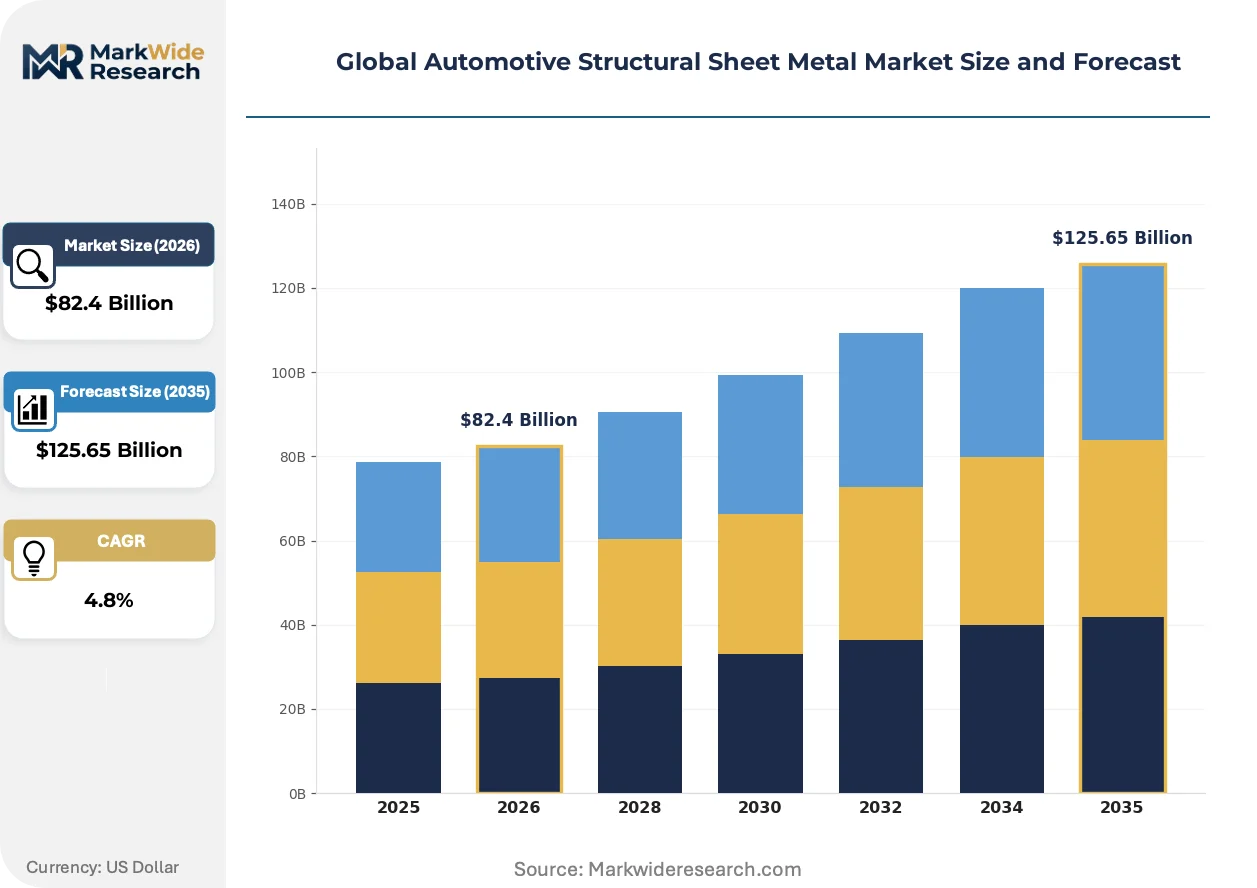
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $125.65 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Sheets, Steel Panels, Titanium Plates, Magnesium Alloys, Copper Sheets Application: Chassis Frames, Body Panels, Door Assemblies, Roof Structures, Floor Pans Manufacturing Stage: Stamping, Welding, Hydroforming, Machining, Heat Treating End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | POSCO, Hyundai Steel, ArcelorMittal, Nucor Corporation, Novelis Inc., Nippon Steel Corporation, United States Steel Corporation, Gestamp Automoción S.A., Thyssenkrupp AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Structural Sheet Metal Market Strategic Shifts & Innovations
A convergence of advanced material science and digital manufacturing processes is redefining possibilities in automotive structures. Simulation-driven design and new forming techniques are enabling lighter, more complex components that were previously unmanufacturable at scale.
Hydroforming uses high-pressure fluid to shape metal into intricate, single-piece structural parts. Automotive OEMs increasingly adopt this for complex components like chassis frames, moving beyond niche applications. This process is collapsing the distinction between part fabrication and sub-assembly, creating unified structures that reduce weight, weld points, and production complexity.
The European Union’s Corporate Sustainability Reporting Directive (CSRD) creates new transparency requirements for supply chain emissions. This forces suppliers to document the lifecycle carbon footprint of their steel and aluminum, a mandate echoed by China's dual carbon goals. Procurement decisions for structural sheet metal are thus expanding beyond cost and performance to include verifiable low-carbon production credentials.
Automaker purchasing is evolving from transactional orders for individual parts to strategic partnerships for complete structural systems. This shift marginalizes smaller fabricators in favor of integrated Tier-1 suppliers capable of co-design, simulation, and assembly. The co-development model is most prominent within the competitive electric vehicle segment in China, where speed-to-market is critical.
Global Automotive Structural Sheet Metal Market Segmentation
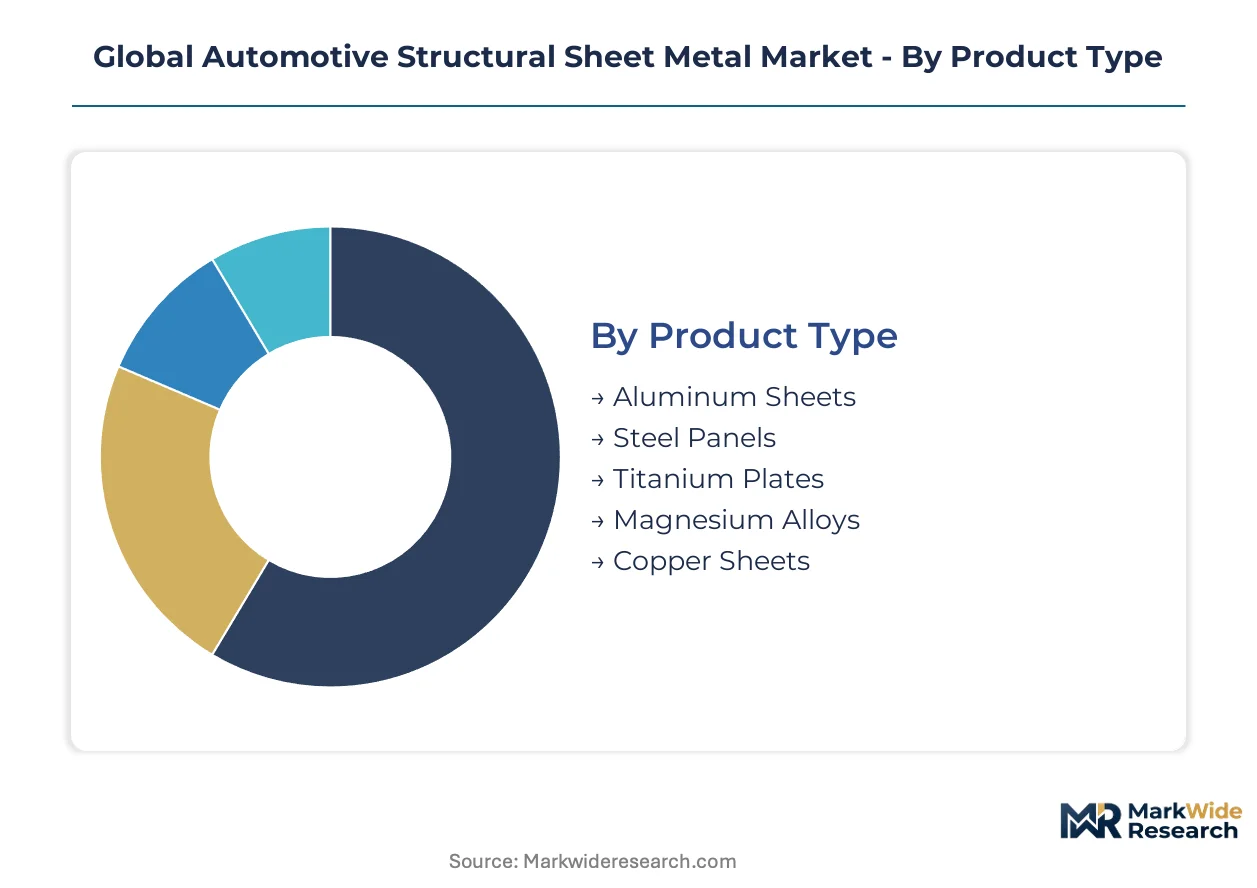
Segmentation within the global automotive structural sheet metal market highlights the diverse material science, manufacturing complexity, and end-use applications driving innovation. Understanding these distinct segments is crucial for suppliers to align their product development and production capabilities with evolving automotive industry demands, particularly those from electric vehicle architectures.
Product Type:
The material composition of automotive structural sheet metal dictates its performance characteristics and suitability for various vehicle components.
- Aluminum Sheets:These lightweight, corrosion-resistant sheets are typically 0.5mm to 3.0mm thick and are increasingly used for EV battery enclosures and body panels. Demand concentrates in regions like China, driven by stringent emissions regulations and the push for vehicle lightweighting.
- Steel Panels:Comprising advanced high-strength steel (AHSS), these panels offer superior crash performance and structural rigidity at a competitive cost. Steel panels maintain a large share in traditional chassis frames and body-in-white structures, essential for vehicle safety and durability.
- Titanium Plates:Known for their exceptional strength-to-weight ratio and corrosion resistance, titanium plates find niche applications in high-performance or specialized automotive components where extreme durability is required.
- Magnesium Alloys:These ultra-lightweight alloys offer further weight reduction benefits but present challenges in formability and cost, limiting their widespread adoption in mainstream structural applications.
- Copper Sheets:Primarily utilized for their electrical and thermal conductivity, copper sheets are employed in specific automotive applications such as battery cooling systems or electrical connections rather than primary structural elements.
Steel Panels commands the established base. The steepest expansion runs through Aluminum Sheets.
Application:
The specific functional requirements of a vehicle component determine the optimal type of structural sheet metal utilized.
- Chassis Frames:These components form the primary load-bearing structure of a vehicle, providing foundational rigidity and crash protection. Demand is shifting towards advanced materials for EV platforms, where the frame integrates battery protection and structural integrity.
- Body Panels:These exterior surfaces define a vehicle's aesthetics and aerodynamics, requiring materials that balance formability, lightweight properties, and dent resistance. Automakers increasingly specify aluminum sheets for body panels to meet fuel economy standards set by the US EPA and CO2 fleet targets under the EU Green Deal.
- Door Assemblies:Integral for passenger ingress/egress and side-impact protection, door assemblies leverage structural sheet metal for internal reinforcement and external skins, focusing on weight reduction without compromising safety.
- Roof Structures:These elements contribute to overall vehicle rigidity and rollover protection, often requiring high-strength materials that can be formed into complex profiles while minimizing weight.
- Floor Pans:Forming the base of the passenger compartment, floor pans provide structural support and protection from road debris, increasingly incorporating multi-material solutions for weight optimization.
Chassis Frames currently constitute the largest volume segment, while Body Panels are experiencing significant material substitution.
Manufacturing Stage:
The complexity and value addition in processing raw sheet metal vary significantly across different manufacturing stages.
- Stamping:This high-volume manufacturing process uses dies to cut and form sheet metal into desired shapes, remaining the most common method for producing a wide range of automotive components efficiently. Stamping is critical for mass-produced parts where cost-effectiveness and speed are paramount.
- Hydroforming:This advanced process uses high-pressure fluid to shape metal into complex, hollow, or single-piece structural components with reduced weight and fewer weld points. Hydroforming commands higher margins for intricate parts like chassis sub-frames, expanding design possibilities for structural engineers.
- Welding:Essential for joining individual sheet metal components into larger assemblies, welding techniques are critical for ensuring the structural integrity and crashworthiness of the body-in-white.
- Machining:This stage involves precise material removal to achieve final dimensions, intricate details, or surface finishes on structural sheet metal components, often used for critical interfaces or complex geometries.
- Heat Treating:Applied to modify the physical and mechanical properties of metals, heat treating enhances strength, hardness, and ductility, particularly for advanced high-strength steel and aluminum alloys.
Stamping remains the dominant process by volume, but Hydroforming is capturing higher value segments.
End User:
The customer type influences procurement strategies and the level of integration required from structural sheet metal suppliers.
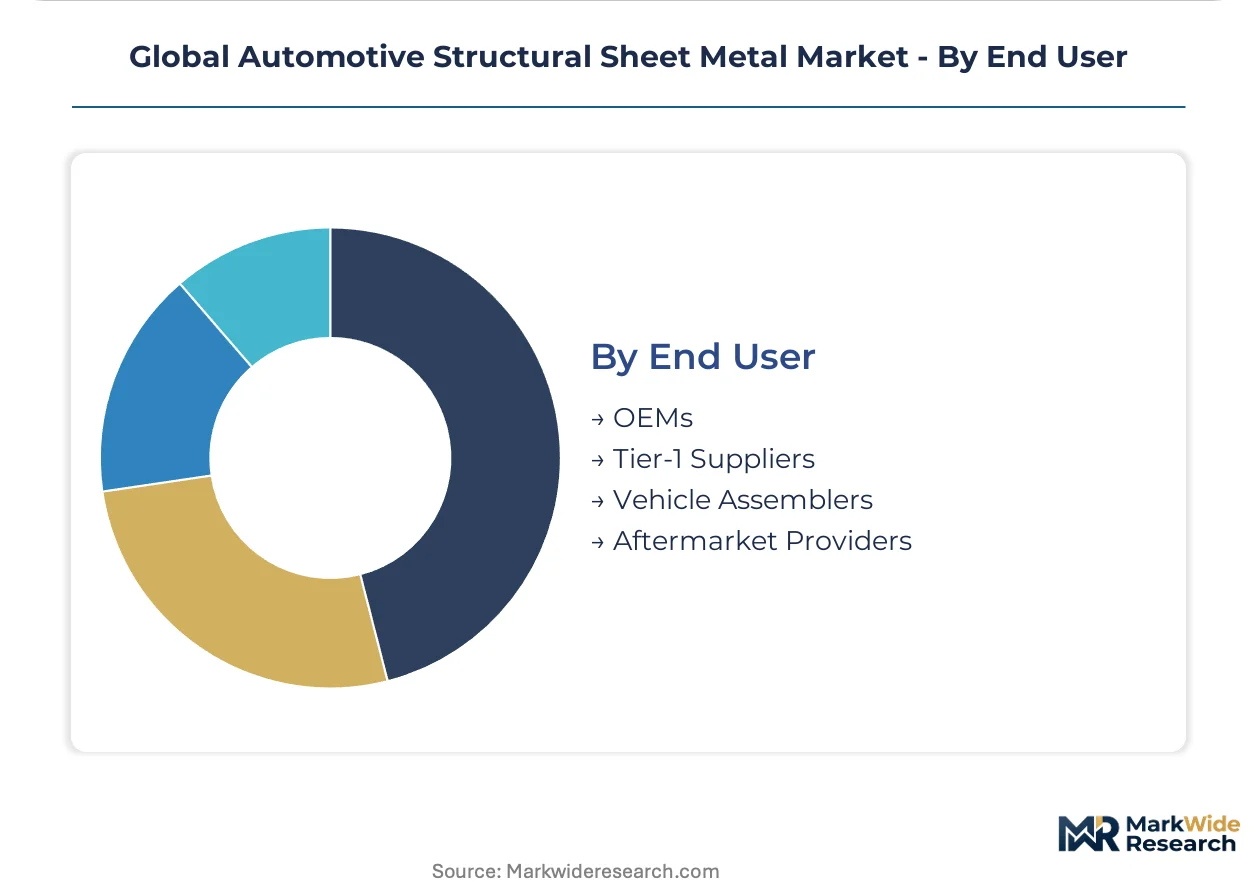
- OEMs:Original Equipment Manufacturers directly integrate structural sheet metal components into their vehicle production lines, often seeking strategic partnerships for co-design and complete structural systems. This model is prominent in the competitive electric vehicle segment in China, prioritizing speed-to-market.
- Tier-1 Suppliers:These integrated suppliers specialize in value-added component fabrication, delivering complex assemblies and sub-systems directly to OEMs. Companies like Gestamp Automoción S.A. exemplify this model, leveraging their expertise in advanced forming and assembly.
- Vehicle Assemblers:These entities focus on the final assembly of vehicles, often sourcing pre-fabricated structural components and sub-assemblies from Tier-1 suppliers or directly from OEMs for localized production.
- Aftermarket Providers:This segment supplies replacement structural parts for vehicle repair and maintenance, typically focusing on standardized components that meet original equipment specifications for compatibility and safety.
OEMs increasingly prefer direct partnerships for advanced structural systems, while Tier-1 Suppliers consolidate value-added fabrication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Structural sheet metal demand exhibits varying elasticity across regions, with some markets prioritizing cost over advanced material specifications. Conversely, regions with stringent emissions regulations show higher willingness to invest in lightweight, high-performance alloys. This distinction shapes regional material procurement strategies.
China
China's automotive sector drives immense demand for structural sheet metal, particularly for electric vehicle architectures. The nation's dual carbon goals mandate the adoption of lower lifecycle emission materials like recycled aluminum. Major manufacturing hubs in Shanghai and Shenzhen lead in co-development models for advanced structural components.
United States
Demand in the United States focuses on lightweight materials for both traditional and electric vehicles. US EPA's fuel economy standards compel automakers to integrate advanced high-strength steel and aluminum. Automotive clusters in Michigan and California pioneer innovations in multi-material body structures.
Germany
Germany's automotive industry emphasizes high-strength steel and aluminum for premium vehicle platforms. The EU Green Deal and CSRD push for verifiable low-carbon production credentials across the supply chain. Manufacturing centers in Bavaria and Stuttgart are at the forefront of hydroforming and hot stamping advancements.
India
India presents a significant growth opportunity for advanced structural component suppliers. The country's PLI scheme encourages localized production and material innovation for both internal combustion engine and electric vehicles. Automotive manufacturing hubs around Chennai and Pune are expanding capabilities for new material processing.
Global Automotive Structural Sheet Metal Market Key Industry Players
Integrated component fabricators and large-scale raw material producers split the automotive structural sheet metal market. This tiered structure sees specialized Tier-1 suppliers delivering complex assemblies directly to OEMs, while material giants focus on high-volume production. Value-added component fabrication is rewriting profit allocation away from raw material supply. Strategic partnerships and capacity expansion in advanced materials represent dominant competitive moves.
Specialists in integrated structural systems include Gestamp Automoción S.A., known for delivering complex assemblies and leveraging an integrated model. ArcelorMittal, a Luxembourg-based industrial entity, anchors the market with its substantial scale in advanced high-strength steel production for chassis frames. Novelis Inc. differentiates itself significantly with its aluminum sheet products, crucial for vehicle lightweighting initiatives and EV battery enclosures. These players exemplify the market's segmentation between material producers and value-added fabricators, reflecting distinct strategic approaches to automotive OEM demands.
| Leading Market Players |
|---|
| POSCO |
| Hyundai Steel |
| ArcelorMittal |
| Nucor Corporation |
| Novelis Inc. |
| Nippon Steel Corporation |
| United States Steel Corporation |
| Gestamp Automoción S.A. |
| Thyssenkrupp AG |
| Others |
Cost & Logistics Intelligence
Trans-oceanic shipping routes for raw materials directly influence the landed cost of structural sheet metal, affecting pricing power for both steel producers and aluminum fabricators. This dynamic shapes the competitive landscape and downstream price differentiation for automotive components.
Pricing Analysis
Aftermarket parts revenue, particularly for collision repair, often drives long-term value for structural sheet metal suppliers. Contract-based long-term offtake agreements dominate the OEM segment, providing stability for both buyers and sellers. Price differentiation stems from material grade certification and the complexity of forming processes like hydroforming. Pricing pressure intensifies due to input material price volatility, particularly for high-grade steel and aluminum alloys. OEMs for mass-market electric vehicles exhibit high price sensitivity, while niche performance vehicle manufacturers prioritize advanced material properties over cost.
Supply Chain Analysis
Commodity price volatility for aluminum and high-grade steel presents a significant structural risk across the supply chain. Geographic supply concentration centers on China, Germany, and the United States for advanced material production and fabrication. The supply chain relies heavily on inputs like bauxite for aluminum and iron ore for steel, which are sourced globally. Distribution primarily runs through integrated Tier-1 suppliers who deliver complex assemblies directly to automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market for automotive structural sheet metal faces a critical skills gap, particularly in advanced forming simulation and multi-material joining techniques, necessitating strategic interventions.
For Market Incumbents: Pre-empt material substitution risks by investing heavily in advanced high-strength steel (AHSS) and aluminum forming capabilities. Expand capacity in key EV manufacturing hubs, such as China and Germany, to meet localized OEM demands for lightweight structures. Deepen vertical integration into value-added fabrication to capture higher margins and control quality. This strategy mitigates the threat from emerging specialized material suppliers and regulatory shifts favoring lower-carbon materials.
For New Entrants and Emerging Players: Specialized fabrication services for structural battery packs represent the most penetrable entry point into the automotive sheet metal market. Target emerging EV OEMs in India with tailored lightweighting solutions and localized production capabilities. A go-to-market angle focused on rapid prototyping and co-design for novel EV architectures can differentiate new players. Focus on closed-loop recycling systems for aluminum to align with evolving sustainability mandates.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial groups and traditional steel producers seeking to divest non-core automotive assets. The long-term viability of structural sheet metal remains strong, driven by persistent vehicle lightweighting and EV adoption over the next decade. Seek specialized fabricators with proprietary hydroforming or hot stamping technologies. A specific signal to watch is the increasing number of OEM design wins for structural battery enclosures using advanced aluminum alloys.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced Materials | Increases supply resilience for high-demand AHSS and aluminum alloys crucial for EV platforms. |
| Advanced Forming Technology Investment | Enables production of complex, lightweight components, reducing weld points and assembly costs for OEMs. |
| OEM Co-development Partnerships | Secures long-term contracts and integrates suppliers into early-stage vehicle design cycles. |
| Recycled Material Loop Establishment | Meets stringent emissions regulations and reduces lifecycle carbon footprint for automotive components. |
| Geographic Expansion into India | Captures growth in an underpenetrated automotive market with rising demand for structural components. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. The primary research involved in-depth discussions with automotive OEM platform engineers, Tier-1 procurement leads, material science R&D directors, and regulatory experts across key regions. This qualitative input was triangulated with quantitative data from secondary sources, including industry association reports, government emissions data, corporate financial filings, and patent databases, to ensure comprehensive coverage and accuracy.
The forecast inputs being considered included vehicle production forecasts, material substitution rates, and the evolving content per vehicle for structural sheet metal components. The analytical framework modeled market dynamics across the analysis window, segmenting by product type, application, manufacturing stage, end user, and EV architecture integration. Compound Annual Growth Rates (CAGRs) were derived through a combination of regression analysis and expert consensus, incorporating industry-specific inputs like advanced material adoption curves and regional EV penetration rates.
Practitioners should monitor shifts in commodity prices, new emissions regulations, and breakthroughs in multi-material joining technologies for early signals of forecast revisions. Forecasts reflect assumptions regarding technological evolution and market adoption rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
Drive System Market
Automotive Components
Automotive Connecting Rod Market
Automotive Components
Europe and North Africa Automotive Window Regulator Market
Automotive Components
Automotive Carbon Fiber Composites Parts Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Automotive Door Module Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
Metal Forming for Automotive Market
Automotive Components
Automotive Metal Stamping Components Market
Automotive Components
Automotive Steering Column Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Automotive Exhaust Manifolds Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Automotive Aftermarket for Brake Components Market