
 Europe Automotive Electric Actuators Market | 2026-2036
Europe Automotive Electric Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Electric Actuators Market Foresight
The EU Green Deal is realigning the cost-of-entry calculus for electric actuator suppliers targeting European automotive OEMs. Robert Bosch GmbH leverages its integrated mechatronics division to dominate brushless DC actuator production for powertrain applications. Continental AG sustains R&D intensity across piezoelectric valve control systems, while ZF Friedrichshafen anchors chassis actuator supply through its suspension technology division.
Europe automotive electric actuators are electromechanical devices that convert electrical energy into precise mechanical motion, typically operating at voltages between 12V and 48V with position feedback resolution below 0.1 degrees for powertrain and chassis control functions. These devices enable throttle control, turbo wastegate positioning, active grille shutter operation, and brake-by-wire actuation across passenger and commercial vehicle platforms. Brushless DC technology leads the technology segment due to superior thermal tolerance and maintenance intervals exceeding 10 million cycles, while piezoelectric actuators represent the fastest-growing sub-category for fuel injection and precision valve timing where nanometer-scale positioning accuracy is required. The application segment shows powertrain and driver assistance systems capturing the dominant margin pools as electrification multiplies actuator count per vehicle.
The European Green Deal, Euro 7 standards, and CE marking requirements collectively mandate higher energy efficiency ratings and restricted substance compliance for automotive electric actuators sold across EU member states. EMA and national type-approval authorities in Germany, France, and Italy enforce electromagnetic compatibility and functional safety certifications that determine market access. Stakeholders must monitor how the EU AI Act and impending software-defined vehicle regulations reshape actuator firmware validation requirements and supplier liability frameworks.
Market Dynamics
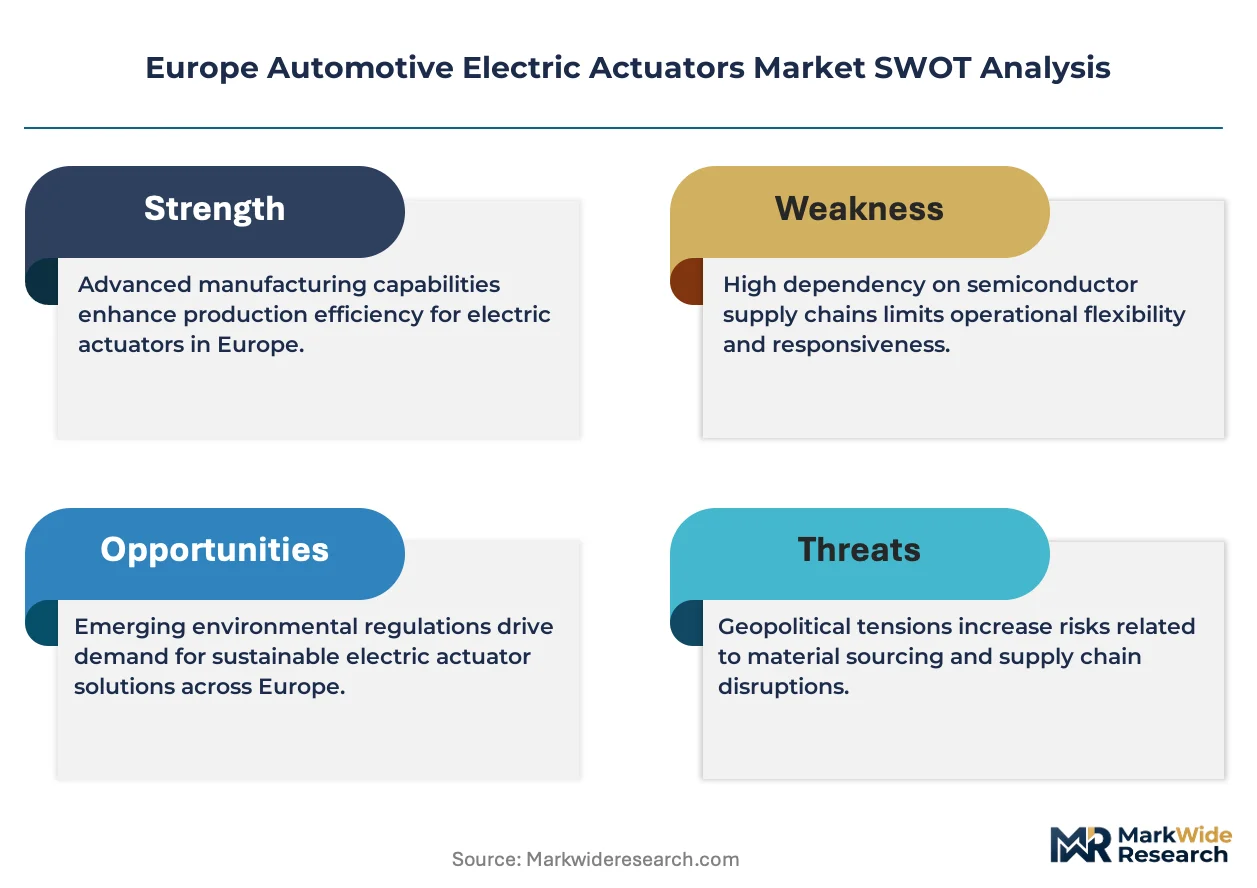
The EU Green Deal and Euro 7 emissions standards are compressing development cycles for electric actuator suppliers serving European automotive OEMs, forcing simultaneous upgrades to energy efficiency ratings and recyclability compliance across powertrain and chassis applications.
Growth Catalysts
- Battery-electric vehicle powertrain electrification:OEMs are multiplying actuator counts per vehicle to manage thermal management valves, active aerodynamics, and brake-by-wire systems. This structural shift expands addressable content per platform.
- EU Green Deal compliance thresholds:Mandatory energy efficiency ratings and restricted substance rules under REACH and RoHS are filtering out lower-tier suppliers, consolidating demand toward certified producers.
- German engineering headquarters concentration:Volkswagen, BMW, and Mercedes-Benz maintain tier-1 supplier ecosystems in Baden-Württemberg and Bavaria, creating localized demand density for precision actuator development.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium dependencies on external processing capacity expose brushless DC actuator producers to input cost volatility and supply interruption risks.
- CE marking and functional safety certification timelines:EMA and KBA type-approval processes for electromagnetic compatibility and ISO 26262 compliance extend product launch cycles by 12-18 months.
- Hydraulic actuator residual preference:Heavy commercial vehicle segments in Eastern Europe continue specifying hydraulic alternatives for high-load chassis applications, limiting electric actuator penetration in truck and bus platforms.
Strategic Opportunities
- Software-defined vehicle firmware validation:The EU AI Act is creating new supplier liability frameworks for actuator control algorithms, opening service revenue streams for cybersecurity-certified firmware developers.
- Piezoelectric fuel injection systems:Nanometer-scale positioning requirements in precision valve timing represent an emerging application white space beyond traditional solenoid architectures.
- Poland and Czech Republic manufacturing expansion:Lower labor cost structures and proximity to German OEM assembly plants are attracting actuator subsystem production for export into Western European supply chains.
Industry Challenges
- Mechatronics engineering talent scarcity:European universities produce insufficient graduates combining electrical machine design, embedded controls, and thermal management expertise to match OEM hiring demand.
- Legacy 12V electrical architecture integration:New 48V actuator designs must maintain backward compatibility with existing vehicle networks, adding validation complexity and hardware cost.
- CSRD supply chain disclosure requirements:Extended producer responsibility mandates force tier-2 and tier-3 suppliers to document carbon intensity and recyclability metrics previously outside audit scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Electric Actuators Market |
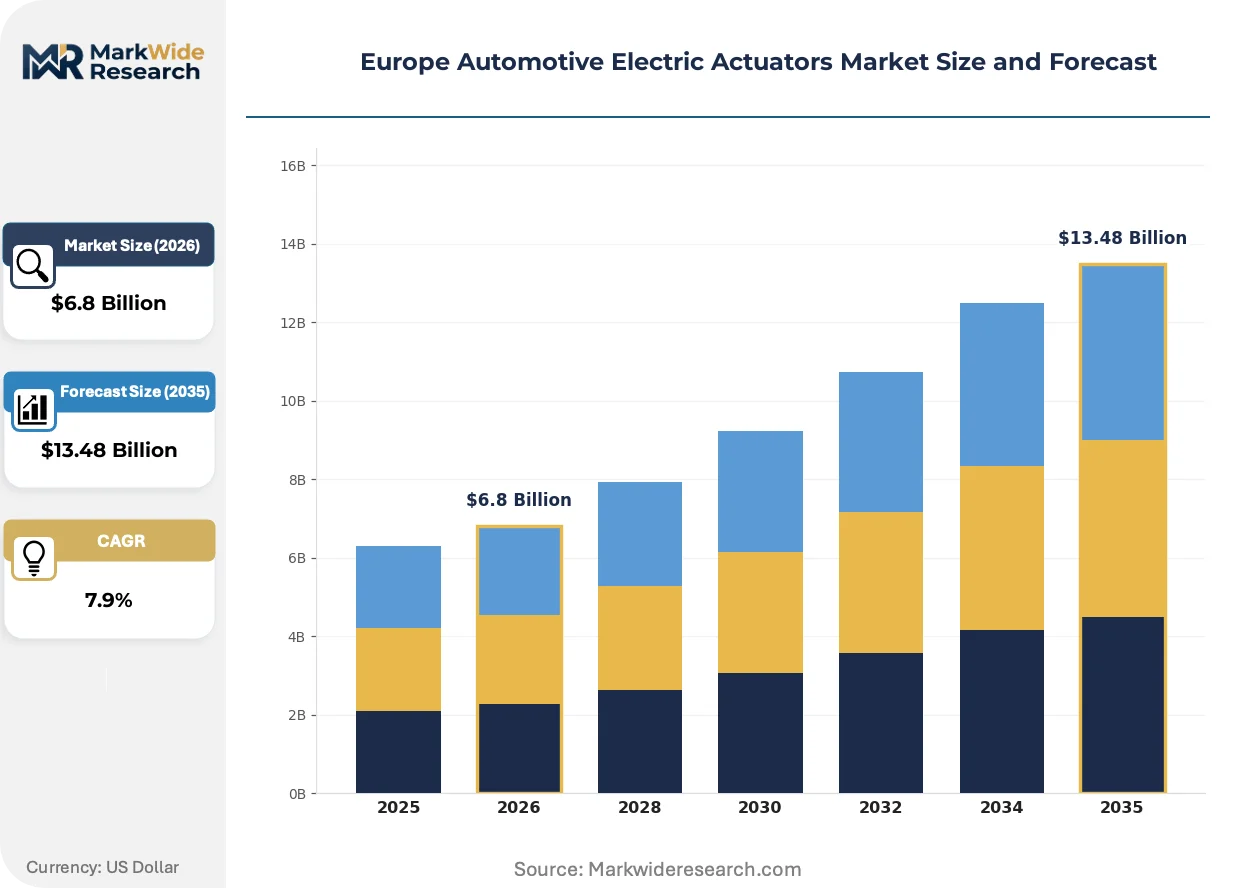
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Brushless DC, Stepper, Linear, Piezoelectric End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Powertrain, Chassis, Body Control, Driver Assistance Installation Type: Integrated, Standalone, Modular, Custom |
| Companies Covered | Wabco Holdings Inc., ZF Friedrichshafen, Continental AG, BorgWarner Inc., Denso Corporation, Robert Bosch GmbH, Sonceboz SA, Johnson Electric, Hella KGaA Hueck & Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Electric Actuators Market Shifts & Advancements
Brushless DC actuator architectures are displacing brushed motor designs across European powertrain applications as thermal tolerance requirements tighten and maintenance interval expectations extend beyond 10 million cycles.
Smart actuator systems with integrated position feedback below 0.1 degrees resolution are integrating edge computing capabilities for real-time diagnostic and predictive maintenance functions. BMW and Mercedes-Benz chassis engineering teams are specifying these units for active suspension and steering systems. This integration is compressing the traditional separation between mechanical actuation and vehicle control software layers.
Euro 7 emissions standards are mandating closed-loop control precision for throttle bodies and turbo wastegates that exceeds prior mechanical system capabilities. The regulation forces suppliers to redesign actuator response algorithms and sensor fusion architectures. Powertrain applications in diesel and gasoline hybrid platforms face the steepest compliance cost increases.
Automotive tier-1 suppliers are unbundling hardware from firmware licensing to capture recurring revenue from over-the-air update services. This model displaces traditional component sales contracts with multi-year software subscription structures. German and French OEM procurement departments are piloting these arrangements for chassis control modules.
Europe Automotive Electric Actuators Market Segmentation
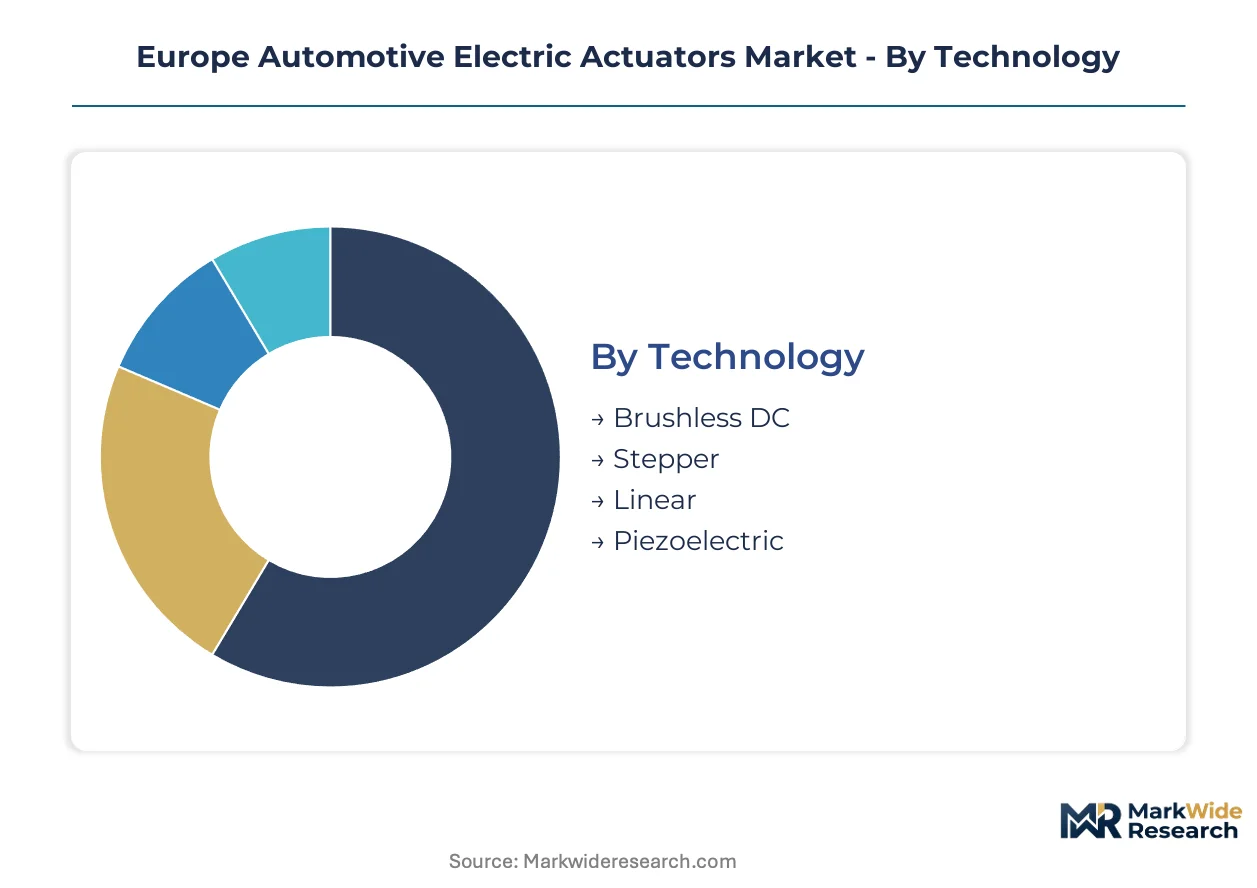
Electric actuator segmentation in Europe reflects the tension between embedded powertrain integration and standalone chassis modules. OEM procurement strategies diverge sharply across these boundaries, with distinct supplier qualification pathways and margin structures governing each configuration.
Technology:
Integration depth varies substantially across motor architectures, with some technologies designed for sealed powertrain embedding and others optimized for accessible chassis mounting.
- Brushless DC:Permanent magnet synchronous motors with Hall-effect position sensing achieve thermal tolerance above 150°C continuous operation. German OEM powertrain divisions in Stuttgart and Munich specify these for turbo wastegate and thermal management valve actuation where maintenance access is impractical.
- Piezoelectric:Ceramic stack actuators deliver nanometer-scale displacement precision through inverse piezoelectric effect. Fuel injection systems at Continental AG and Robert Bosch GmbH development centers exploit this capability for direct injection pressure modulation, climbing the fastest as Euro 7 precision mandates tighten.
- Stepper:Variable reluctance motors with discrete step positioning suit HVAC blend door and headlamp leveling applications.
- Linear:Direct-drive electromagnetic actuators eliminate mechanical conversion losses for active grille shutter and seat adjustment mechanisms.
Brushless DC leads volumes today; piezoelectric is gaining share fastest.
End User:
Procurement authority concentrates differently across the value chain, with specification control shifting from vehicle assemblers to subsystem integrators depending on application complexity.
- Tier-1 Suppliers:Continental AG, ZF Friedrichshafen, and Schaeffler AG maintain captive actuator production for chassis and powertrain modules they deliver to German OEM final assembly. These suppliers control firmware calibration and bear ISO 26262 functional safety liability.
- OEMs:Volkswagen Group, BMW AG, and Mercedes-Benz Group retain in-house actuator development for proprietary drive-by-wire and steer-by-wire architectures where intellectual property protection outweighs supplier economies.
- Vehicle Assemblers:Contract manufacturers in Eastern Europe source standardized actuator subassemblies from regional tier-2 suppliers.
- Aftermarket Providers:Independent distributors serve collision repair and classic vehicle electrification retrofit segments.
Tier-1 suppliers capture the dominant procurement value; OEM direct sourcing is expanding most quickly for software-defined vehicle platforms.
Application:
Actuator density per vehicle escalates dramatically as electrification multiplies thermal management and active aerodynamic control points.
- Powertrain:Battery-electric architectures require actuators for coolant valve routing, active grille shutters, and electric compressor clutch engagement. BMW i-series and Mercedes EQ platforms deploy 8-12 powertrain actuators versus 3-4 in prior internal combustion generations.
- Chassis:Brake-by-wire and active suspension systems demand high-bandwidth position feedback below 0.1 degrees resolution. ZF Friedrichshafen supplies Mercedes-Benz S-Class with integrated chassis actuators combining hydraulic pressure modulation and electromechanical backup.
- Driver Assistance:Lane-keeping and automated parking systems deploy steering column and braking actuators with fail-operational redundancy.
- Body Control:Seat adjustment, window lift, and sunroof mechanisms utilize lower-specification actuator variants.
Powertrain applications dominate unit volumes; chassis systems command the steepest price premiums per actuator.
Installation Type:
Physical packaging determines service accessibility, warranty liability allocation, and supplier integration depth into vehicle electrical architectures.
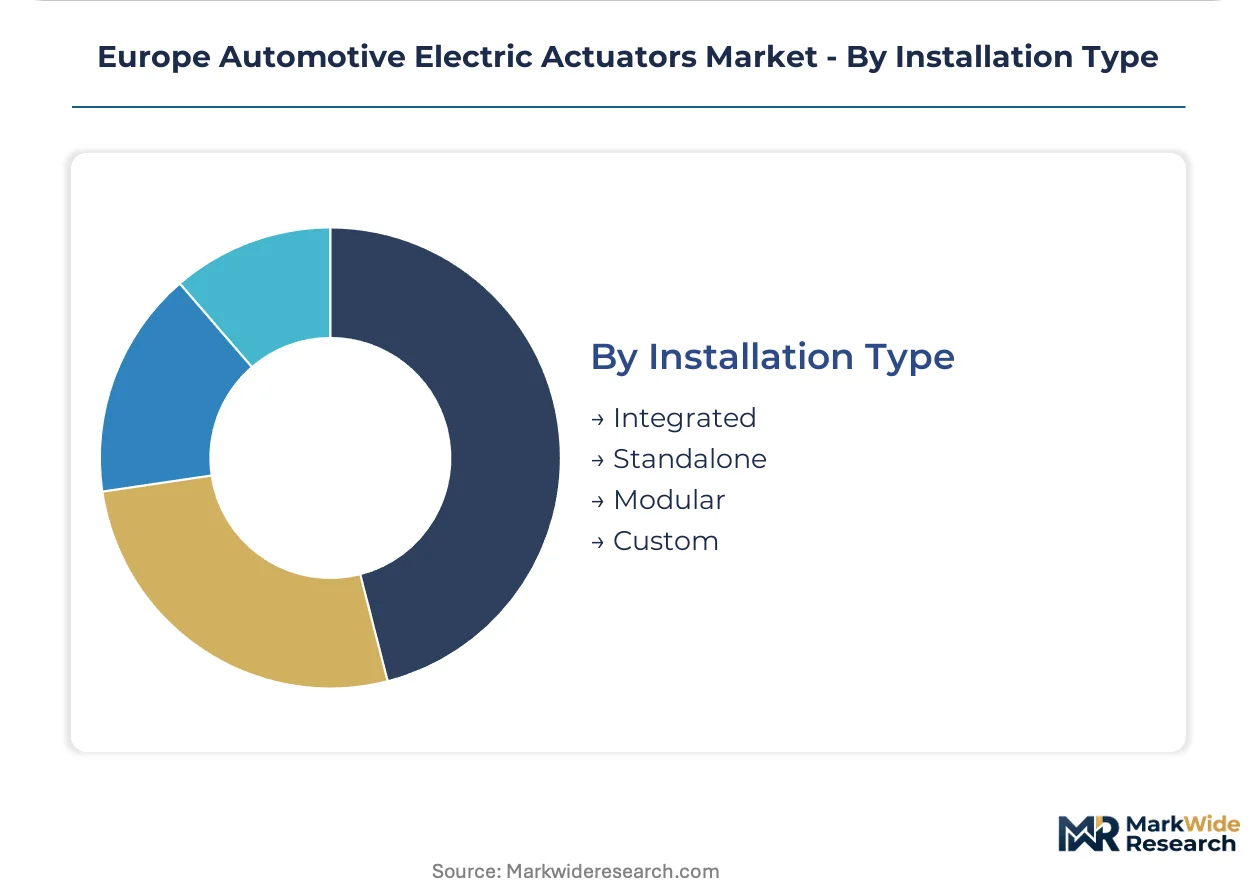
- Integrated:Actuators sealed within transmission housings, battery thermal management manifolds, or steering rack assemblies carry OEM warranty responsibility and demand 15-year design life validation.
- Modular:Self-contained actuator units with standardized electrical connectors and mechanical interfaces enable tier-1 suppliers to serve multiple OEM platforms without redesign.
- Standalone:Discrete actuator packages for aftermarket replacement or low-volume specialty vehicle production.
- Custom:Application-specific mechanical adaptations for commercial vehicle chassis or motorsport derivatives.
Integrated installations lead OEM platform adoption; modular formats are expanding most quickly for multi-brand supplier economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mechatronics engineering talent concentrates in southern Germany, anchoring actuator development clusters across Baden-Württemberg and Bavaria where OEM engineering headquarters and tier-1 supplier ecosystems overlap.
Germany
Volkswagen Group, BMW AG, and Mercedes-Benz Group headquarters in Wolfsburg, Munich, and Stuttgart drive specification authority for precision actuators. KBA enforces type-approval timelines extending 12-18 months for electromagnetic compatibility and ISO 26262 functional safety. Stuttgart engineering corridors host Robert Bosch GmbH and Continental AG development centers for brushless DC powertrain actuators.
France
Renault Group and Stellantis maintain powertrain research centers in Guyancourt and Vélizy-Villacoublay demanding high-resolution position feedback systems. ANSM and national regulators enforce CE marking and REACH substance restrictions on actuator materials. Paris-Saclay technology cluster attracts piezoelectric actuator specialists for fuel injection precision applications.
Italy
Ferrari, Lamborghini, and Maserati supercar manufacturers in Emilia-Romagna specify custom chassis actuators with nanometer-scale positioning for active suspension. EMA coordination with national transport ministry enforces Euro 7 emissions compliance thresholds. Turin automotive engineering corridor sustains Stellantis powertrain development for thermal management valve actuation.
Poland
Lower labor cost structures and proximity to German OEM assembly plants attract actuator subsystem production for export supply chains. EU Green Deal extended producer responsibility mandates require CSRD-aligned carbon intensity documentation from tier-2 suppliers. Wrocław and Poznań manufacturing zones host contract electronics assembly for modular actuator units.
Czech Republic
Škoda Auto operations in Mladá Boleslav generate localized demand for integrated powertrain actuators in battery-electric platforms. National type-approval authorities align with EMA electromagnetic compatibility standards for market access. Ostrava industrial corridor develops metalworking capacity for actuator housing and precision mechanical components.
Europe Automotive Electric Actuators Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology segments. Market structure tilts toward consolidation among integrated mechatronics divisions of large automotive suppliers, though niche ceramic actuator developers retain positioning in precision fuel injection. Three archetypes dominate: diversified tier-1 system integrators, component-specialist mid-caps, and captive OEM engineering divisions. Competitive moves concentrate on firmware licensing unbundling from hardware sales and strategic partnerships for rare earth magnet supply security.
Among diversified tier-1 system integrators, Continental AG and ZF Friedrichshafen occupy positions spanning chassis and powertrain actuator modules, while Robert Bosch GmbH anchors the integrated mechatronics archetype through captive brushless DC production. These three represent the dominant engineering authority shaping OEM procurement specifications across European platforms.
| Leading Market Players |
|---|
| Wabco Holdings Inc. |
| ZF Friedrichshafen |
| Continental AG |
| BorgWarner Inc. |
| Denso Corporation |
| Robert Bosch GmbH |
| Sonceboz SA |
| Johnson Electric |
| Hella KGaA Hueck & Co. |
| Others |
Supply & Pricing Matrix
Captive integration of brushless DC motor production within German tier-1 mechatronics divisions anchors supply positioning and pricing power for powertrain actuators serving Volkswagen, BMW, and Mercedes-Benz platforms. This structural choice insulates qualified suppliers from commodity spot volatility while forcing unbundled firmware licensing premiums that reshape contract economics across the European supply base.
Pricing Analysis
Bundled hardware-firmware contracts dominate legacy chassis and powertrain actuator procurement, though tier-1 suppliers are unbundling firmware licensing to capture recurring revenue from over-the-air update services. Price differentiation stems from ISO 26262 functional safety certification tier and volume scale commitments, with ASIL-D certified actuators commanding substantial premiums over ASIL-B equivalents. Cost compression in standard brushless DC units is intensifying because Polish and Czech manufacturing expansion erodes Western European labor cost advantages. Aftermarket providers exhibit the highest price sensitivity due to fragmented demand and substitute hydraulic actuator availability, while OEM direct-sourcing divisions for steer-by-wire architectures show the least.
Supply Chain Analysis
EU Green Deal extended producer responsibility mandates are reshaping sourcing patterns by requiring CSRD-aligned carbon intensity documentation from tier-2 and tier-3 suppliers previously outside audit scope. Rare earth magnet processing concentrates in China, with neodymium and dysprosium dependencies exposing brushless DC actuator producers to supply interruption risks. Permanent magnet alloys, Hall-effect position sensors, and ceramic stack substrates for piezoelectric units draw from specialized metallurgical and semiconductor supply chains. Single-source vulnerability around rare earth separation capacity represents the dominant structural risk. Distribution runs through captive tier-1 supplier networks into German OEM assembly plants, with modular actuator formats enabling multi-brand platform supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Polish manufacturing cost structures and German OEM specification authority defines viable entry strategies, as EU Green Deal compliance thresholds filter out uncertified competitors while lower labor costs in Eastern Europe compress delivered unit economics.
For Market Incumbents: Acquire firmware validation capabilities and cybersecurity-certified engineering talent to defend against software-defined vehicle liability shifts under the EU AI Act. Deepen backward integration into rare earth magnet supply through strategic offtake agreements with European processing ventures. Prioritize ASIL-D certification investment for brake-by-wire and steer-by-wire architectures where OEMs retain in-house development to protect intellectual property. For New Entrants and Emerging Players: Commercial vehicle aftermarket retrofit segments in Eastern Europe present the most penetrable white space, with hydraulic-to-electric actuator conversion demand outpacing certified supplier coverage. Target piezoelectric fuel injection subsystems for Euro 7 compliance upgrades where nanometer-scale positioning requirements exceed legacy solenoid capabilities. Pursue tier-2 supplier qualification pathways through Polish contract manufacturing zones serving German OEM export supply chains. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap ceramic actuator specialists because precision fuel injection consolidation lags brushless DC powertrain actuator concentration. Five-to-ten year viability hinges on software-defined vehicle firmware licensing revenue streams displacing pure hardware sales. Monitor EU AI Act implementation timelines as the critical inflection signal for supplier liability framework maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Supply Security Partnership | Mitigates neodymium dependency exposure through European processing joint ventures with OEM backing. |
| Software-Defined Vehicle Firmware Investment | Positions tier-1 suppliers for recurring revenue under EU AI Act liability frameworks. |
| Poland Manufacturing Footprint Expansion | Captures labor cost arbitrage for modular actuator export into German OEM supply chains. |
| Piezoelectric Precision Technology Licensing | Addresses Euro 7 nanometer-scale valve timing mandates beyond conventional solenoid reach. |
| CSRD-Aligned Supply Chain Certification | Satisfies extended producer responsibility mandates filtering uncertified tier-2 competitors. |
Research Methodology
Multiple input streams — primary interviews with tier-1 supplier procurement officers, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, EMA type-approval filings, and IHS Markit registration data; plus customs and trade flow records — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations spanned engineering directors at Robert Bosch GmbH and Continental AG development centers, KBA certification officials, and Polish contract manufacturing operators in Wrocław and Poznań.
Data-stream reconciliation across the projection horizon applied vehicle-class, propulsion-architecture, and content-per-vehicle segmentation dimensions to model addressable actuator demand. CAGRs were derived from platform-level build-rate projections and electrification-driven actuator density escalation, with brushless DC thermal tolerance requirements and piezoelectric precision adoption curves serving as primary forecast inputs.
Underlying measurement precision varies by segment; integrated powertrain installations carry tighter precision than aftermarket retrofit estimates due to OEM platform visibility. Forecasts reflect documented assumptions around EU Green Deal implementation pace and rare earth supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Cigarette Lighters Market
Automotive Components
Automotive Plastic Components Market
Automotive Components
United States Automotive Pneumatic Actuators Market
Automotive Components
Germany Automotive Composites Market
Automotive Components
India Automotive Sunroof Market
Automotive Components
Automotive Rear End Module Market
Automotive Components
Automotive Retarders Market
Automotive Components
Automotive Connecting Rod Bearing Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Global Automotive Condenser Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
Europe Automotive Pneumatic Actuators Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Automotive Key Market
Automotive Components
Global Automotive Gearbox Market