
 Drive System Market | 2026-2036
Drive System Market Size, Share, and Industry Trends Forecast 2026-2036
Drive System Market Analysis
Electrification of power transmission architectures is reshaping how drive systems are engineered for heavy-duty applications. National Oilwell Varco leverages integrated drilling packages to anchor its position in offshore energy drive systems. Aker Solutions competes through subsea actuator specialization that sustains premium positioning in harsh-environment deployments. Honghua Group dominates land-based rig drive manufacturing with vertical integration into gearbox and motor production.
A drive system comprises motor, gearbox, actuator, and controller subassemblies engineered to convert, modulate, and deliver mechanical power across specified torque and speed parameters, typically operating at efficiency thresholds above 85 percent in industrial configurations. Electric technology leads the technology dimension as end-users retrofit hydraulic infrastructure to meet tightening efficiency mandates, while pneumatic systems retain niche dominance in explosive-atmosphere manufacturing environments. High power and ultra high power ratings capture concentrated margin pools in aerospace and heavy robotics applications where thermal management and precision control command engineering premiums.
FAA airworthiness standards, EPA industrial emissions frameworks, and EU Green Deal carbon intensity benchmarks collectively tighten efficiency and material disclosure requirements across drive system supply chains. China's MIIT enforces GB efficiency standards that restrict market access for non-compliant motor and gearbox imports. Stakeholders must monitor evolving carbon border adjustment mechanisms and efficiency tier migrations to anticipate procurement specification shifts before they harden into contract requirements.
Market Dynamics
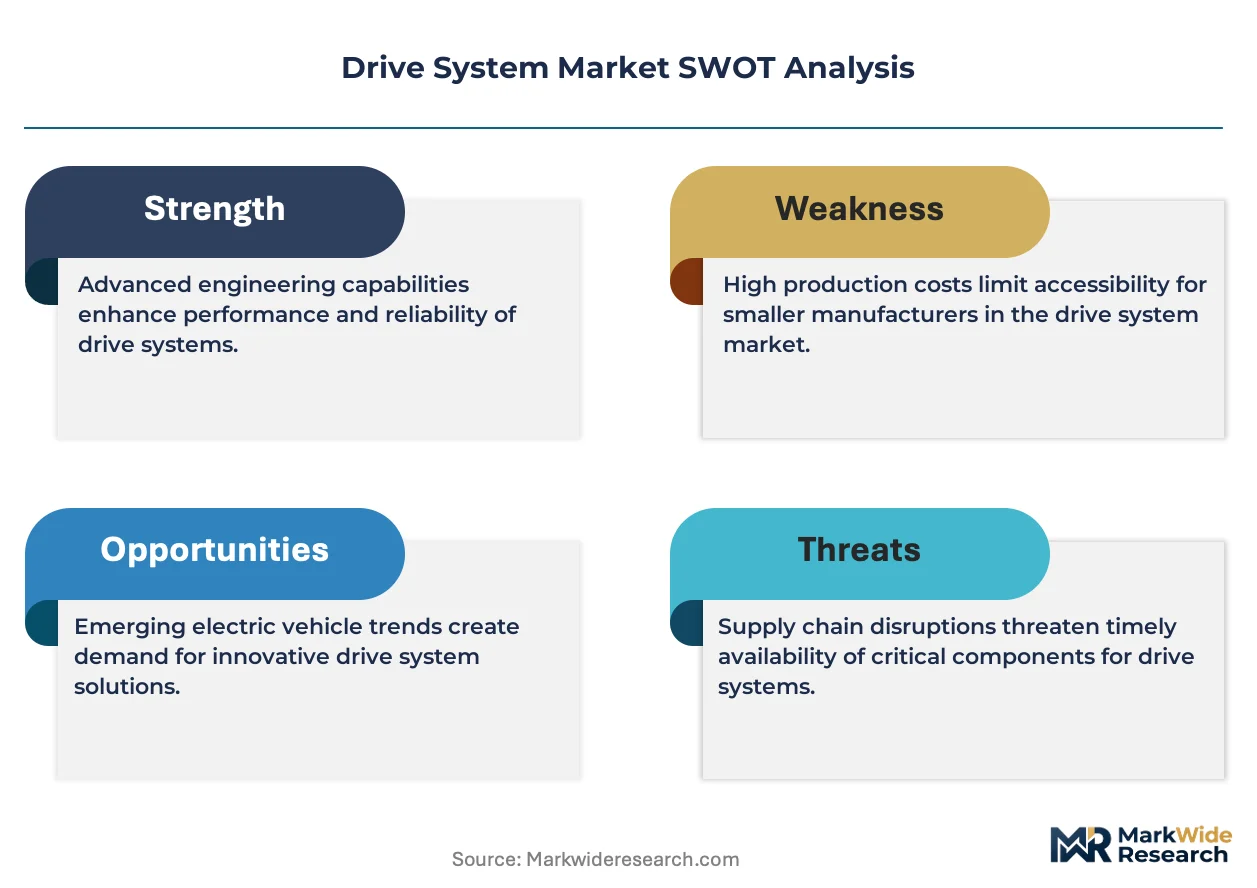
Electrification mandates and carbon border adjustments are compressing demand for hydraulic drive architectures while amplifying procurement volumes for integrated electric drivetrains across automotive, robotics, and energy extraction clusters.
Growth Catalysts
- EU Green Deal industrial benchmarks:Carbon intensity thresholds for power transmission equipment are accelerating facility retrofits in German automotive manufacturing corridors.
- GB efficiency standards enforcement:China's MIIT restrictions on non-compliant motor imports are creating captive demand for domestic and certified foreign suppliers.
- Robotics cluster densification:Precision torque requirements in heavy robotics applications are pulling ultra high power drive system procurement volumes in Shenzhen and Detroit.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet motor production depends on Chinese and Myanmar-sourced neodymium, creating geopolitical input vulnerability.
- FAA airworthiness certification timelines:Aerospace drive system approvals require 18-36 month validation cycles that freeze supplier switching.
- Hydraulic infrastructure lock-in:Existing capital stock in offshore energy and heavy construction sustains incumbent technology through replacement cycle inertia.
Strategic Opportunities
- India PLI scheme for advanced manufacturing:Production-linked incentives for automotive and industrial machinery are attracting drive system assembly investments in Tamil Nadu and Gujarat.
- Subsea actuator integration:Convergence of electric actuation with subsea power distribution is opening premium positioning in Norwegian and Brazilian offshore fields.
- Direct-to-OEM digital channels:Configurator platforms that bypass distributor networks are capturing specification influence in mid-volume robotics procurement.
Industry Challenges
- Power electronics thermal management expertise:SiC and GaN inverter design capabilities remain concentrated among semiconductor specialists, creating talent scarcity for traditional mechanical suppliers.
- Legacy hydraulic-electric integration complexity:Hybrid architectures in retrofit heavy equipment require simultaneous control of dissimilar power domains, extending commissioning timelines.
- Multi-jurisdictional efficiency tier mapping:Suppliers must maintain parallel product lines to satisfy EPA, EU Ecodesign, and GB standard divergence without scale penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drive System Market |
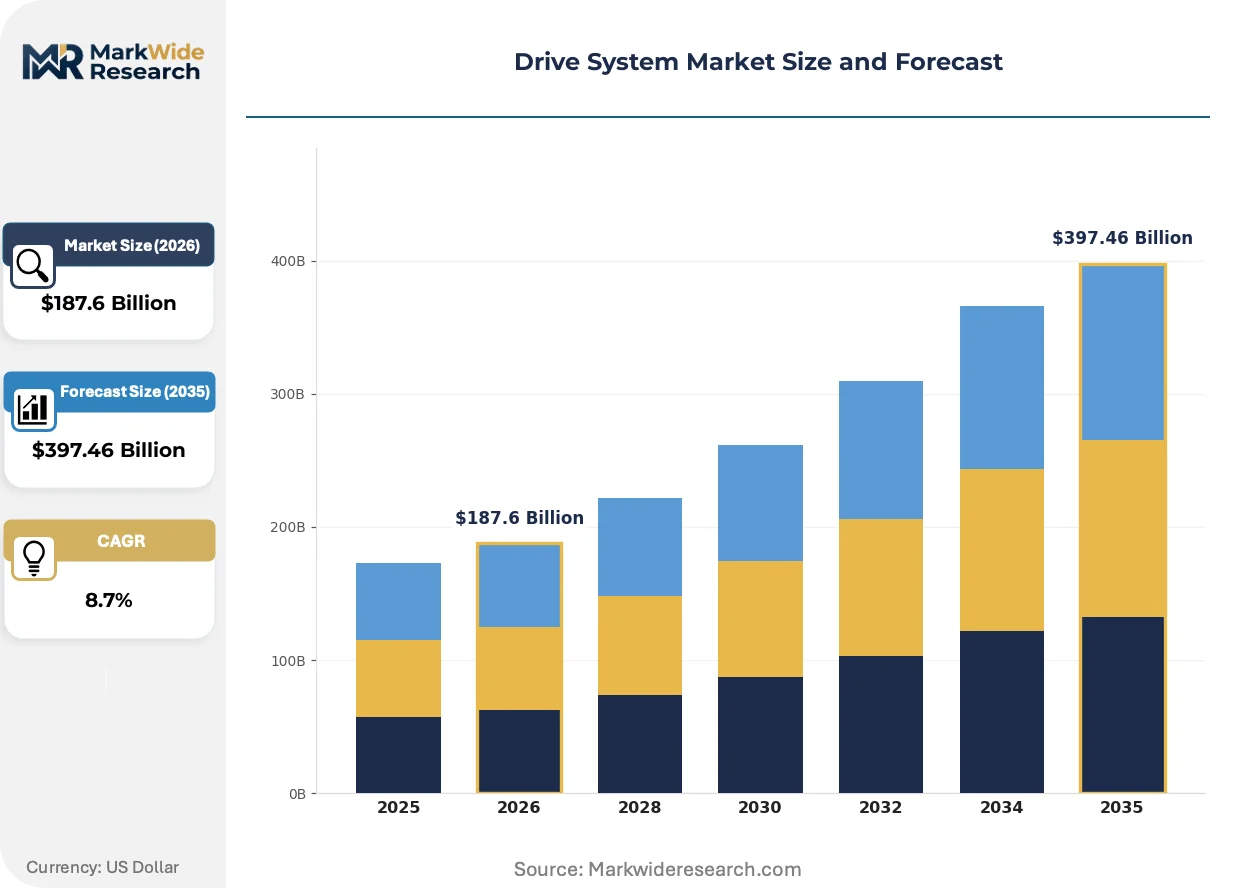
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $397.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electric, Hydraulic, Pneumatic, Mechanical Component: Motor, Gearbox, Actuator, Controller Application: Automotive, Aerospace, Manufacturing, Robotics Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Cameron International Corporation, Axon Energy Products, National Oilwell Varco, Honghua Group, Bentec GMBH Drilling and Oilfield Systems, Canrig Drilling Technology, Aker Solutions, Warrior Manufacturing Service, Tesco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drive System Market Emerging Trajectories
Silicon carbide power electronics and integrated thermal architectures are compressing the efficiency-performance tradeoff that historically separated electric from hydraulic drive solutions in heavy-duty applications.
SiC-based inverter modules are migrating from premium aerospace and motorsport applications into mainstream industrial drive systems. Mining equipment OEMs in Western Australia and Chilean copper extraction operations are piloting 800V architectures that slash cooling system mass. This voltage migration from 400V class infrastructure is enabling power density improvements that compress footprint requirements for underground and space-constrained installations.
The EU F-Gas Regulation phase-down is accelerating refrigerant transitions in drive system thermal management circuits. Industrial motor-integrated cooling systems face redesign cycles to accommodate lower-GWP working fluids before 2030 bans harden. German gearbox manufacturers are responding with sealed-for-life lubrication architectures that eliminate external cooling dependencies in mid-power ratings.
Specification authority is consolidating among automotive OEM procurement centers that now dictate drive system architecture for shared robotics and automation platforms. Tier-2 component suppliers in Stuttgart, Shanghai, and Detroit are bypassing traditional distributor relationships to embed engineers directly within customer technical centers. This channel compression is most visible in electric vehicle battery assembly line procurement, where line integrators have lost specification influence to OEM captive engineering teams.
Drive System Market Segmentation
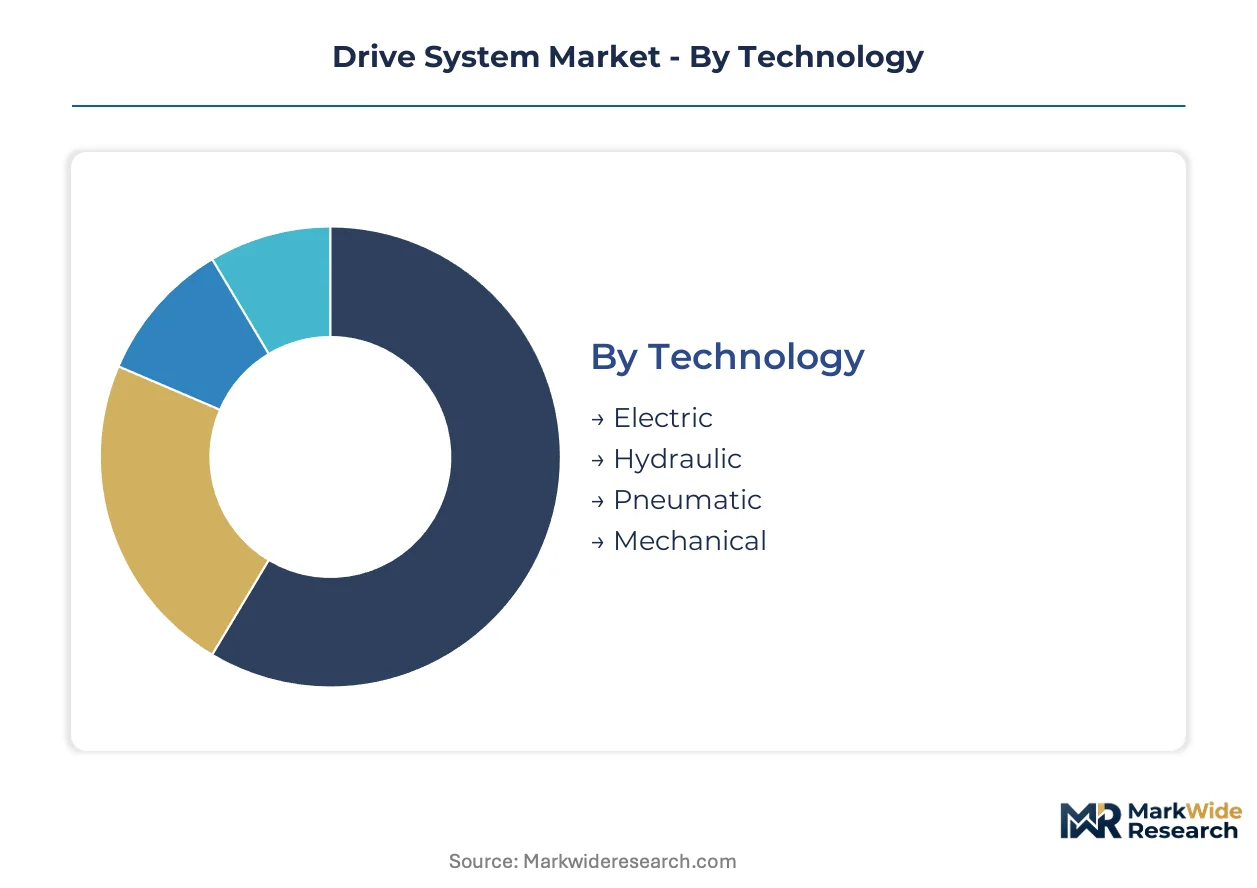
Drive system procurement cycles vary dramatically by underlying technology and end-use application, with automotive electrification programs refreshing specifications every 24-36 months while aerospace platforms lock designs for 15-20 year lifespans. Component-level segmentation reveals where suppliers can capture recurring revenue through replacement wear items versus capital-intensive system sales. Understanding these velocity differentials enables portfolio balancing between stable aftermarket income and high-growth new equipment attachment.
Technology:
Replacement cycles stretch from months for pneumatic seal kits to decades for integrated electric drivetrains, creating fundamentally different cash flow profiles across technology suppliers.
- Electric:Permanent magnet and induction motor architectures dominate new industrial and automotive installations. EPA emissions enforcement and EU Green Deal carbon intensity benchmarks are accelerating facility retrofits in German automotive corridors and Shenzhen manufacturing parks. SiC inverter adoption is compressing the efficiency gap that previously favored hydraulic solutions in heavy-duty mining and construction.
- Hydraulic:Fluid power systems retain installed base dominance in offshore energy extraction and heavy construction where infrastructure replacement inertia sustains demand. Existing capital stock in Norwegian North Sea operations and Western Australian iron ore sites generates recurring seal, hose, and pump replacement revenue with 3-5 year cycle times.
- Pneumatic:Compressed air systems maintain explosive-atmosphere manufacturing dominance where electrical spark hazards prohibit motor deployment. Food processing facilities in the United States and pharmaceutical cleanrooms in Germany specify pneumatic actuators for intrinsic safety compliance with shorter 18-24 month maintenance intervals.
- Mechanical:Direct mechanical linkages persist in cost-sensitive applications with minimal control complexity requirements. Agricultural equipment in India and basic material handling in Brazil leverage mechanical drivetrains for capital efficiency where precision modulation is unnecessary.
Electric systems anchor the volume base while pneumatic solutions gain share at the steepest rate in safety-critical process industries.
Component:
Margin concentration follows functional criticality, with control electronics capturing premium pricing while commodity motors face procurement consolidation.
- Motor:Electromechanical energy conversion subassemblies range from fractional horsepower induction units to multi-megawatt permanent magnet synchronous machines. Rare earth magnet supply concentration in Chinese and Myanmar-sourced neodymium creates input cost volatility for high-performance variants specified in robotics and aerospace.
- Gearbox:Speed-torque transformation systems divide between precision planetary configurations for robotics and heavy-duty epicyclic architectures for mining haul trucks. German manufacturers are responding to EU F-Gas Regulation phase-downs with sealed-for-life lubrication that eliminates external cooling dependencies in mid-power ratings.
- Actuator:Linear and rotary motion output devices bridge power conversion to mechanical work. Subsea actuator integration with electric power distribution is opening premium positioning in Norwegian and Brazilian offshore fields where hydraulic umbilical replacement costs drive specification shifts.
- Controller:Power electronics and embedded control systems command the highest value-add per kilogram in drive system bill-of-materials. SiC and GaN inverter design capabilities remain concentrated among semiconductor specialists, creating talent scarcity for traditional mechanical suppliers attempting vertical integration.
Controllers extract the steepest price premiums while motors generate the largest absolute revenue pools through volume scale.
Application:
End-use diversification determines exposure to cyclical capital spending patterns and regulatory compliance intensities.
- Automotive:Electric drivetrain adoption is accelerating as OEMs phase out hydraulic alternatives in favor of integrated motor-gearbox-controller modules. Procurement specification authority is consolidating among Stuttgart, Shanghai, and Detroit engineering centers that now dictate architecture for shared robotics and automation platforms.
- Aerospace:FAA airworthiness certification timelines require 18-36 month validation cycles that freeze supplier switching and sustain incumbent positions. More electric aircraft initiatives are displacing hydraulic flight control actuators with electromechanical alternatives in next-generation platforms.
- Manufacturing:Factory automation retrofit cycles are compressing as EU Ecodesign efficiency tiers and China's GB standards force equipment replacement. GB efficiency standards enforcement by MIIT is creating captive demand for domestic and certified foreign motor and gearbox suppliers.
- Robotics:Precision torque requirements in heavy robotics applications are pulling ultra high power drive system procurement volumes in Shenzhen and Detroit clusters. Direct-to-OEM digital configurators are capturing specification influence in mid-volume robotics procurement by bypassing traditional distributor networks.
Automotive applications anchor the volume base while robotics gains share at the steepest rate through precision motion control requirements.
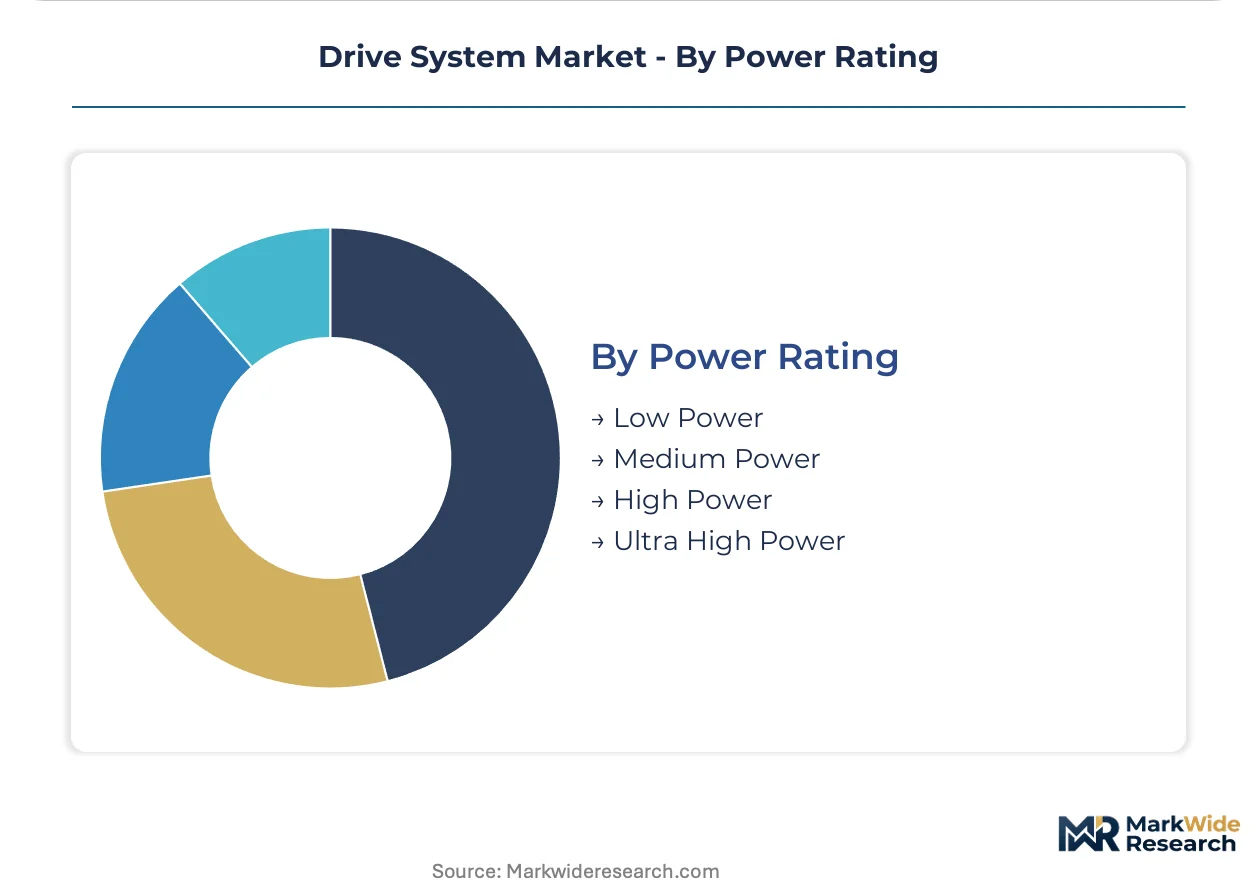
Power Rating:
Engineering complexity and thermal management challenges escalate non-linearly with power density, creating tiered competitive moats.
- Low Power:Fractional horsepower systems serve consumer appliances, small automation cells, and light material handling. Standardized product platforms and distributor-centric sales models dominate this commoditized segment with limited differentiation opportunity.
- Medium Power:Industrial motor ratings from 1-100kW capture the broadest addressable market across manufacturing and process industries. China's MIIT GB efficiency standards are segmenting this tier into compliant and non-compliant supply pools with diverging market access.
- High Power:Heavy industrial and transportation applications demand integrated thermal architectures and precision control capabilities. Mining equipment OEMs in Western Australia and Chilean copper extraction operations are piloting 800V architectures that slash cooling system mass.
- Ultra High Power:Aerospace propulsion and heavy robotics applications command engineering premiums for thermal management and precision control. FAA certification requirements and specialized manufacturing capabilities restrict viable supplier pools to established aerospace-tier vendors.
Medium power ratings anchor the volume base while ultra high power configurations gain share at the steepest rate through aerospace electrification and heavy robotics densification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German drive system exports flow into automotive manufacturing corridors across the United States and China, establishing a trade-flow corridor that anchors transatlantic and transpacific procurement patterns for precision power transmission equipment.
United States
EPA emissions enforcement accelerates hydraulic-to-electric retrofits in Detroit automotive clusters and Houston energy equipment manufacturing. The FAA mandates 18-36 month airworthiness certification timelines that freeze supplier switching in aerospace drive systems. Dallas-Fort Worth robotics densification pulls ultra high power drive procurement volumes for precision automation platforms.
Germany
EU Green Deal industrial benchmarks force efficiency tier migrations across Stuttgart and Munich automotive engineering centers. The EU F-Gas Regulation phase-down accelerates refrigerant transitions in drive system thermal management circuits before 2030. Baden-Württemberg gearbox manufacturers respond with sealed-for-life lubrication architectures that eliminate external cooling dependencies.
China
MIIT GB efficiency standards enforcement creates captive demand for domestic motor and gearbox suppliers while restricting non-compliant imports. Shenzhen and Shanghai robotics clusters anchor procurement volumes for precision torque systems in heavy automation applications. Yangtze River Delta manufacturing corridors concentrate electric drivetrain assembly investments driven by dual carbon goals implementation.
Japan
METI industrial efficiency directives accelerate facility retrofits in Nagoya automotive manufacturing and Osaka robotics production hubs. JIS standards compliance requirements segment domestic procurement pools between certified and non-certified supplier tiers. Kanto region precision engineering clusters sustain demand for ultra high power configurations in aerospace and semiconductor equipment applications.
India
PLI scheme production-linked incentives attract drive system assembly investments in Tamil Nadu and Gujarat automotive manufacturing corridors. BIS efficiency standards enforcement creates compliance barriers for uncertified motor and gearbox imports. Pune industrial automation clusters generate concentrated demand for medium power ratings in factory retrofit cycles.
Drive System Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered competitive positions. Integrated drilling package providers anchor offshore energy segments while subsea actuator specialists capture premium positioning in harsh-environment deployments. Three archetypes dominate: full-system integrators, component-specialist suppliers, and regional manufacturing champions. Competitive moves concentrate on strategic partnerships for technology access and geographic expansion into PLI-subsidized manufacturing corridors.
Among energy-sector system integrators, National Oilwell Varco and Aker Solutions exemplify contrasting positioning archetypes. National Oilwell Varco occupies the integrated drilling package tier with full-system capabilities spanning offshore energy applications. Aker Solutions represents the subsea specialization vector with premium positioning in harsh-environment actuator deployments. Honghua Group anchors the regional manufacturing champion archetype with land-based rig drive production concentration. Cameron International Corporation sits within the diversified industrial technology tier with broad power transmission exposure.
| Leading Market Players |
|---|
| Cameron International Corporation |
| Axon Energy Products |
| National Oilwell Varco |
| Honghua Group |
| Bentec GMBH Drilling and Oilfield Systems |
| Canrig Drilling Technology |
| Aker Solutions |
| Warrior Manufacturing Service |
| Tesco Corporation |
| Others |
Supply Flow & Price Mechanics
Rare earth magnet supply concentration in Chinese and Myanmar-sourced neodymium determines both pricing tier spreads and supply chain shape across electric drive system manufacturing. This single-source dependency for permanent magnet motors compresses margins in high-performance variants while amplifying procurement premiums for certified alternative sourcing.
Pricing Analysis
The 400V-to-800V voltage migration pricing gap separates current-generation industrial drives from next-generation SiC-based architectures. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with EPA Tier 4 and EU Ecodesign compliance commanding substantial markups. Pricing pressure stems from Chinese MIIT GB efficiency standards enforcement that segments medium-power motors into compliant and non-compliant pools with diverging market access. Automotive OEM procurement centers exhibit lowest price sensitivity due to specification authority consolidation, while Indian agricultural equipment buyers remain most cost-responsive.
Supply Chain Analysis
Neodymium and dysprosium feedstock draws from Chinese rare earth processing dominance and Myanmar mining operations, with German gearbox casting and Japanese precision machining providing downstream component specialization. Raw material dependencies center on rare earth magnet alloys, silicon carbide substrates, and high-grade electrical steel laminations. Single-source vulnerability concentrates in Chinese rare earth oxide refining capacity, where export licensing fluctuations cascade through permanent magnet motor pricing. Distribution runs through automotive OEM captive technical centers and robotics integrator direct channels, bypassing traditional industrial distributor networks in high-specification segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric drivetrain retrofit cycles in heavy industrial infrastructure represent an early-cycle expansion story, with EU Green Deal carbon intensity benchmarks accelerating facility replacement timelines beyond historical replacement inertia.
For Market Incumbents: Pre-empt SiC inverter capability gaps by acquiring semiconductor design talent or partnering with power electronics specialists before automotive OEMs consolidate specification authority. Defend against hydraulic-to-electric substitution threats by embedding engineering teams within Detroit and Stuttgart technical centers. Prioritize backward integration into rare earth magnet recycling to offset Chinese supply concentration vulnerability.
For New Entrants and Emerging Players: Establish a beachhead in Indian PLI-subsidized assembly corridors for medium-power industrial motors, where BIS efficiency standards create compliance barriers for uncertified imports. Target subsea actuator integration in Norwegian offshore fields, where hydraulic umbilical replacement costs drive specification shifts toward electric alternatives. Pursue direct-to-OEM digital configurator platforms to bypass entrenched distributor relationships in mid-volume robotics procurement.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors component-specialist suppliers with SiC inverter design capabilities over legacy mechanical gearbox manufacturers. Long-term viability over the next decade hinges on positioning upstream of automotive and robotics OEM specification locks. Acquisition target archetype: precision gearbox manufacturers with sealed-for-life lubrication IP and existing EU Ecodesign certification. Monitor FAA airworthiness certification timeline compression as an inflection indicator for aerospace-tier supplier switching feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| SiC Inverter Capability Acquisition | Power electronics talent scarcity in Stuttgart and Detroit technical centers accelerates specialist firm valuations. |
| Subsea Electric Actuator Integration | Norwegian and Brazilian offshore operators face hydraulic umbilical replacement cost pressure driving specification migration. |
| Rare Earth Magnet Recycling Investment | Chinese export licensing volatility creates captive supply premiums for circular feedstock processing. |
| Direct-to-OEM Digital Configurator Launch | Mid-volume robotics procurement in Shenzhen and Detroit bypasses distributor specification influence. |
| Sealed-for-Life Gearbox Architecture | EU F-Gas Regulation phase-down eliminates external cooling dependencies in Baden-Württemberg manufacturing. |
Methodological Framework
Cross-validation between primary interviews with drive system procurement managers and secondary validation through customs trade data anchors the qualitative findings. Stakeholder engagement spanned maintenance directors at Western Australian mining operations, OEM platform engineers in Stuttgart and Detroit, aftermarket service heads at German gearbox manufacturers, and robotics integrators in Shenzhen. Secondary sources included SEC 10-K filings from listed industrial technology suppliers, MIIT GB standard enforcement notices, EU Ecodesign directive implementation reports, and IHS Markit vehicle production databases. Bottom-up unit economics triangulated against top-down market sizing across technology, component, and application segmentation dimensions.
Calibration against historical efficiency standard adoption curves and automotive electrification program timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include electric-hydraulic-pneumatic technology tiers, motor-gearbox-actuator-controller component categories, automotive-aerospace-manufacturing-robotics applications, and low-medium-high-ultra power ratings. CAGRs derived from installed base replacement velocity analysis and new equipment attachment rates in electrification retrofit cycles. Industry-specific inputs encompassed FAA certification timeline distributions, rare earth magnet price volatility bands, and PLI scheme subsidy phase-out schedules.
Stress conditions across neodymium supply disruption scenarios, EPA emissions enforcement intensity variations, and EU carbon border adjustment implementation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology substitution elasticities and regulatory compliance cost pass-through rates. Cross-checking against IEA industrial efficiency investment tracking and OEM electrification capex disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Electric Vehicle Fluid Lubricants Market
Automotive Components
Automotive Glass Market
Automotive Components
Global Automotive Structural Sheet Metal Market
Automotive Components
Automotive Hubcaps Market
Automotive Components
Global Automotive Gearbox Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Automotive Seat Frame Market
Automotive Components
Active Suspension Damper Actuator Systems Market
Automotive Components
Automotive Buffers Market
Automotive Components
Automotive Gear Oil Market
Automotive Components
Automotive Subframe Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Automotive Straps Market
Automotive Components
Automotive Brake System and Components Market