
 Advanced Automotive Materials Market | 2026-2036
Advanced Automotive Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Automotive Materials Market Outlook
ISO 26262 functional safety certification is reorganizing supplier hierarchies in the advanced automotive materials sector. Voestalpine AG leverages its integrated steelmaking complex in Austria to supply high-strength press-hardened grades for battery enclosures. Novelis Inc. anchors North American aluminum sheet supply through its recycling-intensive rolling network. Gestamp Automoción S.A. specializes in hot-stamped structural solutions that compete on crash-performance metrics across European OEM programs.
Advanced automotive materials encompass engineered substrates including aluminum alloys, carbon fiber reinforced polymers, high-performance thermoplastics, and multi-material composites designed to achieve specific strength-to-weight ratios above 150 MPa/(g/cm³). These materials primarily serve vehicle lightweighting mandates that preserve structural integrity while offsetting battery mass in electrified platforms. Carbon fiber applications command premium positioning in motorsport and limited-production EV architectures where tooling amortization tolerates higher per-kilogram costs. Aluminum dominates volume throughput across structural components and exterior panels due to mature recycling infrastructure and established OEM stamping compatibility. Plastics and composites represent the fastest-expanding material category within interior parts where design flexibility and acoustic damping properties justify process complexity.
The EPA, EU Green Deal framework, and China's MIIT dual carbon goals collectively mandate lifecycle emissions accounting that extends from raw material extraction through end-of-vehicle recycling. REACH substance restrictions and evolving ELV directives in Europe are forcing reformulation of certain polymer stabilizers and surface treatments. Stakeholders must monitor how battery pack architectures reshape material specifications for fire containment and thermal runaway protection.
Market Dynamics
Battery pack architectures are forcing material suppliers to reformulate substrates for thermal runaway containment, compressing development cycles and rewiring qualification protocols across OEM supply chains.
Growth Catalysts
- EU Green Deal lifecycle mandates:Full carbon accounting from extraction to recycling is accelerating closed-loop aluminum and polymer recovery investments across European stamping operations.
- MIIT dual carbon targets:China's domestic OEMs are retooling assembly lines for high-strength steel and CFRP-intensive platforms to meet stringent fleet efficiency thresholds.
- Press-hardened steel adoption:Hot-stamped structural grades are penetrating B-pillar and roof rail applications as EV crash-performance requirements intensify.
Market Restraints
- Primary aluminum cost volatility:Smelter energy costs in China and Iceland are transmitting price instability into sheet and extrusion supply contracts.
- Carbon fiber supply concentration:Precursor and oxidation capacity clusters in Japan and the United States create single-source vulnerability for motorsport and limited-production EV programs.
- REACH substance restrictions:Reformulation of polymer stabilizers and chrome-free surface treatments is extending qualification timelines for European interior component suppliers.
Strategic Opportunities
- India PLI scheme for auto components:Domestic aluminum casting and polymer compounding capacity is attracting tooling investment for export-oriented EV platform supply.
- Battery enclosure multi-material bonding:Structural adhesives joining aluminum extrusions to steel reinforcements are opening specification windows for hybrid substrate specialists.
- IRA clean vehicle credits:North American content requirements are reshoring magnesium and rare earth processing for lightweight powertrain housings.
Industry Challenges
- ISO 26262 functional safety certification:Battery enclosure material suppliers face 18-24 month qualification cycles for traceability and failure-mode documentation.
- Multi-material joining expertise:Dissimilar metal corrosion and adhesive durability testing require capital-intensive R&D infrastructure that mid-tier stampers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Automotive Materials Market |
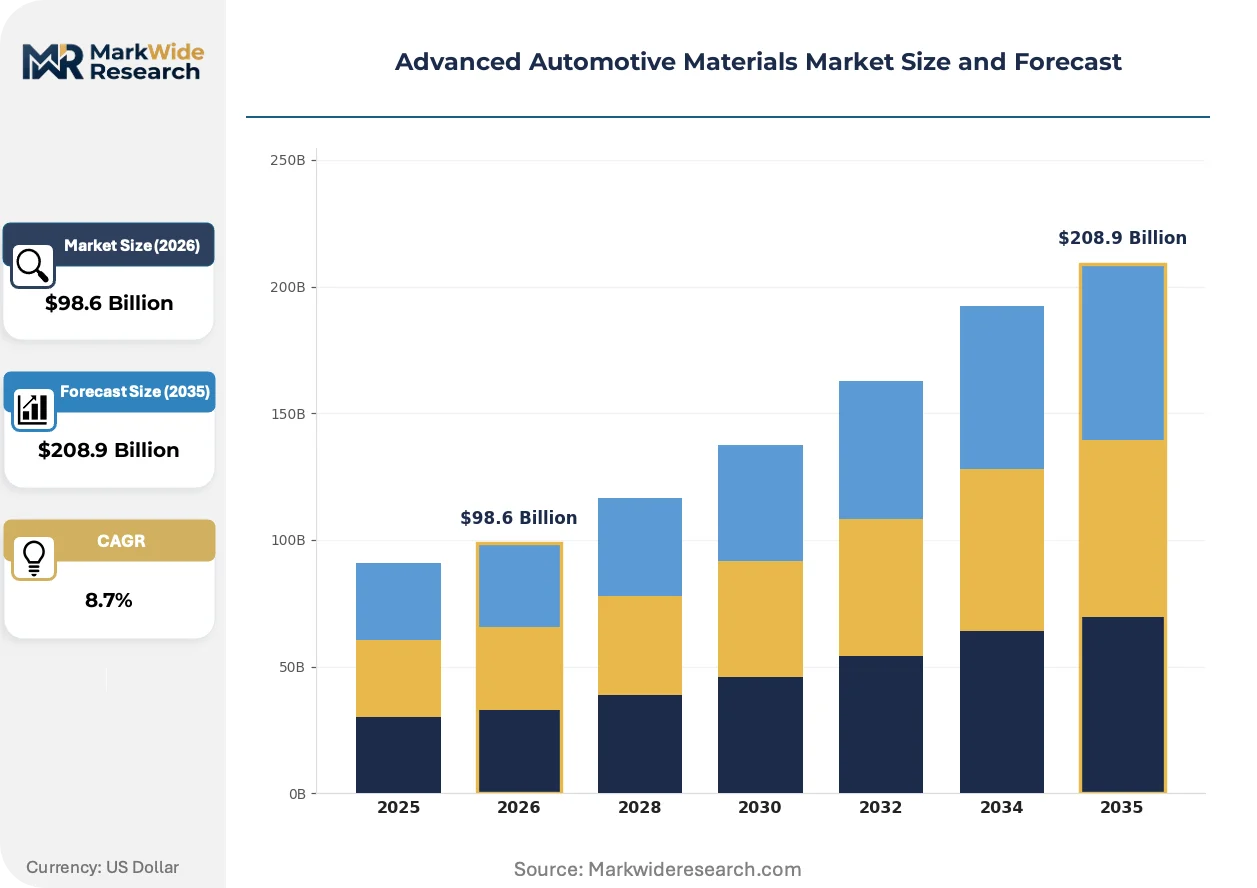
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $208.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Carbon Fiber, Plastics, Composites Application Sector: Lightweighting, Structural Components, Interior Parts, Exterior Panels End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Manufacturing Process: Injection Molding, Die Casting, 3D Printing, Stamping |
| Companies Covered | Martinrea International Inc., Thyssenkrupp Automotive Technology, Magna International Inc., Voestalpine AG, ArcelorMittal Automotive, Gestamp Automoción S.A., Kirchhoff Automotive GmbH, Novelis Inc., Benteler International AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Automotive Materials Market Strategic Shifts
Material innovation is bifurcating between commodity-scale aluminum recycling and premium carbon fiber architectures, with regulatory pressure forcing convergence on traceable, low-carbon-intensity supply chains.
Third-generation press-hardened steels with tailored tempering properties are fragmenting the structural material mix for battery-intensive platforms. OEMs in Germany and the United States are qualifying these grades for floor pan and cross-member applications where crash energy management competes with mass reduction targets. The technology is fragmenting incumbent aluminum sheet positions in lower-body structures where cost-per-kilogram trade-offs favor steel.
REACH substance restrictions and evolving ELV directives are forcing reformulation of polymer stabilizers and chrome-free conversion coatings across European supply chains. Compounders serving interior and underhood applications face 12-18 month requalification cycles for replacement chemistries. Tier-1 molders in Germany and France are consolidating specification control to manage compliance cost absorption.
Automotive OEM procurement organizations are compressing supplier qualification cycles from 36 months to 18 months for EV platform launches. Direct material sourcing from semi-finished producers is displacing traditional mill-service-center-tiered distribution in North America and China. Battery enclosure programs at Tesla, BYD, and Volkswagen Group facilities are piloting this model most aggressively.
Advanced Automotive Materials Market Segmentation
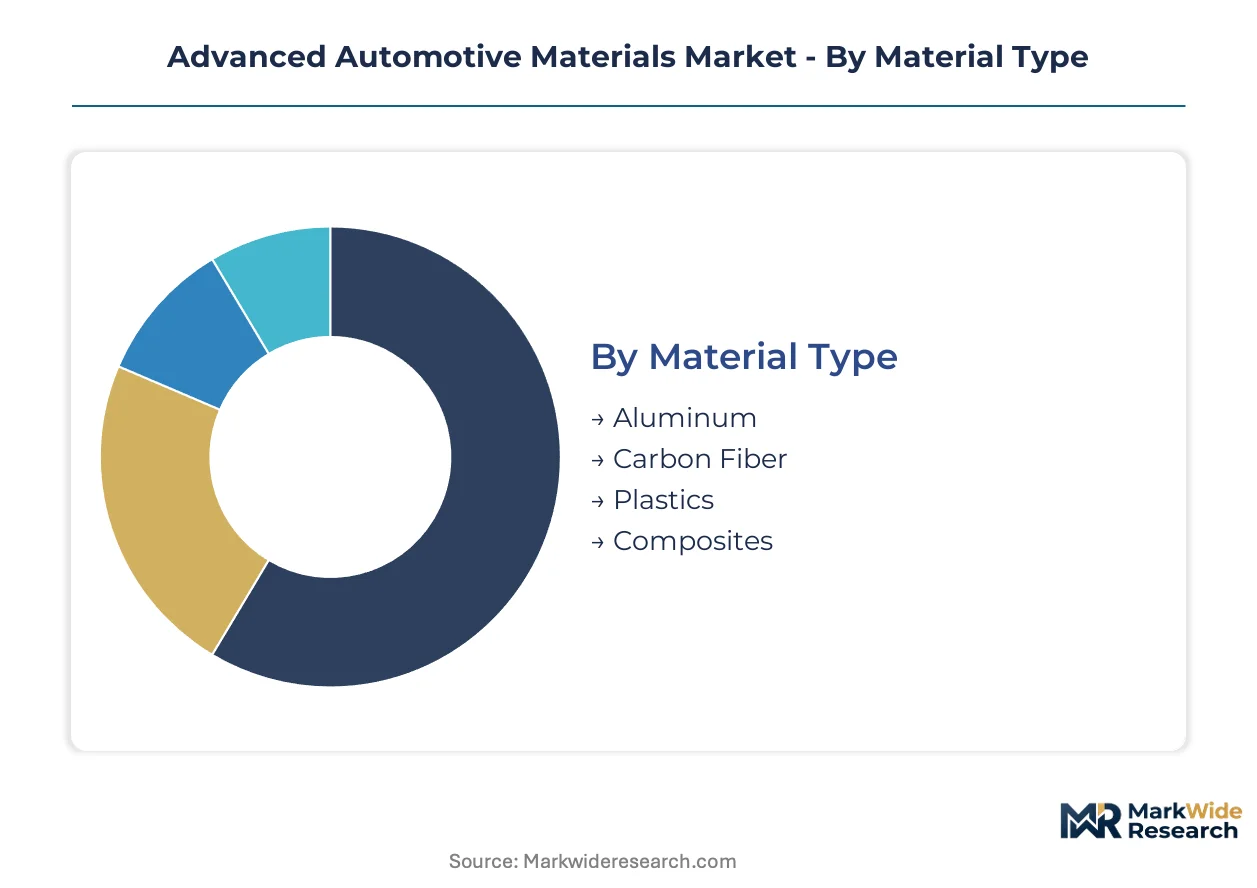
Material selection in automotive platforms determines cost structures, regulatory compliance pathways, and manufacturing flexibility. Segmentation reveals where capital concentrates and which substrate categories command pricing power across electrified vehicle architectures.
Material Type:
Margin pools concentrate in substrates that balance lightweighting performance with established recycling infrastructure and OEM stamping compatibility.
- Aluminum:Rolled sheet and extruded alloys achieve strength-to-weight ratios above 150 MPa/(g/cm³) through work-hardening and precipitation treatments. Demand clusters in Germany, China, and the United States where OEMs retool assembly lines for battery-intensive platforms and the EU Green Deal mandates closed-loop recovery.
- Carbon Fiber:PAN-based precursors and oxidation processes yield stiffness properties exceeding 230 GPa modulus, commanding premium positioning in motorsport and limited-production EV architectures where tooling amortization tolerates higher per-kilogram costs. REACH substance restrictions and precursor supply concentration in Japan and the United States constrain volume scaling.
- Plastics:High-performance thermoplastics serve interior components where design flexibility and acoustic damping justify process complexity; reformulation of polymer stabilizers under evolving ELV directives extends qualification timelines.
- Composites:Multi-material substrates combining fiber reinforcement with thermoset matrices address fire containment and thermal runaway protection requirements in battery enclosures.
The dominant share belongs to Aluminum, while Carbon Fiber is closing the gap fastest in premium EV architectures.
Application Sector:
Volume throughput varies sharply by crash-performance requirements and surface finish specifications across vehicle zones.
- Lightweighting:Systematic mass reduction strategies offset battery pack weight in electrified platforms, with aluminum-intensive body structures and carbon fiber roof panels penetrating luxury and performance segments.
- Structural Components:Press-hardened steel and aluminum extrusions compete for B-pillar, floor pan, and cross-member applications where crash energy management competes with mass targets; third-generation tailored tempering grades fragment incumbent material positions.
- Interior Parts:Polymer compounds and natural fiber composites deliver acoustic damping and haptic quality; REACH restrictions force chrome-free conversion coating reformulation across European supply chains.
- Exterior Panels:Aluminum sheet and polymer composites balance dent resistance, surface quality, and repairability; Class A finish requirements concentrate specification control with Tier-1 stampers in Germany and Michigan.
Structural Components capture the highest value-add per kilogram, though Lightweighting applications are expanding most quickly as fleet efficiency thresholds tighten.
End User:
Procurement authority determines qualification timelines, technical specification control, and pricing leverage across the supply chain.
- OEMs:Volkswagen Group, Tesla, and BYD pilot direct material sourcing from semi-finished producers, compressing qualification cycles from 36 months to 18 months for EV platform launches.
- Tier-1 Suppliers:Gestamp Automoción and Novelis anchor specification control for hot-stamped structural solutions and recycling-intensive aluminum networks; ISO 26262 functional safety certification reorganizes supplier hierarchies for battery enclosure programs.
- Aftermarket Providers:Repair and replacement demand concentrates in collision-damage panels and wear components where material traceability requirements remain less stringent than OE specifications.
- Vehicle Assemblers:Contract manufacturing operations in India and Eastern Europe source aluminum castings and polymer compounds through PLI scheme incentives and export-oriented tooling investment.
OEMs retain the dominant procurement share, while Tier-1 Suppliers are gaining specification influence fastest through integrated material-process capabilities.
Manufacturing Process:
Capital intensity and cycle time differentiation create distinct competitive moats across process categories.
- Injection Molding:High-volume polymer component production for interior and underhood applications; compounders in Germany and France consolidate specification control to manage REACH compliance cost absorption.
- Die Casting:Aluminum and magnesium alloy forming for powertrain housings and structural nodes; IRA clean vehicle credits reshore North American magnesium processing capacity.
- 3D Printing:Additive manufacturing of complex geometries for motorsport and limited-production tooling where design iteration speed outweighs per-unit cost premiums.
- Stamping:Mature aluminum and steel sheet forming infrastructure dominates exterior panel and structural component throughput; press-hardened grades penetrate battery platform architectures.
Stamping maintains the dominant throughput position, while Die Casting is climbing the fastest on EV powertrain housing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's lifecycle carbon mandates, China's MIIT dual carbon targets, and the US IRA clean vehicle credits are rewiring investment flows across major automotive production clusters. OEMs in Germany, China, and the United States are retooling assembly lines for battery-intensive platforms, concentrating material demand in specific industrial corridors.
Germany
Volkswagen Group and BMW are qualifying third-generation press-hardened steels for EV floor pans and cross-members, fragmenting incumbent aluminum positions in lower-body structures. The EU Green Deal's full carbon accounting requirements accelerate closed-loop aluminum recovery investments. Stamping operations in Bavaria and Baden-Württemberg anchor high-strength steel supply for European battery enclosure programs.
China
Domestic OEMs including BYD and NIO are retooling for CFRP-intensive platforms to meet MIIT fleet efficiency thresholds. MIIT dual carbon goals mandate lifecycle emissions tracking from raw material extraction through recycling. Aluminum smelter clusters in Shandong and Xinjiang face energy cost volatility that transmits price instability into sheet and extrusion contracts.
United States
Tesla and Detroit Three manufacturers pilot direct material sourcing from semi-finished producers, compressing qualification cycles from 36 months to 18 months. EPA tailpipe rules tighten material performance thresholds for lightweighting applications. Michigan and Tennessee stamping corridors concentrate press-hardened steel capacity for battery platform architectures.
Japan
Toyota and Honda are qualifying carbon fiber roof panels and structural reinforcements for luxury hybrid platforms. METI industrial policy supports precursor and oxidation capacity expansion to reduce supply concentration vulnerability. Nagoya-area chemical complexes anchor PAN-based carbon fiber feedstock for motorsport and limited-production EV programs.
India
Domestic OEMs and contract manufacturers source aluminum castings and polymer compounds through PLI scheme incentives for export-oriented EV platform supply. The country's national automotive regulator aligns with MIIT-inspired efficiency standards. Gujarat and Maharashtra industrial corridors attract tooling investment from European and Japanese Tier-1 suppliers.
Advanced Automotive Materials Market Competitive Environment
Player mix skews toward integrated steelmakers and aluminum rolling specialists with captive recycling infrastructure. The supplier base organizes around three strategic archetypes: integrated primary metal producers controlling extraction-to-sheet value chains, Tier-1 stampers with hot-forming process expertise, and compounders serving interior polymer specifications. Dominant competitive moves include capacity expansion in closed-loop aluminum recovery and strategic partnerships for multi-material bonding technology.
Among European integrated producers, Voestalpine AG and ArcelorMittal Automotive exemplify the steelmaker archetype with press-hardened grade portfolios. Novelis Inc. anchors North American aluminum supply through recycling-intensive rolling networks. Gestamp Automoción S.A. occupies a position within the Tier-1 stamper tier specializing in hot-stamped structural solutions.
| Leading Market Players |
|---|
| Martinrea International Inc. |
| Thyssenkrupp Automotive Technology |
| Magna International Inc. |
| Voestalpine AG |
| ArcelorMittal Automotive |
| Gestamp Automoción S.A. |
| Kirchhoff Automotive GmbH |
| Novelis Inc. |
| Benteler International AG |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for aluminum sheet and press-hardened steel lock in supply access and price visibility for OEMs retooling assembly lines in Germany and the United States, insulating procurement teams from primary smelter energy cost volatility while compressing Tier-2 supplier margins.
Pricing Analysis
Certification level creates the primary spread across material tiers, with ISO 26262-qualified battery enclosure substrates commanding substantial premiums over standard structural grades. Contract-based long-term offtake structures dominate volume procurement, though spot market exposure persists for carbon fiber precursors. Price differentiation hinges on traceability documentation and REACH compliance status, with European compounders absorbing reformulation costs. Cost compression in standard aluminum grades is intensifying due to Chinese smelter energy price instability. Aftermarket providers exhibit highest price sensitivity, while luxury EV platforms show least elasticity for CFRP-intensive architectures.
Supply Chain Analysis
China and Japan anchor primary aluminum smelting and PAN-based carbon fiber precursor production, with Germany concentrating hot-stamping capacity for European OEM programs. Raw material flows draw from bauxite extraction in Australia and Guinea, petroleum pitch feedstocks for carbon fiber, and alloying elements including magnesium and rare earths. Single-source vulnerability clusters in Japanese precursor oxidation capacity create supply chain risk for motorsport and limited-production EV programs. Distribution runs through direct mill-to-OEM channels that displace traditional service-center tiers for battery enclosure programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around ISO 26262 certification and REACH compliance creates defensive moats that favor incumbent suppliers with established qualification documentation and captive recycling infrastructure.
For Market Incumbents: Consolidate specification control for battery enclosure multi-material bonding through backward integration into structural adhesive formulation and aluminum extrusion capacity. Add press-hardened steel capacity in Michigan and Tennessee corridors to defend against third-generation tailored tempering grades fragmenting lower-body structural positions. Deepen captive aluminum recycling networks to absorb EU Green Deal lifecycle mandates and compress qualification cycles for European OEM programs. For New Entrants and Emerging Players: Service-layer gaps in thermal runaway containment material testing and accelerated qualification protocols present white-space targets for specialized laboratories and engineering consultancies. India's PLI scheme for auto components offers the most penetrable geography, with Gujarat and Maharashtra industrial corridors attracting export-oriented tooling investment for aluminum casting and polymer compounding. A go-to-market angle anchored in ISO 26262 documentation services for mid-tier stampers lacking capital-intensive R&D infrastructure bypasses direct material production barriers. For Investors and Strategic Acquirers: Capital is best deployed toward integrated aluminum rolling specialists with closed-loop recovery infrastructure and established OEM qualification relationships. Long-term viability over the next decade rests on regulatory compliance capabilities rather than commodity scale alone. The inflection indicator to monitor is battery pack architecture standardization across OEM platforms, which would concentrate specification control with qualified incumbent suppliers and compress entry windows for unqualified challengers.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Tesla and BYD direct sourcing from semi-finished producers compresses traditional mill-service-center tiers. |
| Backward Integration | Novelis recycling-intensive rolling networks capture EU Green Deal closed-loop aluminum recovery mandates. |
| Long-term Supply Agreement | Voestalpine press-hardened grade offtake contracts insulate European OEMs from primary steel volatility. |
| Joint Venture | Multi-material bonding partnerships between aluminum extruders and adhesive specialists open hybrid substrate specifications. |
| Geographic Manufacturing Footprint | India PLI scheme incentives attract tooling investment for export-oriented EV platform aluminum casting supply. |
Study Parameters
Operator-level perspectives from OEM platform engineers, Tier-1 supplier procurement directors, aluminum rolling plant managers, and aftermarket distribution heads anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, customs and trade data, vehicle production databases, and IHS Markit registration data. Bottom-up material throughput estimates triangulated against top-down OEM platform content assumptions.
Sensitivity analysis tested forecast robustness across the projection horizon against variations in battery pack architecture standardization, REACH substance restriction timelines, and primary aluminum energy cost trajectories. Segmentation dimensions modeled encompass material type, application sector, end-user procurement authority, and manufacturing process capital intensity. CAGRs derived from regression analysis of historical OEM platform retooling cycles and regulatory mandate implementation schedules, with EV adoption curves and fleet efficiency threshold stringency as automotive-specific forecast inputs.
Underlying assumptions cover sustained MIIT dual carbon enforcement, EU Green Deal lifecycle accounting implementation, and IRA clean vehicle credit continuity, with deviation risk concentrated in aluminum smelter energy cost volatility and carbon fiber precursor supply concentration. Recalibration cycles align with material shifts in battery enclosure qualification protocols and REACH substance restriction amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Aluminum Market
Automotive Components
Iran Automotive Lubricants Market
Automotive Components
Automotive Solar Control Glass Market
Automotive Components
Automotive Radiator Grille Market
Automotive Components
Global Automotive Bumpers Market
Automotive Components
Saudi Arabia Automotive Actuators Market
Automotive Components
Global Automotive Pneumatic Valve Market
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
Automotive Chromium Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Automotive Catalytic Converter Market
Automotive Components
Automotive Tie Rod Market
Automotive Components
North America Automotive Glass Market
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Automotive Hubcaps Market