
 Automotive Steering Column Market | 2026-2036
Automotive Steering Column Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Steering Column Market Analysis
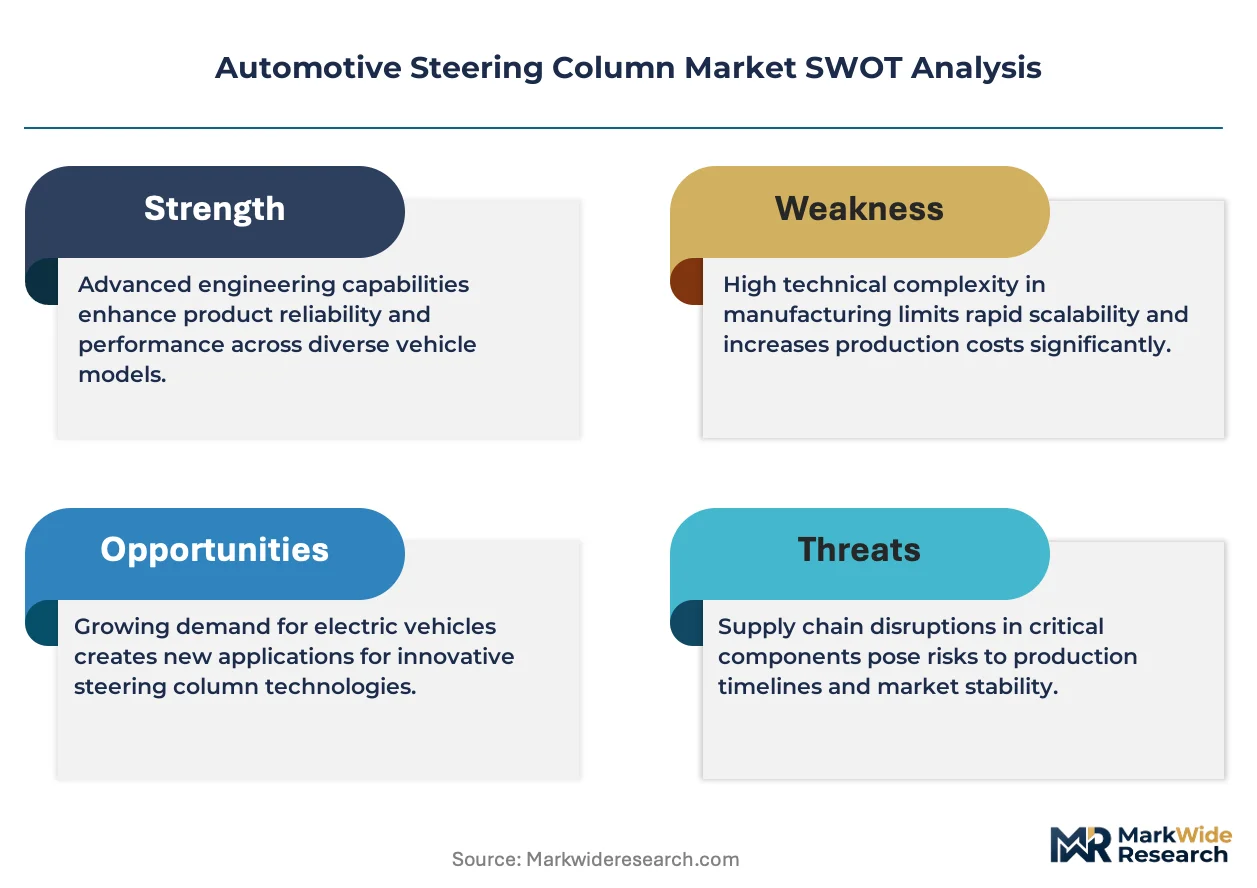
Single-source supply arrangements for steering column modules is pivoting toward dual-source contracts across Tier-1 automotive suppliers. ZF Friedrichshafen AG leverages its integrated chassis systems portfolio to anchor long-term OEM partnerships in Europe and North America. JTEKT Corporation dominates electromechanical steering column production through captive in-house motor manufacturing and precision gear capacity in Japan and China. Nexteer Automotive specializes in column assist electric power steering systems, competing on software-calibrated torque delivery for electric vehicle platforms.
An automotive steering column is a tubular structural assembly that connects the steering wheel to the steering gear mechanism, typically fabricated from seam-welded steel or extruded aluminum with collapsible segments engineered to absorb impact energy during frontal collisions. Its primary commercial purpose is to transmit driver torque input while providing tilt, telescopic, and power assistance functions that reduce steering effort across vehicle speed ranges. Electric power steering columns now lead technology adoption as automakers phase out hydraulic assist systems to save weight and enable advanced driver assistance interfaces. The OEM end user segment captures the dominant margin pool due to multi-year platform contracts and embedded software content, while aftermarket demand sustains replacement volumes for mechanical steering columns in aging vehicle parcs.
NHTSA Federal Motor Vehicle Safety Standard No. 204 governs steering column rearward displacement limits in the United States, while UN ECE Regulation R79 mandates steering equipment type approval across European and aligned markets, directly shaping product design cycles and homologation costs. China's MIIT enforces GB standards for steering system durability and electromagnetic compatibility, creating separate certification pathways for domestic and export-bound production. Stakeholders must monitor how software-defined vehicle architectures redefine steering column interfaces as steer-by-wire platforms eliminate mechanical steering shafts in premium electric vehicle segments.
Market Dynamics
Electric power steering column architecture is consolidating control functions previously distributed across separate modules, compressing supplier tiers and redefining value capture between steering system integrators and vehicle platform architects.
Growth Catalysts
- UN ECE R79 steering equipment mandates:European type-approval requirements for steering safety and electromagnetic compatibility are forcing platform standardization that benefits integrated column suppliers with in-house calibration capabilities.
- Passenger vehicle electrification in China:MIIT dual carbon goals and GB standards for steering durability are accelerating OEM procurement of electric power steering columns as automakers phase out hydraulic assist systems across domestic production lines.
- Collapsible segment engineering:Advanced seam-welded steel and extruded aluminum fabrication processes are enabling lighter-weight columns that absorb frontal collision energy more predictably, satisfying NHTSA FMVSS 204 displacement limits.
Market Restraints
- Neodymium and copper input volatility:Electric power steering motor manufacturing depends on rare-earth magnet supply chains concentrated in Chinese processing facilities, exposing cost structures to export quota fluctuations.
- Homologation cost stacking:Separate certification pathways for NHTSA, UN ECE R79, and China's GB standards create parallel testing burdens that disproportionately burden low-volume platform variants.
- Steer-by-wire substitution trajectory:Premium electric vehicle segments are piloting mechanical-shaft elimination, threatening long-term demand for traditional collapsible column segments in luxury applications.
Strategic Opportunities
- Software-defined vehicle interface convergence:Electric power steering columns integrating torque sensors with ADAS data buses are capturing value previously held by separate chassis control modules.
- Aftermarket mechanical replacement demand:Aging vehicle parcs in the United States and Germany sustain replacement volumes for non-powered steering columns as hydraulic system service intervals compress.
- Dual-source contract proliferation:OEMs are fragmenting sole-source steering module arrangements, creating entry points for Tier-1 suppliers with captive motor manufacturing or precision gear capacity.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification for steering column control software requires specialized embedded systems talent that concentrates at established chassis integrators.
- Legacy platform integration friction:Electric power steering retrofits into internal combustion vehicle architectures demand mechanical packaging compromises that extend development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Steering Column Market |
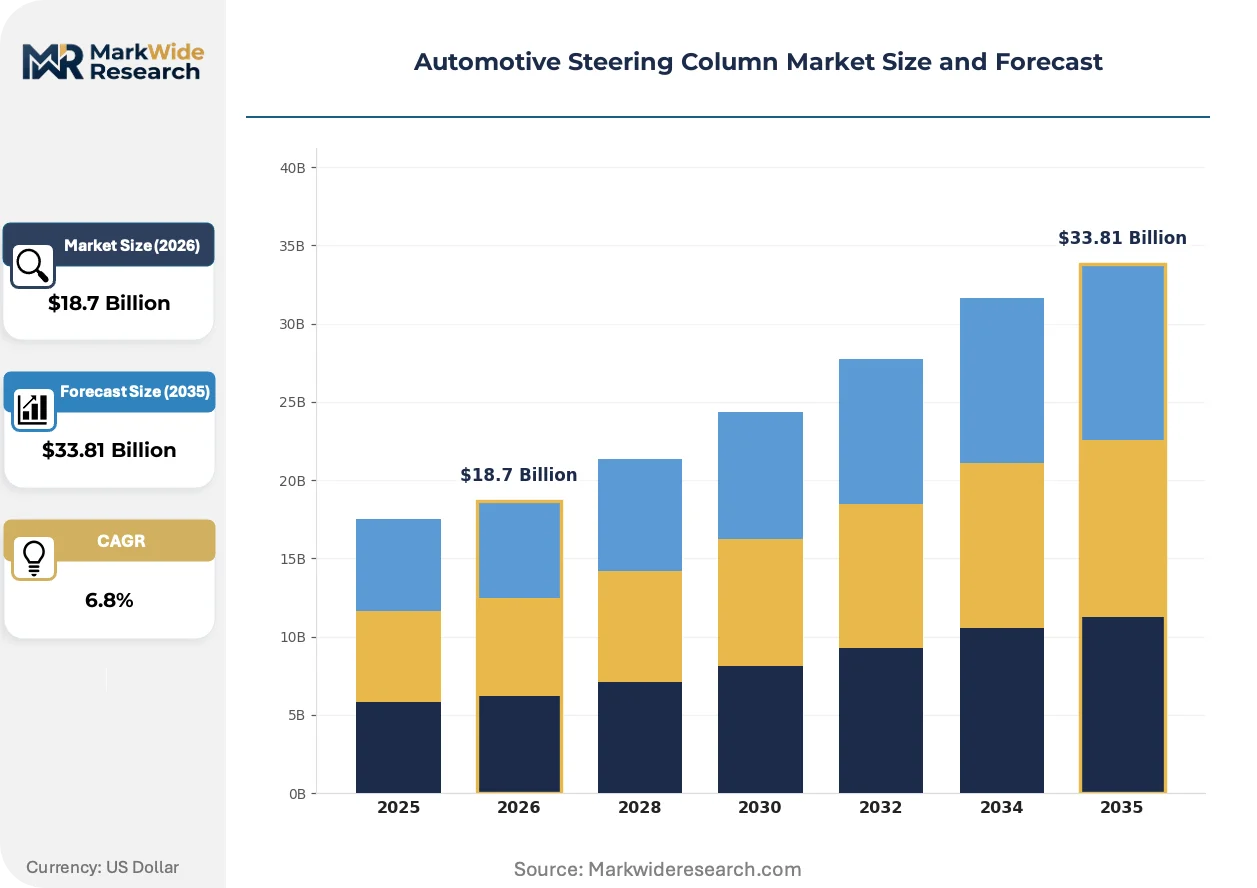
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Electric, Adjustable, Telescopic End User: OEMs, Aftermarket, Tier-1 Suppliers, Dealerships Technology: Column Assist, Power Steering, Mechanical, Electronic Material: Aluminum, Steel, Composite, Plastic |
| Companies Covered | JTEKT Corporation, ZF Friedrichshafen AG, NSK Ltd., Nexteer Automotive, thyssenkrupp AG, Robert Bosch GmbH, DENSO Corporation, Mando Corporation, Leopold Kostal GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Steering Column Market Emerging Trajectories
Steering column architecture is converging with chassis domain controllers, collapsing previously separate electronic modules into unified steering assemblies that handle torque assistance, position sensing, and vehicle dynamics feedback.
Steer-by-wire technology is decentralizing mechanical steering shaft functions across electric vehicle platforms. The technology transmits driver input through electronic signals rather than physical linkages, eliminating collapsible column segments. Premium EV manufacturers in Germany and California are adopting it for packaging flexibility and crash safety optimization. This decentralization is compressing traditional supplier relationships as steering system architects assume responsibility for redundant electronic pathways.
UN ECE Regulation R79 revisions are tightening steering equipment type-approval requirements for automated lane-keeping systems. The regulation now mandates specific torque overlay capabilities and failure-mode responses for Level 2+ driving automation. European OEMs are redesigning column assist electric power steering software calibrations to satisfy these thresholds, with compliance costs falling heaviest on mid-volume platform derivatives that lack scale to amortize development.
Automotive OEMs are consolidating steering column procurement under multi-year platform contracts that embed software content and calibration services. Tier-1 suppliers with integrated chassis portfolios are capturing these consolidated awards, displacing smaller mechanical column specialists. This concentration is most visible in China and Germany, where passenger vehicle output volumes justify dedicated engineering teams assigned to single OEM relationships.
Automotive Steering Column Market Segmentation
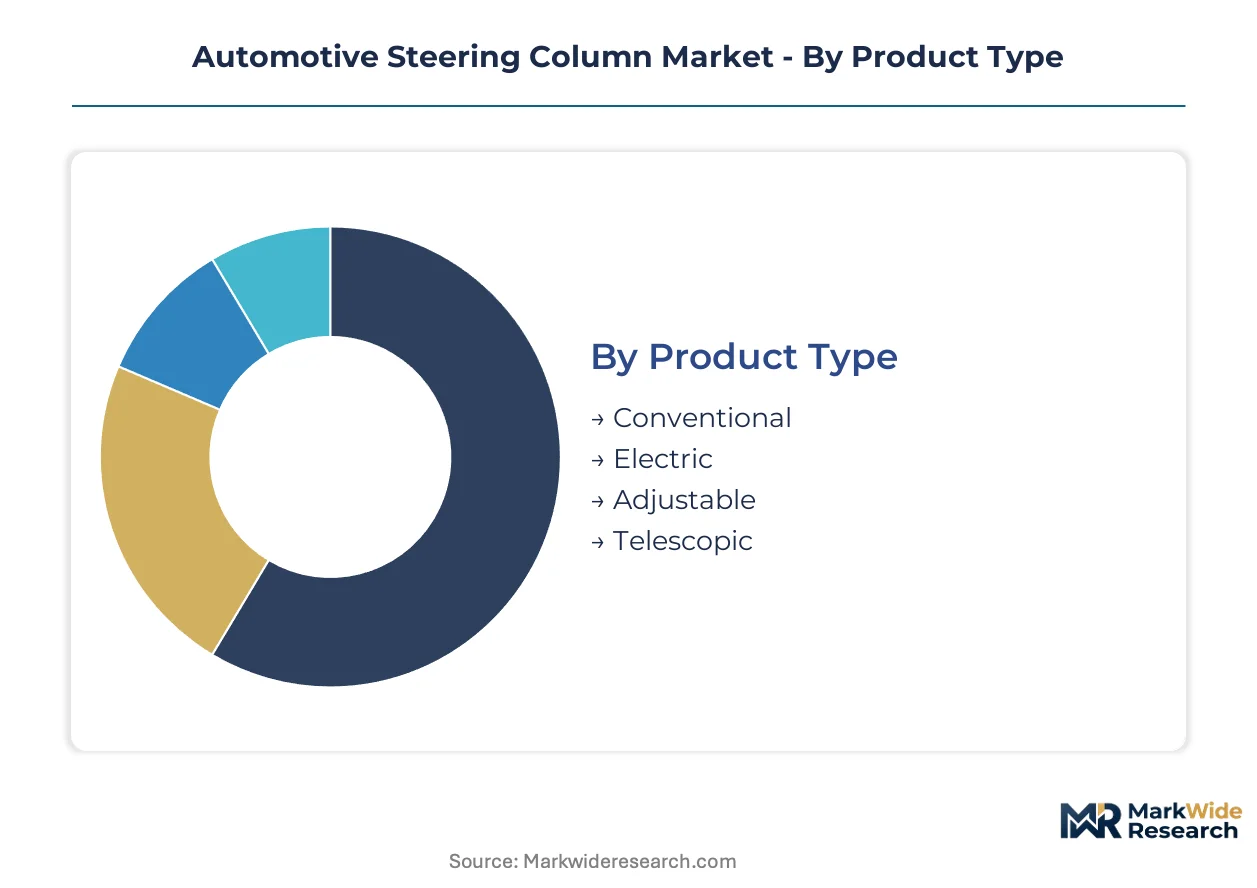
Segmentation reveals how steering column procurement priorities diverge between electrification-focused OEMs and replacement-cycle aftermarket channels. Product architecture choices cascade through material specifications, technology integration depth, and end-user margin structures.
Product Type:
Upgrade cycles from conventional hydraulic systems to electric platforms are compressing procurement timelines and reshaping supplier qualification criteria.
- Conventional:Hydraulic assist architectures persist in legacy internal combustion vehicle parcs where retrofit economics discourage platform redesign. Demand concentrates in aftermarket channels across the United States and Germany as aging vehicle fleets extend service intervals.
- Electric:Column-integrated motor and control electronics eliminate hydraulic fluid circuits while enabling torque-overlay functions for ADAS integration. Procurement accelerates in China as MIIT dual carbon goals mandate efficiency improvements across domestic OEM production lines.
- Adjustable:Tilt and reach mechanisms accommodate driver ergonomic preferences through manual or powered adjustment rails.
- Telescopic:Shaft extension systems optimize steering wheel positioning for varying driver statures and autonomous mode transitions.
Volume placements concentrate in Conventional; the faster expansion belongs to Electric.
End User:
Margin capture varies sharply between multi-year platform contractors and fragmented replacement part distributors.
- OEMs:Vehicle manufacturers specify column modules through platform-level contracts that embed software calibration services and homologation support. Procurement concentrates in Germany and China where passenger vehicle output volumes justify dedicated supplier engineering teams.
- Aftermarket:Independent service channels source mechanical replacement columns for collision repair and wear-item replacement in aging vehicle populations.
- Tier-1 Suppliers:Integrated chassis system providers consolidate steering column procurement with adjacent suspension and braking modules.
- Dealerships:Authorized service networks handle warranty replacements and certified pre-owned vehicle reconditioning.
Revenue concentration sits with OEMs; aftermarket channels deliver steadier replacement-cycle volumes.
Technology:
Control function integration is collapsing distributed electronic modules into unified steering assemblies.
- Column Assist:Electric motor mounted directly on the steering column delivers variable assist torque with minimal packaging intrusion. Nexteer Automotive specializes in software-calibrated torque delivery for electric vehicle platforms in North America.
- Power Steering:Hydraulic pump-driven systems persist in commercial vehicle applications where load-bearing requirements exceed electric motor capacity.
- Mechanical:Non-assisted steering shafts survive in ultra-lightweight vehicle segments and racing applications.
- Electronic:Sensor-integrated columns transmit position and torque data to chassis domain controllers for vehicle dynamics coordination.
Column Assist dominates new platform awards; Electronic architectures are gaining share fastest in premium electric vehicle segments.
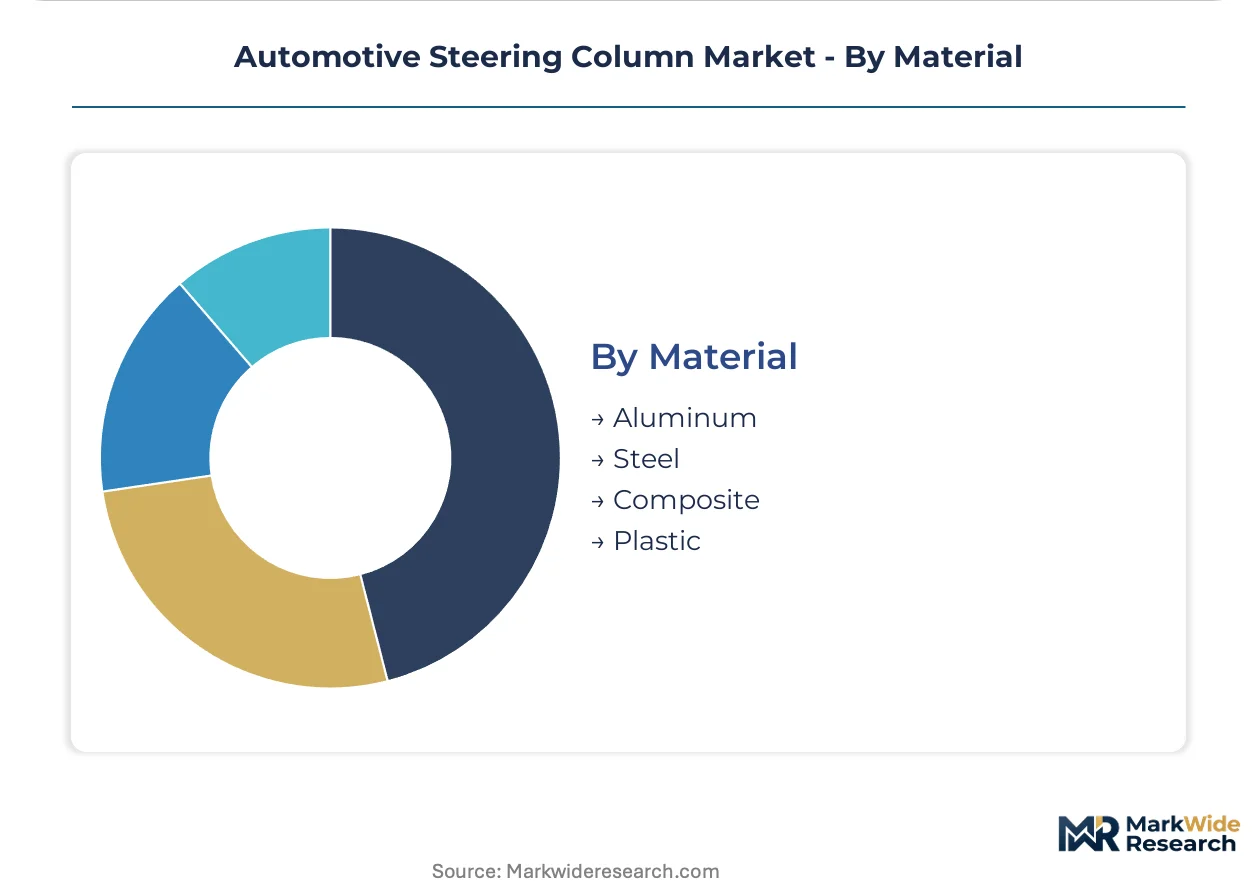
Material:
Fabrication choices trade crash-energy absorption against mass reduction targets and supply chain security.
- Aluminum:Extruded alloy tubes reduce unsprung mass while maintaining collapsible segment performance for NHTSA FMVSS 204 compliance. Demand concentrates in European OEM platforms where CO2 fleet targets prioritize lightweighting.
- Steel:Seam-welded tubular construction dominates high-volume production through mature stamping and welding automation.
- Composite:Carbon fiber reinforced polymers enable radical mass reduction in motorsport and limited-production hypercar applications.
- Plastic:Injection-molded housings and trim components reduce secondary assembly operations.
Steel retains volume leadership; aluminum shows the steepest expansion trajectory as electrification intensifies mass reduction priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium processing facilities in China's Jiangxi Province supply rare-earth magnets that anchor electric power steering motor production across major automotive manufacturing zones.
China
MIIT dual carbon targets and GB standards for steering system durability are accelerating OEM procurement of electric power steering columns. Domestic automakers in Shanghai and Guangzhou are phasing out hydraulic assist systems across passenger vehicle platforms. The Yangtze River Delta cluster hosts integrated motor manufacturing operations that serve both local production and export markets.
Germany
UN ECE R79 type-approval mandates for automated lane-keeping systems are forcing software recalibrations in column assist electric power steering. Stuttgart and Munich engineering centers coordinate homologation pathways for European OEM platform derivatives. The Baden-Württemberg industrial corridor concentrates chassis system integration capabilities that span steering, braking, and suspension modules.
United States
NHTSA FMVSS 204 rearward displacement limits govern collapsible segment engineering for frontal collision protection. Detroit Three automakers specify multi-year platform contracts that embed software calibration services. The Midwest manufacturing belt around Michigan and Ohio retains stamping and welding automation for seam-welded steel tubular construction.
Japan
METI industrial policy supports precision gear manufacturing capacity for electromechanical steering column production. JIS standards for steering durability align with export-market homologation requirements. The Aichi Prefecture cluster around Nagoya integrates captive motor manufacturing with column assembly operations for both domestic OEMs and overseas subsidiaries.
South Korea
MFDS automotive component quality frameworks intersect with OEM demands for ISO 26262 ASIL-D functional safety certification. Hyundai and Kia platform electrification is compressing supplier qualification timelines for electric power steering modules. The Busan-Ulsan industrial zone hosts motor manufacturing facilities that supply integrated column assemblies.
Automotive Steering Column Market Vendor Landscape
Global majors compete with regional champions across homologation expertise and captive manufacturing depth. The vendor base clusters around integrated chassis system providers with in-house motor production, precision gear fabricators with JIS-certified operations, and software-calibration specialists serving electric vehicle platforms. Three archetypes dominate: full-system integrators controlling motor-to-column vertical chains, component specialists supplying precision gears and sensors to multiple integrators, and regional champions leveraging proximity to domestic OEM engineering centers. Competitive moves concentrate on dual-source contract fragmentation and software-defined vehicle interface convergence.
Within the integrated-system tier, ZF Friedrichshafen AG and JTEKT Corporation exemplify contrasting geographic anchoring strategies. The German GmbH structure represents European chassis portfolio consolidation across steering, suspension, and braking modules. The Japanese Corporation format reflects captive motor manufacturing and precision gear capacity concentrated in East Asian production bases. Nexteer Automotive occupies a position bridging North American OEM relationships with software-calibrated torque delivery capabilities for electric vehicle platforms.
| Leading Market Players |
|---|
| JTEKT Corporation |
| ZF Friedrichshafen AG |
| NSK Ltd. |
| Nexteer Automotive |
| thyssenkrupp AG |
| Robert Bosch GmbH |
| DENSO Corporation |
| Mando Corporation |
| Leopold Kostal GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
MIIT dual carbon targets and GB standards compliance gate qualified supply access for electric power steering column suppliers, while NHTSA FMVSS 204 certification tiers stratify pricing across premium-calibrated and economy-grade procurement channels. OEMs with multi-year platform contracts capture embedded software service bundles that smaller aftermarket distributors cannot replicate.
Pricing Analysis
Warranty and calibration service bundling separates OEM platform contracts from unbundled aftermarket mechanical replacement sales. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 26262 ASIL-D certification grade and captive motor manufacturing depth. Pricing pressure stems from neodymium magnet cost volatility concentrated in Chinese processing facilities. Aftermarket channels exhibit highest price sensitivity due to fragmented distributor networks and compressed service intervals.
Supply Chain Analysis
Single-source vulnerability sits with rare-earth magnet processing concentrated in China's Jiangxi Province. Manufacturing capacity clusters in Germany, Japan, and China for precision gear fabrication and seam-welded steel tubular construction. Raw material dependencies center on neodymium, copper windings, and high-strength alloy steels. Tariff exposure on processed rare-earth exports creates procurement risk for European and North American integrators. Distribution runs through Tier-1 chassis system providers with direct OEM platform engineering relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rare-earth magnet refining capacity constraints prop pricing premiums for certified electric power steering suppliers, constraining qualified supply faster than platform demand expands.
For Market Incumbents: Anchor long-term OEM partnerships through captive motor manufacturing investments in the Yangtze River Delta and Aichi Prefecture clusters. Defend against steer-by-wire substitution by deepening software-calibration capabilities for ADAS torque overlay functions. Prioritize ISO 26262 ASIL-D certification maintenance to sustain premium-tier contract access. For New Entrants and Emerging Players: Digital aftermarket catalog platforms offer lowest barrier entry for mechanical steering column replacement parts in aging United States and German vehicle parcs. Target collision repair distributors in the Midwest manufacturing belt and Baden-Württemberg corridor with standardized seam-welded steel SKU ranges. Pursue dual-source contract fragmentation at mid-volume OEMs seeking supply resilience. For Investors and Strategic Acquirers: JTEKT Corporation's precision gear capacity expansion announcements are the leading indicator that electromechanical integration value is concentrating among East Asian suppliers. Five-to-ten-year viability favors integrated chassis system providers with backward control over motor manufacturing. Monitor UN ECE R79 revision timing for automated lane-keeping compliance thresholds as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidates steering column procurement under multi-year contracts with embedded software content. |
| Battery Supply Agreement | Electric vehicle platform electrification accelerates electric power steering motor demand. |
| Software-Defined Vehicle Investment | Enables torque sensor integration with chassis domain controllers for ADAS coordination. |
| Geographic Manufacturing Footprint | Proximity to Jiangxi rare-earth processing reduces magnet procurement cost volatility exposure. |
| Charging Infrastructure Partnership | Aligns steering system suppliers with premium EV manufacturers piloting steer-by-wire architectures. |
Methodological Framework
Document review covered vehicle production databases, IHS Markit registration data, NHTSA FMVSS filings, and UN ECE type-approval records, complemented by interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers. Secondary validation drew from customs trade statistics, SEC chassis supplier filings, and MIIT GB standard documentation. Bottom-up segmentation modeling triangulated against top-down production volume estimates.
Historical production trajectories cross-referenced against expert panel input on electrification timelines and regulatory compliance costs. The analytical framework segmented by vehicle class, propulsion architecture, content per vehicle, and regional production cluster across the projection horizon. CAGRs derived from fitted growth curves calibrated to platform procurement cycle visibility and technology substitution elasticity. Industry-specific inputs included rare-earth magnet price indices and homologation cost stacking estimates.
The model holds under stable NHTSA and UN ECE regulatory frameworks; deviation in steer-by-wire adoption velocity or Chinese rare-earth export policy would shift volume allocations. Forecasts reflect documented assumptions on OEM electrification commitments and supplier consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Carbon Ceramic Brakes Market
Automotive Components
Automotive Chromium Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
India Automotive Airfilters Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Automotive Exhaust Silencer Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
United States Automotive Pneumatic Actuators Market
Automotive Components
Europe Automotive Heat Exchanger Market
Automotive Components
Automotive Wiper Blades Market
Automotive Components
UAE Automotive Composites Market
Automotive Components
Japan Automotive Electric Actuators Market
Automotive Components
North America Automotive Heat Shield Market
Automotive Components
Saudi Arabia Automotive Actuators Market
Automotive Components
Automotive Front-End Module (FEM) Market