
 Automotive Connecting Rod Market | 2026-2036
Automotive Connecting Rod Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Connecting Rod Market Intelligence
European production capacity for high-strength forged steel connecting rods is hardening due to volatile energy prices and supply chain constraints. In this environment, MAHLE GmbH leverages its extensive R&D in lightweight materials to serve OEM efficiency goals. Schaeffler Technologies AG & Co. KG specializes in precision components for both internal combustion and hybrid powertrains. Federal-Mogul Motorparts LLC competes through its broad aftermarket distribution network and portfolio for engine rebuilders.
An automotive connecting rod is the critical engine component that links a piston to a crankshaft. It is typically manufactured through forging or powder metallurgy and must withstand immense compressive and tensile forces while converting the piston's linear motion into the crankshaft's rotation. Forged steel and titanium alloy variants dominate high-performance and motorsport applications due to their superior strength-to-weight ratios. Powder metal components, however, offer cost efficiencies for high-volume production in the mainstream passenger vehicle segment.
Component design and material selection are heavily influenced by global emissions regulations. Mandates from the EPA in the United States and the EU Green Deal framework in Europe push for lighter, more efficient engines, directly impacting connecting rod specifications. Conformance with ISO 9001 standards for quality management remains a baseline requirement for supplier qualification. Balancing investments for advanced ICE components with strategic pivots toward new powertrain technologies will determine future profitability for manufacturers.
Market Dynamics
The imperative to enhance internal combustion engine efficiency, driven by global emissions standards, defines the automotive connecting rod market. This creates a core tension between investing in advanced, lightweight materials for legacy powertrains and allocating capital for the industry's transition to electrification.
Growth Catalysts
- Commercial Vehicle Upgrades:Demand from the heavy-duty truck and bus sectors for more durable and efficient engine components is a primary catalyst, spurred by fleet modernization programs and fuel economy mandates.
- Powder Metallurgy Adoption:The cost-effectiveness and net-shape manufacturing capabilities of powder metal processes drive adoption in high-volume passenger vehicle production, particularly in Asian manufacturing hubs.
- Aftermarket Performance Segment:A robust aftermarket for engine rebuilding and performance tuning, especially in North America, sustains demand for high-strength forged steel and titanium alloy connecting rods.
Market Restraints
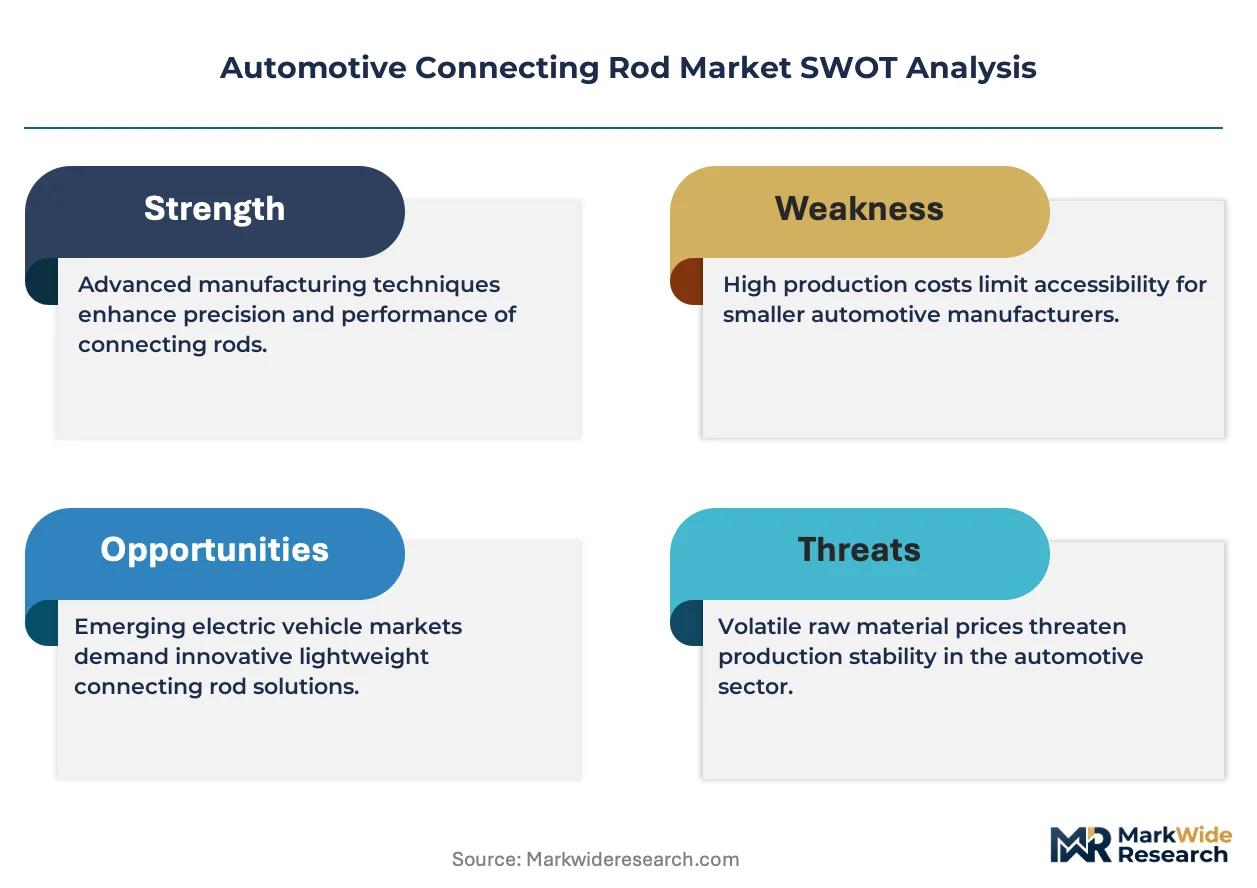
- Input Material Price Volatility:Fluctuations in the cost of high-grade steel, titanium, and aluminum alloys directly compress manufacturer margins and create pricing instability for both OEM and aftermarket customers.
- EV Transition Threat:The accelerating shift to battery electric vehicles (BEVs), which do not contain connecting rods, poses a long-term structural threat, reducing the total addressable market for ICE components.
- High Retooling Costs:Significant capital investment is required to adapt or replace forging presses and machining lines to produce next-generation, lightweight connecting rod designs that meet new engine specifications.
Strategic Opportunities
- Hybrid Powertrain Components:The growth of hybrid and plug-in hybrid vehicles creates a durable market for smaller, highly optimized connecting rods designed for efficient, downsized internal combustion engines.
- Advanced Composite Materials:Research into carbon fiber or metal matrix composite connecting rods presents an opportunity to serve niche, high-performance, and motorsport applications where weight reduction is paramount.
- Emerging Market Production:Expanding automotive manufacturing in Southeast Asia and Latin America offers opportunities for suppliers to establish regional production for cost-effective, standard-duty connecting rods.
Industry Challenges
- Specialized Talent Scarcity:A shortage of metallurgists and process engineers with expertise in advanced powder metallurgy and high-tolerance forging techniques hinders innovation and production scaling.
- Divergent Regulatory Compliance:Manufacturers face complexity and cost in certifying components to meet varying emissions and material standards, such as EPA rules in the US and EU Green Deal requirements in Europe.
- Balancing R&D Investment:Allocating research and development budgets between incremental improvements for ICE components and strategic pivots toward electric powertrain technologies is a critical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Connecting Rod Market |
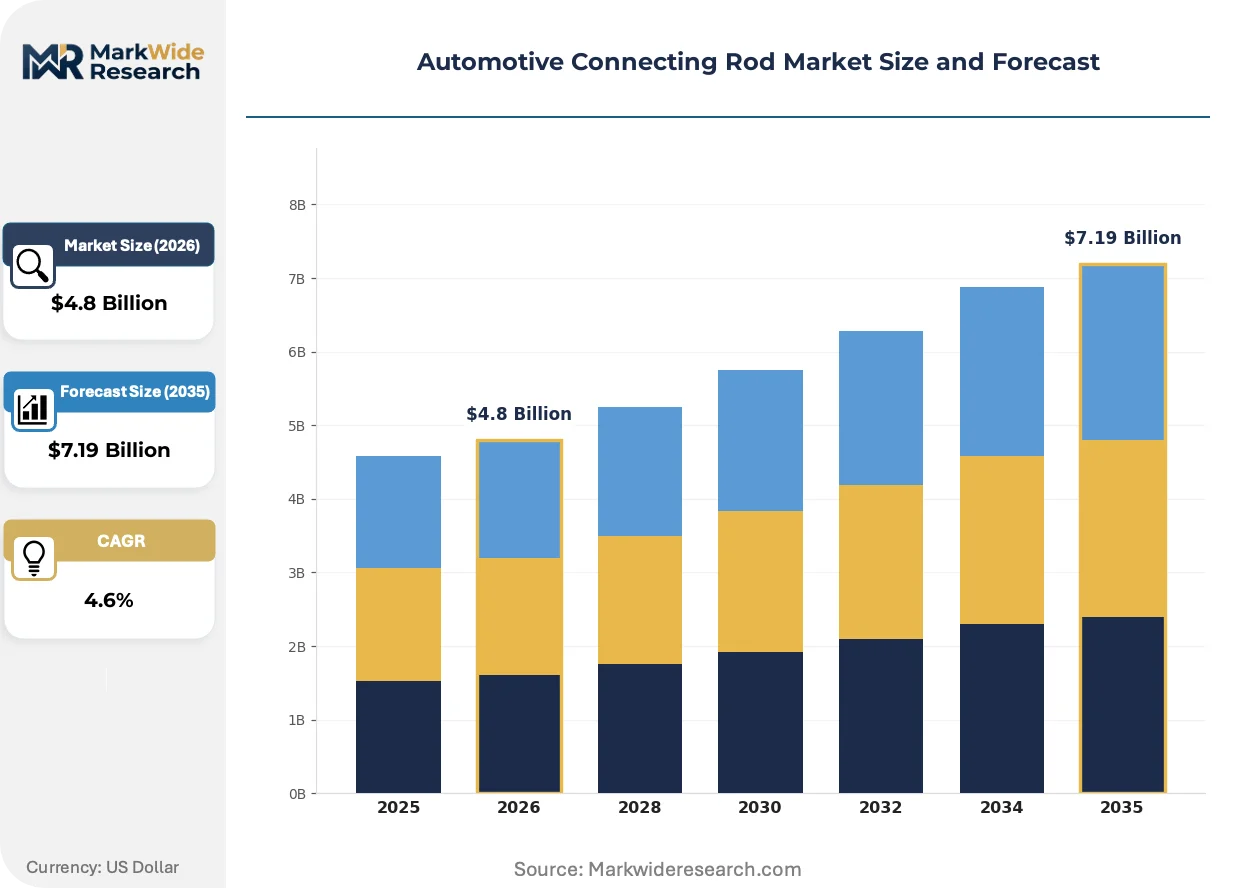
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forged Steel, Powder Metal, Cast Iron, Aluminum Alloy, Titanium Alloy Engine Type: Gasoline Engines, Diesel Engines, Hybrid Powertrains, Electric Motors Application: Passenger Vehicles, Commercial Vehicles, Off-highway Equipment, Motorsport, Marine Engines End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Engine Rebuilders |
| Companies Covered | CP-Carrillo, Albon Engineering & Manufacturing Plc., MAHLE GmbH, JD Norman Industries, Wiseco, Federal-Mogul Motorparts LLC, Schaeffler Technologies AG & Co. KG, Nangong Jingqiang Connecting Rod Co. Ltd., Cummins Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Connecting Rod Market Strategic Shifts & Innovations
Material science and process engineering are central to market evolution. Manufacturers are developing novel alloys and refining production techniques like fracture splitting to meet stringent OEM requirements for lighter weight, higher strength, and improved fuel economy under tightening regulatory pressure.
Powder metal fracture-splitting is a key manufacturing process that forms the connecting rod and its cap as a single unit before it is split. Mainstream passenger car OEMs are widely adopting this method for its high precision and significant cost savings in mass production environments. This technique is overtaking traditional casting and certain forged steel applications in the volume passenger vehicle segment due to superior cost-efficiency and dimensional consistency.
China's "dual carbon" policy and its associated GB standards for vehicle emissions are forcing rapid engine component innovation. This regulatory pressure compels automakers in the region to specify lighter connecting rods made from advanced steel alloys or aluminum to improve fuel efficiency. The commercial vehicle sector is particularly impacted, undergoing substantial engine redesigns to comply with new, stricter fuel consumption mandates.
A distinct behavioral shift is occurring in the performance aftermarket, with rising demand for custom-engineered, high-strength connecting rods for engine tuning. This trend bypasses traditional OEM supply channels, creating a direct-to-consumer market for specialist machine shops and e-commerce brands. This dynamic is most visible in North America and Europe, supported by a strong enthusiast culture centered on vehicle modification and motorsports.
Automotive Connecting Rod Market Segmentation
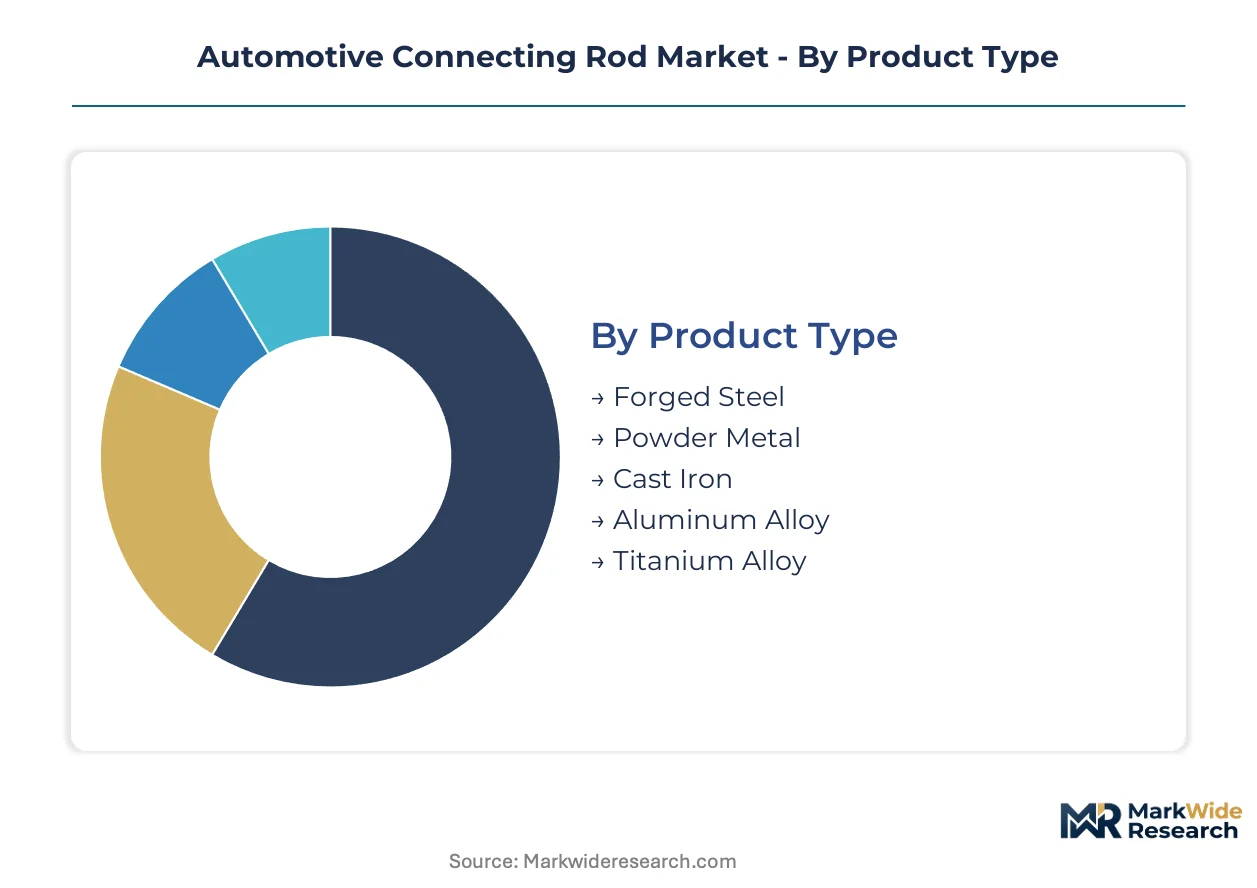
Understanding the Automotive Connecting Rod Market through its segmentation reveals the diverse demands and supply dynamics across various product types, engine applications, end-user groups, and material compositions. This granular view helps stakeholders identify specific growth pockets and areas of technological investment.
Product Type:
Supply for automotive connecting rods is concentrating around specific material types, reflecting specialized manufacturing capabilities and cost structures.
- Powder Metal:Connecting rods produced via powder metallurgy offer net-shape manufacturing and superior cost efficiency for high-volume production. Demand concentrates in mainstream passenger vehicles in China, driven by its massive domestic automotive industry.
- Forged Steel:Hot-forged from high-strength steel alloys, these rods provide exceptional durability and fatigue resistance. Demand is strong from commercial vehicle manufacturers in Germany and the aftermarket performance segment across North America.
- Cast Iron:Cast iron connecting rods represent a legacy technology, primarily used in older engine designs or cost-sensitive applications.
- Aluminum Alloy:Aluminum alloy connecting rods offer significant weight reduction, used in high-performance or lightweight engine designs for fuel economy.
- Titanium Alloy:Titanium alloy connecting rods provide the highest strength-to-weight ratio, specified for elite motorsport and ultra-high-performance vehicles.
Powder Metal absorbs the bulk of installed capacity; Forged Steel is expanding most quickly due to commercial vehicle upgrades and aftermarket demand.
Engine Type:
The type of engine dictates specific design and material requirements for connecting rods, influencing component specialization.
- Diesel Engines:Connecting rods for diesel engines are engineered to withstand higher compressive forces and extreme operating conditions, prioritizing durability. Demand is strong from heavy-duty commercial vehicles in India.
- Hybrid Powertrains:Hybrid powertrains require optimized connecting rods for smaller, downsized internal combustion engines, focusing on lightweight design and efficiency. Growth in Japan creates a durable market.
- Gasoline Engines:Connecting rods in gasoline engines form the largest volume segment, balancing performance, durability, and cost-effectiveness for passenger vehicles.
- Electric Motors:Electric motors do not utilize connecting rods, representing a structural threat to the connecting rod market as electrification advances.
This category highlights the shift towards specialized rod designs for efficient hybrid powertrains, even as diesel engines continue to demand high-strength solutions.
Application:
The application segment for connecting rods is primarily driven by vehicle production volumes and the specific performance demands of each sector.
- Commercial Vehicles:Connecting rods for commercial vehicles prioritize extreme durability and robust construction for prolonged, high-stress operation. Sustained demand in the United States drives fleet modernization.
- Passenger Vehicles:Passenger vehicles represent the largest volume market for connecting rods, balancing cost-efficiency, lightweight design, and strength. Demand concentrates in China, reflecting its massive automotive production.
- Off-highway Equipment:Connecting rods for off-highway vehicles require high fatigue strength and resistance to harsh operating environments.
- Motorsport:Motorsport applications demand ultra-lightweight, high-strength connecting rods, often from exotic materials, to maximize engine performance.
- Marine Engines:Connecting rods in marine engines are designed for continuous, high-load operation, requiring corrosion resistance and exceptional durability.
The dominant share here belongs to Passenger Vehicles, while Commercial Vehicles are experiencing significant upgrades driven by efficiency mandates.
End User:
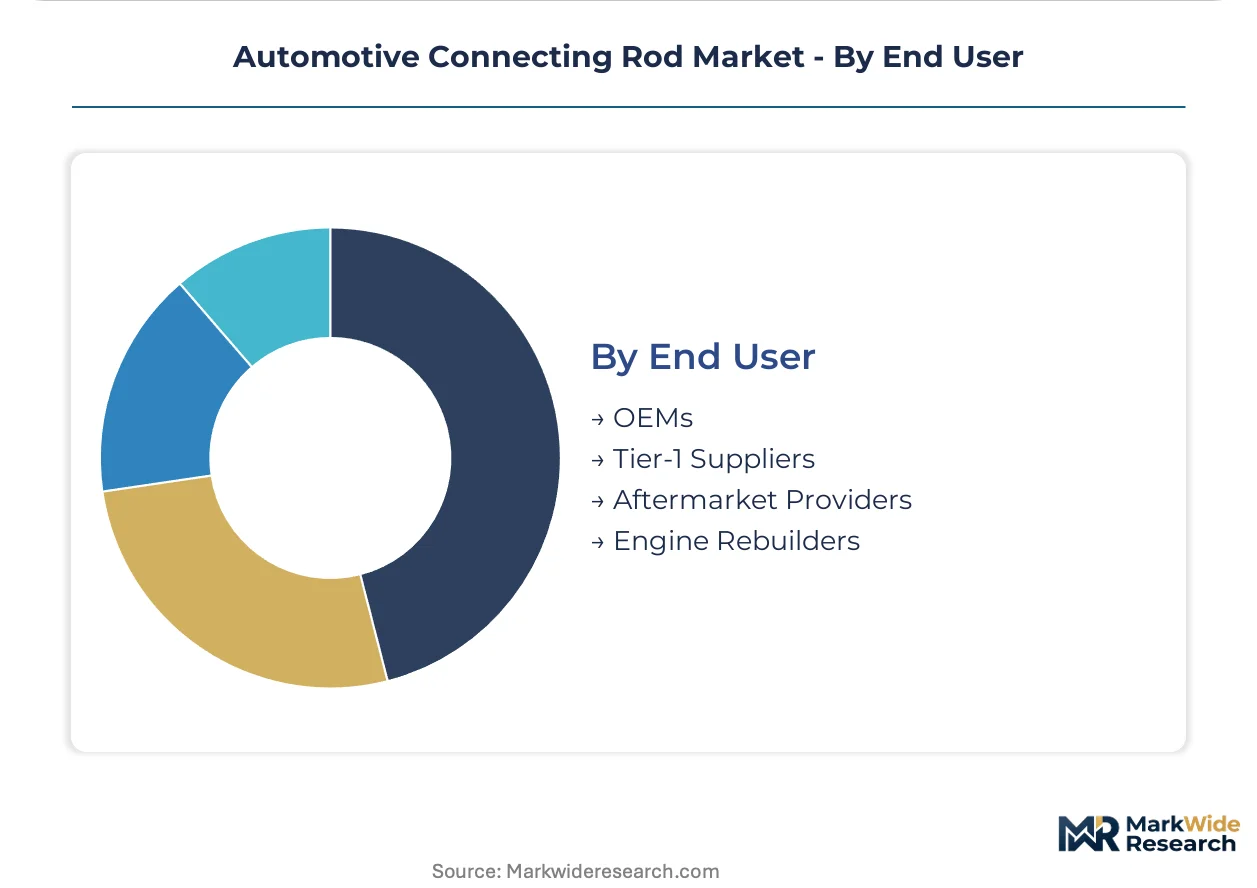
Different end-user types exhibit distinct purchasing patterns and demand characteristics for automotive connecting rods, from mass production to specialized aftermarket needs.
- OEMs:Original Equipment Manufacturers are primary purchasers for new vehicle assembly, driving innovation in lightweight materials and designs to meet efficiency goals. Procurement is influenced by EU Green Deal regulations.
- Aftermarket Providers:Aftermarket providers supply replacement and performance-enhancing connecting rods for vehicle repair, engine rebuilding, and enthusiast tuning. Strong demand for high-strength rods exists in the North American aftermarket.
- Tier-1 Suppliers:Tier-1 suppliers procure raw materials or semi-finished rods, manufacturing final components for direct supply to OEMs under stringent quality specifications.
- Engine Rebuilders:Engine rebuilders purchase specific connecting rods for restoring or upgrading existing engines, requiring a broad portfolio of parts.
This segment reveals the dual nature of demand, with OEMs dictating volume and innovation, and Aftermarket Providers serving specialized repair and performance needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's robust domestic automotive industry anchors significant production and demand for connecting rods, particularly for high-volume passenger vehicles. This region drives innovation in cost-effective manufacturing techniques like powder metallurgy. European production capacity faces challenges from volatile energy prices, pushing manufacturers toward lightweight materials and advanced designs.
China
Demand for connecting rods in China is driven by the sheer scale of its automotive manufacturing and the ongoing modernization of its commercial vehicle fleet. China's GB standards for vehicle emissions compel automakers to specify lighter, more efficient engine components. Industrial clusters in the Yangtze River Delta and Pearl River Delta are centers for high-volume powder metal connecting rod production.
Germany
European production capacity for high-strength forged steel connecting rods concentrates in Germany, serving both premium passenger vehicles and commercial vehicle sectors. The EU Green Deal framework directly influences material selection and design for enhanced engine efficiency. Bavaria and North Rhine-Westphalia house key R&D and manufacturing facilities for precision engine components.
United States
The United States market sustains demand for durable connecting rods from its heavy-duty commercial vehicle sector and a strong aftermarket performance segment. EPA emissions standards push for engine efficiency improvements, impacting component specifications. Michigan and Ohio remain critical hubs for automotive component manufacturing and engine rebuilding specialists.
India
Diesel engines in India represent a significant demand segment for connecting rods, particularly for commercial vehicles and agricultural machinery, prioritizing durability under demanding conditions. The country's Bharat Stage (BS) emission norms are driving a shift towards more efficient diesel engine designs. Maharashtra and Tamil Nadu are key automotive manufacturing states with strong component supplier networks.
Japan
Growth in Japan for hybrid and plug-in hybrid vehicles creates a durable market for optimized connecting rods designed for efficient, downsized internal combustion engines. METI regulations and fuel economy targets encourage lightweight component development. The Kanto region, including Tokyo and its surrounding prefectures, is a center for advanced engine component research and manufacturing.
Automotive Connecting Rod Market Key Industry Players
Global majors compete with regional champions across material science and manufacturing process capabilities, influencing competitive positioning. The market demonstrates a tiered structure, with some players focusing on high-volume cost efficiency and others on specialized, high-performance applications. Strategic partnerships for technology sharing and geographic expansion into emerging automotive markets are dominant competitive moves.
Among Germany-based fabricators, MAHLE GmbH and Schaeffler Technologies AG & Co. KG exemplify engineering-driven excellence, leveraging extensive R&D in lightweight materials and precision components. Federal-Mogul Motorparts LLC, a US-based entity, occupies a significant position within the aftermarket segment, providing a broad portfolio for engine rebuilders and performance tuners, often bypassing OEM supply channels.
| Leading Market Players |
|---|
| CP-Carrillo |
| Albon Engineering & Manufacturing Plc. |
| MAHLE GmbH |
| JD Norman Industries |
| Wiseco |
| Federal-Mogul Motorparts LLC |
| Schaeffler Technologies AG & Co. KG |
| Nangong Jingqiang Connecting Rod Co. Ltd. |
| Cummins Inc. |
| Others |
Cost & Logistics Intelligence
Stricter EPA emissions standards and EU Green Deal mandates compel OEMs to demand lighter, more efficient connecting rods, which in turn drives suppliers to invest in advanced materials, impacting component pricing and supply chain configurations.
Pricing Analysis
Warranty and after-sales service bundling often differentiates pricing for connecting rods, particularly in the aftermarket segment where engine rebuilders seek comprehensive solutions. The dominant pricing model for OEMs involves contract-based long-term offtake agreements, while aftermarket providers operate on a per-unit transactional basis. Price differentiation stems from material type, manufacturing precision, and adherence to ISO 9001 quality standards. Pricing softness is evident in the high-volume passenger vehicle segment, driven by cost-efficiency pressures and the long-term threat of electrification.
Supply Chain Analysis
Single-source vulnerability sits with specialized suppliers for high-strength forged steel connecting rods, particularly in Germany, due to volatile energy prices and niche manufacturing expertise. Geographic supply concentration for high-volume powder metal rods resides predominantly in China, serving its massive domestic automotive industry. The market draws from critical raw materials including high-grade steel, titanium, and aluminum alloys, making input material price volatility a significant risk. Distribution runs through direct OEM supply channels and broad aftermarket networks, especially in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates under supply constraints, particularly for high-strength forged steel connecting rods where European production capacity is hardening due to volatile energy prices. This bottleneck for advanced components can prop up pricing for specialized offerings.
For Market Incumbents: Acquire specialized powder metallurgy facilities in Asian manufacturing hubs to counter rising input material costs and expand high-volume production. Invest aggressively in advanced lightweight material R&D for hybrid powertrains, ensuring relevance against the long-term EV transition threat. Prioritize talent development programs for metallurgists and process engineers to mitigate specialized talent scarcity. Maintain ISO 9001 certifications as a baseline for OEM supplier qualification.
For New Entrants and Emerging Players: Price-point gaps between high-performance titanium alloy rods and cost-sensitive powder metal components offer entry opportunities. Target emerging automotive manufacturing markets in Southeast Asia and Latin America for cost-effective, standard-duty connecting rods. A direct-to-consumer go-to-market strategy can capture demand in the North American performance aftermarket for custom-engineered, high-strength rods. Focus on niche applications where established players face high retooling costs for new designs.
For Investors and Strategic Acquirers: The window for entry favors mid-sized specialists in advanced powder metallurgy or lightweight composite materials with strong intellectual property. Long-term viability, spanning the next five to ten years, will hinge on capabilities for hybrid powertrain components and durable commercial vehicle solutions. Target companies with established aftermarket distribution networks or those developing next-generation fracture-splitting technologies. Monitor the accelerating adoption rate of hybrid vehicles across major automotive markets as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Powder Metallurgy Capacity | Increases cost-efficiency for high-volume passenger vehicle segments, particularly in China's domestic automotive industry. |
| Invest in Advanced Composite R&D | Develops ultra-lightweight solutions for niche motorsport and high-performance applications, meeting extreme weight reduction goals. |
| Regional Production for Emerging Markets | Establishes local supply for cost-effective, standard-duty connecting rods in growing automotive manufacturing regions like Southeast Asia. |
| Partner for Hybrid Powertrain Components | Secures market share in the growing segment of optimized connecting rods for efficient, downsized internal combustion engines. |
| Strengthen Aftermarket Distribution | Broadens reach to engine rebuilders and performance tuners, sustaining demand for high-strength rods in North America. |
Research Approach
Independent corroboration across vehicle production databases, regulatory filings, and industry association reports underwrites the qualitative findings of this study. Primary interviews with OEM procurement managers, Tier-1 engineering leads, and aftermarket distributors provided direct market insights. This approach combined top-down market sizing with bottom-up validation, ensuring comprehensive data triangulation.
The forecast window was anchored to historical reference periods, with market projections extending across the analysis window. This framework modeled segmentation across product type, engine type, application, and end-user categories, alongside regional production clusters. Compound annual growth rates were derived from projected vehicle production volumes and anticipated emissions regulation timelines.
Inputs from published automotive production data and regulatory bodies were available through the study window; gaps in real-time supply chain cost data introduce uncertainty bands. Forecasts reflect assumptions regarding the pace of EV transition and raw material price volatility. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Evaporative Emission Control (EVAP) System Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
Automotive Light Bars Market
Automotive Components
Automotive Hardware Market
Automotive Components
Automotive Polycarbonate Glazing Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Stainless Steel Tubes Market
Automotive Components
China Automotive Composites Market
Automotive Components
Automotive Clutch Disc Market
Automotive Components
Automotive Exhaust Manifolds Market
Automotive Components
Automotive Headliners Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market
Automotive Components
Russia Automotive Pneumatic Actuators Market
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
Automotive Skid Plate Market