
 Automotive Door Module Market | 2026-2036
Automotive Door Module Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Door Module Market Analysis
Mechatronics engineering talent is rotating toward automotive electronics hubs as door modules absorb more sensor and actuator functions. Brose Fahrzeugteile SE & Co. KG leverages its specialization in window lift and closure systems to sustain premium OEM relationships across Europe. Magna International Inc. anchors North American supply through integrated module assembly plants in Michigan and Ontario. Continental AG differentiates via software-defined door control units that manage multiple electromechanical functions.
An automotive door module is an integrated assembly housing window regulators, latches, wiring harnesses, and side-impact beams within a single carrier structure, typically manufactured through injection-molded plastic or stamped metal framing processes and designed to reduce assembly time at vehicle final assembly lines. The module serves as a functional sub-system that consolidates multiple door-mounted mechanisms into a pre-tested unit delivered directly to OEM assembly sequences. Power door lock and window regulator categories dominate current revenue as these electromechanical functions carry the highest replacement frequency and technology refresh cycles. Wiring harness segments within door modules are experiencing accelerated complexity growth as manufacturers integrate side-curtain airbag sensors, ambient lighting, and mirror control circuits into unified electrical architectures.
The National Highway Traffic Safety Administration enforces FMVSS 214 side-impact protection standards that directly dictate beam reinforcement specifications and intrusion resistance testing protocols for door module suppliers selling into the US market. Europe's ECE R95 and the EU General Safety Regulation mandate automatic emergency calling and advanced side-impact detection, pushing module integrators to embed crash sensors and communication hardware directly into door structures. Stakeholders must monitor how cybersecurity requirements under UN R155 and R156 vehicle regulations reshape authentication protocols for wireless entry systems embedded in next-generation door electronics.
Market Dynamics
Platform electrification from manufacturers including Tesla and BYD is compressing development cycles for door module architectures, forcing suppliers to integrate sensor fusion and wireless entry systems into unified carrier structures ahead of traditional refresh timelines.
Growth Catalysts
- ECE R95 side-impact mandates:Europe's reinforced intrusion resistance standards push OEMs toward advanced beam architectures that consolidate safety-critical functions within door modules.
- Mechatronics talent migration:Engineering expertise is concentrating in Stuttgart and Munich as electronics integration demands outpace mechanical-only module capabilities.
- Window regulator refresh cycles:Electromechanical replacement frequency sustains aftermarket revenue streams and technology upgrade pathways for integrated door systems.
Market Restraints
- Resin cost volatility:Injection-molded carrier structures face margin pressure from petroleum-based polymer feedstock fluctuations that resist long-term contract hedging.
- Supplier concentration in Baden-Württemberg:Germany's premium cluster creates geographic vulnerability for OEMs dependent on just-in-time module delivery from a single industrial basin.
- Wiring harness complexity ceiling:Physical space constraints within door cavities limit further sensor integration without fundamental carrier redesign.
Strategic Opportunities
- Software-defined door control units:Continental's architecture model enables over-the-air functional updates that extend module lifecycle value beyond hardware replacement.
- UN R155 cybersecurity protocols:Authentication hardware mandates for wireless entry systems create premium tiering opportunities for compliant module suppliers.
- BYD platform standardization:China's electric vehicle volume production offers scale partnerships for simplified module variants across multiple nameplates.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL ratings for crash sensor integration extend validation cycles beyond traditional mechanical component schedules.
- Legacy vehicle electrical architectures:12V systems in existing fleets resist seamless integration with 48V-enabled smart door modules without harness redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Door Module Market |
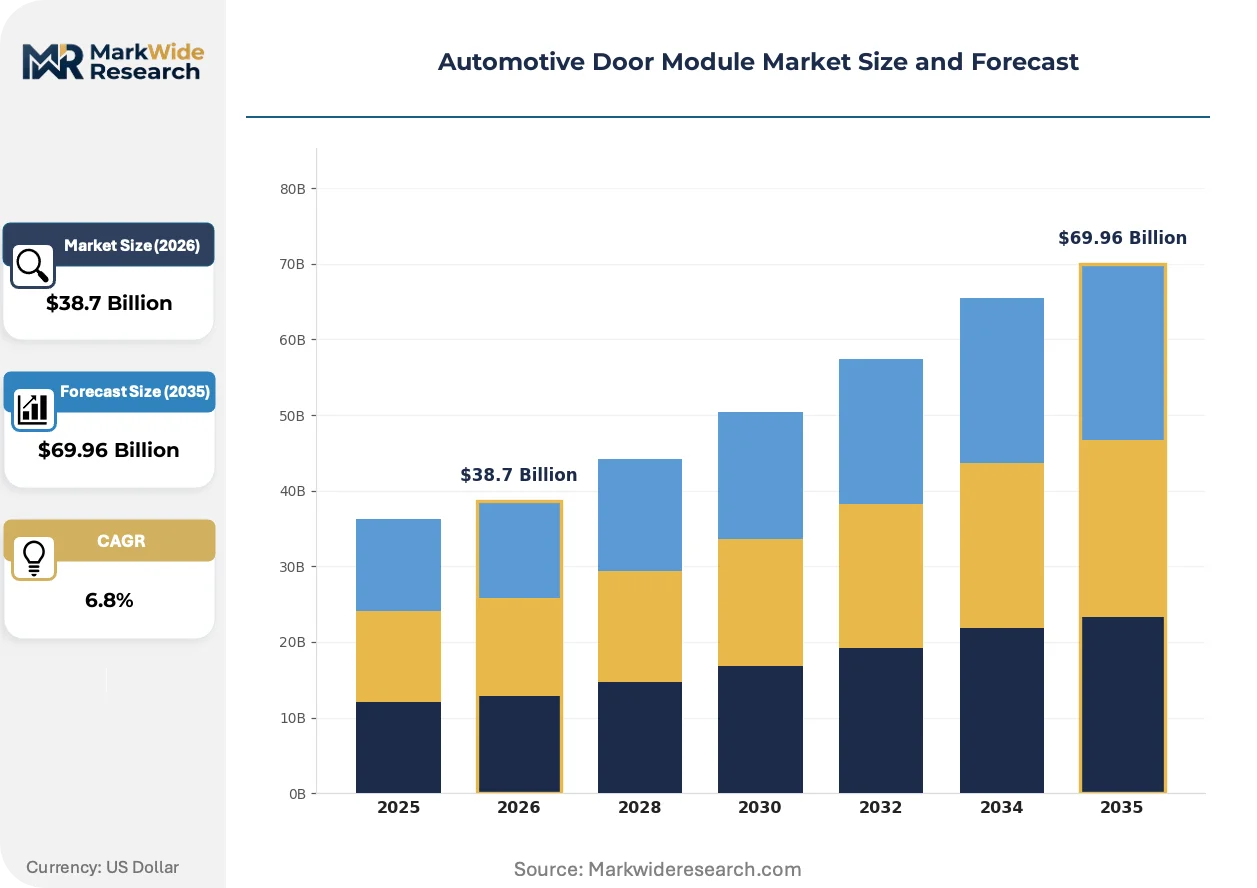
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Door Lock, Window Regulator, Side Impact Beam, Wiring Harness End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Mechanical, Electrical, Pneumatic, Hybrid Material: Plastic, Metal, Composite, Glass |
| Companies Covered | Aptiv PLC, Valeo SA, Magna International Inc., Denso Corporation, ZF Friedrichshafen AG, Brose Fahrzeugteile SE & Co. KG, Robert Bosch GmbH, Aisin Corporation, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Door Module Market Emerging Trajectories
Door module engineering is pivoting from mechanical consolidation toward electromechanical software integration, with crash sensing and entry authentication functions migrating onto unified control platforms.
Smart surface technology is bifurcating door panel interfaces into capacitive touch zones and physical backup controls. Premium OEMs in Germany are deploying hidden actuator arrays that eliminate traditional handle mechanisms entirely. This architecture is compressing supplier tiers by merging electronics, software, and mechanical actuation into single-source relationships.
NHTSA FMVSS 214 side-impact testing protocols are expanding to evaluate sensor-integrated beam performance under oblique collision angles. Suppliers must now validate crash data transmission speeds alongside structural intrusion metrics. The US market is responding with pre-certified module platforms that reduce OEM homologation overhead.
Fleet procurement of standardized module variants is replacing model-specific custom engineering. Rental and commercial vehicle operators in North America now specify configurable door electronics that reduce spare part proliferation. This pattern is most visible in Michigan-based assembly plants serving commercial van platforms.
Automotive Door Module Market Segmentation
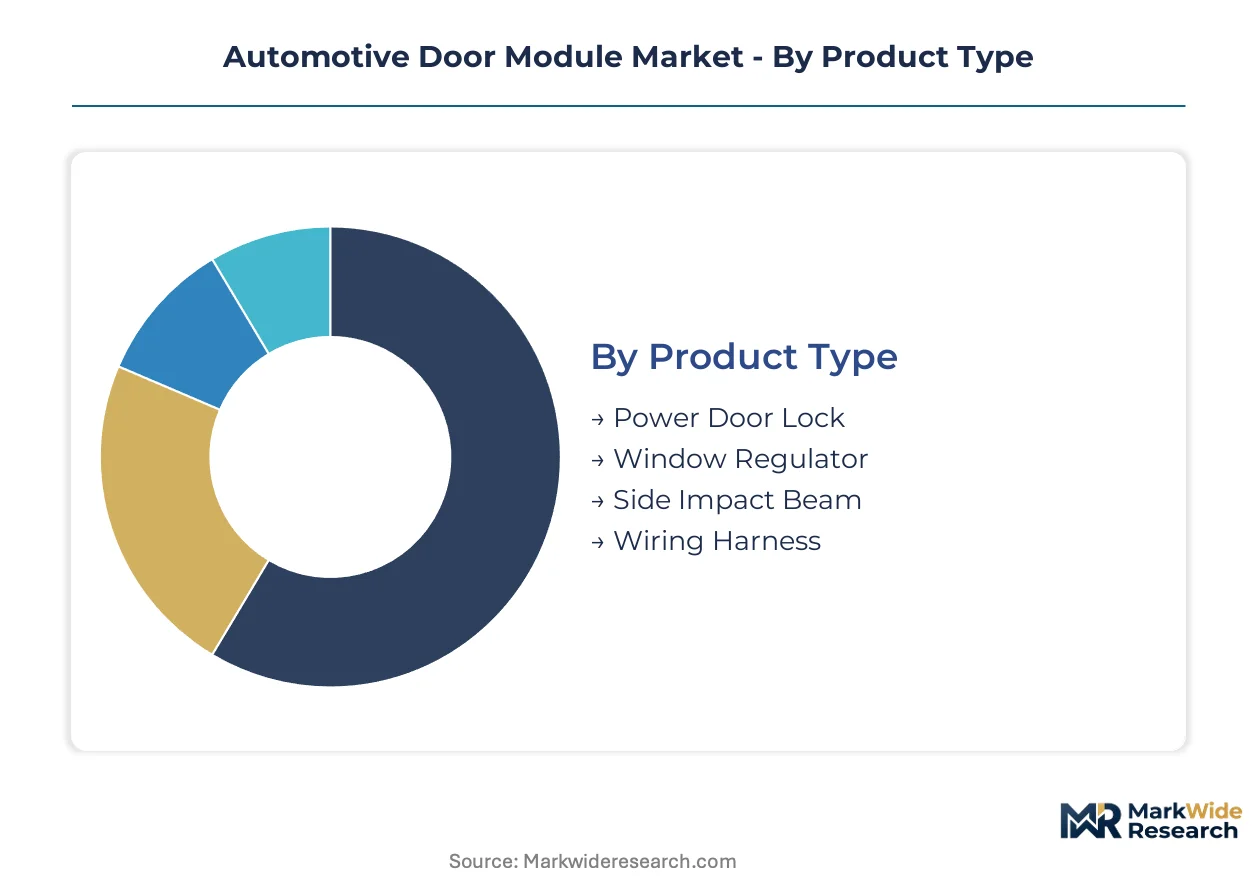
Door module segmentation reveals how supplier capabilities align with distinct technical requirements across vehicle programs. Product architecture choices directly determine which manufacturing competencies—stamping, injection molding, or electronics integration—dominate procurement decisions for each category.
Product Type:
Domestic assembly plants in Germany and the United States consume the highest volumes of integrated door modules, while export-led demand concentrates in Chinese EV platforms seeking standardized carrier structures.
- Power Door Lock:Electromechanical latch mechanisms incorporating actuator motors and position sensors within sealed housings. German premium OEMs around Stuttgart specify these for their highest-volume sedans, driven by ECE R95 mandates for reinforced intrusion resistance that integrate locking hardware with crash-rated carrier frames.
- Window Regulator:Cable-drive or scissor-lift mechanisms that translate motor rotation into vertical glass movement. Michigan-based assembly plants source these most intensively for full-size pickup platforms, constrained by wiring harness complexity ceilings that limit further sensor integration without carrier redesign.
- Side Impact Beam:High-strength steel or aluminum reinforcement members welded or bolted to door cavities. OEMs in Baden-Württemberg specify these for compliance with European side-impact protocols.
- Wiring Harness:Bundled conductor assemblies routing power and signals to door-mounted functions. Chinese manufacturers are absorbing these into unified electrical architectures for BYD platform standardization.
Window regulator holds the largest share; momentum sits with power door lock as cybersecurity mandates reshape authentication hardware requirements.
End User:
Margin structures vary sharply across this category, with captive OEM operations commanding price premiums over independent aftermarket channels.
- OEMs:Vehicle manufacturers specifying complete door modules for original factory installation. Tesla and BYD compress development cycles by sourcing integrated electromechanical platforms from single-source relationships.
- Tier-1 Suppliers:System integrators like Brose and Magna consolidating subcomponent procurement into delivered modules. These entities concentrate engineering talent in Stuttgart and Munich as electronics integration demands accelerate.
- Aftermarket Providers:Independent distributors serving collision repair and wear-item replacement. North American fleet operators now specify configurable door electronics that reduce spare part proliferation.
- Vehicle Assemblers:Contract manufacturers performing final module attachment at assembly lines. Ontario-based plants anchor regional supply through just-in-time delivery sequences.
OEMs dominate absolute volume; aftermarket providers are expanding most quickly as fleet standardization creates replacement part consolidation opportunities.
Technology:
Technology selection tracks with platform electrification intensity, with 48V architectures displacing legacy 12V mechanical systems in premium vehicle segments.
- Mechanical:Purely kinematic linkages without powered actuation. These persist in economy vehicle segments where cost minimization overrides feature content.
- Electrical:Motor-driven actuators with electronic control units managing position and force feedback. Continental's software-defined door control units exemplify this tier's migration toward over-the-air functional updates.
- Pneumatic:Compressed-air actuation for central locking in commercial vehicle applications. Limited to heavy-duty platforms where electrical system redundancy is prioritized.
- Hybrid:Combined electromechanical architectures with mechanical backup for safety-critical functions. Premium German OEMs deploy hidden actuator arrays that eliminate traditional handle mechanisms entirely.
Electrical technology commands the dominant position; hybrid systems are climbing the fastest as smart surface interfaces bifurcate door panel designs.
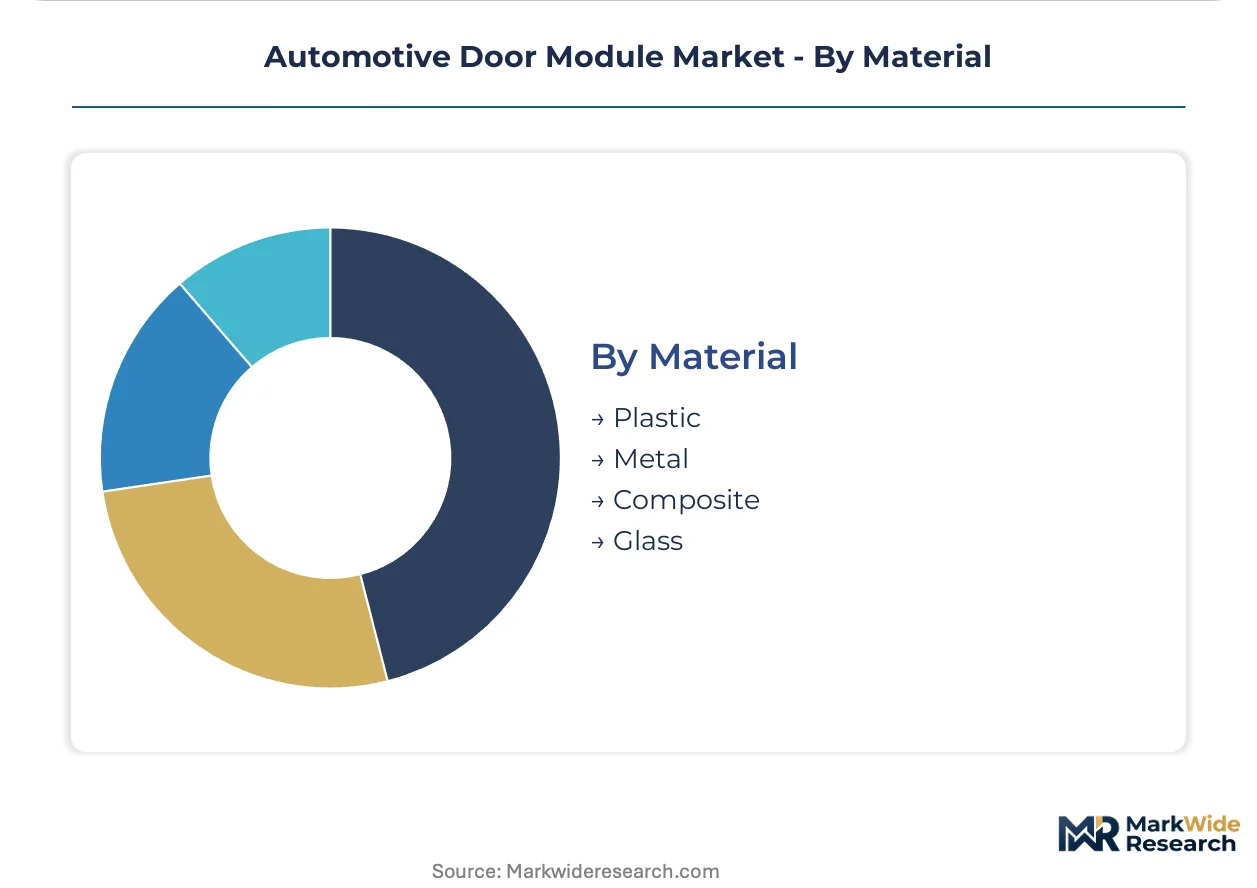
Material:
Material selection reflects the tension between lightweighting imperatives and crash performance requirements, with resin cost volatility pressuring injection-molded carrier margins.
- Plastic:Injection-molded polymer carriers consolidating multiple attachment points into single structures. Petroleum-based feedstock fluctuations resist long-term contract hedging for these components.
- Metal:Stamped steel or aluminum framing providing structural rigidity for side-impact beams. German suppliers leverage this category for ECE R95 compliance in premium vehicle architectures.
- Composite:Fiber-reinforced polymers combining stiffness with mass reduction. Emerging applications in EV platforms seeking range optimization through component lightweighting.
- Glass:Tempered or laminated glazing integrated into module assembly sequences. Window regulator mechanisms must accommodate increasing glass area in modern vehicle designs.
Metal retains the largest installed base; composite materials are gaining share fastest as electric vehicle platforms prioritize mass reduction for range extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA's FMVSS 214 side-impact standards anchor North American procurement patterns, while ECE R95 mandates reshape European sourcing and China's GB standards accelerate domestic EV platform integration.
Germany
Baden-Württemberg's premium automotive cluster concentrates door module engineering around Stuttgart and Munich as mechatronics talent migrates toward electronics integration. ECE R95 reinforced intrusion standards push OEMs toward advanced beam architectures that consolidate safety-critical functions. Suppliers in this region leverage software-defined control units to manage multiple electromechanical functions within unified carrier structures.
United States
Michigan-based assembly plants anchor North American supply through integrated module facilities serving full-size pickup and commercial van platforms. NHTSA FMVSS 214 testing protocols now evaluate sensor-integrated beam performance under oblique collision angles, forcing pre-certified module platforms that reduce OEM homologation overhead. Fleet procurement of standardized variants is replacing model-specific custom engineering in Ontario and Michigan corridors.
China
BYD platform standardization drives volume demand for simplified module variants across multiple electric vehicle nameplates. The country's GB standards for vehicle safety and MIIT regulations for intelligent connected vehicles push module integrators toward embedded crash sensors and wireless entry authentication hardware. Yangtze River Delta manufacturing bases absorb wiring harness complexity into unified electrical architectures for domestic EV production.
Japan
METI's vehicle electrification roadmaps and JIS standards for automotive components guide supplier investment toward 48V-enabled smart door modules. Kansai and Chubu industrial regions host system integrators consolidating window regulator and latch mechanisms into pre-tested carrier units. Japanese OEMs prioritize hybrid electromechanical architectures with mechanical backup for safety-critical functions in premium vehicle segments.
South Korea
Seoul Capital Area suppliers respond to MFDS-equivalent vehicle safety benchmarks and domestic OEM electrification timelines by compressing development cycles for integrated door electronics. Busan-Ulsan manufacturing corridors specialize in injection-molded carrier structures facing resin cost volatility from petroleum-based polymer feedstock fluctuations. Korean battery-electric platforms drive demand for lightweight composite door modules that extend vehicle range.
Automotive Door Module Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market consolidating around full-system module providers capable of delivering pre-tested electromechanical platforms directly to OEM assembly sequences. The structure rewards backward integration into injection molding, stamping, and electronics control, while punishing pure-play mechanical component suppliers unable to absorb sensor fusion and software functions. Three archetypes dominate: European mechatronics specialists with premium OEM relationships, North American scale assemblers serving high-volume truck platforms, and Asian diversified industrials leveraging EV platform standardization. Competitive moves concentrate on captive supply of critical subcomponents and geographic expansion into Chinese EV manufacturing corridors.
Among the integrated European tier, Continental AG and Brose Fahrzeugteile SE & Co. KG exemplify the shift toward software-defined architectures and window closure specialization respectively. Magna International Inc. anchors the North American scale-assembler archetype through Michigan and Ontario assembly plants. These three entities occupy positions that illustrate how supplier capabilities align with distinct regional procurement patterns—European premium electronics integration, North American high-volume truck supply, and Asian EV platform standardization.
| Leading Market Players |
|---|
| Aptiv PLC |
| Valeo SA |
| Magna International Inc. |
| Denso Corporation |
| ZF Friedrichshafen AG |
| Brose Fahrzeugteile SE & Co. KG |
| Robert Bosch GmbH |
| Aisin Corporation |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
Thirty-five to forty-five day module lead times from Baden-Württemberg suppliers compress pricing power for North American OEMs while reinforcing Germany's premium tier dominance through just-in-time dependency. This inventory band concentrates procurement leverage among integrated mechatronics specialists capable of delivering pre-tested electromechanical platforms.
Pricing Analysis
Price spreads between German premium modules and Chinese standardized variants exceed three-to-one, reflecting certification grade differentiation under ECE R95 and UN R155 mandates. Three-tier pricing structure across premium, standard, and economy levels tracks with electronics integration depth, software-defined control units commanding the highest tier. Cost compression in economy segments is intensifying because petroleum-based polymer feedstock fluctuations resist long-term contract hedging. Fleet procurement teams exhibit the highest price sensitivity, while premium German OEMs prioritize certification compliance over unit cost.
Supply Chain Analysis
Inventory buffers of fifteen to twenty days at Michigan assembly plants expose just-in-time sequences to disruption from single-source dependencies in Baden-Württemberg. Manufacturing gravity centers on Germany, China, and Mexico, with injection-molded carriers and stamped steel beams drawing from regional petrochemical and metals processing corridors. Single-source vulnerability concentrates in wiring harness subassemblies sourced from Yangtze River Delta facilities. Distribution runs through Tier-1 integrator hubs delivering pre-tested modules directly to OEM final assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Door module supply exhibits defensive moat characteristics through regulatory entrenchment: ECE R95 and FMVSS 214 certification requirements create multi-year validation barriers that protect incumbent positions from rapid displacement.
For Market Incumbents: Compound software-defined control unit capabilities through backward integration into sensor fusion hardware, defending against emerging electronics specialists from Shenzhen. Prioritize captive supply of crash-rated beam stampings to lock out new entrants lacking ASIL-rated validation infrastructure. Certification investment in UN R155 cybersecurity protocols represents the critical lever for premium tier retention. For New Entrants and Emerging Players: Anchor in North American fleet procurement channels where standardized module variants replace model-specific engineering, the most penetrable white-space. Target commercial van platforms in Michigan-Ontario corridors seeking configurable door electronics that reduce spare part proliferation. A software-only entry angle—supplying authentication algorithms to incumbent module integrators—bypasses capital-intensive carrier manufacturing. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming automotive door module divisions lacking software integration capabilities. Long-term viability hinges on 48V architecture transition completion and smart surface technology adoption curves. The signal to watch is BYD platform standardization rate: accelerated volume consolidation favors simplified module suppliers over complex custom engineering shops.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Door Control Investment | Continental's architecture enables over-the-air updates that extend module lifecycle value beyond hardware replacement cycles. |
| Platform Standardization Partnership | BYD's volume production offers scale economies for simplified module variants across multiple electric vehicle nameplates. |
| Cybersecurity Certification Program | UN R155 compliance creates premium tiering opportunities for suppliers embedding authentication hardware in wireless entry systems. |
| Geographic Manufacturing Footprint Expansion | Ontario and Michigan assembly plants anchor North American supply through just-in-time delivery to full-size pickup platforms. |
| Composite Material Lightweighting Transition | Fiber-reinforced polymers reduce door module mass for electric vehicle range extension in Korean battery-electric platforms. |
Methodological Framework
Desk research of regulatory filings from NHTSA and UNECE, trade databases tracking polymer feedstock flows, and vehicle production registries preceded structured interviews with Tier-1 supplier procurement directors, OEM platform engineers, and aftermarket distribution heads. Secondary validation drew from ECE R95 homologation records, FMVSS 214 test protocols, and customs data on injection-molded carrier imports. Bottom-up segmentation modeling triangulated against top-down automotive production forecasts.
Variance decomposition across technology, material, and end-user dimensions anchored the analytical framework throughout the forecast period. Segmentation tracked vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from regression analysis of historical module content growth against electrification penetration curves and safety mandate implementation timelines. Forecast inputs incorporated mechatronics talent migration patterns and resin cost volatility indices.
Material uncertainties — tariff reconfigurations affecting Mexico-Germany component flows, petroleum price shocks disrupting polymer economics, and cybersecurity mandate enforcement delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and OEM platform consolidation trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
GCC Automotive Lubrication Services Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Automotive Commutator Market
Automotive Components
Global Cylinder Deactivation System Market
Automotive Components
Automotive Brake Rotor Market
Automotive Components
Global Automotive Collapsible Steering Column Market
Automotive Components
China Automotive Actuators Market
Automotive Components
North America Automotive Glass Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
India Automotive Stamping Market
Automotive Components
Automotive Catalyst Market
Automotive Components
Automotive Metal Market
Automotive Components
Aftermarket Automotive Parts & Components Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Asia-Pacific Automotive Composites Market
Automotive Components
Automotive Gudgeon Pin Market