
 Automotive Structural Sheet Market | 2026-2036
Automotive Structural Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Structural Sheet Market Analysis
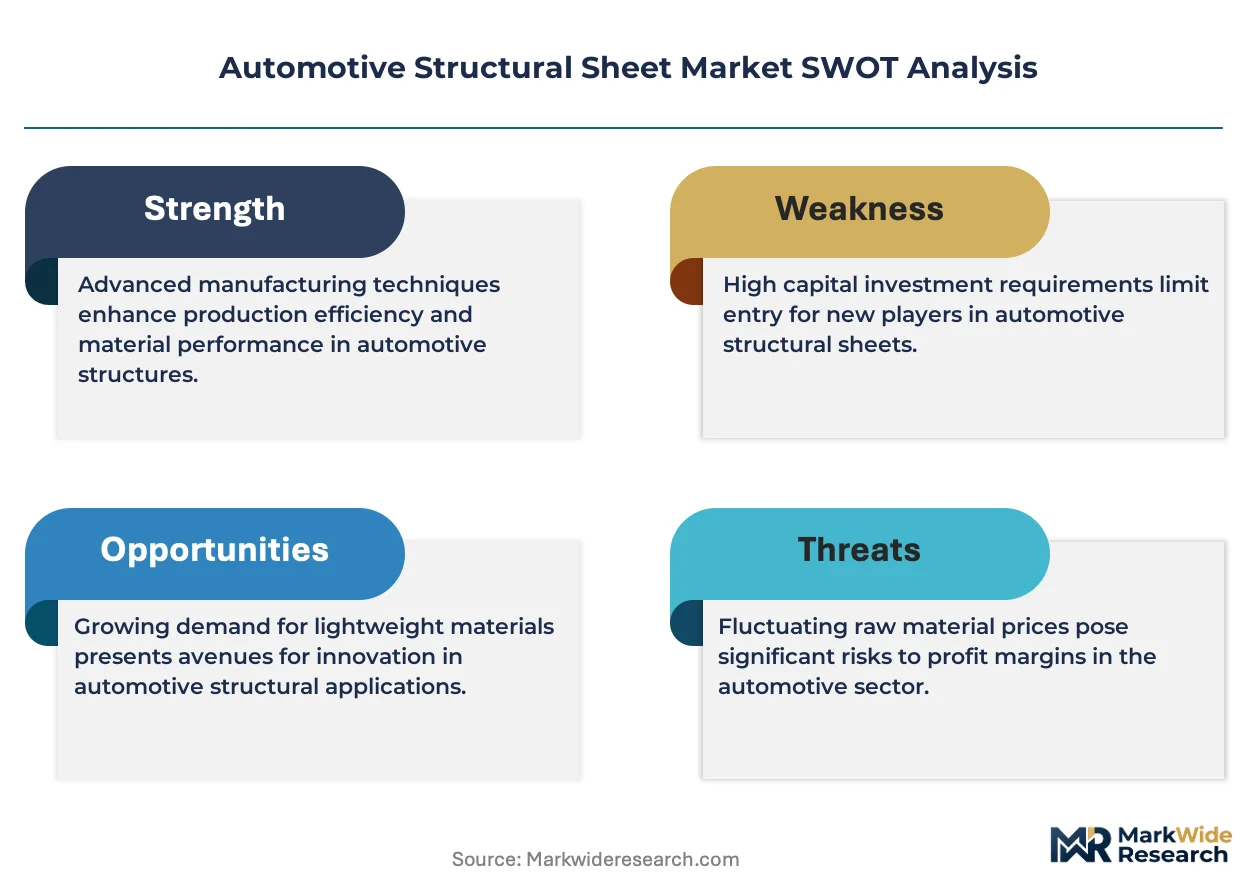
Advanced high-strength steel (AHSS) grade qualification is collapsing the gap between legacy mild steel and aluminum-intensive architectures across passenger vehicle programs. ArcelorMittal leverages its integrated R&D pipeline to sustain proprietary AHSS formulations for OEM crashworthiness targets. POSCO anchors Asia-Pacific supply through dedicated automotive service centers in South Korea and China. Nippon Steel Corporation differentiates via ultra-high-strength grades above 980 MPa tensile strength for battery enclosure applications.
Automotive structural sheet denotes flat-rolled metal or composite substrates engineered to 0.5–3.0 mm gauge ranges, formed through hot or cold stamping into load-bearing vehicle components including pillars, rails, and floor pans, with primary purpose of maintaining occupant safety cell integrity while minimizing curb weight. Steel retains dominant share in production process segmentation due to cost-efficient stamping throughput at million-unit scales, though aluminum roll forming gains share in electric vehicle body applications where 30–50% mass reduction offsets material cost premiums. Composite stamping occupies niche positions in premium structural reinforcement segments where carbon fiber-reinforced thermoplastics enable part consolidation.
F-Gas Regulation and REACH in Europe restrict fluorinated greenhouse gas use in aluminum sheet production processes, while EPA tailpipe standards in the United States push OEMs toward lighter structural materials to meet fleet efficiency mandates. China's GB standards and MIIT new energy vehicle mandates enforce specific lightweighting coefficients that directly translate to structural sheet specification upgrades. Stakeholders must monitor evolving crash test protocols from NHTSA and Euro NCAP, as these agencies progressively weight pedestrian protection and offset collision metrics that favor multi-material sheet architectures over homogeneous steel designs.
Market Dynamics
Electric vehicle platform architectures are compressing design cycles for structural sheet specifications, forcing simultaneous optimization of crash performance, thermal management, and mass reduction in single-substrate solutions.
Growth Catalysts
- EU Green Deal vehicle emission targets:OEMs in Germany and France must achieve fleet-wide CO2 reductions, mandating AHSS and aluminum substitution in body-in-white structures.
- Battery enclosure thermal runaway protection:Ultra-high-strength steel grades above 980 MPa enable thinner-gauge protection plates that maintain structural integrity during cell failure events.
- China's MIIT new energy vehicle mandates:Lightweighting coefficients enforced through GB standards require structural sheet upgrades across domestic EV production lines.
Market Restraints
- Aluminum sheet energy cost volatility:Smelting electricity inputs in China and Russia create price instability that disrupts long-term OEM supply agreements.
- AHSS stamping die wear rates:Higher forming forces accelerate tool degradation, requiring capital-intensive press retrofits that Tier-1 suppliers defer.
- F-Gas Regulation process constraints:REACH restrictions on fluorinated greenhouse gases limit conventional heat treatment options for certain aluminum alloy tempering operations.
Strategic Opportunities
- India PLI scheme automotive manufacturing:Domestic OEM capacity expansion creates demand for localized structural sheet service centers with blanking and laser-cutting capabilities.
- Tailored blank laser welding:Continuous coil joining of multiple steel grades enables part consolidation in B-pillar and rail assemblies, reducing stamping press counts.
- Japan METI carbon-neutral steel certification:Hydrogen-reduced iron production creates premium positioning for low-emission structural sheet in luxury EV programs.
Industry Challenges
- Multi-material joining technician scarcity:Self-piercing rivet and flow-drill screw operations require specialized training that vocational programs have not scaled to meet.
- Euro NCAP pedestrian protection protocol updates:Hood and fender substrate specifications must be requalified against moving legform impactors, extending program validation timelines by 8-14 months.
- Legacy mild steel supply contract renegotiation:Long-term volume commitments with integrated mills block rapid grade transitions to third-generation AHSS formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Structural Sheet Market |
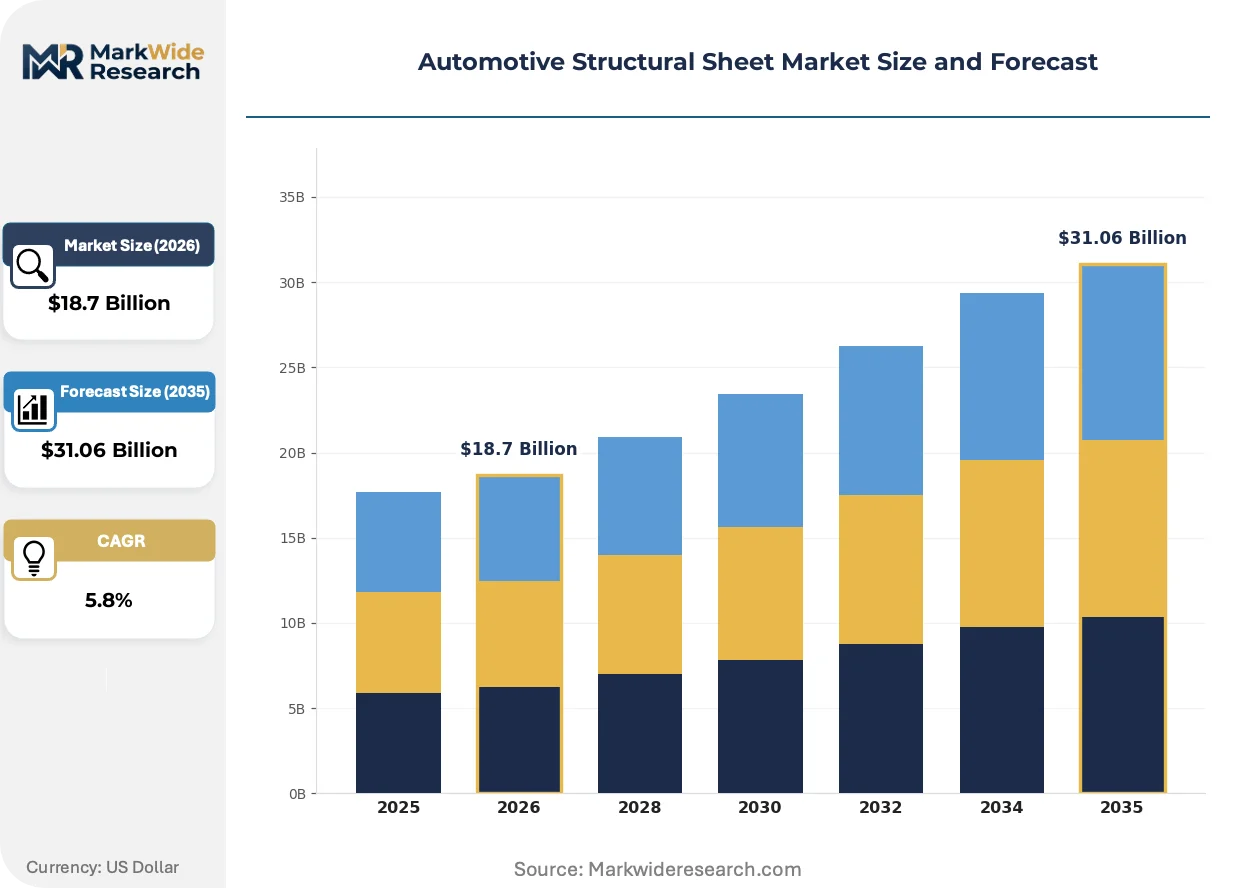
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Aluminum, Composite, Polymer Production Process: Stamping, Casting, Roll Forming, Welding End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Body, Chassis, Structural Reinforcement, Interior |
| Companies Covered | ArcelorMittal, POSCO, Nippon Steel Corporation, Thyssenkrupp AG, Magna International, Gestamp Automoción, United States Steel Corporation, Hyundai Steel, Nucor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Structural Sheet Market Emerging Trajectories
Hot stamping process innovation is collapsing the traditional trade-off between part complexity and strength-to-weight ratios, enabling single-piece solutions that previously required multi-component assemblies.
Press-hardened boron steel is miniaturizing section thicknesses in A- and B-pillar reinforcements while maintaining intrusion resistance. German OEMs have adopted 1,500 MPa grades across premium sedan architectures since 2022. The technology is miniaturizing the gauge ranges required for equivalent crash performance, reducing substrate mass by 20-35% against conventional dual-phase alternatives.
REACH authorization requirements for chromium trioxide in zinc coating passivation are forcing conversion to trivalent chromium and chrome-free alternatives. Surface treatment suppliers in Belgium and the Netherlands have accelerated qualification timelines for OEM corrosion warranties. European coating lines face 18-24 month revalidation cycles that compress available supply during transition periods.
Fleet procurement consolidation among rental and mobility-service operators is concentrating structural sheet specification power with volume buyers. Tier-1 stampers now negotiate directly with platform engineering teams at Uber, Lyft, and European equivalents rather than through traditional OEM purchasing departments. This channel shift is most pronounced in North American full-size SUV and van segments where fleet penetration exceeds 40% of new registrations.
Automotive Structural Sheet Market Segmentation
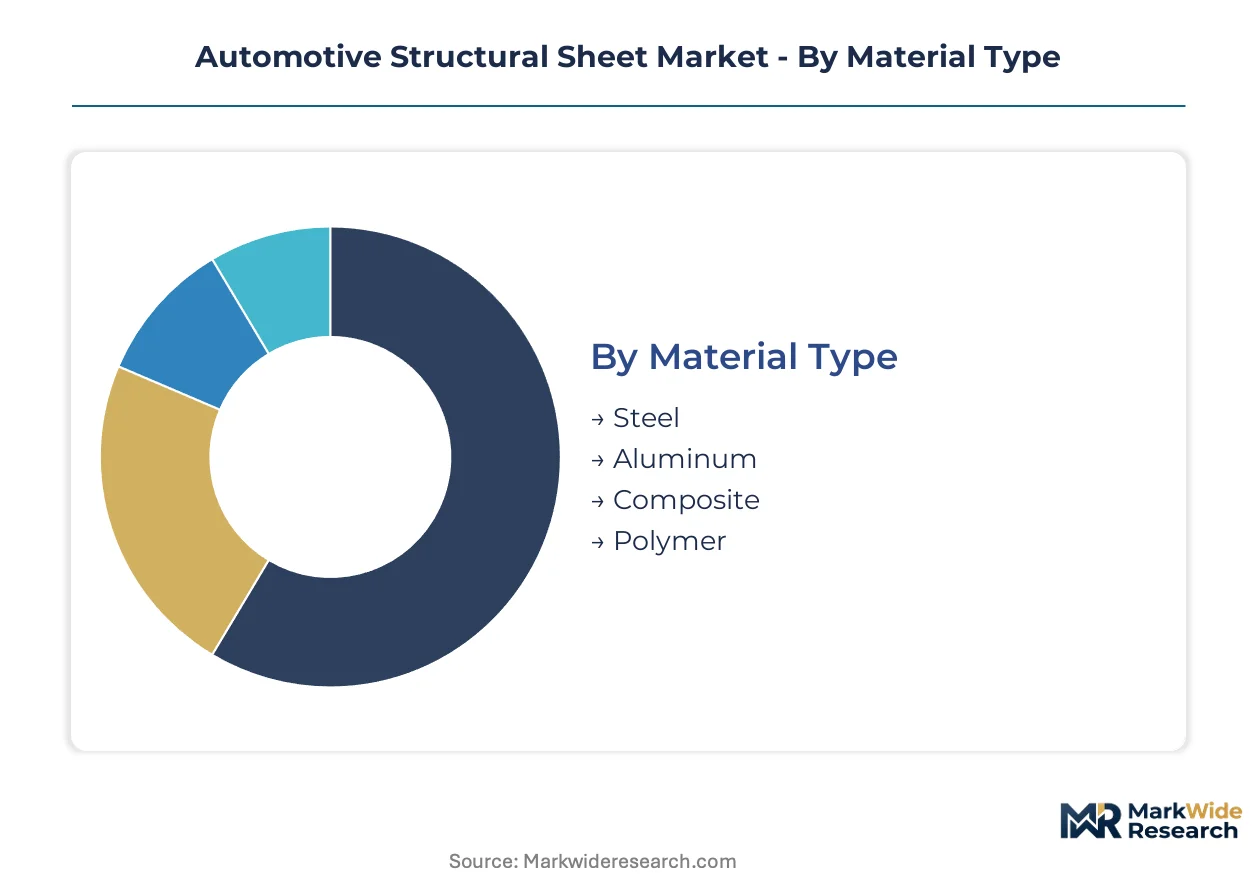
Automotive structural sheet specifications diverge sharply across material grades and forming methods, with procurement patterns splitting between legacy steel platforms and emerging aluminum-intensive electric vehicle architectures. Understanding these segment boundaries clarifies where capital deployment concentrates and which technical qualifications create supplier stickiness.
Material Type:
Steel grades dominate domestic supply chains across Germany, Japan, and the United States, while aluminum sheet flows through import-dependent channels from Canadian smelters and Middle Eastern primary producers.
- Steel:Advanced high-strength grades from 600 MPa to 1,500 MPa tensile strength enable gauge reduction in crash-critical pillars and rails. German OEMs source proprietary dual-phase and press-hardened boron formulations from integrated mills in the Ruhr Valley for body-in-white programs.
- Aluminum:5xxx and 6xxx series sheet in 1.0–3.0 mm gauges serves battery enclosure floors and hood outer panels where 30–50% mass reduction offsets material cost premiums. European F-Gas Regulation constraints on fluorinated greenhouse gas use during heat treatment tempering operations limit domestic alloy processing capacity.
- Composite:Carbon fiber-reinforced thermoplastic stampings consolidate multi-part assemblies in premium structural reinforcement segments.
- Polymer:Glass-mat thermoplastic and long-fiber-reinforced compounds occupy non-structural interior carrier applications with lower load-bearing requirements.
Steel commands the established base. The steepest expansion runs through aluminum.
Production Process:
Cost tier separation distinguishes high-volume stamping from capital-light roll forming, with welding and casting occupying intermediate positions based on part complexity and tooling amortization schedules.
- Stamping:Mechanical and hydraulic press lines process 0.5–3.0 mm coil stock into complex-draw panels at million-unit annual volumes. Tier-1 suppliers in Michigan and Stuttgart operate tandem press configurations with automated blank feeding for A-pillar and floor pan production.
- Roll Forming:Continuous bending of aluminum and steel coil produces straight and contoured sections for bumper beams and roof rails with minimal tooling changeover. Korean automotive service centers deploy roll forming for electric vehicle side member programs requiring 20–30% lighter section modulus than stamped alternatives.
- Casting:High-pressure die casting generates structural nodes and mounting brackets from aluminum alloys in integrated multi-material assemblies.
- Welding:Tailored blank laser welding joins dissimilar steel grades into single coil feeds for B-pillar reinforcements, reducing downstream press counts and part consolidation steps.
Stamping retains volume leadership. Roll forming gains share fastest in electric vehicle platform conversions.
End User:
Customer type determines specification authority, with OEM engineering teams controlling grade selection while Tier-1 stampers manage blanking logistics and aftermarket channels serve collision repair demand.
- OEMs:Platform engineering groups at Volkswagen, Toyota, and Ford define structural sheet grade specifications, corrosion warranties, and forming process requirements that propagate through supply contracts. Direct mill relationships secure allocation priority during coil shortages.
- Tier-1 Suppliers:Magna, Gestamp, and Benteler operate blanking and laser-cutting service centers proximate to OEM assembly plants, converting master coil inventory into sequenced part kits for just-in-time delivery.
- Aftermarket Providers:Independent distributors stock certified equivalent grades for collision repair networks, requiring traceability documentation to maintain OEM corrosion warranty compliance.
- Vehicle Assemblers:Contract manufacturers and regional kit assemblers procure structural sheet through Tier-1 intermediaries without direct mill relationships.
OEMs command specification authority. Tier-1 Suppliers represent the most active capacity expansion channel.
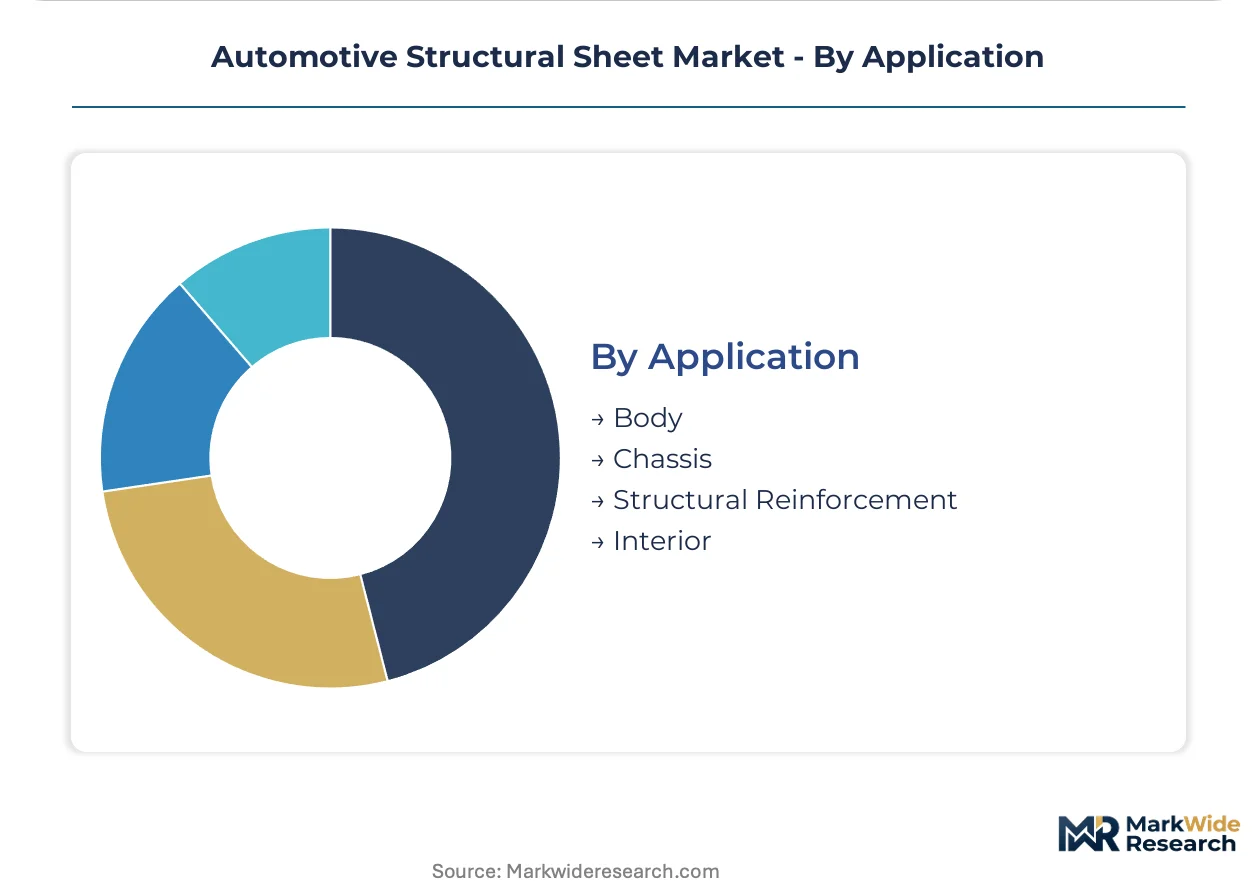
Application:
Application segmentation tracks load path criticality, with body and chassis structures subject to crash test protocol validation while interior applications face lower regulatory qualification barriers.
- Body:Body-in-white assemblies including hoods, doors, roofs, and fenders require grade optimization across dent resistance, formability, and weldability metrics. Euro NCAP pedestrian protection protocols now govern hood outer panel substrate selection against moving legform impactors.
- Chassis:Frame rails, crossmembers, and suspension mounting points demand ultra-high-strength grades above 980 MPa for intrusion resistance during offset collision events. Battery enclosure floors in electric vehicles integrate chassis structural functions with thermal runaway protection requirements.
- Structural Reinforcement:B-pillar inserts, roof bow reinforcements, and rocker panel inners utilize press-hardened boron steel in 1,500 MPa grades to miniaturize section thickness while maintaining occupant safety cell integrity.
- Interior:Seat frames, instrument panel carriers, and cargo area panels employ lower-strength grades with priority on formability and surface finish quality for visible applications.
Body applications command the established base. The steepest expansion trajectory runs through chassis as electric vehicle platform volumes scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated steel mills in Germany, Japan, and the United States supply the majority of advanced high-strength coil stock. Chinese aluminum smelters and South Korean automotive service centers round out critical supply nodes. Regulatory pressure from EU, Chinese, and American agencies drives grade substitution toward lighter substrates.
Germany
Volkswagen and BMW specifications for press-hardened boron steel dominate procurement volumes. The F-Gas Regulation restricts fluorinated greenhouse gas use in aluminum tempering operations, forcing heat treatment process redesigns. The Ruhr Valley steel corridor ships proprietary dual-phase formulations directly to OEM body-in-white plants.
China
MIIT lightweighting coefficients mandate structural sheet upgrades across domestic EV production lines. GB standards enforce specific material performance thresholds for new energy vehicle platforms. Yangtze River Delta service centers blank and laser-cut coil for BYD and NIO battery enclosure programs.
United States
EPA tailpipe standards push Detroit Three OEMs toward aluminum-intensive body architectures. NHTSA crash test protocols govern grade selection for offset collision resistance. Michigan-based Tier-1 stampers operate tandem press lines serving Ford and General Motors assembly plants.
Japan
METI carbon-neutral steel certification creates premium positioning for hydrogen-reduced iron production. Toyota platform engineering teams specify ultra-high-strength grades above 980 MPa for thermal runaway protection. Kanto region mills supply proprietary formulations to domestic OEM safety cell programs.
South Korea
Hyundai and Kia electric vehicle platforms compress design cycles for multi-material sheet solutions. Korean automotive service centers deploy roll forming for side member programs requiring mass reduction. Busan-Ulsan industrial complexes coordinate coil logistics for export-bound vehicle production.
Automotive Structural Sheet Market Vendor Landscape
Concentration sits with integrated steel producers possessing proprietary metallurgy pipelines and captive R&D facilities. The vendor base splits between commodity-grade suppliers and specialists in ultra-high-strength formulations above 1,500 MPa. Three archetypes dominate: integrated mills with blast furnace assets, automotive service centers with blanking and laser-cutting capabilities, and aluminum smelters with rolling mill integration. Competitive moves center on capacity expansion near OEM assembly clusters and strategic partnerships for tailored blank laser welding technology.
Within the integrated mill tier, ArcelorMittal and POSCO exemplify scale-driven metallurgy leadership. Nippon Steel Corporation anchors the ultra-high-strength specialist position. These three entities represent distinct geographic supply anchors—European, Asia-Pacific, and Japanese—each serving regional OEM platform engineering teams with proprietary grade formulations.
| Leading Market Players |
|---|
| ArcelorMittal |
| POSCO |
| Nippon Steel Corporation |
| Thyssenkrupp AG |
| Magna International |
| Gestamp Automoción |
| United States Steel Corporation |
| Hyundai Steel |
| Nucor Corporation |
| Others |
Supply Flow & Price Mechanics
Million-unit stamping throughput at integrated mills in Germany and Japan anchors cost floors across structural sheet tiers, concentrating pricing power with blast furnace operators while compressing margins for regional re-rollers lacking captive iron ore access. Scale economies in coil production propagate through long-term offtake contracts that lock OEMs into grade-specific pricing bands, with spot market volatility reserved for secondary distribution channels serving aftermarket collision repair networks.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure for aluminum-intensive structural solutions, separating premium heat-treated alloys compliant with fluorinated greenhouse gas restrictions from standard grades facing process redesign costs. Pricing stratifies across premium, standard, and economy tiers based on tensile strength certification above 980 MPa and geographic delivery proximity to Ruhr Valley or Great Lakes steel corridors. Cost compression in standard-grade mild steel is intensifying because legacy supply contracts block rapid transitions to third-generation AHSS formulations. Tier-1 stampers exhibit highest price sensitivity due to capital-intensive press retrofit requirements, while OEM platform engineering teams prioritize crash performance over unit cost in battery enclosure specifications.
Supply Chain Analysis
Germany, Japan, and South Korea anchor advanced high-strength coil production, with Chinese aluminum smelters and Canadian rolling mills feeding import-dependent European and North American channels. Raw material flows draw from Australian iron ore, Chilean copper for electrical conductivity alloys, and Middle Eastern primary aluminum. Single-source vulnerability concentrates in 1,500 MPa press-hardened boron steel formulations where proprietary metallurgy pipelines limit qualified supplier counts. Distribution runs through automotive service centers with blanking and laser-cutting capabilities positioned within 150 kilometers of OEM assembly plants for just-in-time sequenced delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized technician training for multi-material joining operations represents the critical capability gap constraining electric vehicle platform scaling, with self-piercing rivet and flow-drill screw expertise scarce across vocational programs in Germany, Michigan, and South Korea.
For Market Incumbents: Compound proprietary AHSS formulation advantages by expanding tailored blank laser welding partnerships with Tier-1 stampers, while accelerating hydrogen-reduced iron certification to defend against low-emission steel imports threatening premium positioning in luxury EV programs. Capacity additions in India's automotive manufacturing corridor under PLI scheme incentives will secure allocation priority during coil shortages. For New Entrants and Emerging Players: Aftermarket collision repair certification gaps present white-space opportunities where independent distributors lack traceability documentation for OEM corrosion warranty compliance. Target chassis battery enclosure applications requiring ultra-high-strength grades above 980 MPa, where incumbent mill qualification timelines create 18-24 month supply windows. Establish direct relationships with platform engineering teams at mobility-service fleet operators bypassing traditional OEM purchasing departments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automotive service centers with captive blanking and laser-cutting capabilities tied to long-term OEM logistics contracts. Five-to-ten year viability favors specialists in 1,500 MPa press-hardened boron steel with integrated R&D pipelines over commodity-grade re-rollers. Monitor Euro NCAP pedestrian protection protocol adoption rates as inflection indicators for hood outer panel substrate specification shifts favoring multi-material architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Tailored Blank Laser Welding Partnership | Enables part consolidation in B-pillar assemblies, reducing stamping press counts at Magna and Gestamp facilities. |
| Hydrogen-Reduced Iron Certification | METI carbon-neutral steel standards create premium positioning for low-emission structural sheet in Toyota and BMW programs. |
| India PLI Scheme Manufacturing Expansion | Domestic OEM capacity builds localize coil logistics for BYD and Tata Motors battery enclosure supply chains. |
| Multi-Material Joining Technician Training | Self-piercing rivet expertise scarcity constrains Hyundai and Kia electric vehicle platform assembly ramp rates. |
| Aftermarket Certification Documentation | Traceability gaps in collision repair networks block independent distributors from OEM corrosion warranty compliance. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across OEM platform engineering teams, Tier-1 stamper procurement directors, aftermarket distributor operations managers, and integrated mill metallurgy R&D leads. Secondary validation incorporated vehicle production databases, IHS Markit registration data, SEC filings from listed steel producers, and customs records tracking aluminum coil flows from Canadian smelters. Bottom-up volume builds triangulated against top-down market sizing from regulatory mandate analysis across EU Green Deal, MIIT lightweighting coefficients, and EPA tailpipe standards.
Across the analysis window, projections segment by material type, production process, end-user category, and application criticality, with vehicle class and propulsion architecture as cross-cutting dimensions. CAGRs derive from regression against historical grade substitution patterns and OEM platform launch timelines. Forecast inputs include battery electric vehicle production ramp assumptions, crash test protocol evolution from NHTSA and Euro NCAP, and integrated mill capacity utilization rates in the Ruhr Valley and Great Lakes corridors.
Forecasts assume regulatory continuity in EU F-Gas Regulation, MIIT GB standards, and EPA tailpipe regimes; material policy shifts in fluorinated greenhouse gas restrictions or lightweighting coefficient enforcement would require re-modeling. Supply disruption risks from aluminum smelting energy cost volatility and AHSS stamping die wear rate uncertainties could compress grade transition timelines. Recalibration cycles align with material shifts in electric vehicle platform architectures and pedestrian protection protocol updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
Automotive Side Impact Assembly Market
Automotive Assemblies
Automotive Ball Joints Market
Automotive Assemblies
Automotive Rocker Arm Market
Automotive Assemblies
China Automotive Heat Exchanger Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Throttle Body Assembly Market
Automotive Assemblies
Automotive Constant Velocity Joint Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Automotive Casting Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
Automotive Tie Rod Assembly Market
Automotive Assemblies
Automotive Idler Arm Market
Automotive Assemblies
Automotive Roof Bar and Roof Racks Market
Automotive Assemblies
Rocker Arm Assembly Market
Automotive Assemblies
Automotive Strut Bar Market