
 Europe and North Africa Automotive Window Regulator Market | 2026-2036
Europe and North Africa Automotive Window Regulator Market Size, Share, and Industry Trends Forecast 2026-2036
Europe and North Africa Automotive Window Regulator Market Insights
OEM procurement consolidation around modular door systems is repositioning tier-one suppliers toward integrated regulator-motor-switch packages. Brose Fahrzeugteile SE & Co. KG leverages its captive motor production to control cost structures across European assembly lines. Robert Bosch GmbH anchors its position through software-integrated anti-pinch algorithms that extend into premium vehicle programs. Magna International Inc. competes on manufacturing scale, operating dedicated regulator plants in Slovakia and Morocco to serve regional OEM footprints.
Automotive window regulators are electromechanical or manual mechanisms that translate rotational motor output into vertical glass movement through cable, scissor, or rack-and-pinion architectures, typically achieving stroke lengths of 200–400 mm and load capacities exceeding 80 N for laminated side glass. The primary commercial purpose centers on occupant comfort, ventilation control, and regulatory compliance with emergency egress standards. Electric regulator assemblies lead value generation across the product type dimension, while the motor sub-component captures disproportionate margin pools due to precision winding requirements and thermal durability specifications. OEM delivery mode dominates volume throughput, though aftermarket providers are gaining share as vehicle parc ages across Southern Europe and North African fleet segments.
EMA device safety directives and REACH substance restrictions shape material selection and recyclability mandates for European-sourced regulators, while Morocco's national automotive regulator enforces alignment with UNECE type-approval standards for exported components. The EU F-Gas Regulation indirectly pressures motor sealing designs to prevent refrigerant pathway interference in integrated climate-door modules. Stakeholders must monitor how pending EU battery passport requirements and extended producer responsibility frameworks will cascade into motor-recovery obligations across the value chain.
Market Dynamics
OEM procurement consolidation around modular door systems is forcing tier-one suppliers to absorb motor-switch integration costs while Morocco's Tangier Automotive City attracts cable-driven regulator investments from European assemblers seeking tariff-advantaged export platforms.
Growth Catalysts
- REACH polymer compliance:ECHA substance restrictions on phthalate plasticizers are accelerating substitution toward bio-based cable sheathing compounds that reduce regulatory friction for German OEM exports.
- Tangier Automotive City concentration:Morocco's free trade agreements with the European Union are positioning the port zone as a preferred assembly location for cable-driven regulators serving Renault-Nissan and Stellantis programs.
- Anti-pinch algorithm mandates:UNECE R21 type-approval requirements for power window force limitation are embedding software-integrated motor controllers as standard fitment across premium electric vehicle platforms.
Market Restraints
- Copper winding cost volatility:Motor stator production depends on LME copper price swings that compress margin pools for European suppliers lacking backward integration into magnet wire drawing.
- Baden-Württemberg supplier corridor concentration:Three-quarters of precision gear machining capacity sits within 150 kilometers of Stuttgart, creating geographic vulnerability to single-point logistics disruptions.
- Scissor mechanism displacement:Cable-driven architectures are capturing share in lightweight door modules, stranding capital equipment investments at scissor-specialist toolrooms.
Strategic Opportunities
- Algerian aftermarket penetration:Vehicle parc aging across Oran and Algiers is expanding demand for replacement regulator kits as OEM dealer networks remain sparse outside coastal zones.
- EU battery passport alignment:Pending motor-recovery obligations under extended producer responsibility frameworks are creating first-mover advantage for suppliers with disassembly-ready designs.
- Climate-door module convergence:Integration of window sealing with HVAC refrigerant pathways is automating demand for motor housings compatible with F-Gas Regulation sealing specifications.
Industry Challenges
- Precision winding skill scarcity:Motor stator production requires technicians capable of maintaining 0.05 mm tolerance on multi-strand coil insertion, a competency concentrated at aging workforce pools in Stuttgart and Bratislava.
- UNECE type-approval timeline compression:Anti-pinch validation protocols now demand 200,000-cycle durability testing that extends product development schedules by eight to twelve months.
- Legacy scissor inventory stranding:Tooling amortization schedules at established suppliers conflict with cable-driven procurement preferences from electric vehicle program directors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe and North Africa Automotive Window Regulator Market |
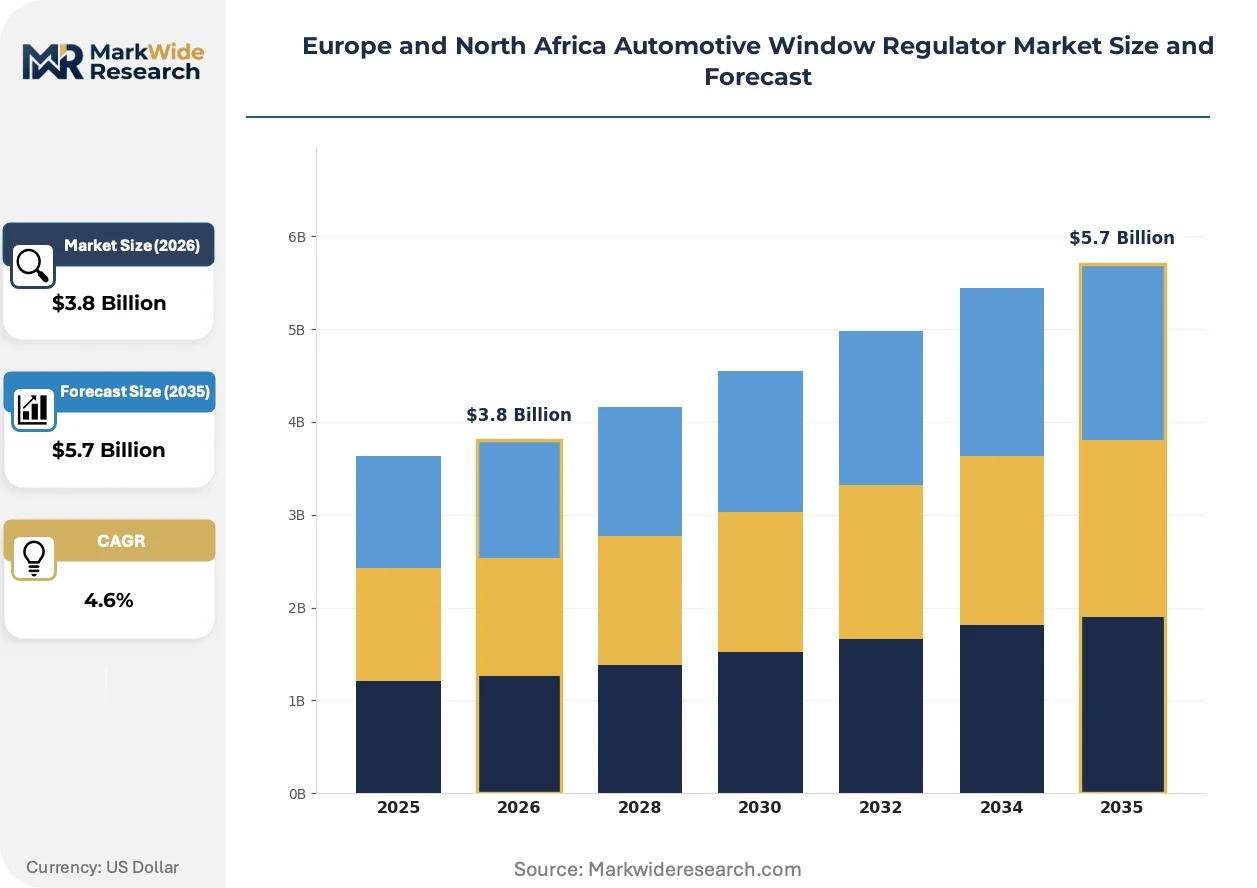
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Manual, Power, Hybrid Delivery Mode: Direct Sales, Distributors, Online Retail, OEMs End User: Manufacturers, Aftermarket Providers, Vehicle Assemblers, Repair Shops Component: Regulator Assembly, Switch, Cable, Motor |
| Companies Covered | Brose Fahrzeugteile SE & Co. KG, Robert Bosch GmbH, Magna International Inc., Continental AG, Valeo SA, Grupo Antolin SA, Elta Automotive Ltd, Küster Holding GmbH, Inteva Products, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe and North Africa Automotive Window Regulator Market Trends and Innovations
Lightweighting imperatives and software-defined vehicle architectures are converging to reshape electromechanical component specifications across European and North African assembly lines.
Carbon-fiber-reinforced polyamide cable pulleys are automating mass reduction in premium door modules. BMW and Mercedes-Benz electric vehicle programs have specified these composite guides for 2026 platform launches. The substitution is compressing metal stamping volumes at traditional scissor mechanism suppliers while expanding polymer compounding demand at specialized compounders near Lyon.
EU F-Gas Regulation motor sealing standards are mandating barrier-layer compatibility for integrated climate-door modules. Suppliers must now validate that motor housings prevent refrigerant permeation across 15-year service life projections. German OEM technical service bulletins are rejecting legacy gasket materials that fail accelerated aging protocols, forcing compound reformulation at seal manufacturers.
Direct-to-fleet aftermarket channels are disrupting traditional parts distribution across Southern Europe. Leasing companies operating aged vehicle pools in Spain and Portugal are negotiating bulk regulator procurement contracts that bypass national distributor markups. The disintermediation is most visible in Lisbon and Barcelona, where fleet maintenance depots now source cable repair kits through specialized B2B platforms.
Europe and North Africa Automotive Window Regulator Market Segmentation
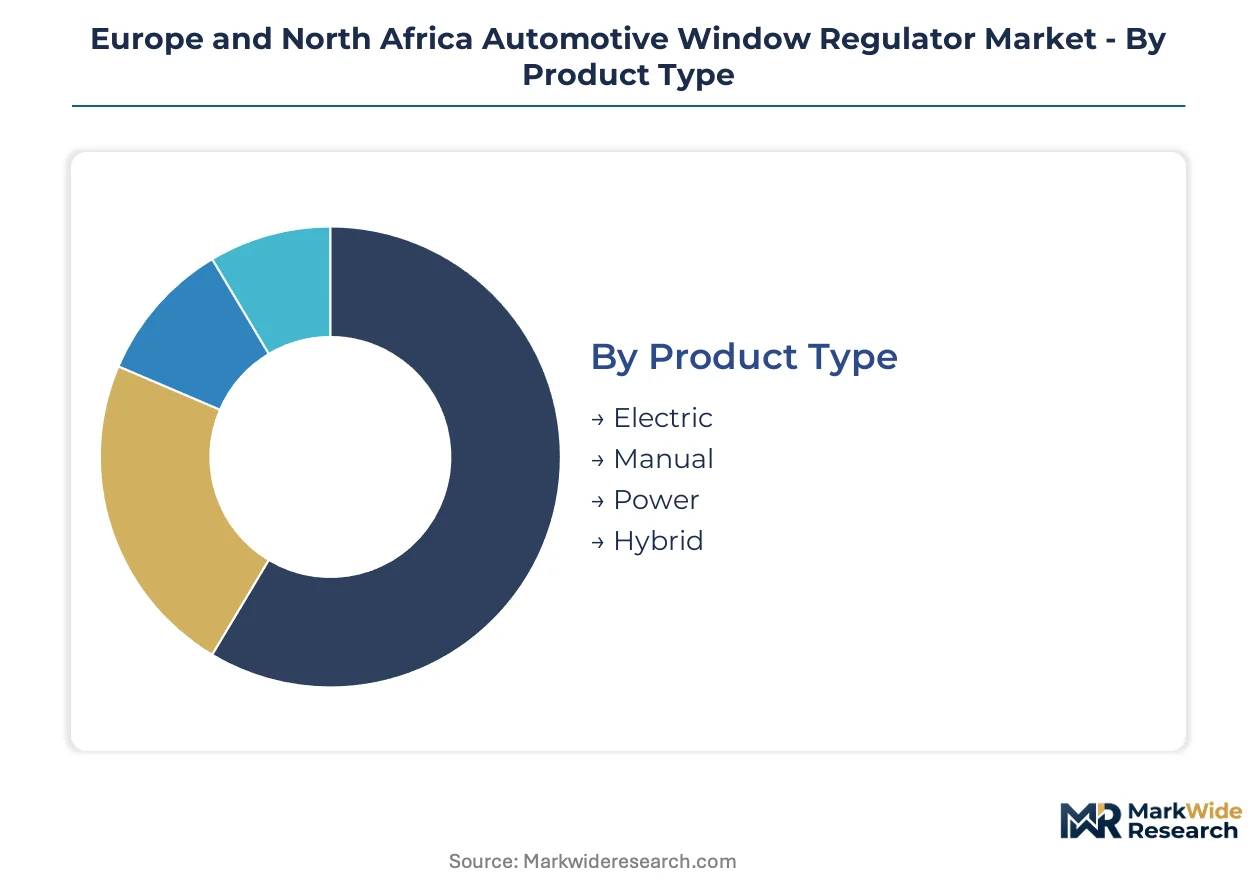
Window regulator procurement in Europe and North Africa fragments across electromechanical architectures, supply chain configurations, and regulatory compliance tiers. Each segment carries distinct certification burdens from UNECE type-approval and REACH substance restrictions that shape supplier qualification pathways.
Product Type:
Electric regulators carry mandatory UNECE R21 force-limitation certification, while manual variants face lighter documentation loads but stricter durability testing under ECE R21 annexes.
- Electric:Cable-driven architectures dominate premium electric vehicle programs across Baden-Württemberg and Tangier Automotive City. Demand concentrates at BMW and Mercedes-Benz assembly lines where anti-pinch algorithms require software-integrated motor controllers validated to 200,000-cycle durability protocols.
- Manual:Scissor mechanisms persist in entry-level fleet vehicles across Algeria's coastal assembly zones where cost minimization overrides comfort specifications. Renault-Nissan procurement in Morocco retains manual fitments for specific commercial vehicle configurations.
- Power:Encompasses enhanced electric variants with express-up functionality requiring additional pinch-detection circuitry. Moroccan exports to Southern European markets favor this specification for mid-tier passenger programs.
- Hybrid:Dual-mode systems enabling manual override during electrical failure. Limited deployment in specialized commercial and emergency vehicle applications across German federal procurement.
Electric sits at the top of the volume ranking, with Power climbing the fastest as mid-tier OEMs upgrade feature content.
Delivery Mode:
Channel selection determines margin capture and inventory risk exposure, with OEM direct contracts absorbing design-in costs while aftermarket channels face price transparency pressure.
- Direct Sales:Tier-one suppliers negotiate multi-year frame contracts with Stellantis and Renault-Nissan procurement centers. These agreements specify cable tensile strength, motor thermal class, and switch cycle life with penalty clauses for specification deviation.
- Distributors:National parts networks across Spain and Portugal hold safety stock for independent repair channels. Lisbon and Barcelona distribution hubs face margin compression from fleet direct-sourcing disintermediation.
- Online Retail:B2B platforms serving leasing company maintenance depots in Southern Europe. Growth constrained by fitment verification complexity and return logistics costs.
- OEMs:Captive supply arrangements where vehicle assemblers internalize regulator production. Limited to vertically integrated groups with door module manufacturing capability.
OEMs command the largest revenue pool, though Online Retail is gaining share fastest among fleet-age segments.
End User:
Customer type dictates specification stringency, with vehicle assemblers imposing full UNECE validation while repair channels accept equivalent aftermarket certifications.
- Manufacturers:Component suppliers producing sub-assemblies for tier-one system integrators. These entities must maintain ISO/TS 16949 quality system registration and ECHA REACH substance documentation for polymer content.
- Aftermarket Providers:Independent brands sourcing cable repair kits and motor replacements for aged vehicle parc. Oran and Algiers represent expansion targets where OEM dealer networks remain sparse.
- Vehicle Assemblers:Final manufacturers specifying integrated door modules. Baden-Württemberg corridor concentration creates geographic dependency for precision gear machining capacity.
- Repair Shops:Service bay installation of replacement regulators. Southern European independents favor cable-driven repair kits over complete scissor assembly swaps due to labor time differentials.
Vehicle Assemblers absorb the highest unit volumes, with Aftermarket Providers expanding most quickly in North African coastal zones.
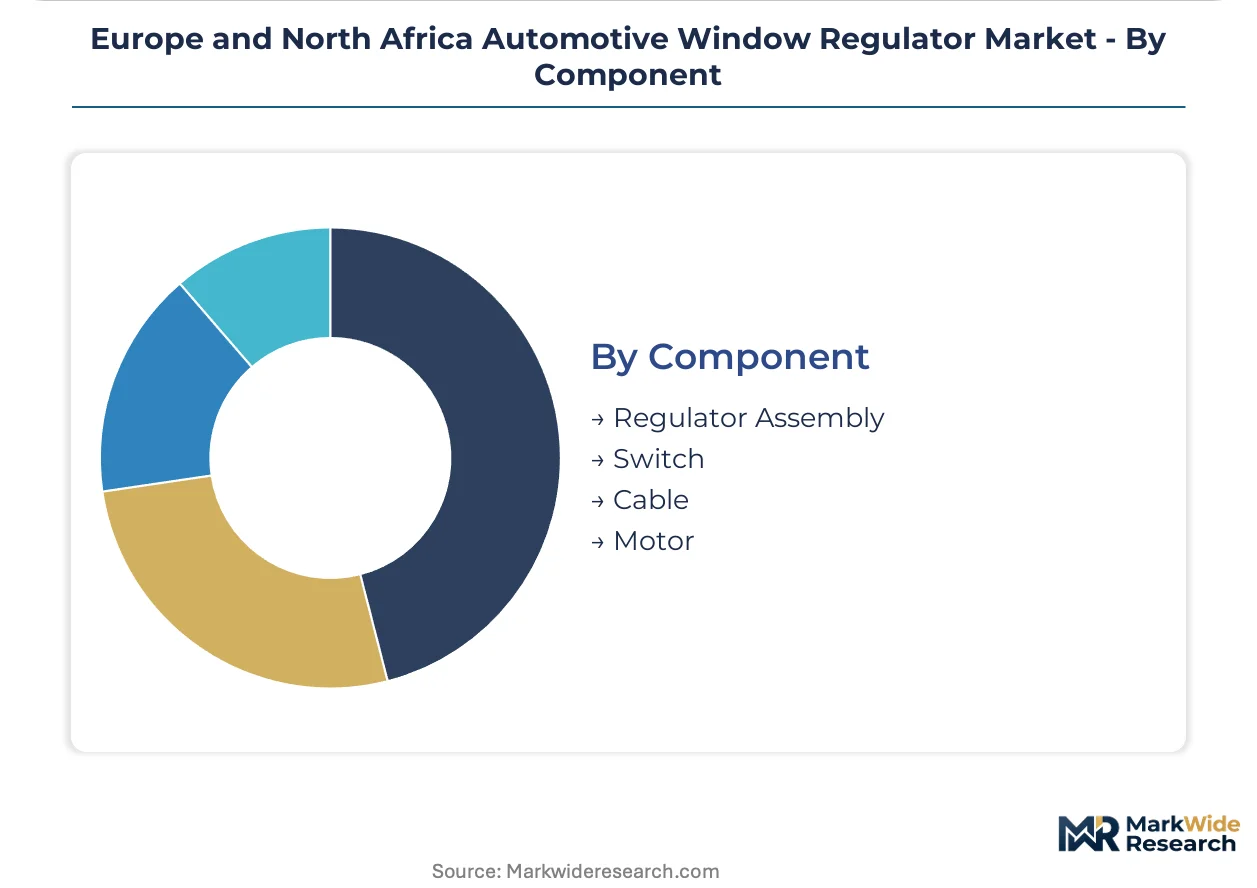
Component:
Sub-component sourcing strategies vary by technical complexity, with motor production requiring precision winding capability while cable assemblies tolerate broader supplier bases.
- Regulator Assembly:Complete electromechanical unit integrating guide rails, pulleys, and attachment hardware. Carbon-fiber-reinforced polyamide pulleys specified for BMW and Mercedes-Benz electric vehicle platforms reduce mass versus metal stampings.
- Switch:Control interface with anti-pinch signal processing. Embedded software development concentrated at Brose and Bosch controller engineering centers.
- Cable:Multi-strand steel or synthetic load-bearing element. Bio-based sheathing compounds substitute phthalate plasticizers under ECHA substance restrictions.
- Motor:Brushed or brushless DC drive unit with thermal durability specifications. Copper winding cost volatility compresses margins for suppliers lacking backward integration into magnet wire drawing.
Motor captures the steepest margin pool, with Cable assembly volumes expanding fastest from lightweighting procurement shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Baden-Württemberg corridor concentrates precision gear machining capacity while Morocco's Tangier Automotive City attracts cable-driven regulator investments through tariff-advantaged export platforms.
Germany
Baden-Württemberg hosts three-quarters of European precision gear machining within 150 kilometers of Stuttgart. REACH compliance on polymer content and motor efficiency standards reshape supplier qualification criteria for BMW and Mercedes-Benz electric vehicle programs. Brose Fahrzeugteile SE & Co. KG leverages captive motor production to control cost structures across regional assembly lines.
Morocco
Tangier Automotive City expands procurement of lightweight cable-driven regulators for Renault-Nissan and Stellantis programs. Free trade agreements with the European Union position the port zone as a preferred assembly location for export-bound components. The national automotive regulator enforces alignment with UNECE type-approval standards for all exported regulators.
France
Auvergne-Rhône-Alpes region near Lyon specializes in carbon-fiber-reinforced polyamide compounding for premium door module pulleys. ECHA substance restrictions on phthalate plasticizers accelerate substitution toward bio-based cable sheathing compounds. Valeo SA anchors its position through climate-door module integration compatible with EU F-Gas Regulation sealing specifications.
Spain
Catalonia and Madrid distribution hubs face margin compression from fleet direct-sourcing disintermediation. Leasing companies operating aged vehicle pools negotiate bulk regulator procurement contracts that bypass national distributor markups. Independent repair channels across Barcelona favor cable-driven repair kits over complete scissor assembly swaps.
Algeria
Vehicle parc aging across Oran and Algiers expands demand for replacement regulator kits. OEM dealer networks remain sparse outside coastal zones, creating aftermarket penetration opportunities. Repair shops source components through specialized B2B platforms serving fleet maintenance depots.
Europe and North Africa Automotive Window Regulator Market Competitive Landscape
German producers anchor one tier; North American and French specialists hold complementary positions in integrated door systems and climate-control modules. The supplier base concentrates around tier-one system integrators with captive motor production or software-integrated controller capabilities. Three strategic archetypes dominate: vertically integrated electromechanical specialists, scale-driven modular door system suppliers, and precision polymer compounders. Competitive moves center on M&A for motor-switch integration capacity and geographic expansion into tariff-advantaged export platforms.
Within the integrated electromechanical tier, Brose Fahrzeugteile SE & Co. KG exemplifies the vertically integrated archetype through its captive motor production base. Robert Bosch GmbH represents the software-integrated controller segment, occupying a position defined by anti-pinch algorithm development. Magna International Inc. anchors the scale-driven manufacturing archetype with dedicated production facilities serving regional OEM footprints.
| Leading Market Players |
|---|
| Brose Fahrzeugteile SE & Co. KG |
| Robert Bosch GmbH |
| Magna International Inc. |
| Continental AG |
| Valeo SA |
| Grupo Antolin SA |
| Elta Automotive Ltd |
| Küster Holding GmbH |
| Inteva Products |
| Others |
Pricing and Supply Chain Analysis
OEM procurement consolidation around modular door systems is compressing supplier margins while forcing tier-one integrators to absorb motor-switch design costs. This demand-side pressure concentrates pricing power at vehicle assemblers with multi-year frame contracts, leaving component specialists exposed to copper winding cost volatility and REACH compliance investments.
Pricing Analysis
Capacity additions in Morocco's Tangier Automotive City are reshaping price floors for cable-driven regulators serving European export markets. Three-tier pricing structure across premium, standard, and economy levels separates BMW-Mercedes electric vehicle specifications from mid-tier Stellantis programs and entry-level fleet configurations. Cost compression in motor production is intensifying because LME copper price swings hit suppliers lacking captive magnet wire drawing. Aftermarket providers in Southern Europe exhibit highest price sensitivity, while German OEMs prioritize anti-pinch algorithm certification over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Renault-Nissan and Stellantis procurement centers, while distributor networks across Spain and Portugal serve fragmented repair channels. Supply concentrates in Germany, Morocco, and Slovakia, with precision gear machining anchored in Baden-Württemberg and cable assembly scaling in Tangier. Raw material dependencies center on copper magnet wire, carbon-fiber-reinforced polyamide compounds, and bio-based cable sheathing substituting phthalate plasticizers. Single-source vulnerability in Stuttgart-area gear machining creates geographic risk. Distribution runs through tier-one system integrators with captive motor production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where ECHA REACH substance restrictions and UNECE R21 anti-pinch mandates continuously reset supplier qualification thresholds. The EU F-Gas Regulation's motor sealing specifications exemplify how compliance investments cascade into pricing power for prepared incumbents.
For Market Incumbents: Anticipate displacement risk from cable-driven architectures by securing carbon-fiber-reinforced polyamide pulley supply agreements near Lyon compounding clusters. Defensive consolidation should prioritize backward integration into magnet wire drawing to buffer LME copper volatility, while embedding disassembly-ready motor designs to capture EU battery passport alignment premiums.
For New Entrants and Emerging Players: Enter via Algerian aftermarket channels where vehicle parc aging across Oran and Algiers outpaces OEM dealer network coverage. The most penetrable segment lies in cable repair kits for fleet maintenance depots sourcing through B2B platforms. A specialized logistics partnership with Lisbon-Barcelona distribution hubs provides go-to-market velocity.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision polymer compounders supplying climate-door module sealing compatible with F-Gas Regulation specifications. Long-term viability favors suppliers with software-integrated controller capabilities validated to 200,000-cycle durability protocols. Watch for anti-pinch algorithm patent filings as inflection indicators of competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Motor-Switch Integration Investment | Brose and Bosch engineering centers dominate embedded software development for UNECE R21 compliance. |
| Tangier Manufacturing Footprint | Tariff-advantaged export platforms serve Renault-Nissan and Stellantis programs under EU free trade agreements. |
| Backward Integration into Magnet Wire | Captive copper winding production buffers margin compression from LME price volatility. |
| Climate-Door Module Convergence | Valeo's F-Gas Regulation sealing specifications anchor positioning in integrated HVAC-window systems. |
| Aftermarket B2B Platform Development | Fleet direct-sourcing disintermediation bypasses traditional Spanish-Portuguese distributor markups. |
Research Methodology
Direct dialogue with tier-one supplier procurement officers, OEM platform engineers, aftermarket distributors, and motor controller engineering directors grounded qualitative assessments. Secondary validation drew from UNECE type-approval documentation, ECHA REACH substance registrations, vehicle production databases, and IHS Markit registration data. Bottom-up segment sizing triangulated against top-down market value estimates across the analysis window.
Segmentation outputs reflect modeling across product architecture, delivery mode, end-user category, and component sub-system dimensions throughout the forecast period. CAGRs derived from regression analysis of historical procurement volumes, OEM platform launch schedules, and regulatory compliance timeline impacts. Industry-specific inputs included copper price correlation models and REACH substitution cost curves for bio-based cable sheathing compounds.
Inputs from tier-one supplier interviews and regulatory filing databases were available through the study window; gaps in Algerian aftermarket transaction data introduce uncertainty bands for North African volume estimates. Forecasts reflect documented assumptions around OEM platform electrification rates and polymer substitution timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Selector Lever Market
Automotive Components
Europe Automotive Relay Market
Automotive Components
Automotive Polymer Composites Market
Automotive Components
Automotive Transaxle Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
Automotive Catalyst Market
Automotive Components
Automotive Carbon Fiber Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
Automotive Exhaust Emission Control Device Market
Automotive Components
Global Automotive Sun Visor Market
Automotive Components
Automotive Glass Fiber Composites Market
Automotive Components
Automotive Exhaust Manifolds Market
Automotive Components
Automotive Silencer Market
Automotive Components
Australia Automotive Glass Fiber Composites Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Automotive Axle Market