
 South Korea Automotive Pneumatic Actuators Market | 2026-2036
South Korea Automotive Pneumatic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Automotive Pneumatic Actuators Market Analytics
South Korean actuator producers is recalibrating capacity to match Hyundai Motor Group's electrification roadmap. Continental AG leverages its Busan technical center to anchor pneumatic module development for domestic OEMs. Denso Corporation sustains precision manufacturing partnerships with Kia's Hwaseong plant. Robert Bosch GmbH competes through localized valve assembly operations serving brake system integrators in Ulsan.
Automotive pneumatic actuators are fluid-power devices converting compressed air into linear or rotary mechanical motion, typically operating at pressures between 0.4 and 1.0 MPa to control engine intake valves, brake calipers, and exhaust gas recirculation flaps. Double-acting cylinders dominate engine control applications where bidirectional force delivery ensures precise throttle positioning under variable load conditions. OEM procurement channels capture the majority of value as vehicle assemblers specify actuator performance tiers during platform development, while aftermarket providers occupy a narrower margin pool concentrated in brake system rebuilds and exhaust component replacements.
MFDS quality enforcement and Korea's K-Auto safety standards compel actuator suppliers to validate fatigue resistance across temperature cycles spanning minus 40 to 150 degrees Celsius. METI-aligned technical cooperation agreements with Japanese component makers further tighten interoperability requirements for pneumatic control modules. Stakeholders must monitor Seoul's evolving carbon-neutral vehicle regulations, which will determine whether hybrid pneumatic-electric actuators gain procurement preference over pure pneumatic designs in next-generation platforms.
Market Dynamics
Hyundai Motor Group's electrified platform rollout is compressing actuator procurement cycles as Gyeonggi Province assembly lines demand higher-precision pneumatic modules validated against MFDS fatigue benchmarks.
Growth Catalysts
- Electrified platform proliferation:Hybrid and battery-electric vehicle architectures from domestic OEMs expand actuator integration points across thermal management and brake-by-wire systems.
- K-Auto safety certification:Mandatory fatigue-resistance validation across minus 40 to 150 degrees Celsius temperature cycles compels tier-one suppliers to upgrade precision manufacturing capabilities.
- Seoul-Incheon corridor concentration:Proximity of tier-one suppliers to final assembly operations reduces logistics friction and accelerates just-in-sequence delivery windows.
Market Restraints
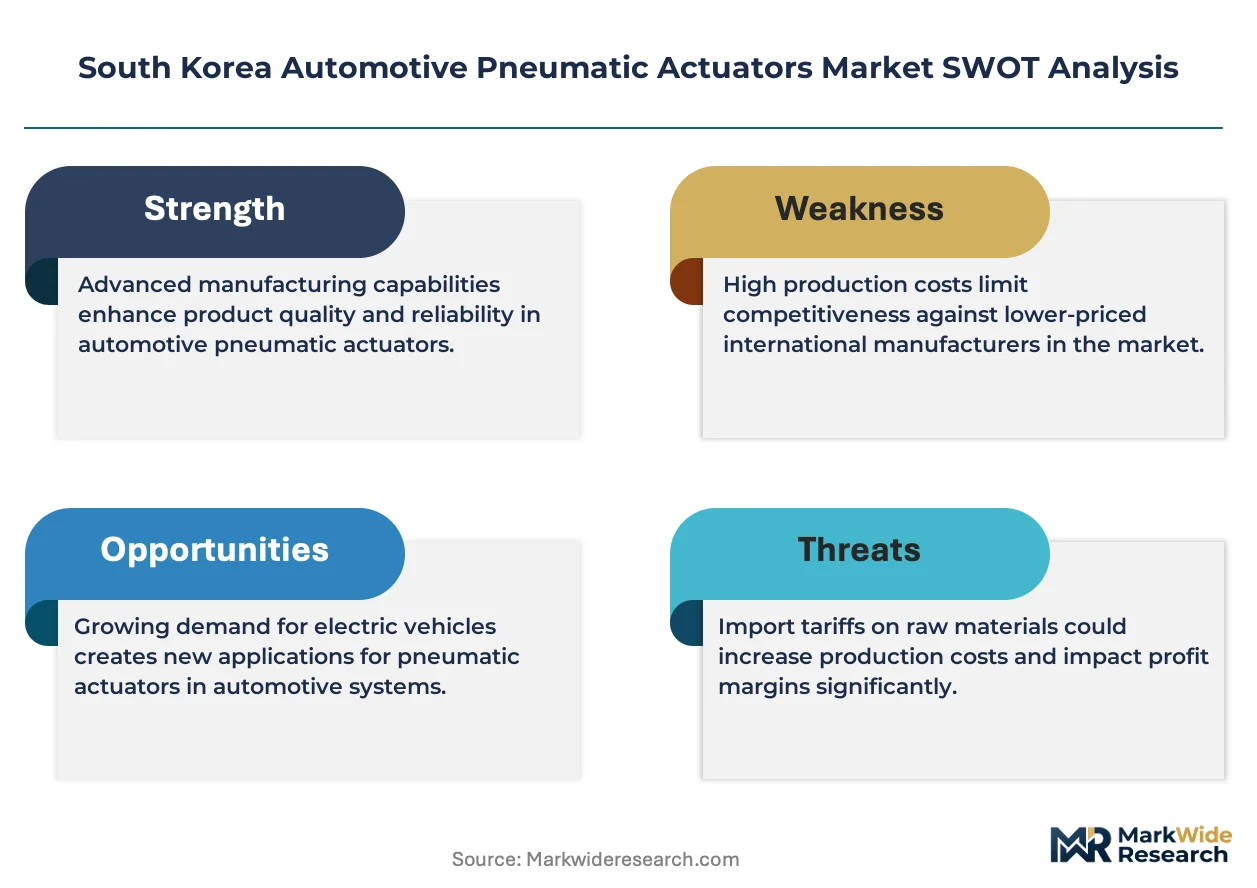
- Raw material volatility:Aluminum alloy and specialty elastomer input costs fluctuate with energy price swings, compressing margin buffers for pneumatic cylinder producers.
- Supplier concentration risk:Domestic valve assembly operations cluster in Ulsan and Busan, creating geographic vulnerability to regional supply disruptions.
- Electromechanical substitution:Pure electric actuators gain traction in next-generation brake caliper applications, threatening pneumatic share in high-force positioning segments.
Strategic Opportunities
- Carbon-neutral vehicle regulations:Seoul's evolving emissions mandates create procurement preference windows for hybrid pneumatic-electric designs over conventional pure pneumatic modules.
- Hwaseong plant partnerships:Precision manufacturing collaborations with Kia's domestic operations open captive supply arrangements for next-generation throttle control systems.
- METI technical cooperation:Aligned interoperability standards with Japanese component makers enable cross-border module standardization and scale economies.
Industry Challenges
- MFDS compliance timelines:Extended validation protocols for temperature-cycle fatigue resistance delay new product qualification and compress development windows.
- Legacy system integration:Electrified platforms require pneumatic actuators to interface with electronic control units, demanding firmware competency that traditional fluid-power suppliers must acquire.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Automotive Pneumatic Actuators Market |
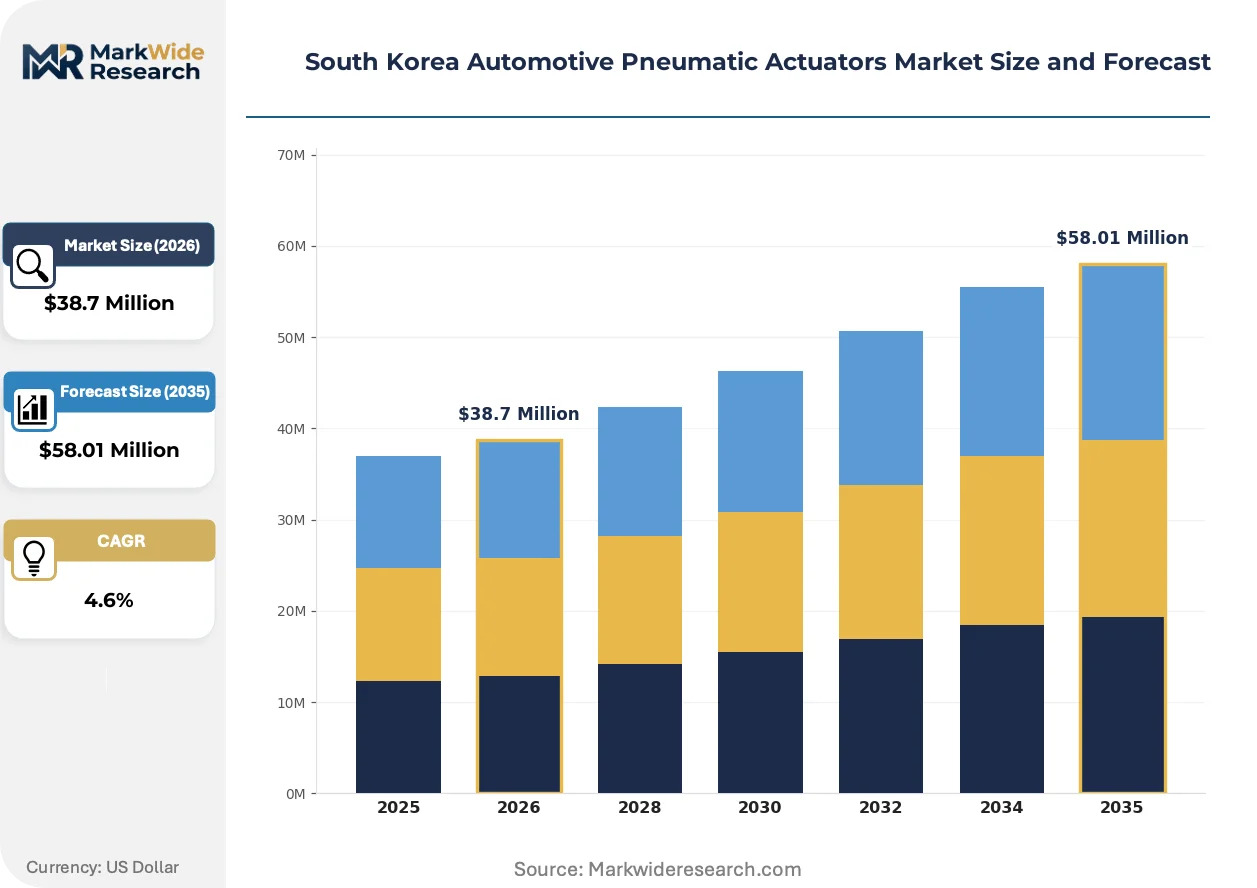
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $58.01 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Acting, Double-Acting, Rod-Type, Rotary End User: OEMs, Aftermarket Providers, Suppliers, Assemblers Technology: Pneumatic Control, Electric Control, Hybrid Control, Solenoid Control Application: Engine Control, Brake Systems, Exhaust Systems, Suspension Systems |
| Companies Covered | Continental AG, Nidec Corporation, Denso Corporation, ASCO Valve Inc, SMC Corporation of America, Robert Bosch GmbH, Bosch Rexroth AG, CTS Corporation, Hitachi Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Automotive Pneumatic Actuators Market Evolving Landscape
Pneumatic module development is pivoting toward hybrid architectures as electrification pressures force fluid-power suppliers to embed electronic sensing and control capabilities alongside mechanical actuation.
Smart pneumatic actuators incorporating position feedback sensors and IoT-enabled condition monitoring are converging with brake-by-wire and thermal management systems in Hyundai's electrified platforms. Tier-one integrators in Gyeonggi Province are adopting these modules at compressed development cycles to meet platform launch timelines. This convergence is collapsing the traditional separation between fluid-power and electronic control supply chains, forcing pneumatic specialists to acquire firmware development capabilities or cede positioning to electromechanical competitors.
MFDS enforcement of fatigue-resistance validation across extended temperature ranges is tightening quality benchmarks for pneumatic components serving safety-critical applications. Domestic suppliers must demonstrate cycle durability under thermal stress conditions that exceed prior industry norms. Brake system integrators in Ulsan and engine control module producers in Seoul-Incheon corridors are responding by consolidating procurement around suppliers with certified in-house testing laboratories.
Buyer concentration among Hyundai Motor Group affiliates is compressing supplier negotiation leverage and accelerating price-down schedules across contract renewals. Tier-two pneumatic component producers are responding by forming manufacturing consortia to achieve volume scale. This consolidation is most visible in Gyeonggi Province, where proximity to final assembly has intensified competitive pressure on logistics-cost positioning.
South Korea Automotive Pneumatic Actuators Market Segmentation
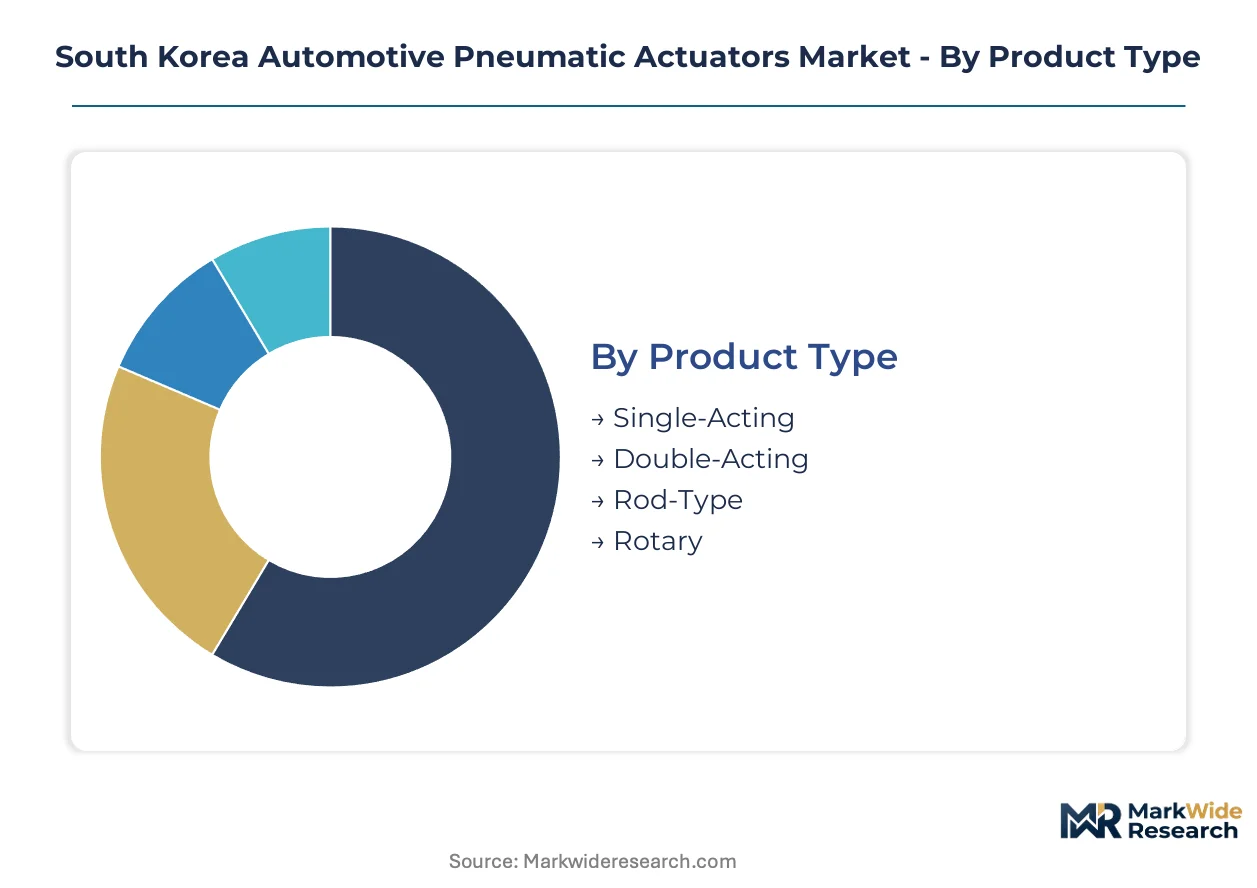
Pneumatic actuator segmentation in South Korea reflects the tension between legacy fluid-power architectures and electrified platform requirements. Hyundai Motor Group's procurement specifications increasingly favor segments that bridge mechanical reliability with electronic interoperability, reshaping how tier-one suppliers allocate R&D resources across product lines.
Product Type:
Standalone pneumatic cylinders dominate brake and exhaust applications, while embedded actuator modules integrate directly with electronic control units in next-generation throttle systems.
- Double-Acting:Bidirectional force delivery enables precise throttle positioning under variable load conditions in engine control modules. Gyeonggi Province assembly lines specify these for thermal management systems where MFDS fatigue validation across minus 40 to 150 degrees Celsius is mandatory.
- Single-Acting:Spring-return mechanisms suit brake caliper reset functions where unidirectional force suffices and cost minimization matters. Seoul-Incheon corridor suppliers concentrate production here for aftermarket rebuild kits serving domestic service networks.
- Rod-Type:Linear motion output serves exhaust gas recirculation flap positioning in diesel platforms still produced for export markets.
- Rotary:Angular displacement capabilities address HVAC blend door actuation in hybrid vehicle thermal systems.
Double-Acting leads volumes today; Hybrid Control is gaining share fastest.
End User:
Procurement authority concentrates with vehicle assemblers who specify performance tiers during platform development, while aftermarket channels operate on compressed margin structures.
- OEMs:Hyundai and Kia captive procurement channels demand actuator modules validated against K-Auto safety certification before platform integration. These buyers negotiate multi-year supply agreements with price-down schedules tied to volume ramps.
- Suppliers:Tier-one integrators in Ulsan and Busan consolidate valve assembly operations to serve brake system producers requiring just-in-sequence delivery windows. Geographic clustering near final assembly reduces logistics friction but intensifies competitive pressure.
- Aftermarket Providers:Brake system rebuild specialists source replacement cylinders through distribution networks concentrated in Seoul metropolitan area.
- Assemblers:Contract manufacturers in Gyeonggi Province perform final actuator module assembly for export-bound vehicle platforms.
OEMs command the dominant revenue share; Suppliers face the steepest margin compression.
Technology:
Control architecture selection determines whether pneumatic specialists retain positioning or cede share to electromechanical competitors in safety-critical applications.
- Pneumatic Control:Pure fluid-power designs maintain cost advantage in exhaust system applications where electronic integration is unnecessary. MFDS quality enforcement still demands fatigue resistance validation that domestic producers must demonstrate through certified in-house testing laboratories.
- Hybrid Control:Combined pneumatic-electric architectures embed position feedback sensors and IoT-enabled condition monitoring for brake-by-wire systems. Seoul's evolving carbon-neutral vehicle regulations create procurement preference windows for these designs over conventional pure pneumatic modules.
- Electric Control:Solid-state actuation threatens pneumatic share in high-force positioning segments as electromechanical reliability improves.
- Solenoid Control:Electromagnetic valve actuation serves rapid-response applications in engine intake systems where millisecond timing precision is required.
Pneumatic Control retains installed base dominance; Hybrid Control climbs the fastest.
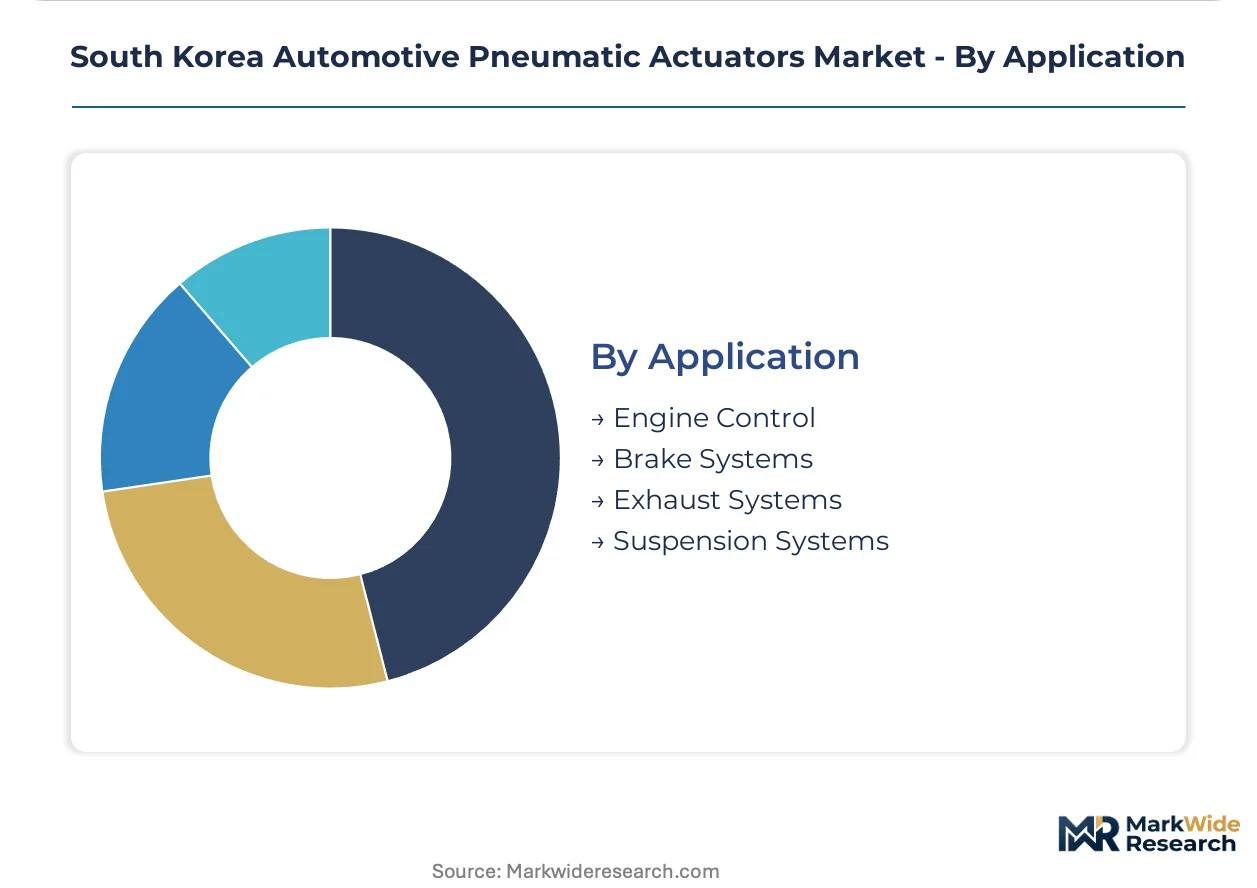
Application:
Functional requirements vary sharply across vehicle systems, with safety-critical applications imposing the most stringent validation protocols on actuator suppliers.
- Brake Systems:Pneumatic actuators in brake-by-wire architectures must interface with electronic control units, demanding firmware competency that traditional fluid-power suppliers must acquire. Ulsan-based integrators consolidate procurement around suppliers with demonstrated ECU interoperability.
- Engine Control:Throttle positioning and exhaust gas recirculation flaps require bidirectional force delivery under thermal stress conditions. Hwaseong plant partnerships with Kia open captive supply arrangements for next-generation systems.
- Exhaust Systems:EGR valve actuation in remaining diesel platforms generates replacement demand through aftermarket channels.
- Suspension Systems:Pneumatic spring and damping control applications are losing share to electromechanical alternatives in premium vehicle segments.
Engine Control leads current procurement volumes; Brake Systems show the steepest technology-driven expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and South Korea anchor automotive pneumatic actuator demand through distinct supply chain configurations, with German precision engineering contrasting Korean platform-specific integration models. Japan maintains specialized positioning in sensor-embedded hybrid designs. China's domestic EV platforms are compressing import dependency for fluid-power components. Mexico's nearshoring momentum is reshaping North American actuator procurement geography.
United States
NHTSA brake-by-wire safety mandates and EPA emissions compliance are accelerating hybrid pneumatic-electric actuator adoption across Detroit Three electrified platforms. Michigan and Ohio assembly corridors concentrate tier-one supplier technical centers where validation against FMVSS 135 brake standards occurs. Domestic OEMs specify fatigue-resistant modules for thermal management systems in battery-electric vehicle architectures.
Germany
KBA type-approval requirements and EU Green Deal carbon-neutral vehicle targets are forcing actuator suppliers to demonstrate lifecycle emissions reductions. Bavaria and Baden-Württemberg host concentrated development activity where Bosch and Continental anchor pneumatic module engineering for premium OEM platforms. Suppliers validate components against ECE R13-H brake system harmonization standards.
Japan
METI technical cooperation agreements with Korean component makers are tightening interoperability standards for pneumatic control modules serving hybrid vehicle production. Nagoya and Tokyo metropolitan manufacturing belts concentrate precision actuator fabrication where Denso and Hitachi embed position feedback sensors. JIS B 8377 cylinder standards govern fatigue resistance validation protocols.
China
MIIT new energy vehicle mandates and dual carbon goals are displacing pure pneumatic designs with electromechanical alternatives in domestic EV platforms. Yangtze River Delta and Pearl River Delta industrial clusters concentrate tier-one supplier manufacturing where local OEMs specify cost-optimized actuators. GB/T 15622 hydraulic and pneumatic cylinder standards impose quality benchmarks.
Mexico
Nearshoring acceleration under USMCA trade provisions is drawing brake system actuator assembly operations to Nuevo León and Bajío Region industrial parks. Proximity to US final assembly reduces logistics friction for just-in-sequence delivery windows. OEM technical centers in Mexico City metropolitan area coordinate validation against NHTSA-aligned safety standards for export-bound platforms.
South Korea Automotive Pneumatic Actuators Market Competitive Landscape
South Korean producers anchor one tier; German and Japanese specialists hold differentiated positions through precision engineering and sensor integration capabilities. The vendor base clusters around three strategic archetypes: integrated automotive suppliers with captive pneumatic module divisions, dedicated fluid-power component specialists, and diversified industrial automation players extending into vehicle applications. Competitive dynamics center on backward integration into valve assembly operations and technology licensing arrangements for hybrid control architectures.
Within the integrated supplier tier, Continental AG and Robert Bosch GmbH exemplify scale-driven positioning through diversified automotive component portfolios. Denso Corporation occupies a specialized position representing Japanese precision manufacturing archetypes. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning without dictating specific strategic moves or market share claims.
| Leading Market Players |
|---|
| Continental AG |
| Nidec Corporation |
| Denso Corporation |
| ASCO Valve Inc |
| SMC Corporation of America |
| Robert Bosch GmbH |
| Bosch Rexroth AG |
| CTS Corporation |
| Hitachi Ltd |
| Others |
Value Network & Pricing Analysis
Captive valve assembly operations in Ulsan and Busan anchor tier-one supplier positioning while compressing margin buffers for pneumatic cylinder producers serving Hyundai Motor Group's electrified platforms. This backward integration into precision manufacturing feeds directly into pricing power consolidation among domestic OEM procurement channels.
Pricing Analysis
Capacity additions in Gyeonggi Province are reshaping price floors as tier-two producers form manufacturing consortia to achieve volume scale. Contract-based long-term offtake agreements dominate OEM procurement, with price differentiation driven by K-Auto certification tier and volume scale commitments. Cost compression in standard-grade pneumatic modules is intensifying because raw material volatility in aluminum alloys and specialty elastomers erodes producer margins. Aftermarket providers exhibit highest price sensitivity due to compressed margin structures in brake system rebuild kits, while OEMs with captive supply arrangements demonstrate lowest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements from Hyundai and Kia procurement teams mandate multi-supplier qualification for safety-critical brake system components, dispersing valve assembly operations across Ulsan, Busan, and Seoul-Incheon corridors. Geographic supply concentration centers on South Korea, Japan, and Germany for precision pneumatic modules and sensor-embedded hybrid designs. Raw material dependencies rest on aluminum alloy feedstock, fluorocarbon elastomer seals, and precision-machined valve bodies. Single-source vulnerability persists for specialty elastomer compounds subject to energy price swings. Distribution runs through just-in-sequence delivery networks directly into Gyeonggi Province assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in South Korea's automotive pneumatic actuator market stems from premium-tier shift toward hybrid pneumatic-electric architectures commanding procurement preference under Seoul's carbon-neutral vehicle regulations.
For Market Incumbents: To counter electromechanical substitution in brake-by-wire applications, tier-one suppliers must acquire firmware development capabilities for ECU interoperability and consolidate procurement relationships through certified in-house testing laboratories demonstrating MFDS fatigue validation. Backward integration into valve assembly operations in Ulsan and Busan secures captive supply positioning against geographic disruption risks. For New Entrants and Emerging Players: Aftermarket brake system rebuild specialists in Seoul metropolitan area represent the most penetrable buyer archetype, underserved by precision-focused tier-one incumbents. White-space targets include single-acting cylinder replacement kits for domestic service networks and thermal management actuators for hybrid vehicle platforms. Go-to-market execution should emphasize rapid certification against K-Auto safety standards to unlock distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for precision manufacturing specialists with demonstrated MFDS compliance because buyer concentration among Hyundai Motor Group affiliates compresses supplier negotiation leverage and accelerates price-down schedules. Long-term viability favors targets with hybrid control architecture capabilities and established Hwaseong plant partnerships. The signal to monitor is Seoul's regulatory trajectory on carbon-neutral vehicle mandates determining procurement preference windows.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Control Architecture Development | MFDS-aligned fatigue validation opens procurement preference under Seoul's carbon-neutral regulations. |
| Backward Integration into Valve Assembly | Ulsan and Busan manufacturing footprints reduce logistics friction for just-in-sequence delivery. |
| K-Auto Safety Certification Investment | Certified in-house testing laboratories consolidate tier-one procurement relationships with domestic OEMs. |
| Firmware Capability Acquisition | ECU interoperability competency defends positioning against electromechanical competitors in brake-by-wire. |
| Manufacturing Consortium Formation | Volume scale achievement counters price-down pressure from Hyundai Motor Group procurement concentration. |
Research Methodology
Bottom-up vehicle platform modeling reconciled against top-down supplier capacity tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations specialists combined with secondary validation from vehicle production databases, IHS Markit registration data, MFDS quality enforcement filings, and Korea Automobile Manufacturers Association reports. Triangulation across these sources ensures segment-level precision.
Input-output matrices map pneumatic actuator content per vehicle across propulsion architecture, vehicle class, and OEM tier dimensions. Modeled segmentation spans product type, end user, technology, and application categories throughout the forecast period. CAGRs derive from production volume trajectories, platform electrification roadmaps, and regulatory compliance timelines. Industry-specific inputs include Hyundai Motor Group's electrified platform rollout schedules and Seoul's evolving carbon-neutral vehicle mandates.
Underlying measurement precision varies by segment; OEM procurement volumes carry tighter precision than aftermarket replacement demand due to consolidated buyer visibility. Forecasts reflect assumptions on platform electrification pace, MFDS enforcement stringency, and raw material cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Connecting Rod Bearing Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
Automotive Steering Column Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Italy Automotive Actuators Market
Automotive Components
Global Automotive Sun Visor Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
India Automotive Stamping Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Europe Automotive Relay Market
Automotive Components
Mexico Automotive Pneumatic Actuators Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
China Automotive Composites Market
Automotive Components
Australia Automotive Pneumatic Actuators Market
Automotive Components
Casted Automotive Components Market
Automotive Components
Automotive Chromium Market