
 Automotive Micro Switch Market | 2026-2036
Automotive Micro Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Micro Switch Market Analysis
A capital-intensity divergence between in-house ceramic substrate fabrication and outsourced semiconductor packaging is bifurcating competitive tiers. Omron Corporation leverages captive cleanroom capacity in Japan to sustain margin on high-cycle sealed switches. TE Connectivity anchors North American supply through automated reel-to-reel assembly lines serving Detroit-based OEMs. C&K Components specializes in miniature surface-mount variants for European transmission module suppliers.
An automotive micro switch is an electromechanical device actuated by minimal physical force through a tipping-point mechanism, typically rated for operating lives exceeding one million cycles with contact resistances below 100 milliohms. These components translate mechanical position or pressure into discrete electrical signals for vehicle control systems. Sealed micro switches command premium positioning as ingress protection requirements harden under electric vehicle thermal management demands, while snap action variants occupy volume tiers in legacy door latch applications. Optical sensing technology is displacing mechanical architectures in transmission position detection where arc suppression and contactless operation reduce warranty exposure.
FDA oversight of automotive-grade materials remains indirect, yet NHTSA Federal Motor Vehicle Safety Standards governing unintended acceleration and stall protection directly prescribe switch redundancy in powertrain controls. EPA tailpipe regulations cascade into engine management switch precision requirements as lean-burn combustion strategies demand tighter sensor-actuator synchronization. Stakeholders must monitor how China's GB standards for new energy vehicles harmonize with EU REACH substance restrictions on contact plating alloys, since dual compliance will determine factory qualification for cross-border platform programs.
Market Dynamics
Electrification of vehicle powertrains is forcing a wholesale redesign of switch architectures, as thermal management demands and high-voltage isolation requirements render legacy electromechanical designs obsolete for battery-electric platforms.
Growth Catalysts
- China's MIIT intelligent connected vehicle mandates:Tightening reliability standards for signal integrity in autonomous driving subsystems are pulling precision micro switches into advanced driver-assistance modules.
- Transmission electrification:Dual-clutch and continuously variable transmission architectures require position sensing at multiple points, expanding switch count per vehicle in hybrid powertrains.
- Germany's automotive corridor concentration:Tier-1 suppliers headquartered in Stuttgart and Munich are sourcing sealed variants for next-generation electric platforms, creating demand density.
Market Restraints
- Silver-palladium contact plating volatility:Precious metal input costs for high-cycle rated switches create margin compression for manufacturers without captive refining arrangements.
- Japanese cleanroom supply concentration:Captive ceramic substrate fabrication capacity clusters in specific industrial zones, creating single-source vulnerability for sealed switch supply.
- Optical sensing substitution:Contactless position detection in transmission modules eliminates mechanical wear points, threatening replacement demand for traditional snap-action architectures.
Strategic Opportunities
- India's PLI scheme for automotive components:Localized production incentives for electromechanical parts create factory qualification pathways for export to ASEAN markets.
- Vehicle-to-everything communication modules:Antenna position sensing and charging port detection represent emerging switch applications in connected vehicle architectures.
- EU REACH substance restriction harmonization:Dual compliance frameworks with China's GB standards create certification arbitrage for suppliers mastering both regulatory regimes.
Industry Challenges
- High-voltage isolation certification timelines:UL and IEC qualification protocols for 800-volt electric vehicle systems extend product validation cycles by 8-12 months.
- Legacy powertrain integration complexity:Mechanical switches must interface with controller area network architectures designed for solid-state sensing, requiring signal conditioning electronics.
- Cleanroom technician scarcity:Hermetic sealing processes require specialized ceramic-to-metal bonding expertise concentrated in aging workforce demographics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Micro Switch Market |
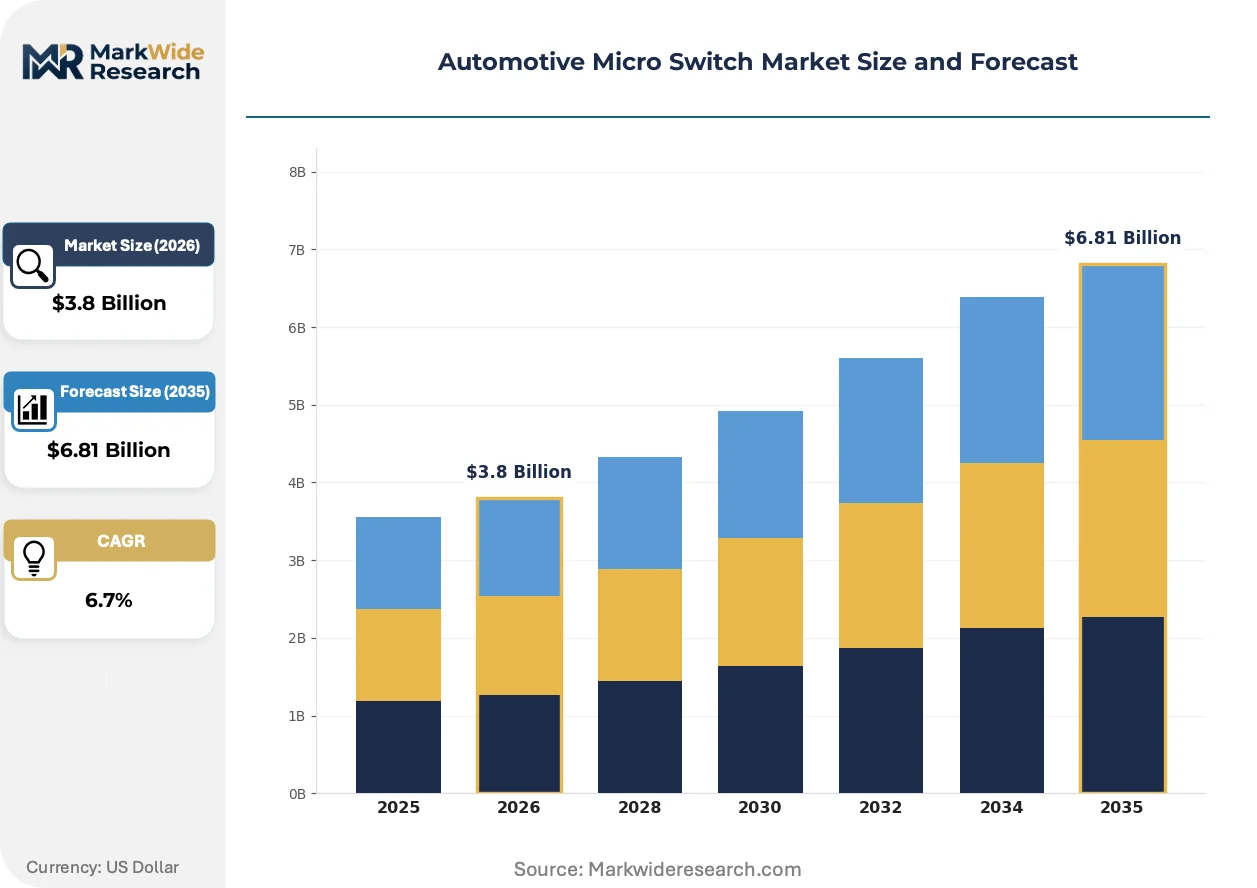
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Micro Switches, Sealed Micro Switches, Pushbutton Switches, Snap Action Switches Technology: Mechanical, Electrical, Optical, Proximity Application: Door Locks, Lighting Control, Engine Management, Transmission Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | C&K Components, Inc., Omron Corporation, Johnson Electric Holdings Limited, Crouzet Automatismes SAS, ZF Friedrichshafen AG, Alps Electric Co., Ltd., Honeywell International Inc., TE Connectivity, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Micro Switch Market Emerging Trajectories
Material science breakthroughs in contact alloys and housing polymers are enabling switches to survive temperature excursions beyond 150°C, while magnetic and optical sensing architectures erode the mechanical switch's traditional strongholds.
Platinum-nickel contact coatings with nano-structured surface morphologies are extending electrical life beyond five million cycles in sealed powertrain applications. Battery-electric vehicle manufacturers in South Korea and Germany are specifying these variants for thermal management valve actuation. This metallurgical advance is supplanting conventional silver-cadmium-oxide compositions in high-reliability segments where arc erosion previously limited service life.
REACH substance restrictions on hexavalent chromium plating are forcing conversion to trivalent alternatives for switch housings and levers. European Tier-1 suppliers face reformulation costs and supply base requalification. Transmission module manufacturers are responding by consolidating procurement with vendors holding pre-certified material libraries, compressing qualified supplier lists.
Automotive OEMs are unbundling after-sales switch replacement from dealer service contracts, creating independent channel demand. E-commerce platforms specializing in electromechanical components are capturing growing share of maintenance procurement for commercial vehicle fleets. North American long-haul trucking operators are driving this shift through direct sourcing of standardized snap-action variants for door latch and cabin control repairs.
Automotive Micro Switch Market Segmentation
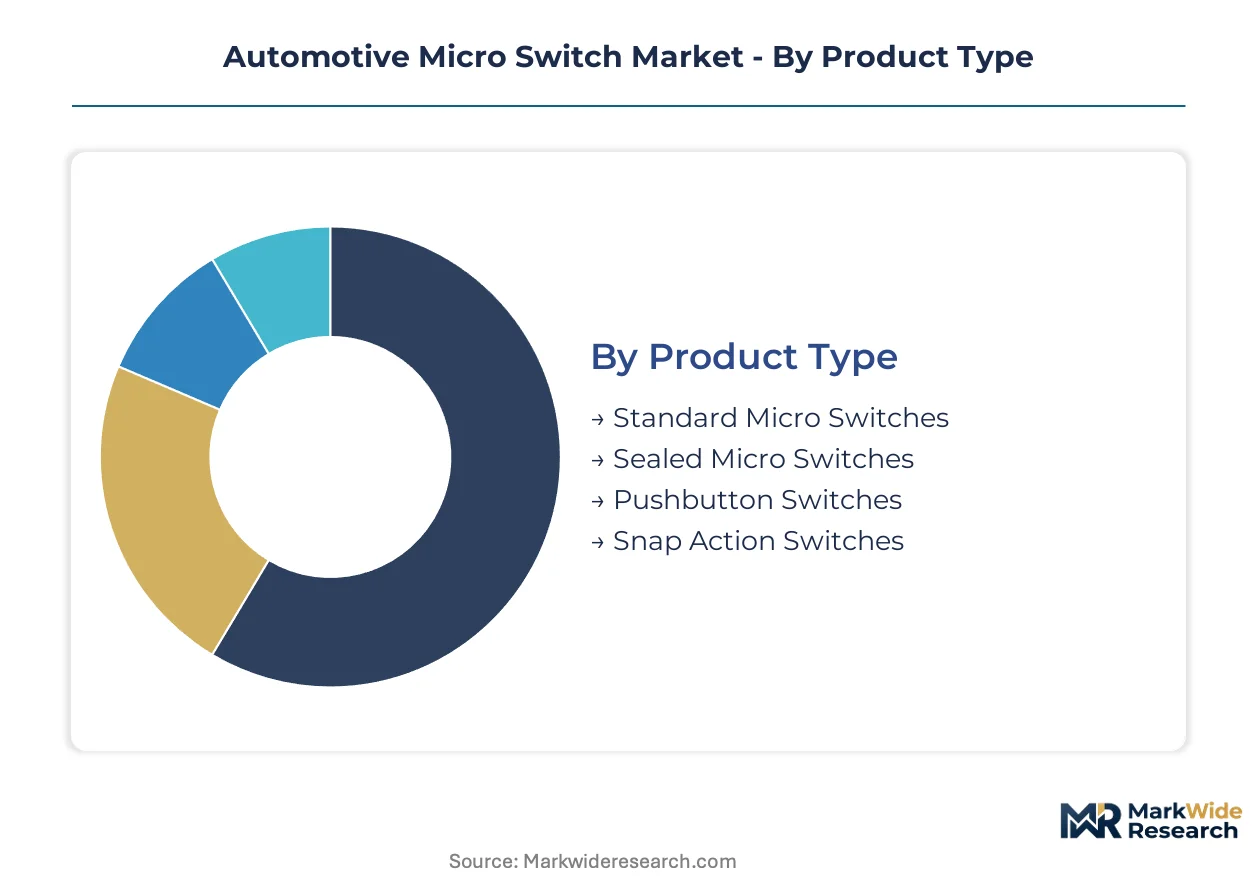
Segmentation in automotive micro switches tracks how thermal management demands and electrification architectures are redistributing value across component specifications. Understanding where margin concentrates by product type and technology enables suppliers to align R&D investment with OEM platform roadmaps.
Product Type:
Sealed variants capture premium margin pools as ingress protection ratings tighten under electric vehicle thermal cycling requirements.
- Sealed Micro Switches:Hermetic ceramic-to-metal bonding withstands temperature excursions beyond 150°C in battery-electric powertrain valve actuation. South Korean and German OEMs specify these for thermal management systems where arc suppression extends electrical life past five million cycles.
- Snap Action Switches:Tipping-point mechanisms deliver discrete electrical signals through minimal physical force, traditionally dominating door latch and cabin control applications. North American long-haul fleet operators source standardized variants through independent e-commerce channels as OEMs unbundle after-sales service contracts.
- Standard Micro Switches:Unsealed electromechanical designs serve cost-sensitive legacy platforms with operating lives rated near one million cycles.
- Pushbutton Switches:Manual actuation variants occupy steering wheel and dashboard interface positions where tactile feedback requirements persist.
Sealed Micro Switches hold installed capacity in captive cleanroom facilities. Snap Action Switches are rotating up the share rankings in independent aftermarket channels.
Technology:
Mechanical architectures still dominate unit volume, yet optical sensing is climbing the technology stack where contactless operation reduces warranty exposure.
- Optical:Contactless position detection eliminates mechanical wear points in transmission modules, displacing traditional architectures where arc erosion previously limited service life. Dual-clutch and continuously variable transmission designs in hybrid powertrains specify these for multi-point position sensing.
- Mechanical:Electromechanical tipping-point designs translate physical force into discrete signals through precious metal contacts, typically silver-palladium or platinum-nickel compositions. China's MIIT mandates for intelligent connected vehicles are pulling precision mechanical variants into advanced driver-assistance modules.
- Electrical:Solid-state signal conditioning interfaces legacy mechanical switches with controller area network architectures.
- Proximity:Non-contact detection enables charging port position sensing and antenna alignment in vehicle-to-everything communication modules.
Mechanical technology retains the deepest supplier qualification lists. Optical is expanding most quickly in transmission electrification programs.
Application:
Engine Management and Transmission Systems concentrate specification complexity as powertrain electrification forces wholesale switch architecture redesigns.
- Transmission Systems:Position sensing at multiple points in dual-clutch and continuously variable architectures expands switch count per vehicle in hybrid powertrains. NHTSA Federal Motor Vehicle Safety Standards governing unintended acceleration directly prescribe switch redundancy in these controls.
- Engine Management:Lean-burn combustion strategies demand tighter sensor-actuator synchronization, cascading EPA tailpipe regulations into precision switch requirements. EU REACH substance restrictions on contact plating alloys complicate dual compliance with China's GB standards for new energy vehicles.
- Door Locks:Latch actuation and central locking systems specify snap-action variants with operating lives exceeding one million cycles.
- Lighting Control:Headlamp leveling and interior dimming circuits employ compact surface-mount designs.
Transmission Systems anchor Tier-1 supplier procurement concentration in Germany's automotive corridor. Engine Management is climbing the specification ladder as 800-volt electric vehicle platforms extend validation cycles.
End User:
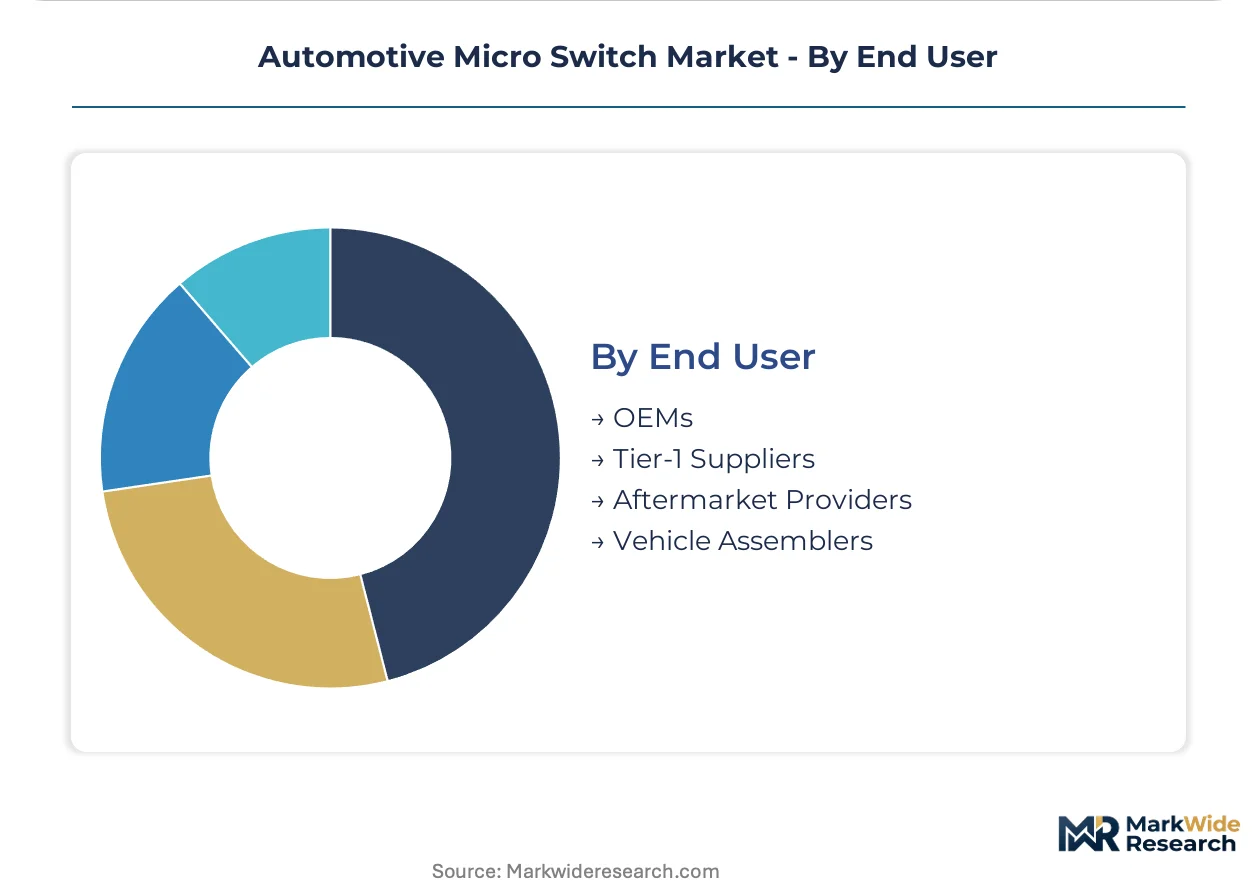
Tier-1 Suppliers and OEMs control qualified supplier list access, while Aftermarket Providers capture growing share as procurement patterns shift toward direct fleet sourcing.
- Tier-1 Suppliers:Transmission module and powertrain system integrators in Stuttgart and Munich consolidate procurement with vendors holding pre-certified material libraries under EU REACH trivalent chromium conversion requirements. These suppliers source sealed variants for next-generation electric platforms.
- Aftermarket Providers:E-commerce platforms specializing in electromechanical components capture maintenance procurement for commercial vehicle fleets as North American long-haul operators bypass dealer service contracts for standardized snap-action door latch repairs.
- OEMs:Vehicle manufacturers specify switch architectures at platform design stage, driving captive cleanroom capacity investment for high-reliability segments.
- Vehicle Assemblers:Final assembly operations integrate pre-validated switch modules from approved Tier-1 sources.
Tier-1 Suppliers hold the deepest factory qualification pathways. Aftermarket Providers are gaining share fastest in independent channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in precision electromechanical components are reshaping factory qualification pathways. China's MIIT mandates and Germany's automotive corridor concentration create divergent demand centers. South Korean battery-electric platforms and India's component incentives add new supply nodes.
China
MIIT intelligent connected vehicle mandates pull precision micro switches into advanced driver-assistance modules. GB standards for new energy vehicles harmonize with substance restrictions on contact plating alloys. Yangtze River Delta clusters house captive cleanroom capacity for sealed switch ceramic substrate fabrication.
Germany
Stuttgart and Munich-based Tier-1 suppliers source sealed variants for next-generation electric platforms. EU REACH trivalent chromium conversion requirements compress qualified supplier lists. Baden-Württemberg's automotive corridor anchors procurement concentration for transmission module manufacturers.
United States
NHTSA Federal Motor Vehicle Safety Standards prescribe switch redundancy in powertrain controls for unintended acceleration prevention. EPA tailpipe regulations cascade into engine management precision requirements. Detroit-based OEMs drive automated reel-to-reel assembly line investment by North American suppliers.
South Korea
Battery-electric vehicle manufacturers specify platinum-nickel contact coatings for thermal management valve actuation. MFDS oversight of automotive-grade materials intersects with national EV platform roadmaps. Seoul Capital Area suppliers extend electrical life specifications beyond five million cycles in sealed powertrain applications.
India
PLI scheme incentives for automotive components create factory qualification pathways for ASEAN export markets. BIS standards for electromechanical parts align with dual compliance frameworks for EU-bound production. Maharashtra and Tamil Nadu industrial corridors attract localized switch manufacturing for transmission electrification programs.
Automotive Micro Switch Market Vendor Landscape
Concentration sits with diversified electromechanical conglomerates and specialized precision component fabricators. The vendor base spans Japanese cleanroom-dependent sealed switch producers, European automotive corridor-anchored Tier-1 suppliers, and North American automated assembly specialists. Two strategic archetypes dominate: vertically integrated ceramic substrate manufacturers and outsourced semiconductor packaging partners. Competitive moves center on captive refining arrangements for precious metal contacts and pre-certified material library consolidation under REACH compliance.
Within the diversified conglomerate tier, Omron Corporation and Panasonic Corporation exemplify cleanroom-captive production models. TE Connectivity occupies a position among North American automated assembly specialists serving Detroit OEMs. C&K Components, Inc. represents the precision miniature specialist archetype for European transmission module sourcing.
| Leading Market Players |
|---|
| C&K Components, Inc. |
| Omron Corporation |
| Johnson Electric Holdings Limited |
| Crouzet Automatismes SAS |
| ZF Friedrichshafen AG |
| Alps Electric Co., Ltd. |
| Honeywell International Inc. |
| TE Connectivity |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Eighteen-week lead times for sealed micro switch ceramic substrates concentrate pricing power with Japanese cleanroom operators while forcing European Tier-1 suppliers into long-term offtake contracts. This inventory compression cascades into spot market premiums for snap-action variants serving North American aftermarket channels.
Pricing Analysis
Configured-to-order pricing for sealed variants with platinum-nickel contacts commands spreads over standard snap-action designs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade, with UL/IEC 800-volt qualified products capturing margin premiums. Cost compression in unsealed standard tiers intensifies because silver-palladium plating volatility squeezes contract manufacturers lacking captive refining. Fleet operators sourcing through independent e-commerce platforms exhibit highest price sensitivity, while German OEMs specifying hermetic bonding show lowest sensitivity due to platform lock-in requirements.
Supply Chain Analysis
Inventory tightness at eighteen weeks for ceramic substrates feeds from supply concentration across Japan, Germany, and China. Raw material dependencies rest on silver-palladium contact alloys, ceramic-to-metal bonding compounds, and trivalent chromium housing platings. Single-source vulnerability clusters in Yangtze River Delta cleanroom facilities under MIIT qualification requirements. Distribution runs through Tier-1 system integrators in Stuttgart and Munich, with aftermarket channels fragmenting toward direct e-commerce procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in powertrain electrification cyclical recovery as battery-electric platform ramps pull precision switch demand from trough levels.
For Market Incumbents: Secure captive refining arrangements for precious metal contacts to defend against silver-palladium volatility eroding contract margins. Consolidate pre-certified material libraries under REACH trivalent chromium requirements to compress qualified supplier lists and lock out challengers. Add cleanroom capacity in South Korea to offset aging technician demographics threatening hermetic sealing yields. For New Entrants and Emerging Players: Differentiate on proximity sensing architectures for vehicle-to-everything charging port detection, where optical substitution has not yet displaced mechanical designs. Target India's PLI scheme corridors for localized production serving ASEAN transmission electrification programs. Pursue direct fleet e-commerce channels in North American long-haul trucking as OEMs unbundle after-sales service contracts. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cleanroom-captive production models and REACH certification moats favor scaled incumbents over fragmented assemblers. Acquisition targets should display backward integration into ceramic substrate fabrication or pre-qualified material libraries. Watch NHTSA rulemaking on unintended acceleration switch redundancy as inflection signal for specification intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Substrate Capacity Expansion | Captive cleanroom investment in South Korea supports platinum-nickel contact coating specifications from Seoul-based OEMs. |
| REACH Certification Pre-Qualification | Trivalent chromium material libraries compress supplier lists for Stuttgart transmission module manufacturers. |
| Aftermarket Channel Direct Access | E-commerce platform partnerships capture fleet procurement as dealer service contracts unbundle. |
| Optical Sensing R&D Partnership | Contactless position detection development addresses transmission module warranty exposure reduction. |
| India PLI Manufacturing Footprint | Maharashtra and Tamil Nadu localized production creates ASEAN export qualification pathways. |
Methodological Framework
The analysis maps sealed micro switch, snap-action variant, optical sensing, and proximity detection sub-sectors, each validated through Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution specialists, and ceramic substrate fabrication technicians. Primary interview findings triangulate against vehicle production databases, IHS Markit registration data, MIIT GB standard filings, and EU REACH substance restriction updates. Bottom-up bill-of-materials content per vehicle estimates reconcile with top-down market sizing across propulsion architectures.
Consistency checks validate volume and value outputs against external benchmarks throughout the forecast period. Segmentation dimensions model product type, technology architecture, application system, and end-user channel across the analysis window. CAGRs derive from fitted growth curves applied to platform electrification roadmaps and thermal management valve actuation content trajectories. Battery-electric vehicle production schedules and dual-clutch transmission penetration rates serve as key forecast inputs.
Forecasts assume regulatory continuity in NHTSA Federal Motor Vehicle Safety Standards, EU REACH substance restrictions, and China's MIIT intelligent connected vehicle mandates; material policy shifts would require re-modeling switch redundancy requirements or contact plating alloy specifications. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
On Board Connectivity Market
Automotive Electronics & Wiring
Automotive Wiring Harness Market
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Connectivity Control Unit Market
Automotive Electronics & Wiring
India Automotive Lighting Market
Automotive Electronics & Wiring
Automotive Camera and Camera Module Market
Automotive Electronics & Wiring
North America Electric Vehicle Sensor Market
Automotive Electronics & Wiring
North America Automotive Steering Sensor Market
Automotive Electronics & Wiring
Automotive Electronics Sensor Aftermarket Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
Car Speaker Market
Automotive Electronics & Wiring
Vehicle Control Unit (VCU) Market