
 Automotive Aftermarket for Brake Components Market | 2026-2036
Automotive Aftermarket for Brake Components Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Aftermarket for Brake Components Market Analytics
Electrification of braking systems is narrowing the performance gap between friction-based and regenerative braking architectures. Brembo S.p.A. leverages its motorsport heritage to develop high-performance calipers for hybrid platforms. Continental AG anchors its aftermarket position through integrated brake-by-wire modules that simplify repair shop diagnostics. Robert Bosch GmbH dominates the sensor-embedded pad segment where wear-monitoring electronics extend service revenue streams.
The automotive aftermarket for brake components encompasses replacement friction materials, hydraulics, and actuation hardware engineered to OEM thermal, wear, and NVH specifications for vehicle deceleration and safety-critical stopping performance. Brake pads utilize semi-metallic, ceramic, or organic formulations bonded to steel backing plates, while rotors employ cast iron or carbon-ceramic composites machined to precise runout tolerances. Brake pads command the largest revenue share among product types due to their shorter replacement cycles and material-intensive formulations. The online distribution channel grows fastest as digital fitment databases reduce counter returns and mobile service vans expand last-mile installation capacity.
The US NHTSA enforces FMVSS 135 stopping-distance standards that aftermarket suppliers must validate through third-party testing. Europe's ECE R90 homologation framework prevents non-certified brake linings from entering EU member states, creating a compliance moat for established manufacturers. China's GB 5763 standard governs friction material performance testing for domestic and imported aftermarket components. Stakeholders must weigh regulatory certification costs against the margin compression from unlicensed competitors in emerging supply corridors.
Market Dynamics
Electrification of vehicle platforms is compressing brake component replacement cycles while simultaneously elevating thermal performance requirements for friction materials that must interface with regenerative braking systems.
Growth Catalysts
- Extended service interval mandates:Fleet operators across North America now specify brake pad formulations rated for longer duty cycles, pulling premium ceramic-composite demand upward.
- ECE R90 homologation framework:Europe's mandatory certification for aftermarket brake linings creates a compliance barrier that filters low-grade imports and secures revenue for certified manufacturers.
- Ceramic-composite production scaling:China's eastern manufacturing corridor has concentrated domestic supplier investment in advanced friction material capacity.
Market Restraints
- Raw material volatility:Copper and rare earth prices in friction formulations expose margin compression for semi-metallic pad producers.
- Supplier concentration risk:Carbon-ceramic rotor manufacturing clusters in Germany and Italy create single-source dependencies for high-performance applications.
- Regulatory friction:China's GB 5763 testing protocols impose extended validation timelines that delay product entry for foreign suppliers.
Strategic Opportunities
- Mobile installation networks:Service vans equipped with digital fitment databases are capturing last-mile brake replacement volume in suburban US markets.
- Sensor-embedded pad integration:Wear-monitoring electronics convergence with telematics platforms opens recurring revenue streams for connected brake systems.
- India's PLI scheme for auto components:Production-linked incentives for advanced braking hardware attract capital toward domestic friction material plants.
Industry Challenges
- Brake-by-wire calibration expertise:Repair shops face skill gaps in diagnosing integrated electronic-hydraulic actuation modules.
- Homologation timeline compression:ECE R90 certification cycles strain R&D bandwidth as platforms proliferate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Aftermarket for Brake Components Market |
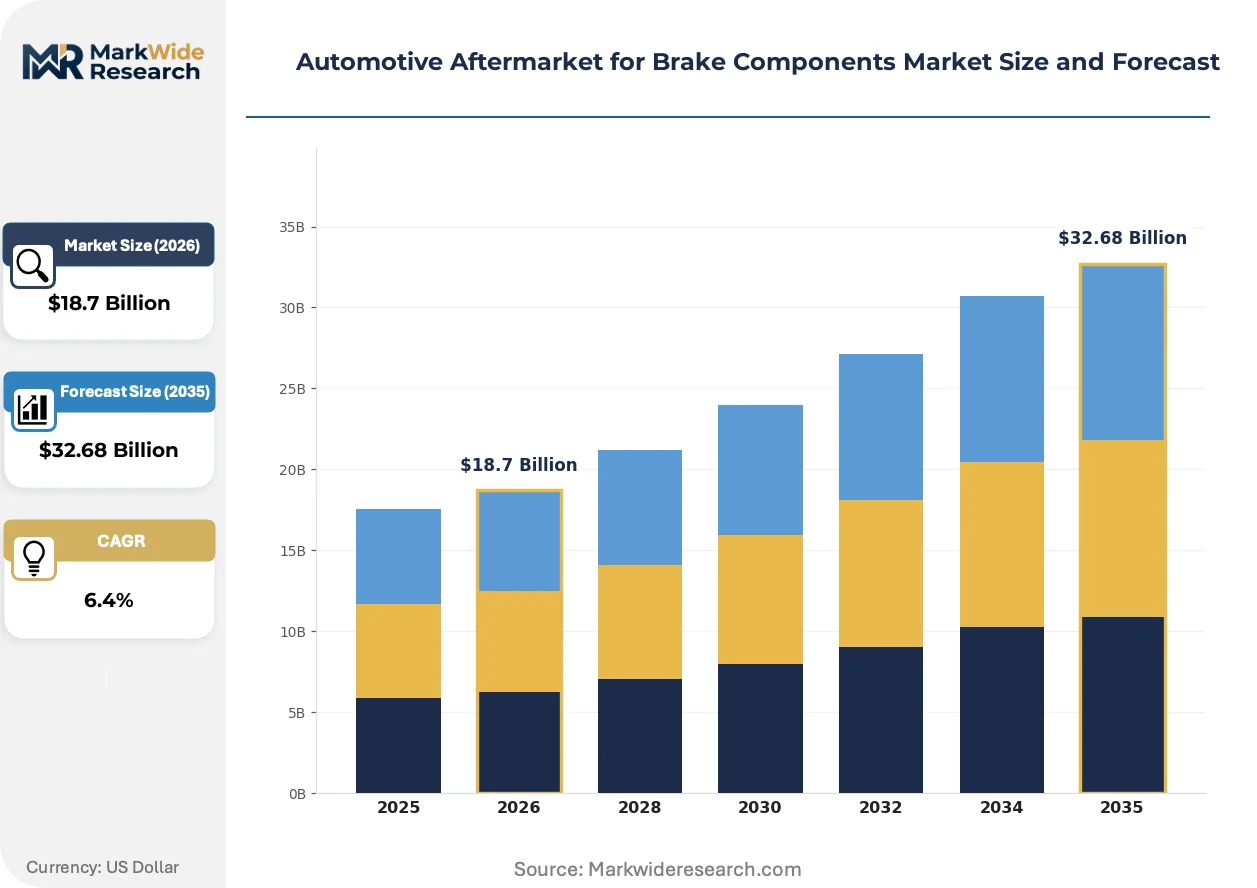
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brake Pads, Brake Rotors, Brake Calipers, Brake Shoes End User: Repair Shops, DIY Enthusiasts, Vehicle Fleets, Online Retailers Distribution Channel: Wholesale, Retail, Online, Mobile Services Vehicle Type: Passenger Cars, Light Trucks, Motorcycles, Heavy-Duty Vehicles |
| Companies Covered | Brembo S.p.A., Continental AG, Robert Bosch GmbH, ZF Friedrichshafen AG, Akebono Brake Industry Co. Ltd., AISIN CORP., BorgWarner Inc., Carlisle Companies Inc., ABS Friction Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Aftermarket for Brake Components Market Evolving Landscape
Friction material chemistry and electronic integration are the twin vectors reshaping brake component value creation, with thermal management and predictive maintenance emerging as the decisive performance differentiators.
Ceramic-composite formulations are migrating from motorsport and supercar applications toward mass-market hybrid platforms. OEMs specify these materials for regenerative braking compatibility where reduced dust and thermal stability outweigh cost premiums. The shift is compressing market share for traditional semi-metallic compounds in the premium replacement segment.
Europe's ECE R90 homologation framework tightens enforcement through member-state market surveillance authorities. Non-certified brake linings face border detention and recall liability, elevating compliance costs for smaller suppliers. The regulation most impacts imported economy-grade pads, driving consolidation among distributors who must verify certificate authenticity.
Fleet procurement now mandates outcome-based brake wear contracts rather than unit-volume purchases. Commercial vehicle operators in North America negotiate per-mile stopping performance agreements that transfer material selection risk to suppliers. This model concentrates buying power with integrated service providers who control specification authority.
Automotive Aftermarket for Brake Components Market Segmentation
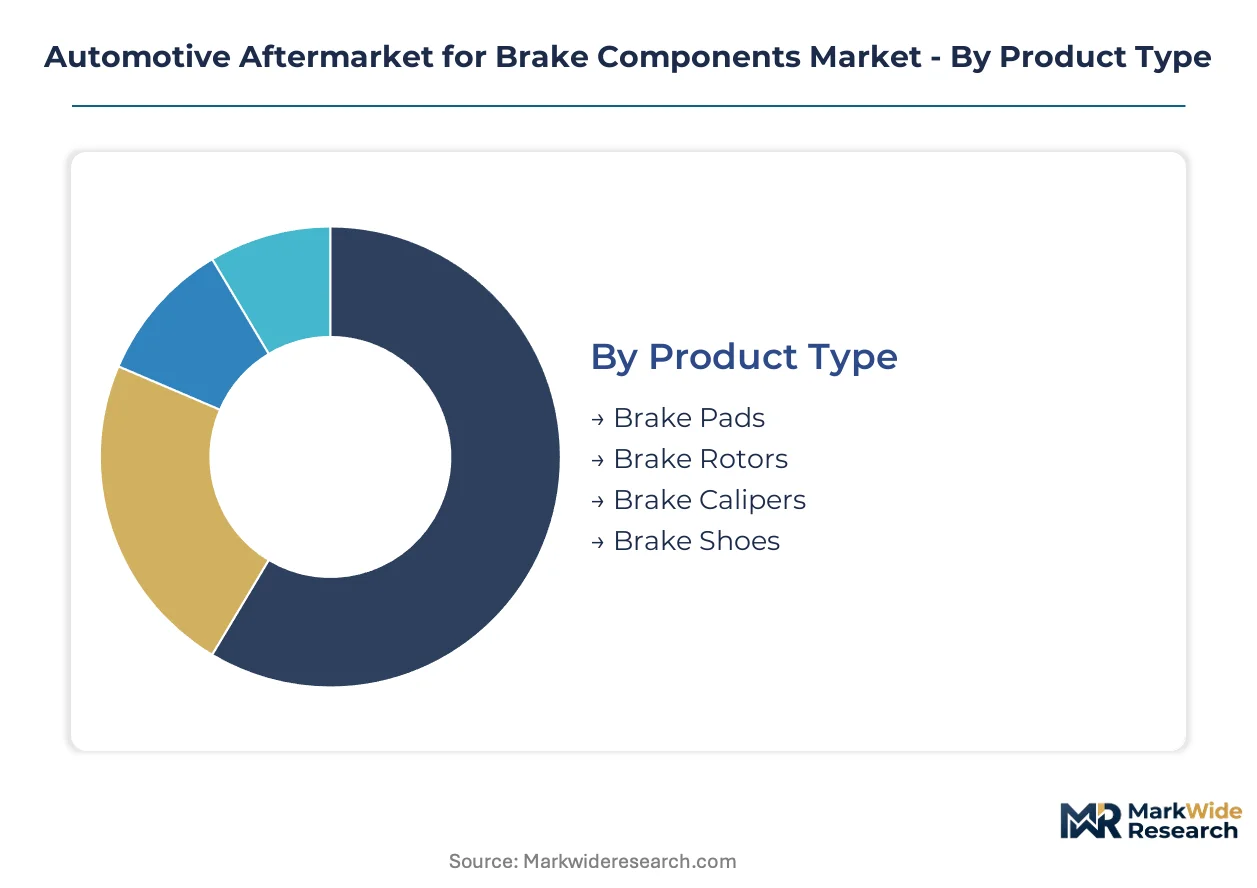
Segmentation in brake components aftermarket reveals how replacement cycles, installation complexity, and procurement authority fragment demand across incompatible technical specifications and service models. Each dimension carries distinct margin profiles and competitive entry barriers.
Product Type:
Mature friction materials dominate revenue concentration while emerging electronic-hydraulic integration reshapes value capture.
- Brake Pads:Friction materials bonded to steel backing plates utilize semi-metallic, ceramic, or organic formulations engineered to OEM thermal and NVH specifications. Fleet procurement in North America now mandates extended-duty ceramic-composite formulations rated for longer replacement intervals, compressing volume for economy-grade semi-metallic compounds.
- Brake Rotors:Cast iron or carbon-ceramic discs machined to precise runout tolerances interface with caliper clamping force to dissipate kinetic energy as heat. China's eastern manufacturing corridor has concentrated domestic supplier investment in ventilated rotor capacity serving the replacement market for light trucks.
- Brake Calipers:Hydraulic actuation housings manufactured through precision casting and piston bore honing operations.
- Brake Shoes:Drum brake friction assemblies retaining niche application in heavy-duty rear axle configurations and emerging market vehicle parc.
Brake pads retain volume leadership; brake calipers hold the steepest expansion curve as electronic parking brake integration elevates unit values.
End User:
Procurement authority concentrates with integrated service providers while fragmentation persists among self-directed consumers.
- Repair Shops:Independent and franchised service centers controlling specification authority for 70%+ of installed aftermarket brake components. US NHTSA FMVSS 135 compliance documentation requirements favor suppliers with established third-party testing relationships, filtering smaller competitors from shop-approved vendor lists.
- Vehicle Fleets:Commercial operators negotiating outcome-based wear contracts that transfer material selection risk to suppliers. North American fleet procurement now specifies per-mile stopping performance agreements rather than unit-volume purchases, concentrating buying power with integrated brake service providers.
- DIY Enthusiasts:Self-installing consumers sourcing components through retail and online channels.
- Online Retailers:Digital platforms capturing growing share of informed consumer procurement through fitment database accuracy.
Repair shops retain volume leadership; vehicle fleets hold the steepest expansion curve as commercial procurement consolidates.
Distribution Channel:
Physical infrastructure maintains installed base service while digital integration reconfigures last-mile fulfillment economics.
- Wholesale:Warehouse distributors serving repair shop networks with inventory depth and technical support. Europe's ECE R90 homologation enforcement through member-state market surveillance authorities elevates compliance documentation requirements, favoring established wholesale suppliers with certificate verification systems.
- Online:Digital platforms leveraging VIN-specific fitment databases to reduce counter returns and expand geographic reach. Mobile service van networks equipped with these databases are capturing suburban brake replacement volume through direct-to-consumer installation.
- Retail:Counter-based parts stores serving DIY and walk-in professional trade.
- Mobile Services:Technician-operated vans delivering on-site brake replacement without fixed facility overhead.
Wholesale retains volume leadership; mobile services hold the steepest expansion curve as suburban last-mile models proliferate.
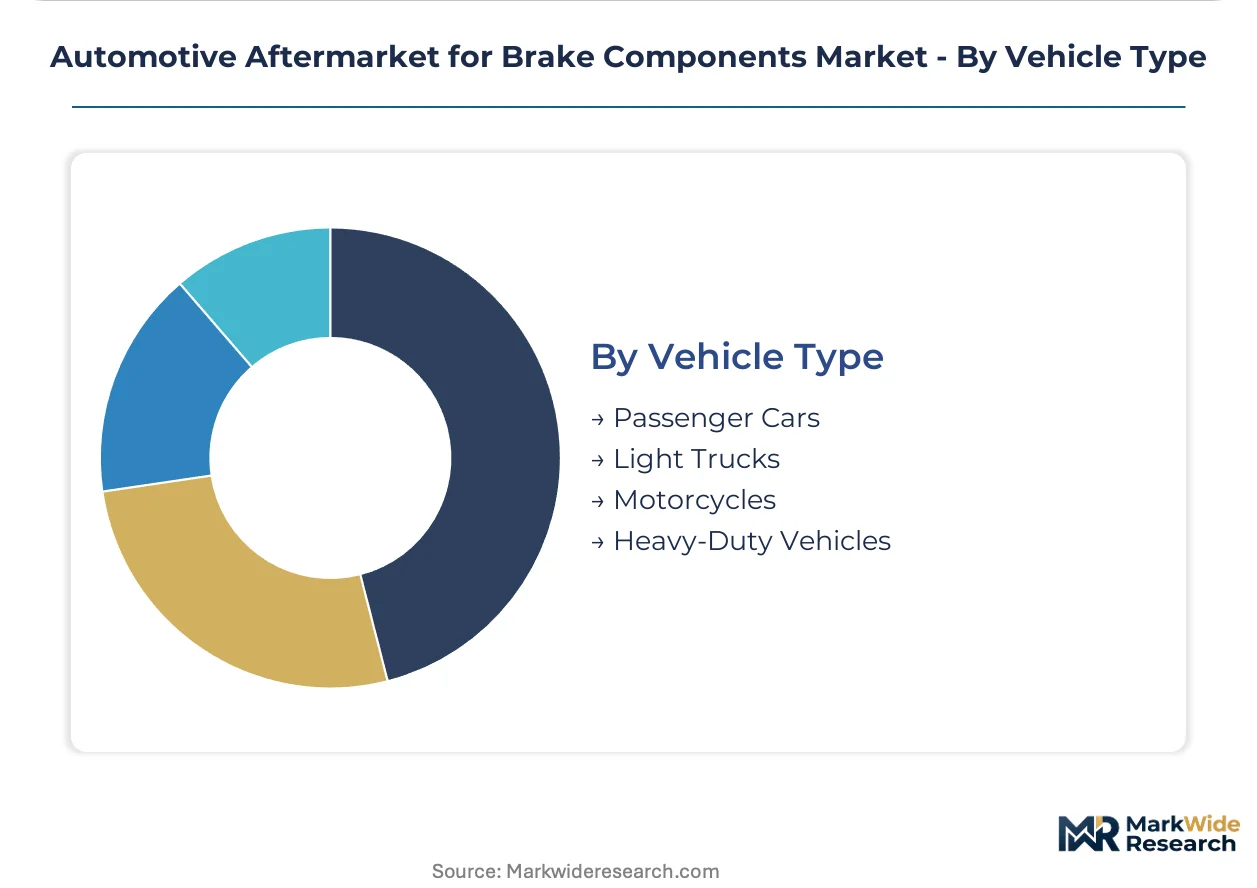
Vehicle Type:
Passenger car parc scale generates replacement volume while commercial duty cycles elevate per-vehicle component consumption.
- Passenger Cars:The largest installed base generating recurring pad and rotor replacement demand across diverse friction material specifications. China's GB 5763 standard governs friction material performance testing for domestic aftermarket components, imposing extended validation timelines that delay foreign supplier entry.
- Heavy-Duty Vehicles:Commercial trucks and buses consuming multiple pad sets annually under severe thermal loading. Fleet specification of extended-service ceramic formulations in North America pulls premium material demand upward despite higher unit costs.
- Light Trucks:Pickup and van platforms with elevated payload duty cycles versus passenger cars.
- Motorcycles:Two-wheel applications with specialized sintered pad formulations and smaller rotor diameters.
Passenger cars retain volume leadership; heavy-duty vehicles hold the steepest expansion curve as fleet procurement concentrates specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports brake components across EU member states while China's eastern manufacturing corridor supplies friction materials to Southeast Asian replacement markets. Trade flows concentrate through Rotterdam and Hamburg ports for European distribution, with Shanghai and Ningbo handling Asia-Pacific volume.
United States
Fleet operators specify extended-service ceramic-composite formulations for commercial vehicle parc. NHTSA enforces FMVSS 135 stopping-distance standards through third-party validation requirements. Detroit's supplier ecosystem anchors domestic rotor machining capacity serving North American light truck replacement demand.
Germany
Carbon-ceramic rotor manufacturing clusters serve premium vehicle aftermarket segments. KBA administers ECE R90 homologation enforcement through border surveillance and certificate verification. Stuttgart's precision casting operations concentrate hydraulic caliper production for EU-wide distribution.
China
Domestic suppliers scale ceramic-composite friction material output for hybrid platform compatibility. MIIT oversees GB 5763 standard compliance through extended validation protocols. Yangtze River Delta manufacturing bases concentrate ventilated rotor capacity for domestic and export replacement markets.
Japan
OEM heritage suppliers leverage motorsport thermal management expertise for aftermarket premium segments. METI coordinates JIS standard alignment with international brake performance protocols. Aichi Prefecture's industrial corridor hosts precision machining operations for electronic parking brake integration.
India
Commercial vehicle parc expansion drives drum brake shoe replacement volume in heavy-duty applications. PLI scheme for auto components attracts capital toward domestic friction material plants. Tamil Nadu's automotive belt concentrates supplier investment in semi-metallic pad production capacity.
Automotive Aftermarket for Brake Components Market Competitive Landscape
On the supply side, the industry is tiered across integrated system suppliers, specialized friction material manufacturers, and regional fabrication operations. Consolidation pressures concentrate among homologation-certified players while unlicensed imports face enforcement barriers. Three archetypes dominate: motorsport-heritage performance specialists, sensor-integrated electronics integrators, and scale-driven commodity friction suppliers. Competitive moves center on ECE R90 certification acquisition and mobile service network partnerships.
Within the integrated system supplier tier, Brembo S.p.A., Continental AG, and Robert Bosch GmbH exemplify divergent strategic positioning. Brembo S.p.A. occupies a heritage-anchored position in high-performance thermal management applications. Continental AG represents the electronics-hydraulic convergence archetype with brake-by-wire module integration. Robert Bosch GmbH anchors the sensor-embedded pad segment where wear-monitoring hardware extends service revenue capture.
| Leading Market Players |
|---|
| Brembo S.p.A. |
| Continental AG |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Akebono Brake Industry Co. Ltd. |
| AISIN CORP. |
| BorgWarner Inc. |
| Carlisle Companies Inc. |
| ABS Friction Inc. |
| Others |
Value Network & Pricing Analysis
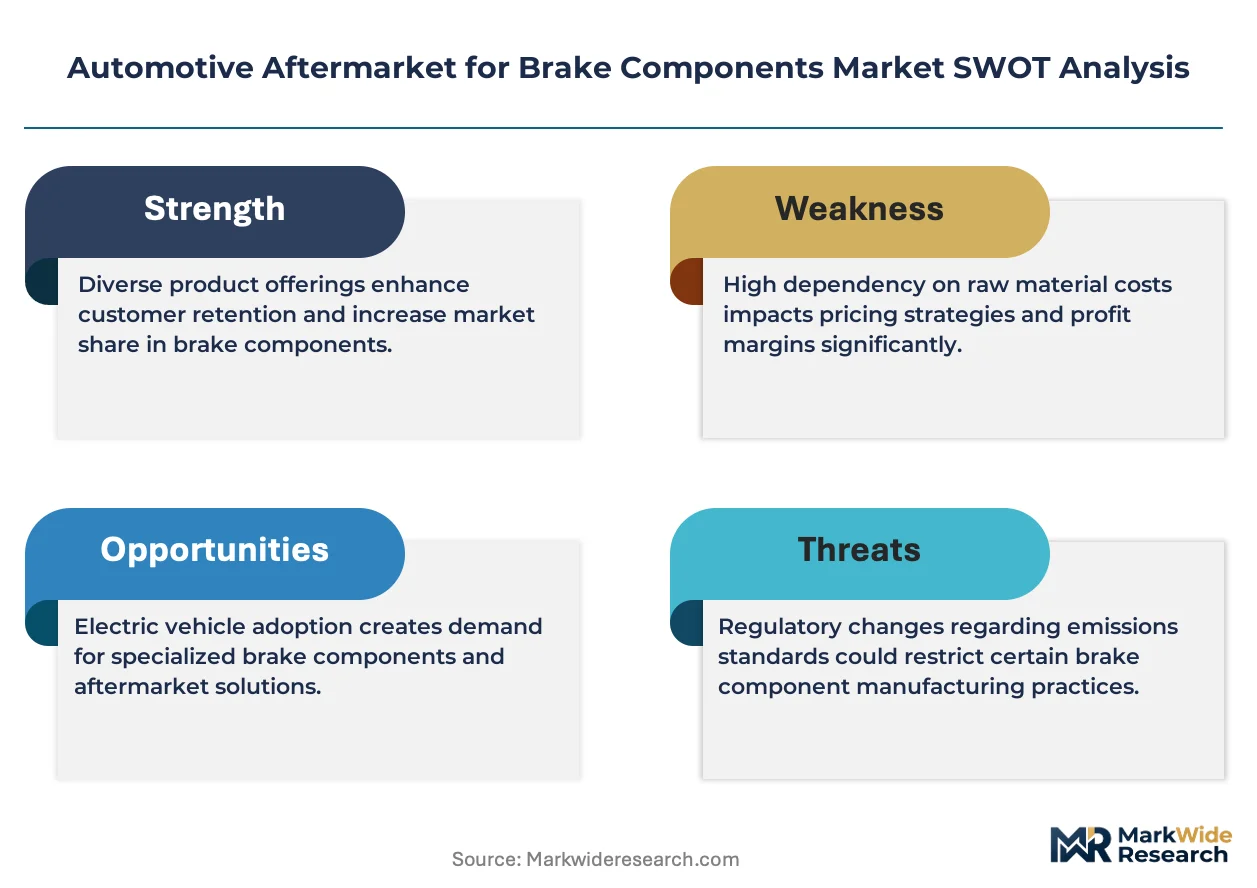
Overcapacity in China's eastern manufacturing corridor compresses margin recovery for ceramic-composite friction suppliers while simultaneously enabling aggressive pricing postures in export markets. Utilization rates below threshold levels force domestic producers to absorb copper and rare earth input volatility rather than pass through cost increases, reshaping competitive dynamics for semi-metallic pad manufacturers competing at lower specification tiers.
Pricing Analysis
Current-generation ceramic-composite formulations command substantial premiums over prior-generation semi-metallic compounds, while next-generation carbon-ceramic rotor technology remains priced at specialist tier levels inaccessible to mass-market replacement demand. Three-tier pricing structure across premium, standard, and economy levels separates ECE R90-certified suppliers from unlicensed imports and gray-market distributors. Pricing pressure stems from fleet procurement consolidation in North America, where per-mile stopping performance contracts transfer material selection risk downward through supply chains. DIY enthusiasts exhibit highest price sensitivity, sourcing through online fitment databases that transparently compare unit economics across certification grades; commercial fleets demonstrate lowest sensitivity, prioritizing extended service intervals over upfront component costs.
Supply Chain Analysis
Upstream feedstock concentration in copper mining operations across Chile and Indonesia, combined with rare earth processing dominance in China, exposes friction material producers to commodity volatility that propagates through formulation costs. Germany, China, and Italy anchor carbon-ceramic rotor manufacturing, while Japan and South Korea supply precision steel backing plates and sensor-embedded hardware. Single-source vulnerability concentrates in German carbon-ceramic machining clusters serving premium vehicle segments. Distribution runs through wholesale warehouse networks serving repair shop ecosystems, with mobile service vans emerging as last-mile disintermediation threat to traditional channel economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat opportunity where regulatory entrenchment creates durable barriers against unlicensed competition. ECE R90 homologation requirements and equivalent national standards erect compliance costs that scale entrants cannot absorb without dedicated certification infrastructure.
For Market Incumbents: Pre-empt margin erosion from unlicensed Chinese ceramic-composite imports by accelerating backward integration into copper and rare earth sourcing through offtake agreements with Chilean and Indonesian mining operations. Deepen certification moats through investment in multi-jurisdictional homologation capacity that covers ECE R90, GB 5763, and FMVSS 135 validation under unified testing protocols, compressing timeline advantages for emerging competitors.
For New Entrants and Emerging Players: Mobile installation networks in suburban US markets represent the most penetrable entry point, where digital fitment databases and van-based service models bypass wholesale distributor gatekeeping that protects incumbent parts suppliers. India's PLI scheme for auto components offers second white-space opportunity through domestic friction material plant investment serving commercial vehicle parc expansion. Go-to-market execution should prioritize direct fleet contracting relationships that disintermediate repair shop specification authority.
For Investors and Strategic Acquirers: Capital is best deployed toward homologation-certified mid-cap specialists with established ECE R90 testing relationships and sensor-embedded pad integration capabilities. Long-term viability across the projection horizon hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Watch for inflection in enforcement intensity at Chinese ports, where GB 5763 validation timeline compression for foreign suppliers would signal margin recovery for certified incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| ECE R90 Certification Acquisition | Homologation compliance filters low-grade imports and secures EU market access for established manufacturers. |
| Sensor-Embedded Pad Integration | Wear-monitoring electronics convergence with telematics platforms opens recurring revenue streams for connected brake systems. |
| Mobile Service Network Partnership | Van-based installation models capture suburban last-mile volume without fixed facility overhead burdens. |
| Ceramic-Composite Capacity Scaling | Domestic supplier investment in China's eastern corridor targets hybrid platform compatibility requirements. |
| Backward Integration into Feedstock | Copper and rare earth sourcing control mitigates margin compression from semi-metallic formulation volatility. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with aftermarket distributors, fleet procurement managers, brake component manufacturing executives, and repair shop operations heads. Secondary validation drew from NHTSA FMVSS 135 enforcement records, ECE R90 certificate registries, Chinese customs friction material trade data, and vehicle parc registration databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators to anchor volume and value estimates.
Calibration against historical replacement cycle data and fleet procurement contract structures informed growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product type friction materials, end-user procurement authority, distribution channel structure, and vehicle duty cycle classification. CAGRs were derived from replacement intensity curves, regulatory enforcement timeline assumptions, and technology substitution rates for regenerative braking compatibility. Industry-specific inputs encompassed ECE R90 certification penetration rates and mobile service network expansion metrics.
Stress conditions across copper price volatility, homologation timeline extensions, and fleet procurement consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology substitution pace. Cross-checking against IHS Markit vehicle parc data and aftermarket parts shipment records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Automotive Grade Modules Market
Automotive Components
Automotive Backing Plate Market
Automotive Components
Europe Automotive Plastics Market
Automotive Components
Brazil Automotive Composites Market
Automotive Components
Global Automotive Bumpers Market
Automotive Components
China Automotive Actuators Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Automotive Clutch Disc Market
Automotive Components
Automotive Ignition Box Market
Automotive Components
Japan Automotive Electric Actuators Market
Automotive Components
Global Automotive Brake Components Market
Automotive Components
India Automotive Heat Exchanger Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market