
 Automotive Skid Plate Market | 2026-2036
Automotive Skid Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Skid Plate Market Intelligence
Software-defined vehicle protection packages is broadening what suppliers monetize beyond physical hardware. ARB leverages its Australian engineering heritage to dominate premium off-road channels across North America and the Middle East. EVO MFG specializes in Jeep-specific platforms, anchoring its brand within a narrow but deeply loyal enthusiast segment. ICON Vehicle Dynamics controls distribution through dealer networks that bundle skid plates with suspension upgrades, extending average transaction values.
An automotive skid plate is a protective panel mounted beneath a vehicle's chassis, typically fabricated from aluminum alloys, high-strength steel, or carbon fiber composites through stamping, hydroforming, or thermoplastic molding processes, designed to shield powertrain components, fuel tanks, and differentials from impact damage during off-road traversal or debris strikes on paved surfaces. Aluminum skid plates lead volume shipments due to their strength-to-weight ratio, though carbon fiber variants command the deepest margin pools as performance SUV and electric vehicle OEMs pursue mass reduction targets. Bolt-on mounting systems capture the largest aftermarket share because enthusiasts prioritize reversible installation, while welded configurations sustain dominance in factory-fit applications where structural integration matters.
The EPA, NHTSA, and ISO 9001 quality frameworks collectively shape material selection, crashworthiness validation, and supplier qualification thresholds for chassis protection components sold into the United States market. California Air Resources Board emissions rules indirectly influence skid plate design by pressuring overall vehicle weight reduction, which favors aluminum over steel in OE programs. Stakeholders must monitor how NHTSA's evolving pedestrian safety standards might constrain underbody protrusion geometries, potentially forcing redesign cycles faster than traditional automotive tooling timelines accommodate.
Market Dynamics
Adventure tourism's geographic expansion is compressing product development cycles as aftermarket suppliers race to cover emerging trail systems and vehicle platforms before competitors lock in distribution.
Growth Catalysts
- EPA Fuel Economy Standards:Weight reduction mandates in the United States are accelerating aluminum and composite substitution for steel in factory-fit applications, expanding addressable volume for lightweight material suppliers.
- Off-Road Vehicle Registration Clusters:Rocky Mountain and Southwestern states are generating disproportionate demand concentration as trail access permits and recreation infrastructure investments concentrate enthusiast populations.
- Bolt-On Mounting Systems:Reversible installation technology is capturing aftermarket preference as weekend warriors prioritize lease-friendly modifications over permanent chassis alterations.
Market Restraints
- Aluminum Price Volatility:London Metal Exchange pricing fluctuations for primary aluminum are compressing margin predictability for stampers serving OE programs with annual price lock contracts.
- Tooling Amortization Burden:Hydroforming die costs for complex underbody geometries require 80,000+ unit production runs to break even, excluding smaller suppliers from OEM bidding pools.
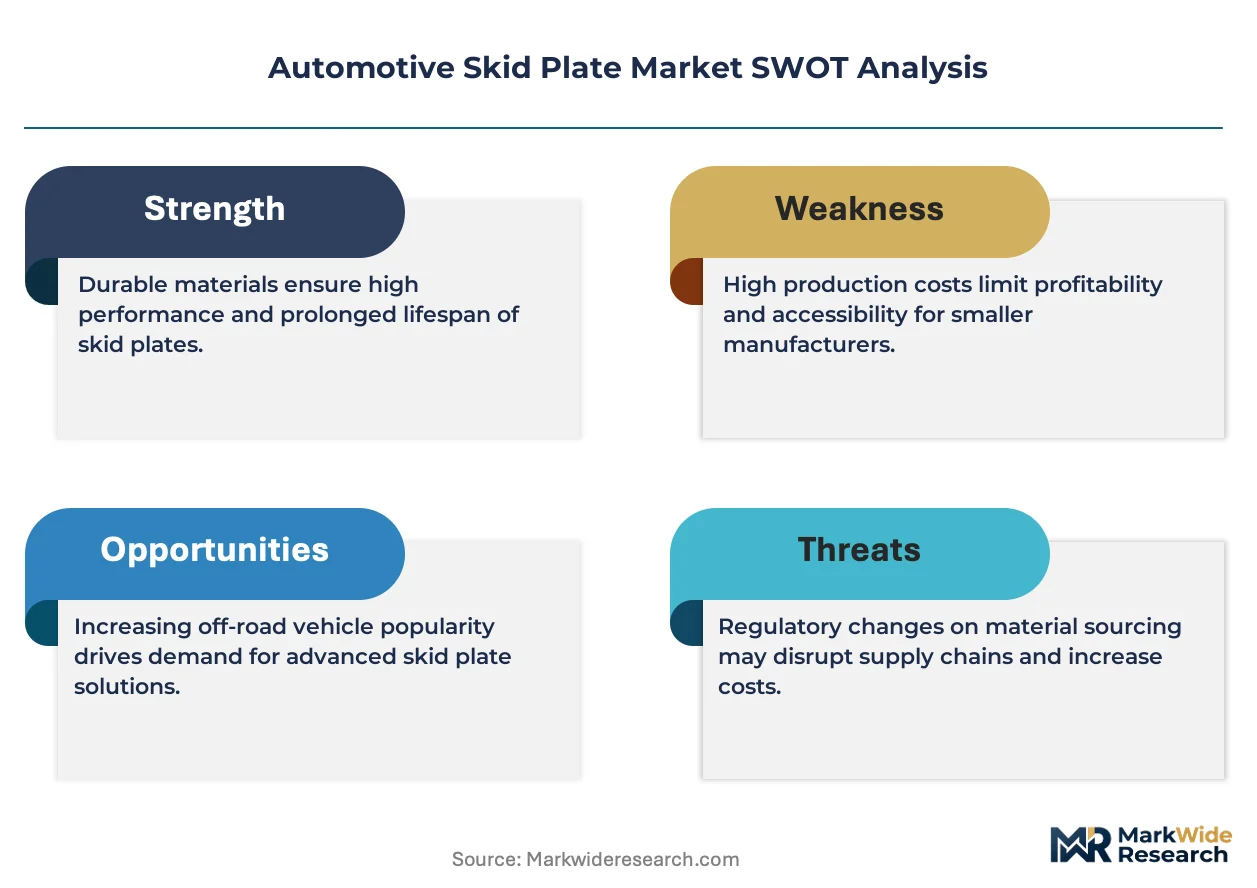
- NHTSA Pedestrian Safety Standards:Evolving underbody protrusion limits are forcing redesign cycles that outpace traditional automotive tooling timelines, straining engineering bandwidth.
Strategic Opportunities
- Electric Vehicle Underbody Protection:Battery pack shielding requirements are opening new specification categories as OEMs seek impact-resistant, thermally stable materials for high-voltage platforms.
- Software-Defined Protection Packages:Telemetry-integrated skid plates enabling impact logging and predictive maintenance are creating recurring revenue streams beyond hardware sales.
- Middle East Adventure Tourism:Desert safari operators in the UAE and Saudi Arabia are professionalizing fleet specifications, creating demand for corrosion-resistant premium products.
Industry Challenges
- Composite Repair Technician Shortage:Carbon fiber damage assessment and field repair capabilities remain scarce outside motorsport service networks, limiting warranty coverage options.
- ISO 9001 Supplier Qualification:Tier-1 OEM onboarding timelines stretching 18-24 months are freezing out agile aftermarket specialists from factory-fit expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Skid Plate Market |
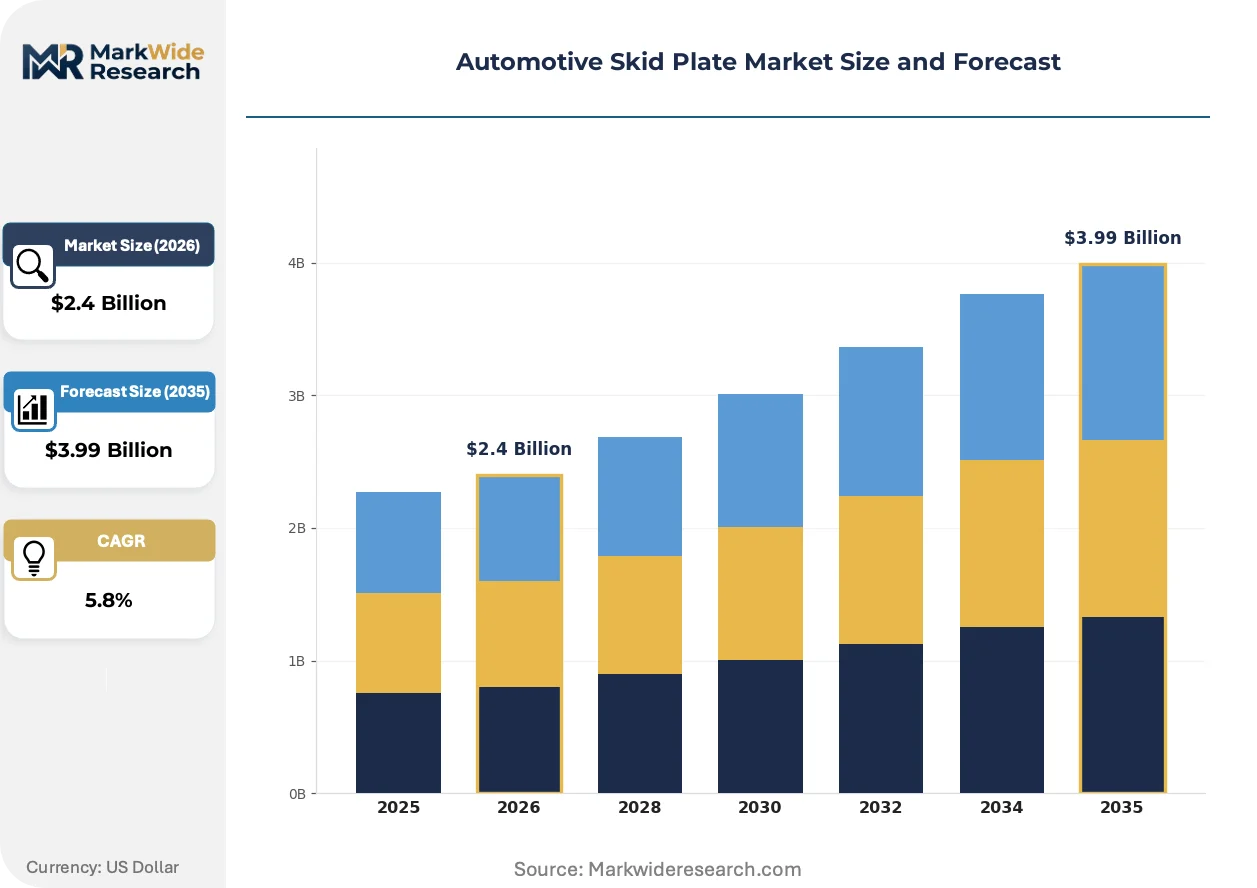
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum, Steel, Carbon Fiber, Plastic, Titanium Vehicle Type: Passenger Cars, SUVs, Pickup Trucks, Crossovers, Electric Vehicles Mounting Type: Bolt-On, Welded, Clamped, Adhesive, Magnetic End User: Aftermarket Retailers, Vehicle Manufacturers, Off-Road Enthusiasts, Fleet Operators |
| Companies Covered | EVO MFG, JCROFFROAD INC., ARB, Setina Manufacturing Inc., ICON Vehicle Dynamics, ARTEC INDUSTRIES LLC, Clayton Offroad, Fabtech, All Pro Off Road, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Skid Plate Market Strategic Shifts & Innovations
Physical-digital convergence is redefining what chassis protection encompasses, with sensor integration and predictive capabilities becoming as critical as impact resistance in buyer evaluations.
Multi-material hybrid construction is modularizing skid plate architecture. Tier-1 suppliers are bonding aluminum impact faces to polymer energy-absorbing cores, achieving localized stiffness without chassis-wide weight penalties. Electric vehicle OEMs are adopting this approach fastest, using the technology to protect battery enclosures while preserving range targets.
California Air Resources Board emissions rules are indirectly reshaping material selection. Vehicle weight reduction pressures are favoring aluminum over steel in OE programs, even where raw material costs exceed traditional alternatives. Suppliers serving California-registered fleets are responding by qualifying lighter gauge alloys with enhanced surface hardening treatments.
Direct-to-consumer configuration tools are fragmenting traditional distribution. Enthusiasts now specify vehicle-year-make-model combinations online, receiving laser-cut plate kits shipped to home garages. This pattern is most visible in the United States, where weekend modification culture and two-day delivery infrastructure compress purchase-to-installation timelines below traditional retail channels.
Automotive Skid Plate Market Segmentation
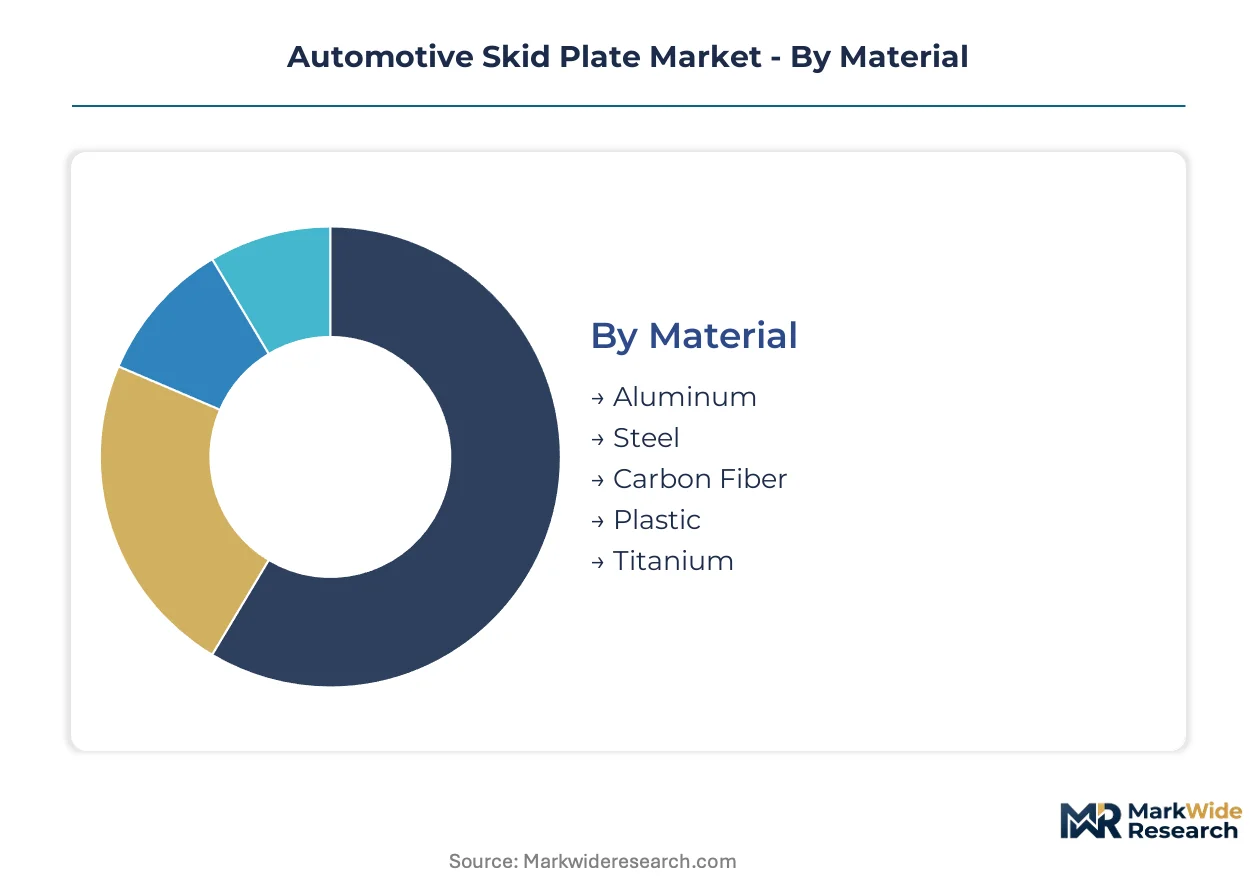
Skid plate procurement patterns diverge sharply across material grades, vehicle architectures, and installation methods. Suppliers must align production footprints with these fault lines to capture margin pools concentrated in lightweight OE programs and reversible aftermarket configurations.
Material:
Aluminum and carbon fiber anchor premium factory-fit programs, while steel and plastics sustain cost-sensitive volume tiers.
- Aluminum:Heat-treatable 5xxx and 6xxx series alloys deliver optimal strength-to-weight ratios for OEM underbody protection. Rocky Mountain and Southwestern United States states generate disproportionate demand as EPA fuel economy standards accelerate substitution away from steel in light truck platforms.
- Carbon Fiber:Thermoset prepregs and RTM-processed composites command the deepest margin pools in performance SUV and electric vehicle applications. Mass reduction targets from California Air Resources Board emissions rules favor this segment despite raw material premiums.
- Steel:High-strength low-alloy grades retain dominance in heavy-duty pickup and commercial fleet specifications where impact resistance outweighs weight penalties.
- Plastic:Glass-reinforced nylon and polypropylene compounds serve entry-level passenger car applications with minimal off-road exposure.
- Titanium:Aerospace-grade Ti-6Al-4V finds limited adoption in motorsport and ultra-premium desert racing platforms where cost tolerance is highest.
Most installed capacity flows through aluminum. Expansion is steepest in carbon fiber.
Vehicle Type:
Platform electrification and adventure tourism are redrawing volume concentration across body styles.
- Pickup Trucks:Full-size and mid-size truck architectures generate the largest absolute unit demand. Southwestern United States registration clusters and commercial fleet refresh cycles sustain factory-fit procurement at scale.
- SUVs:Body-on-frame and unibody sport-utility vehicles split demand between trail-rated off-road variants and urban-focused crossovers. Battery electric SUV launches are opening new specification categories for thermally stable underbody shielding.
- Passenger Cars:Sedan and hatchback applications concentrate in debris protection for paved surface operation, with minimal off-road specification.
- Crossovers:Car-based utility platforms prioritize aerodynamic underbody panels over structural impact protection.
- Electric Vehicles:Dedicated BEV architectures require battery enclosure shielding against road debris and thermal runaway containment. NHTSA safety mandates and OEM range targets are accelerating material qualification timelines.
Pickup trucks absorb the highest absolute volume. Electric vehicles are climbing the fastest.
Mounting Type:
Reversibility and structural integration define the trade-off spectrum between aftermarket and factory-fit channels.
- Bolt-On:Threaded fastener systems with captured nut plates enable installation without chassis modification. Weekend enthusiasts in the United States lease market prioritize this configuration for its reversibility.
- Welded:Factory-integrated attachment points and seam welding deliver structural continuity for OE programs where crashworthiness validation is mandatory.
- Clamped:Frame-rail and subframe clamping systems serve commercial fleet upfitters requiring rapid configuration changes across mixed vehicle pools.
- Adhesive:Structural bonding tapes and epoxy systems find niche adoption in carbon fiber applications where drilling compromises material integrity.
- Magnetic:Rare-earth magnet arrays enable temporary protection for low-speed trail sections, with limited permanent installation uptake.
Bolt-on systems dominate aftermarket revenue. Welded configurations lock in factory-fit relationships.
End User:
Channel structure fragments between professional procurement and enthusiast self-installation.
- Vehicle Manufacturers:Tier-1 supply agreements with stamped aluminum and hydroformed steel producers sustain high-volume production. NHTSA safety mandates and ISO 9001 qualification thresholds constrain supplier pools.
- Aftermarket Retailers:Specialty off-road distributors and direct-to-consumer platforms capture enthusiast demand with vehicle-specific fitment databases and rapid fulfillment infrastructure.
- Off-Road Enthusiasts:Weekend trail users and overland expedition communities drive specification toward modular, reversible systems with visual customization options.
- Fleet Operators:Commercial and government vehicle pools prioritize total cost of ownership, warranty coverage, and standardized maintenance protocols across multi-vehicle deployments.
Vehicle manufacturers command the largest contract values. Aftermarket retailers are gaining share fastest through digital configuration tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates deeper specification diversity than Germany, where OEM factory-fit programs dominate procurement patterns. Adventure tourism infrastructure and off-road vehicle registration clusters concentrate demand in distinct geographic pockets across both markets.
United States
Rocky Mountain and Southwestern states sustain the highest off-road vehicle registration rates nationally. The EPA's fuel economy standards and NHTSA safety mandates accelerate aluminum substitution in factory-fit programs. Denver and Phoenix metropolitan areas anchor aftermarket distribution networks serving weekend enthusiast communities.
Germany
Performance SUV and electric vehicle OEMs drive specification for carbon fiber and multi-material hybrid constructions. The KBA enforces pedestrian safety standards that constrain underbody protrusion geometries. Stuttgart and Munich industrial corridors concentrate Tier-1 supplier engineering capabilities for lightweight chassis protection.
Australia
Desert racing and remote-area touring cultures sustain demand for premium off-road protection systems. Australian Design Rules govern crashworthiness and pedestrian safety compliance for aftermarket fitment. ARB leverages Melbourne-based engineering heritage to supply Middle Eastern and North American export markets.
United Arab Emirates
Desert safari fleet operators professionalize specifications for corrosion-resistant premium products. The country's national automotive regulator enforces safety standards for commercial vehicle upfitting. Dubai and Abu Dhabi serve as regional distribution hubs for Middle East adventure tourism infrastructure.
China
Domestic electric vehicle OEMs open new specification categories for battery enclosure shielding. MIIT vehicle safety standards and GB standards shape material qualification timelines. Yangtze River Delta manufacturing clusters scale aluminum stamping capacity for export and domestic OEM programs.
Automotive Skid Plate Market Key Industry Players
Top-tier vendors anchor factory-fit supply relationships with major OEMs, while mid-tier fabricators compete through aftermarket specialization and rapid vehicle-platform coverage. The vendor base stratifies across three tiers: multinational Tier-1 suppliers with ISO 9001 qualification, regional specialists serving enthusiast distribution channels, and direct-to-consumer configurators leveraging digital fitment tools. Strategic archetypes include heritage engineering brands, platform-specific specialists, and vertically integrated suspension bundlers. Competitive moves concentrate on geographic expansion into Middle East adventure tourism markets and portfolio diversification into electric vehicle battery protection categories.
Among Australian-heritage engineering specialists, ARB occupies a position exemplifying premium off-road channel dominance across export markets. Within the platform-specific tier, EVO MFG and JCROFFROAD INC. represent specialists anchoring brand loyalty within narrow but deeply committed enthusiast segments. At the bundled-solution end, ICON Vehicle Dynamics exemplifies distributors controlling transaction value through suspension-upgrade packaging. Clayton Offroad and Fabtech sit within the mid-tier fabricator archetype competing on rapid platform coverage and reversible installation technology.
| Leading Market Players |
|---|
| EVO MFG |
| JCROFFROAD INC. |
| ARB |
| Setina Manufacturing Inc. |
| ICON Vehicle Dynamics |
| ARTEC INDUSTRIES LLC |
| Clayton Offroad |
| Fabtech |
| All Pro Off Road |
| Others |
Cost & Logistics Intelligence
Tier-1 OEM procurement teams concentrate factory-fit contract awards among stampers with NHTSA validation and ISO 9001 certification, creating a pricing model where qualification barriers sustain premium capture for qualified suppliers while aftermarket channels fragment toward transactional spot purchasing.
Pricing Analysis
Capacity additions in China's Yangtze River Delta aluminum stamping corridors are reshaping price floors for heat-treatable 5xxx and 6xxx series alloys. Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber composite systems from aluminum bolt-on kits from steel welded configurations. Price differentiation stems from NHTSA crashworthiness certification tier and volume scale commitments in annual offtake contracts. Cost compression in standard-grade aluminum stampings is intensifying because London Metal Exchange volatility transfers downstream through annual price lock mechanisms. Fleet operators exhibit highest price sensitivity due to total cost of ownership calculations, while desert safari operators in the UAE demonstrate lowest sensitivity for corrosion-resistant premium specifications.
Supply Chain Analysis
Primary aluminum supply rests on Chinese smelting capacity, Australian bauxite extraction, and Canadian hydro-powered refining. Carbon fiber prepreg feedstock draws from Japanese specialty chemical producers and German textile weaving operations. High-strength steel alloys source from German and South Korean integrated mills. Single-source vulnerability concentrates in aerospace-grade Ti-6Al-4V titanium sponge processing. Distribution runs through Tier-1 supplier direct OEM contracts, specialty off-road distributor networks, and direct-to-consumer laser-cut kit platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive skid plate market functions as a stable compounder where EPA fuel economy standards and NHTSA safety mandates perpetuate material substitution cycles that sustain supplier revenue visibility across vehicle refresh programs.
For Market Incumbents: Hedge aluminum price exposure through long-term LME hedging instruments and backward integration into recycled alloy sourcing. Defend factory-fit relationships by accelerating multi-material hybrid qualification timelines ahead of NHTSA pedestrian safety standard revisions. Prioritize ISO 9001 certification maintenance as Tier-1 OEM onboarding timelines stretch to 24 months.
For New Entrants and Emerging Players: The gap between ARB-level premium positioning and entry-level steel stampings creates white-space for mid-tier aluminum specialists. Target electric vehicle battery enclosure shielding specifications where OEMs lack incumbent supplier relationships. Penetrate direct-to-consumer configuration tools with vehicle-year-make-model fitment databases and two-day fulfillment infrastructure.
For Investors and Strategic Acquirers: Suspension system integrators are the most active acquirer in this space, seeking bundling opportunities that extend average transaction values. Five-to-ten year viability rests on electric vehicle platform coverage and software-defined protection package development. Watch NHTSA pedestrian safety standard finalization timing as inflection indicator for redesign cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Material Hybrid Qualification | Bonding aluminum impact faces to polymer cores satisfies EPA weight targets for electric SUV programs. |
| Software-Defined Protection Integration | Telemetry-enabled impact logging creates recurring revenue beyond hardware for OEM service contracts. |
| Middle East Distribution Expansion | Dubai and Abu Dhabi hubs capture professionalized fleet specifications from desert safari operators. |
| Direct-to-Consumer Configuration Launch | Laser-cut kit platforms compress purchase-to-installation timelines below traditional retail channels. |
| Recycled Aluminum Supply Integration | Captive secondary alloy sourcing hedges London Metal Exchange volatility in annual OEM contracts. |
Research Approach
Direct dialogue with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributor category managers, and off-road enthusiast community leaders grounded qualitative findings. Secondary validation drew from NHTSA safety filings, EPA fuel economy compliance databases, vehicle production registries, and London Metal Exchange pricing archives. Bottom-up build from material-grade shipment volumes and top-down cross-check against OEM program awards enabled triangulation.
Bottom-up modeling segmented the market across material type, vehicle architecture, mounting configuration, and end-user channel. Top-down validation assessed macro-level aluminum consumption patterns and off-road vehicle registration clusters in Rocky Mountain and Southwestern states. CAGRs were derived from production volume trajectories and content-per-vehicle assumptions across the projection horizon. Key inputs included electric vehicle battery pack shielding specifications and adventure tourism infrastructure investment flows.
Caveats apply where NHTSA pedestrian safety standard finalization, aluminum price volatility spikes, or electric vehicle platform delays could materially shift the outlook. Forecasts reflect assumptions about regulatory timelines, material substitution elasticities, and aftermarket channel migration rates. A small set of triggers—NHTSA rulemaking, LME pricing regimes, and BEV launch schedules—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Brake Tube Market
Automotive Components
Global Automotive Collapsible Steering Column Market
Automotive Components
South Korea Automotive Sunroof Market
Automotive Components
Automotive Clutch Disc Market
Automotive Components
India Automotive Heat Exchanger Market
Automotive Components
Turkey Automotive Plastic Compounding Market
Automotive Components
Automotive Bushing Market
Automotive Components
Automotive Key Market
Automotive Components
Automotive Metal Casting Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Automotive Push Rods Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Automotive V-Belts Market
Automotive Components
Automotive Stainless Steel Tubes Market
Automotive Components
Global Automotive Plastic Compounding Market
Automotive Components
Automotive Dynamic Spotlight Market