
 Automotive Exhaust Manifolds Market | 2026-2036
Automotive Exhaust Manifolds Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Exhaust Manifolds Market Analytics
OEM procurement concentration is pivoting toward integrated exhaust system suppliers capable of delivering manifold-converter assemblies as single modules. Tenneco leverages its emissions control integration capabilities to anchor long-term platform contracts with North American truck manufacturers. Faurecia sustains competitive positioning through captive hot-end engineering centers in France and Poland that specialize in thin-wall stainless steel forming.
An automotive exhaust manifold is a branched tubular component, typically cast from nodular iron or fabricated from austenitic stainless steel grades such as 309 or 321, that collects combustion gases from multiple engine cylinders and channels them into a single outlet for downstream aftertreatment. Its primary function is to optimize exhaust pulse timing, preserve thermal energy for catalytic light-off, and withstand cyclic thermal loads exceeding 900°C in turbocharged applications. Stainless steel manifolds command the premium tier due to weight reduction potential and corrosion resistance under lean-burn conditions, while cast iron retains cost-sensitive volume in heavy-duty truck segments where thermal mass stabilizes converter temperatures. Passenger vehicle applications dominate absolute unit demand, though commercial vehicle installations generate higher per-unit value through multi-turbo configurations and integrated EGR routing.
EPA emission certification protocols and Euro 7 proposals from the European Commission are tightening allowable cold-start hydrocarbon limits, which forces manifold designers to position catalyst substrates closer to the exhaust port. NHTSA fuel economy standards in the United States create parallel pressure to reduce manifold wall thickness and eliminate heat shields through improved material grades. Stakeholders must monitor regulatory divergence between California Air Resources Board pathways and federal EPA timelines, as dual compliance strategies will determine tooling amortization and platform commonization decisions.
Market Dynamics
Powertrain electrification timelines are fragmenting demand trajectories across OEM portfolios, forcing manifold suppliers to engineer dual-capacity tooling that serves both thermal engine platforms and range-extender hybrid architectures without full asset redundancy.
Growth Catalysts
- Euro 7 emission readiness:European Commission proposals mandate closer catalyst positioning to exhaust ports, accelerating integrated manifold-converter module adoption across passenger vehicle platforms.
- Stainless steel forming advances:Thin-wall austenitic grades enable 30-40% weight reduction over cast iron, satisfying NHTSA fuel economy standards while preserving thermal durability for turbocharged light trucks.
- Mexico manufacturing clustering:Powertrain export concentration around Puebla and Guanajuato generates localized procurement pull for tiered supplier networks serving North American OEM assembly plants.
Market Restraints
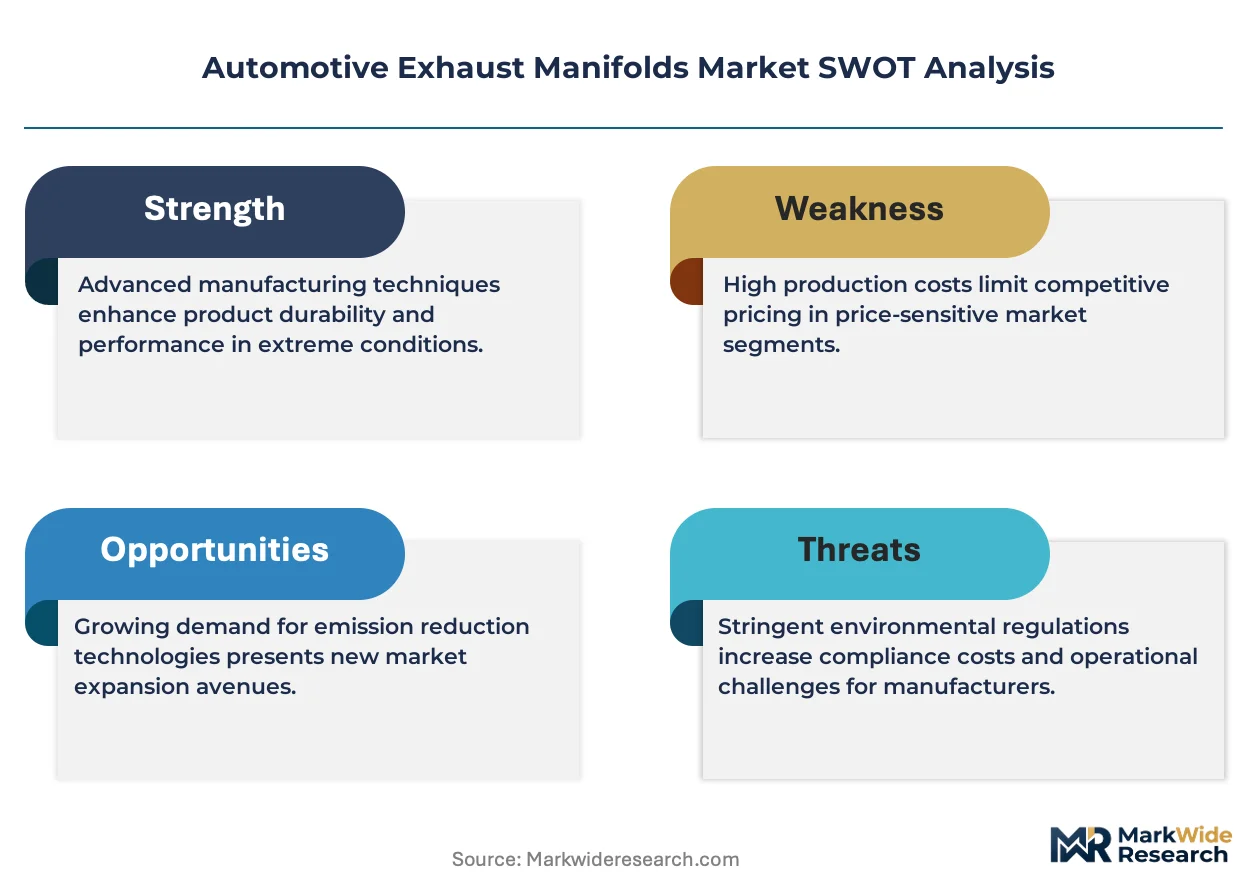
- Nickel price volatility:Austenitic stainless grades 309 and 321 depend on nickel content exceeding 12%, exposing margin compression when London Metal Exchange pricing spikes.
- Foundry capacity concentration:Nodular iron casting for heavy-duty manifolds clusters in legacy industrial regions with aging furnace infrastructure and limited greenfield investment.
- Thermal mass tradeoffs:Thin-wall stainless designs sacrifice heat retention that stabilizes catalytic converter temperatures during transient load cycles, limiting application in certain commercial vehicle duty profiles.
Strategic Opportunities
- India commercial vehicle expansion:Bharat Stage VI Phase II implementation creates demand for integrated EGR manifolds in medium-duty truck segments where domestic casting capacity remains underdeveloped.
- Additive manufacturing convergence:Hybrid production combining laser powder bed fusion for complex runner geometries with conventional forming for flange structures reduces prototype-to-production lead times.
- Direct-to-fleet aftermarket channels:Commercial vehicle fleet operators bypass traditional distribution tiers through digital procurement platforms, enabling margin capture previously absorbed by wholesale intermediaries.
Industry Challenges
- Dual-path compliance engineering:Divergent California Air Resources Board and federal EPA certification timelines force parallel validation programs that strain engineering bandwidth and tooling amortization schedules.
- Thermo-mechanical fatigue simulation:Predictive modeling of cyclic thermal loads exceeding 900°C requires specialized computational fluid dynamics expertise scarce among mid-tier design houses.
- Platform commonization tension:OEM demands for component standardization across engine families conflict with manifold designs optimized for specific cylinder head port geometries and firing orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Exhaust Manifolds Market |
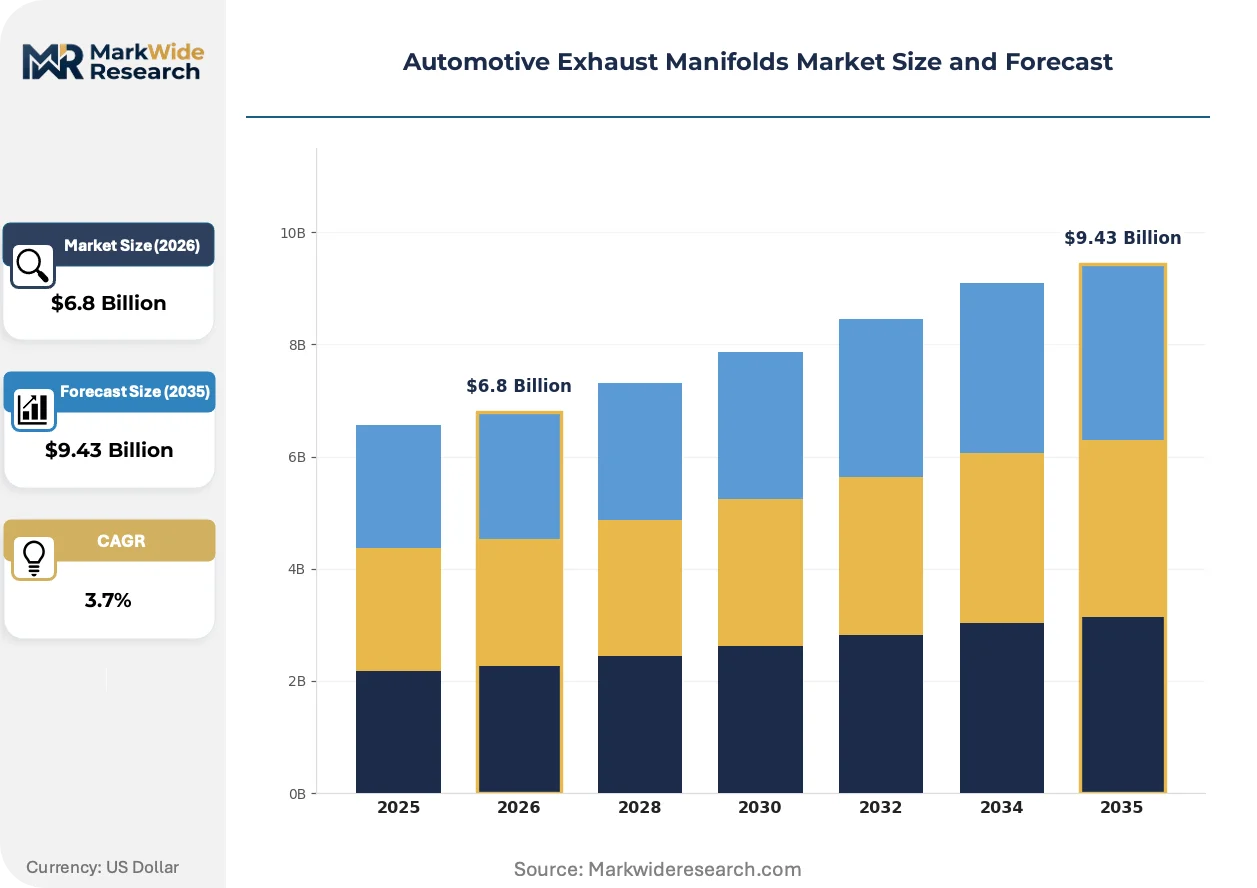
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.43 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Iron, Stainless Steel, Aluminum, Composite End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles Installation Type: On-road, Off-road, Racing, Industrial |
| Companies Covered | Faurecia, Tenneco, Eberspächer, Benteler, Futaba Industrial, Boysen, Yutaka Giken, Katcon, Bosal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Exhaust Manifolds Market Evolving Landscape
Material science breakthroughs and regulatory proximity mandates are compressing the traditional boundary between exhaust manifolds and aftertreatment hardware, creating integrated thermal modules that redefine supplier value capture.
Thin-wall stainless steel hydroforming is decentralizing production economics previously dominated by high-volume sand casting operations. Tier 2 suppliers in Poland and the Czech Republic now compete for platform contracts using robotic tube manipulation cells that slash minimum efficient scale thresholds. This capability dispersion enables regional sourcing for low-volume performance variants without dedicated foundry investment.
EPA emission certification protocols are tightening cold-start hydrocarbon limits through test-cycle modifications that penalize distant catalyst placement. Manifold designers respond with bifurcated runner architectures that split exhaust flow between close-coupled and underfloor converter positions. Heavy-duty diesel applications face the steepest redesign burden due to larger thermal mass requirements and longer light-off intervals.
Fleet procurement teams now specify total cost of ownership metrics that internalize fuel consumption, maintenance intervals, and residual value rather than upfront component pricing. This recalibration favors stainless steel manifolds with corrosion warranties extending to 10 years or 500,000 miles in North American long-haul trucking. OEM sales organizations restructure incentive programs to align dealer compensation with lifecycle performance rather than transaction margin alone.
Automotive Exhaust Manifolds Market Segmentation
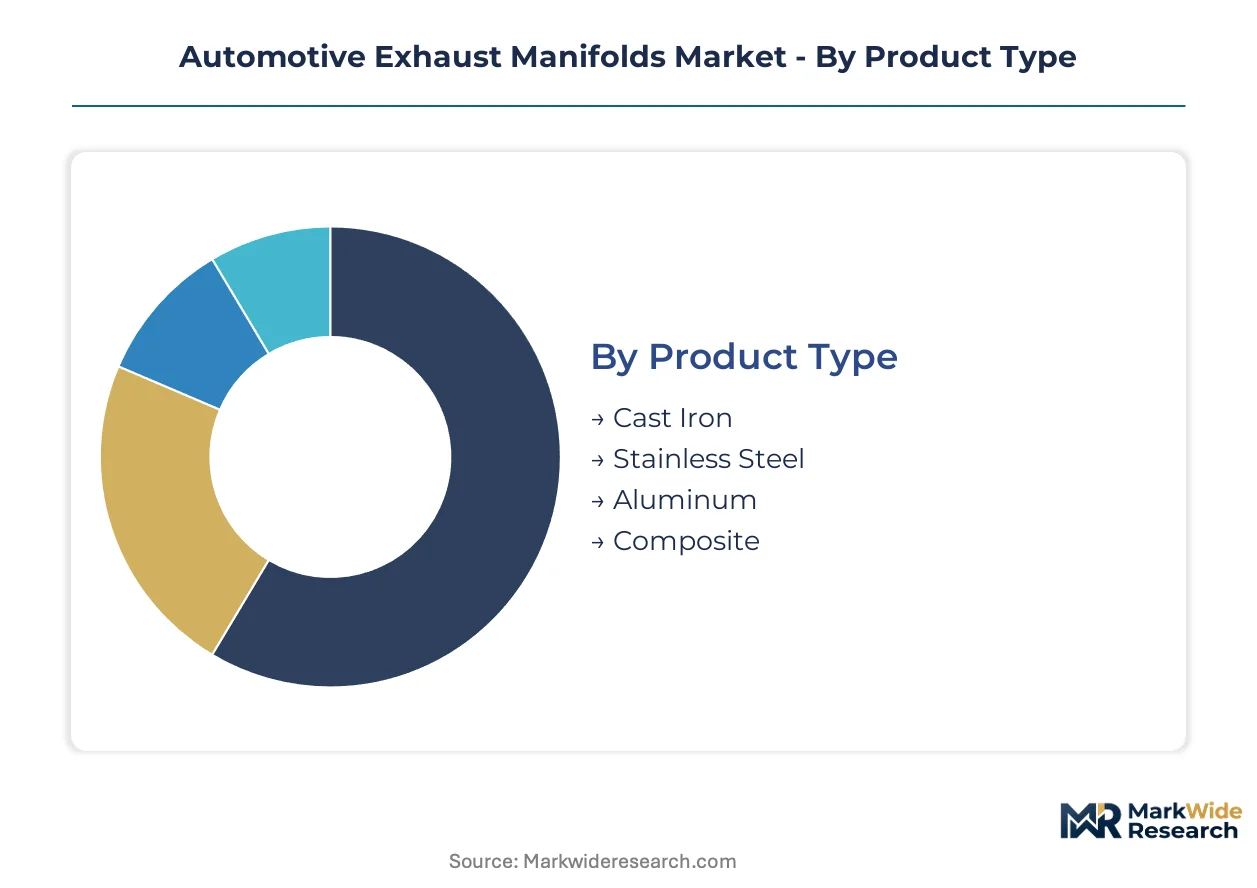
Exhaust manifold procurement patterns diverge sharply across material grades and installation contexts, with upgrade cycles and replacement intervals determining supplier contract structures. Platform standardization pressures collide with thermal performance requirements to create distinct segment economics.
Product Type:
Replacement-cycle timing and thermal durability requirements segment procurement volumes across material categories, with fleet operators weighing warranty length against upfront capital outlay.
- Cast Iron:Nodular iron grades with ferritic microstructures withstand thermal cycling above 800°C in heavy-duty diesel configurations. Demand concentrates in North American long-haul trucking where thermal mass stabilizes converter temperatures during grade climbs; foundry capacity constraints in legacy industrial regions limit supply elasticity.
- Stainless Steel:Austenitic grades 309 and 321 enable wall thickness reductions below 2mm, cutting per-unit weight by 30-40% versus cast alternatives. Procurement accelerates in European passenger vehicle platforms where Euro 7 proximity mandates favor thin-wall designs with integrated catalytic substrates.
- Aluminum:Cast aluminum-silicon alloys serve low-temperature applications in motorcycle and small displacement engines where thermal loads remain below 450°C.
- Composite:Ceramic matrix and polymer-derived ceramic formulations address prototype racing applications and limited-series performance vehicles.
Volume placements concentrate in Cast Iron; the faster expansion belongs to Stainless Steel.
End User:
Customer-type economics separate captive production decisions from merchant market procurement, with warranty liability allocation determining contract terms.
- OEMs:Vehicle manufacturers source manifold-converter modules through single-source platform contracts spanning 5-7 year production cycles. Specifications tighten as EPA cold-start hydrocarbon limits force closer catalyst positioning to exhaust ports.
- Aftermarket Providers:Independent distributors and service chains stock replacement manifolds for vehicles outside warranty coverage. Demand clusters in corrosion-prone coastal regions and salt-belt states where stainless steel upgrades command price premiums.
- Tier-1 Suppliers:Integrated exhaust system specialists deliver manifold-catalytic converter assemblies to OEM assembly plants, absorbing design validation costs in exchange for long-term volume commitments.
- Vehicle Assemblers:Contract manufacturers and kit assembly operations procure manifolds for low-volume specialty builds and export market variants.
Contract value pools deepest at OEMs; aftermarket channels are climbing the fastest.
Application:
Duty-cycle severity and engine displacement segment design requirements, with per-unit value scaling with thermal load and emissions control complexity.
- Passenger Vehicles:Four-cylinder and V6 configurations dominate absolute unit demand. Integrated manifold-turbocharger housings consolidate components to meet NHTSA fuel economy standards through packaging efficiency.
- Commercial Vehicles:Medium-duty trucks and delivery vans require EGR-integrated manifolds with dedicated coolant passages. Specifications diverge between urban stop-start duty and highway cruise profiles.
- Heavy-Duty Trucks:Multi-turbo diesel configurations with dual exhaust paths generate the highest per-unit value in the market. Fleet procurement teams specify 10-year corrosion warranties that internalize lifecycle cost.
- Motorcycles:Compact single and twin-cylinder applications prioritize weight minimization over thermal retention, with stainless steel headers replacing chromed steel in premium segments.
Unit volumes peak in Passenger Vehicles; value expansion is steepest in Heavy-Duty Trucks.
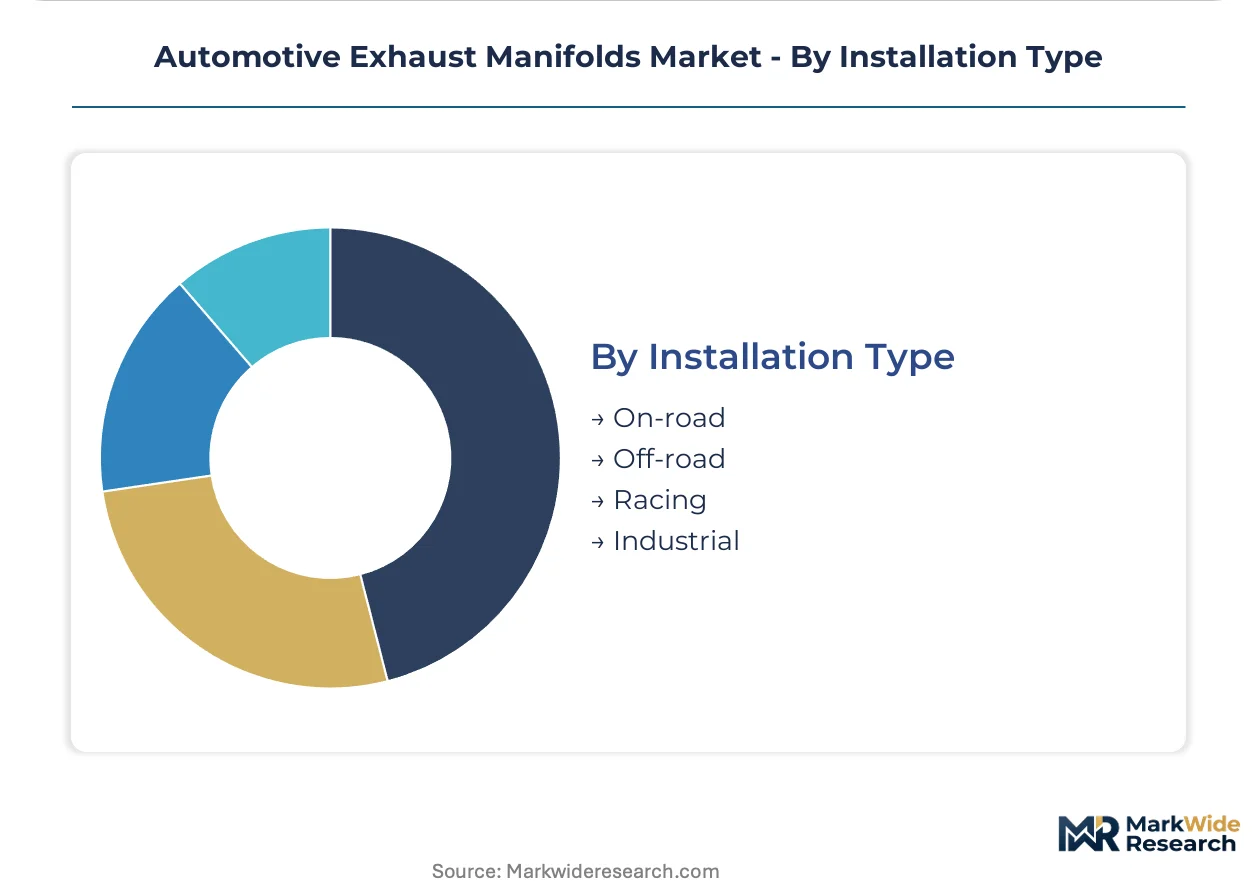
Installation Type:
Operating environment severity separates on-road compliance requirements from off-road durability specifications, with certification pathways diverging accordingly.
- On-road:EPA and CARB certification protocols govern manifold designs for street-legal vehicles. Cold-start emission test cycles penalize distant catalyst placement, favoring compact integrated modules.
- Off-road:Construction and agricultural equipment operate under less stringent emission tiers but face severe thermal shock from intermittent high-load operation. Cast iron retains dominance for thermal mass retention.
- Racing:Competition exhaust systems prioritize flow optimization over emission compliance, with Inconel and titanium alloys replacing steel in professional motorsport.
- Industrial:Stationary engines and generator sets employ heavy-wall cast manifolds with extended service intervals measured in operating hours rather than mileage.
Production volumes cluster in On-road; specification complexity expands most quickly in Off-road as Stage V compliance tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in manufacturing clusters serving powertrain export hubs, with regulatory divergence between EPA and Euro 7 timelines forcing parallel engineering programs across jurisdictions.
United States
NHTSA fuel economy standards drive stainless steel adoption in light trucks, with thin-wall designs replacing cast iron in turbocharged configurations. EPA cold-start hydrocarbon test cycles penalize distant catalyst placement. Detroit-area suppliers anchor production for domestic OEM assembly networks.
Germany
Euro 7 emission readiness programs accelerate integrated manifold-converter module development for premium passenger vehicle platforms. KBA certification protocols mandate closer exhaust port positioning for catalyst substrates. Engineering centers in Stuttgart and Munich specialize in austenitic stainless forming for thermal durability.
China
Domestic OEM procurement expands for medium-duty commercial vehicles as MIIT emission tiers tighten. Dual carbon goals under national climate policy favor lightweight stainless designs over nodular iron in new platform development. Yangtze River Delta foundries and fabricators cluster around Shanghai automotive assembly corridors.
Mexico
Powertrain export manufacturing concentrates around Puebla and Guanajuato, generating localized tiered supplier networks for North American OEM plants. NAFTA-origin content rules govern procurement decisions for cross-border assembly. Querétaro and Aguascalientes host stainless steel forming operations serving light commercial vehicle programs.
Japan
Hybrid powertrain architectures sustain demand for range-extender optimized manifolds with rapid thermal response characteristics. METI carbon neutrality roadmaps pressure material efficiency in small-displacement engine applications. Aichi Prefecture suppliers integrate exhaust hardware with turbocharger housings for platform consolidation.
Automotive Exhaust Manifolds Market Competitive Landscape
European producers anchor the integrated emissions control tier; Asian specialists hold forming and fabrication capabilities. Market structure shows moderate consolidation around full-system suppliers capable of manifold-converter module delivery, with mid-tier fabricators competing on regional sourcing proximity. Three archetypes dominate: vertically integrated exhaust system integrators, captive hot-end engineering subsidiaries, and independent metalforming specialists. Competitive moves center on dual-path compliance engineering for divergent regulatory timelines and capacity expansion near OEM assembly clusters.
Among European-based system integrators, Faurecia and Tenneco exemplify the integrated emissions control archetype, occupying positions that span hot-end engineering through aftertreatment module assembly. Eberspächer represents the specialist tier focused on thermal management solutions. These anchors demonstrate how supplier value capture shifts toward integrated module delivery as regulatory proximity mandates compress the boundary between manifold and catalyst hardware.
| Leading Market Players |
|---|
| Faurecia |
| Tenneco |
| Eberspächer |
| Benteler |
| Futaba Industrial |
| Boysen |
| Yutaka Giken |
| Katcon |
| Bosal |
| Others |
Value Network & Pricing Analysis
Captive hot-end engineering centers anchor supplier pricing power by internalizing thin-wall stainless steel forming expertise that OEMs cannot easily replicate. This integration choice concentrates value capture with Faurecia in France and Poland while forcing tier-2 fabricators to compete on regional proximity rather than technical differentiation.
Pricing Analysis
Volume placements concentrate in cast iron manifolds for heavy-duty trucks; margins expand fastest in stainless steel integrated modules for Euro 7-compliant passenger vehicles. Price differentiation rests on thermal performance certification and wall-thickness grade, with OEM platform contracts absorbing design validation costs in exchange for long-term commitments. Cost compression in nodular iron casting is intensifying because foundry capacity constraints in legacy industrial regions limit supply elasticity. Fleet operators show the least price sensitivity, internalizing total cost of ownership across 500,000-mile service intervals.
Supply Chain Analysis
Workforce availability for precision tube manipulation in Poland and the Czech Republic enables tier-2 suppliers to compete for platform contracts using robotic forming cells. Raw material sourcing draws from nickel-dependent austenitic grades 309 and 321, nodular iron feedstock, and catalytic substrate ceramics. Single-source vulnerability concentrates in London Metal Exchange nickel pricing spikes that compress margins unpredictably. Distribution runs through integrated exhaust system suppliers delivering manifold-converter assemblies directly to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-wall stainless steel hydroforming is displacing sand casting as the dominant production technology, compressing minimum efficient scale thresholds and fragmenting competitive positioning across regional fabricators.
For Market Incumbents: To counter tier-2 robotic forming cells in Eastern Europe, Tenneco should expand captive hot-end engineering capacity in Guanajuato to anchor North American platform contracts. Backward integration into nickel alloy sourcing would buffer margin compression from London Metal Exchange volatility. For New Entrants and Emerging Players: Euro 7 in the European Union opens a window for specialized thin-wall forming operations serving premium passenger vehicle platforms where incumbent capacity is committed to legacy truck programs. Bharat Stage VI Phase II in India presents the most penetrable regulatory tailwind for EGR-integrated manifold supply where domestic casting capacity remains underdeveloped. A direct-to-fleet digital procurement channel would bypass wholesale intermediaries and capture aftermarket margin. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated emissions control conglomerates seeking regional forming capabilities. Long-term viability hinges on dual-path compliance engineering bandwidth for divergent EPA and CARB timelines. The signal to watch is tooling amortization schedules straining under parallel validation programs.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Path Compliance Engineering | Parallel EPA and CARB validation programs protect platform contract eligibility across regulatory jurisdictions. |
| Regional Forming Capacity Expansion | Robotic tube manipulation cells in Querétaro reduce logistics costs for Puebla powertrain export clusters. |
| Integrated Manifold-Converter Module Development | Close-coupled catalyst positioning satisfies Euro 7 proximity mandates while consolidating supplier value capture. |
| Nickel Alloy Supply Agreement | Long-term offtake contracts with austenitic stainless producers hedge London Metal Exchange price volatility exposure. |
| Direct-to-Fleet Digital Platform | Bypassing wholesale intermediaries enables margin capture from commercial vehicle operators specifying total cost of ownership metrics. |
Research Methodology
Multi-period observation of stainless steel forming adoption rates and Euro 7 readiness program timelines anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and foundry operations managers. Secondary validation drew from vehicle production databases, EPA emission certification filings, IHS Markit registration data, and SEC 10-K disclosures from integrated exhaust system suppliers. Bottom-up segment sizing triangulated against top-down powertrain production forecasts.
Segment-weighting across material grade, vehicle class, propulsion architecture, and regional production cluster shaped the analytical framework throughout the forecast period. CAGRs were derived from installed base turnover modeling and content-per-vehicle trajectories for turbocharged configurations. Industry-specific inputs included thermal durability testing protocols, catalytic substrate integration complexity, and fleet procurement specification trends.
Caveats apply where nickel price volatility, foundry capacity constraints, or regulatory timeline divergence could materially shift the outlook. Forecasts reflect assumptions about powertrain electrification pacing and OEM platform commonization decisions. Material deviation in London Metal Exchange pricing or EPA-CARB certification alignment warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Active Body Panel Market
Automotive Components
Automotive Rear End Module Market
Automotive Components
Global Automotive Components Forging Market
Automotive Components
Automotive Exhaust Headers Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Global Automotive Water Valve Market
Automotive Components
Automotive Axle Market
Automotive Components
Automotive Carbon Ceramic Brakes Market
Automotive Components
Automotive Seat Frame Market
Automotive Components
Automotive Lightweighting Market
Automotive Components
Automotive Metal Casting Market
Automotive Components
Global Automotive Structural Sheet Metal Market
Automotive Components
Automotive Bushing Market
Automotive Components
Automotive Push Rods Market
Automotive Components
Automotive Bearing Market