
 Metal Forming for Automotive Market | 2026-2036
Metal Forming for Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Forming for Automotive Market Intelligence
The traditional divide between mechanical engineering and materials science expertise is collapsing due to the introduction of multi-material vehicle bodies. This shift demands a new type of integrated skillset from process technicians and design engineers. Magna International leverages its global manufacturing footprint to supply complex assemblies across multiple material types. Gestamp Automoción specializes in hot and cold stamping technologies for body-in-white applications. Thyssenkrupp anchors its market position through its deep expertise in steel and aluminum material development for automotive customers.
Metal forming for automotive encompasses a range of manufacturing processes that shape metal sheets, tubes, and billets into finished vehicle components. These processes, including stamping, forging, and roll forming, create parts with high strength-to-weight ratios essential for modern vehicle platforms. The primary purpose is to produce structural parts, body panels, and chassis elements that meet precise safety and performance specifications. Stamping continues to be the dominant product type by volume, while aluminum is gaining share from steel in the material segment to meet lightweighting objectives.
Regulatory frameworks such as the US EPA's fuel economy standards and the EU Green Deal's circular economy principles directly influence material and process selection. Conformance with quality management systems like ISO 9001 is a baseline requirement for supplying global OEMs. These regulations compel automakers and their suppliers to invest in forming technologies that reduce waste and accommodate lighter, more recyclable materials. Component suppliers must now decide on capital allocation toward flexible forming technologies capable of handling next-generation alloys.
Market Dynamics
The imperative for vehicle lightweighting, driven by the global expansion of electric vehicles and stringent emissions regulations, is the central structural force in the metal forming market. This pressure compels a transition from traditional steel to advanced aluminum alloys and high-strength steels.
Growth Catalysts
- Electric Vehicle Platforms:Demand for lightweight battery enclosures, subframes, and body structures for EVs creates new, high-volume opportunities for advanced forming processes that can handle complex geometries in aluminum.
- Emissions Regulations:Mandates like the US EPA's fuel economy standards and China's dual carbon goals directly incentivize mass reduction, pushing automakers to specify components made from lighter, stronger formed metals.
- Material Science Advances:The commercialization of new-generation aluminum alloys and advanced high-strength steels with improved formability allows for more aggressive lightweighting without compromising crash performance standards.
Market Restraints
- Input Material Volatility:Price fluctuations in primary aluminum and specialized steel alloying elements create significant cost uncertainty for stampers and forgers, compressing margins on long-term supply contracts with OEMs.
- High Capital Expenditure:The adoption of technologies like hot stamping or servo presses for next-generation materials requires substantial capital investment in new equipment, tooling, and facility upgrades, creating a barrier for smaller suppliers.
- Processing Complexity:Advanced alloys exhibit challenging forming behaviors such as increased springback and lower ductility, which can lead to higher scrap rates and require more sophisticated process control and simulation.
Strategic Opportunities
- Multi-Material Joining:Developing and scaling technologies for joining dissimilar materials, such as aluminum to steel, represents a significant value-add service for suppliers building complex body-in-white sub-assemblies.
- Closed-Loop Recycling:Establishing systems to segregate, process, and re-introduce high-value production scrap from aluminum stamping into the supply chain aligns with circular economy principles and creates a new revenue stream.
- Digital Process Simulation:Offering advanced forming simulation as a service allows suppliers to engage earlier in the vehicle design process, optimizing part design for manufacturability and reducing costly tooling rework.
Industry Challenges
- Integrated Skillset Scarcity:A critical shortage of process engineers and technicians who possess combined expertise in materials science, mechanical engineering, and data analytics hinders the effective deployment of advanced forming technologies.
- Supply Chain Synchronization:Coordinating the just-in-time delivery of large, complex assemblies from production hubs like Mexico and China to OEM assembly plants globally requires sophisticated logistics and risk management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Forming for Automotive Market |
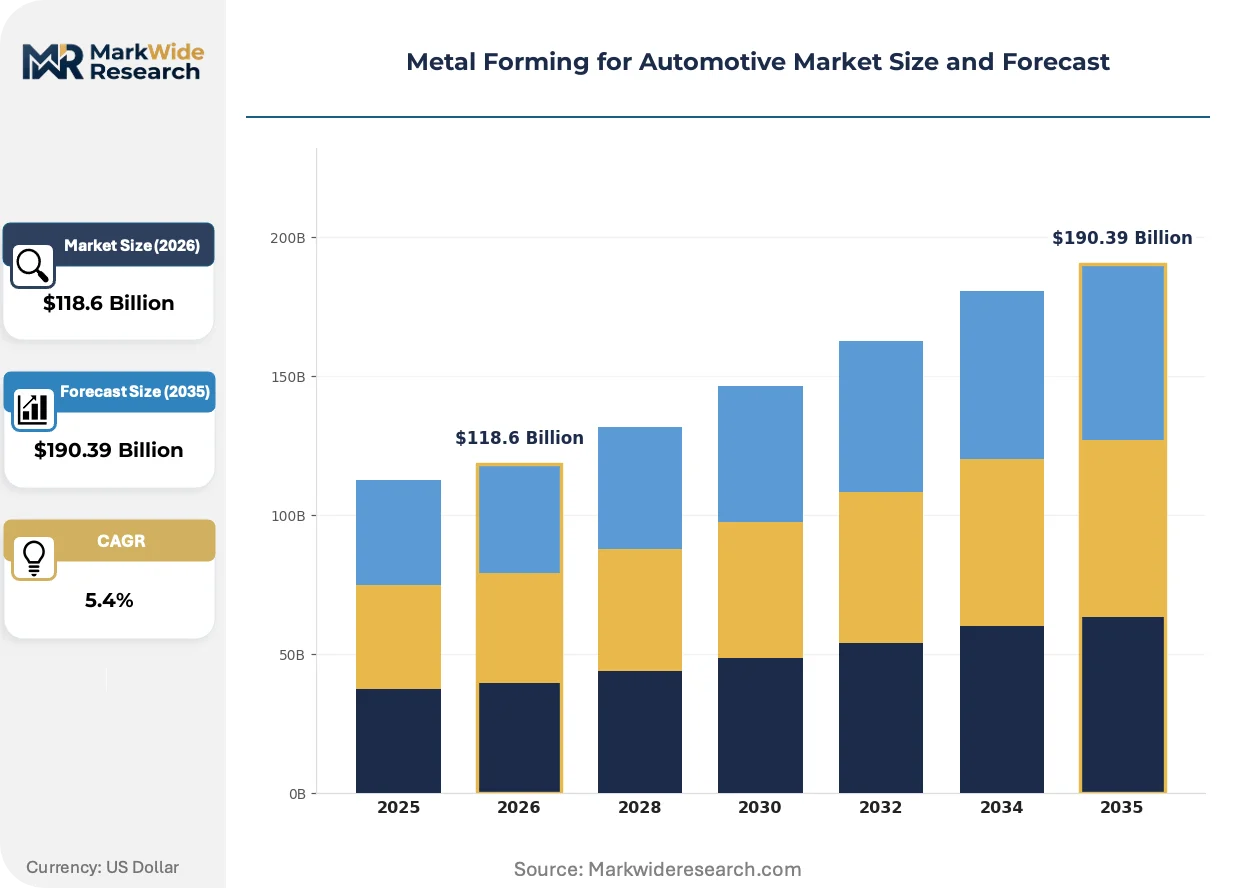
| Market Size in 2026 | $118.6 Billion |
| Market Size in 2035 | $190.39 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stamping, Bending, Roll Forming, Forging Material: Steel, Aluminum, Titanium, Copper End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Die Casting, Hydroforming, Additive Manufacturing, CNC Machining |
| Companies Covered | Martinrea International, Thyssenkrupp, Magna International, Voestalpine Group, ArcelorMittal, Benteler, Gestamp Automoción, Kirchhoff, Tower International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Forming for Automotive Market Strategic Shifts & Innovations
The convergence of advanced material science and digital manufacturing tools is redefining the boundaries of component design and production efficiency. This shift enables the creation of lighter, stronger, and more complex parts to meet the demands of next-generation vehicle architectures.
Hot stamping, or press hardening, allows for the formation of ultra-high-strength steel components in a single process step. Automotive OEMs are specifying this technology for critical safety cage elements like B-pillars and roof reinforcements. The adoption of hot stamping is displacing traditional multi-piece, cold-stamped and welded assemblies, enabling significant weight reduction while simultaneously improving crash intrusion resistance.
Regulatory frameworks, particularly the EU Green Deal and its focus on the circular economy, are directly influencing material selection. This forces suppliers to track and report the carbon footprint and recycled content of their materials, a requirement enforced by directives like the CSRD. The aluminum segment is most affected, with suppliers now investing in scrap segregation and traceability systems to validate the use of low-carbon primary and recycled inputs.
Automaker procurement behavior is evolving from sourcing individual stamped parts to purchasing large, integrated modules. This change disrupts the traditional Tier-2 supplier model focused on single components, favoring large Tier-1 suppliers capable of complex multi-material assembly and logistical management. This trend is most pronounced in new electric vehicle platform launches across North America and China, where speed-to-market is critical.
Metal Forming for Automotive Market Segmentation
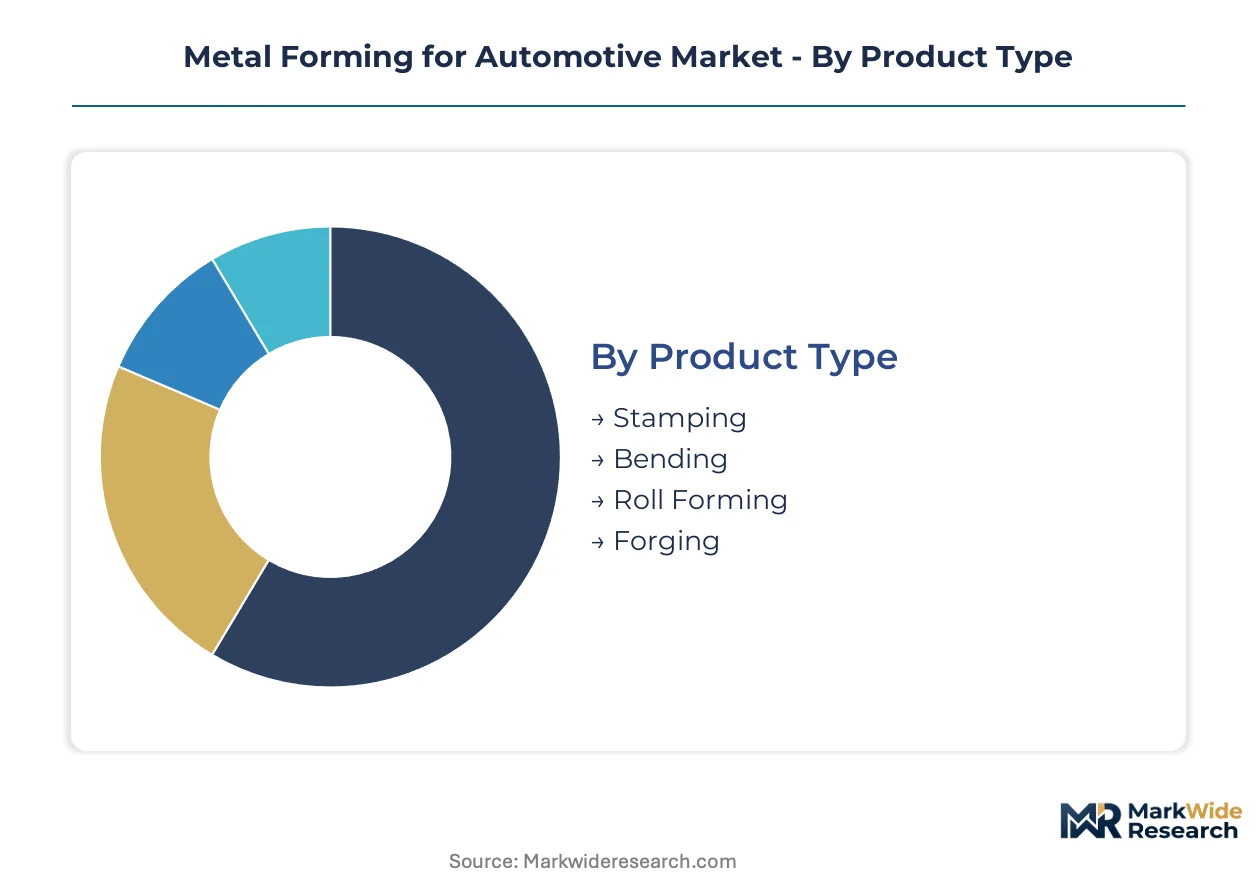
Understanding the distinct segments within the metal forming for automotive market clarifies how different processes and materials contribute to vehicle manufacturing. This segmentation highlights the diverse technological requirements and supplier specializations across the automotive value chain. Each category reflects specific operational demands from automakers and their Tier suppliers.
Product Type:
Regulatory frameworks such as the US EPA's fuel economy standards and the EU Green Deal significantly influence the selection of metal forming product types. Automakers prioritize processes that enable lightweighting while maintaining structural integrity for safety compliance.
- Stamping:This process forms sheet metal into desired shapes using a press and die, creating high-volume body panels and structural components. Stamping remains the most widely used metal forming technique due to its efficiency and cost-effectiveness for mass production.
- Forging:Forging involves shaping metal through localized compressive forces, producing components with superior strength and fatigue resistance for critical powertrain and chassis applications. Demand for forged components is strong in heavy-duty vehicle platforms requiring robust performance.
- Bending:Bending deforms metal along a linear axis, creating angled parts and complex geometries often used in exhaust systems and chassis frames. This technique offers flexibility for custom component fabrication.
- Roll Forming:Roll forming continuously bends long strips of metal into desired cross-sections, producing lightweight and high-strength structural elements. This method is gaining traction for EV battery frames and body-in-white structures.
Stamping handles the majority of throughput; Roll Forming is the fastest mover on share.
Material:
The choice of material often dictates specific application requirements, impacting vehicle performance and manufacturing complexity. Different alloys offer distinct advantages in terms of strength, weight, and formability for automotive components.
- Aluminum:Aluminum alloys offer significant weight reduction capabilities, making them critical for electric vehicle battery enclosures and structural components. The demand for formed aluminum parts is expanding rapidly due to stringent emissions standards.
- Steel:Steel, including advanced high-strength steel (AHSS), remains a foundational material for body-in-white structures and chassis components due to its cost-effectiveness and crash energy absorption properties. Traditional steel continues to dominate in high-volume, cost-sensitive vehicle segments.
- Titanium:Titanium alloys provide an exceptional strength-to-weight ratio and corrosion resistance, primarily used in high-performance or specialized automotive applications. Its high cost limits widespread adoption in mass-market vehicles.
- Copper:Copper is primarily used for electrical components, wiring harnesses, and heat exchangers within automotive systems due to its excellent electrical and thermal conductivity. Formed copper parts are essential for EV power electronics.
Steel accounts for the largest volume of material formed; Aluminum exhibits the steepest expansion trajectory.
End User:
Customer type defines the sales channels and specific quality and volume requirements for formed metal components. Each end-user segment has distinct procurement strategies and supply chain expectations.
- OEMs:Original Equipment Manufacturers procure a wide range of formed components directly for vehicle assembly, often demanding high volumes and strict quality control. OEMs increasingly seek integrated module suppliers capable of complex multi-material assemblies.
- Tier-1 Suppliers:Tier-1 suppliers integrate various formed components into larger sub-assemblies before supplying them to OEMs, managing complex manufacturing processes and logistics. These suppliers often specialize in specific component systems like chassis or body structures.
- Aftermarket Providers:Aftermarket providers supply replacement parts for vehicles already in service, requiring a diverse inventory of formed components for various models and years. This segment prioritizes availability and cost-effectiveness for repair and maintenance.
- Vehicle Assemblers:Vehicle assemblers focus on the final integration of components into complete vehicles, relying on timely delivery of formed parts from their supply chain. Their demand is driven by production schedules and model specifications.
OEMs represent the most mature customer segment; Tier-1 Suppliers are demonstrating the most dynamic growth in procurement complexity.
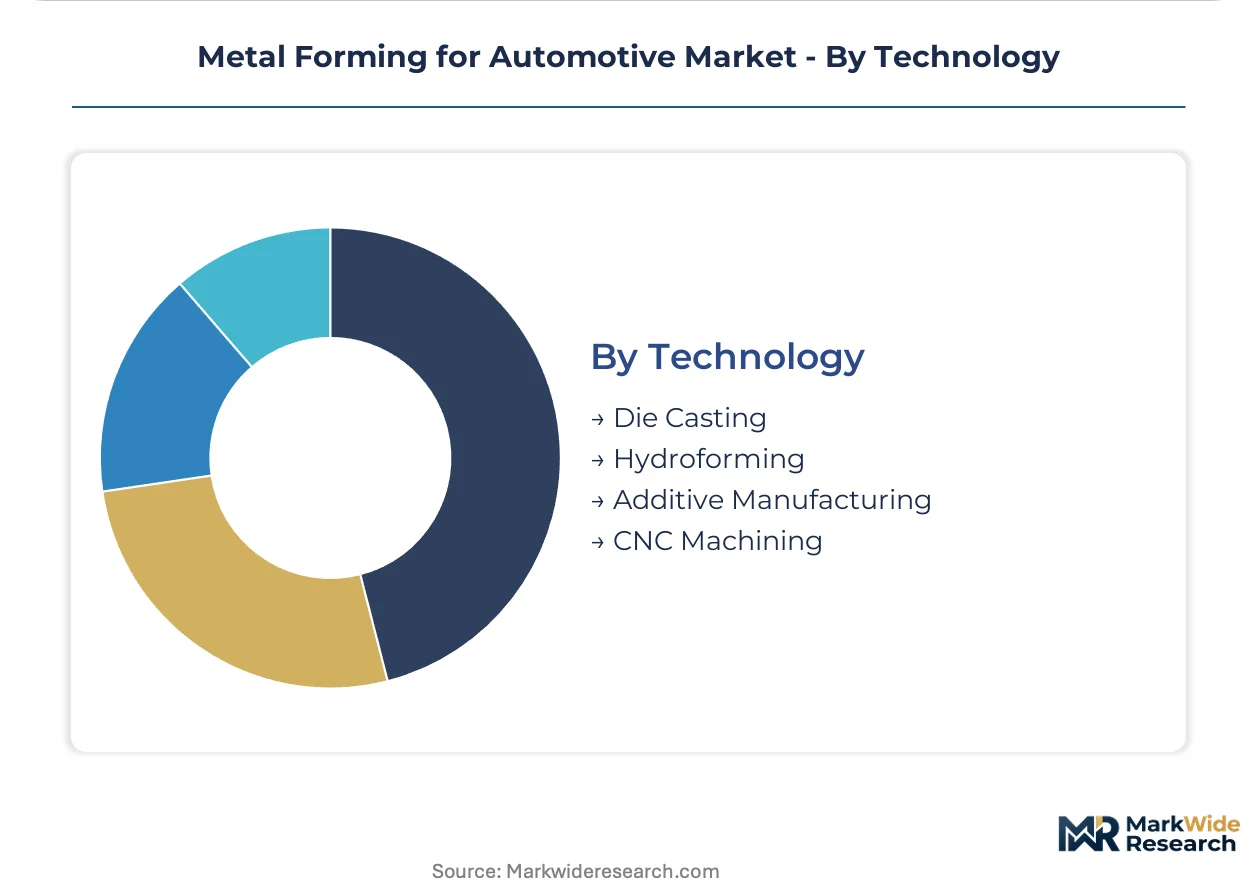
Technology:
Supply concentration in specific forming technologies reflects the specialized equipment and expertise required for advanced material processing. Different technologies cater to varying part geometries, material types, and production volumes.
- Die Casting:Die casting forces molten metal into a mold cavity under high pressure, producing complex, high-precision parts with excellent surface finish for engine blocks and transmission housings. This technology is crucial for producing intricate aluminum and magnesium components.
- Hydroforming:Hydroforming uses pressurized fluid to shape metal tubes or sheets into complex, lightweight structures, reducing part count and improving structural rigidity. This process is increasingly employed for automotive chassis and frame elements.
- Additive Manufacturing:Additive manufacturing, or 3D printing, builds metal parts layer by layer directly from digital designs, enabling rapid prototyping and the creation of highly complex, optimized geometries. This technology is gaining traction for specialized tooling and low-volume, high-value components.
- CNC Machining:Computer Numerical Control (CNC) machining uses automated cutting tools to precisely shape metal parts from solid blocks or pre-formed components, ensuring tight tolerances for critical engine and suspension parts. It offers high precision for complex, low-volume production.
Die Casting commands the largest margin potential; Additive Manufacturing is exhibiting the most aggressive margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption patterns for metal forming in automotive differ significantly across major global manufacturing hubs. While traditional steel stamping remains foundational, countries with aggressive electric vehicle targets are rapidly increasing demand for advanced aluminum forming. This regional divergence impacts technology adoption and material procurement strategies for automotive suppliers.
China
China's robust electric vehicle market drives demand for formed aluminum components, especially for battery enclosures and subframes. The government's dual carbon goals accelerate the shift towards lighter vehicle designs. Automotive clusters in the Yangtze River Delta region invest heavily in advanced forming for new materials.
Mexico
Mexico's automotive sector, a major exporter to the United States, focuses on high-volume chassis and structural components. Compliance with US EPA fuel economy standards mandates lightweighting efforts. Production facilities in the Bajío region integrate advanced high-strength steels and aluminum forming processes for OEMs.
Germany
German automotive manufacturers prioritize precision-formed components for premium vehicles and electric platforms. The EU Green Deal and CSRD regulations compel carbon footprint reporting for materials like aluminum. Automotive centers in Bavaria and Baden-Württemberg lead innovation in hot stamping and multi-material joining.
United States
The United States market sees strong demand for formed components in light trucks and electric vehicle platforms. US EPA fuel economy standards and IRA incentives drive investment in domestic lightweighting solutions. Automotive suppliers in Michigan and the Southeast expand capacity for advanced aluminum and high-strength steel forming.
Japan
Japanese automakers require high-precision formed parts for global vehicle platforms, with focus on hybrid and electric powertrains. METI supports advanced manufacturing, while JIS standards ensure material quality. Automotive production in the Chubu region drives demand for highly automated stamping and roll forming lines.
Metal Forming for Automotive Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the metal forming for automotive market. These larger entities often possess global manufacturing footprints and diverse material capabilities, enabling them to offer comprehensive solutions. Strategic archetypes include vertically integrated material specialists, complex multi-material assembly providers, and niche technology innovators. Competitive moves frequently involve capacity expansion to handle advanced materials, strategic partnerships for multi-material joining solutions, and investment in digital process simulation capabilities.
Within the integrated leader and specialist tiers, Germany-based Thyssenkrupp AG exemplifies deep expertise in steel and aluminum material development, anchoring its position as a materials technology provider. Canadian-headquartered Magna International Inc. represents a global manufacturing footprint capable of supplying complex multi-material assemblies, catering to diverse OEM needs. Spain-based Gestamp Automoción S.A. anchors its position through specialization in hot and cold stamping technologies for body-in-white applications, reflecting a focus on advanced forming processes. These companies collectively illustrate the diverse strategic approaches employed to serve the evolving automotive sector.
| Leading Market Players |
|---|
| Martinrea International |
| Thyssenkrupp |
| Magna International |
| Voestalpine Group |
| ArcelorMittal |
| Benteler |
| Gestamp Automoción |
| Kirchhoff |
| Tower International |
| Others |
Cost & Logistics Intelligence
The substitution of advanced aluminum for traditional steel simultaneously reshapes supply geography and pricing economics in the metal forming market. This shift compels suppliers to re-evaluate material sourcing and manufacturing footprints to align with evolving OEM demands.
Pricing Analysis
Long-term supply contracts anchor metal forming pricing. Automakers often secure stable component costs through multi-year agreements with Tier-1 suppliers. Price differentiation stems from material type, forming complexity, and the level of customization. Pricing pressure stems from volatile primary aluminum and specialized steel alloying element costs, compressing supplier margins. OEMs are highly price-sensitive for high-volume, standard components, while showing less sensitivity for safety-critical, complex assemblies.
Supply Chain Analysis
Logistics synchronization across global production hubs presents a chokepoint for complex multi-material assemblies. Supply concentration centers in China, Mexico, and Germany for automotive components. Raw material dependencies include primary aluminum and advanced high-strength steel alloys. Input material price volatility represents a significant structural risk. Distribution primarily occurs through just-in-time delivery systems directly to OEM assembly plants worldwide.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metal forming for automotive market is entering a cyclical recovery, driven by renewed global automotive production cycles and new electric vehicle platform launches.
For Market Incumbents: Fortify existing market positions by investing in advanced forming technologies like hot stamping and multi-material joining. This counters the threat from specialized new entrants and stringent emissions regulations. Capacity expansion in Mexico or the US for advanced high-strength steel and aluminum forming leverages regional demand. R&D into digital process simulation enhances efficiency and reduces material waste.
For New Entrants and Emerging Players: Lead with niche technological expertise in areas like additive manufacturing for tooling or closed-loop recycling systems for aluminum. The electric vehicle battery enclosure segment offers penetrable white space. Target smaller, agile EV startups in North America. A go-to-market angle focused on sustainability and rapid prototyping capabilities can differentiate offerings.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized, specialized metal formers proficient in advanced materials. The long-term viability hinges on their ability to adapt to multi-material vehicle bodies over the next decade. Target acquisition archetypes include Tier-2 suppliers with strong intellectual property in forming simulation or proprietary joining technologies. The signal to watch is the sustained increase in OEM commitments to new EV platforms requiring complex formed components.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for AHSS/Aluminum | Ensures supply to meet lightweighting demand from EV platforms. |
| Multi-Material Joining R&D | Enables complex assemblies for advanced vehicle body structures. |
| Closed-Loop Recycling Integration | Aligns with circular economy principles and reduces material costs. |
| Digital Process Simulation Adoption | Optimizes part design for manufacturability and reduces tooling rework. |
| Strategic Partnerships with Material Suppliers | Secures access to next-generation alloys and specialized expertise. |
Research Approach
A spread of perspectives from OEM procurement leads, Tier-1 engineering directors, material science R&D heads, and process technicians converged on the working assumptions for this analysis. This involved primary interviews combined with secondary validation from sources like US EPA reports, EU Green Deal documents, and ISO 9001 standards. The research employed both bottom-up and top-down triangulation to ensure data accuracy and coherence.
The market model integrates segmentation dimensions including product type, material, end-user, technology, and regional automotive production clusters. Compound annual growth rates were derived from historical trends, market dynamics, and expert projections across the analysis window. Key industry-specific forecast inputs included global vehicle production forecasts and material lightweighting targets per vehicle platform.
Forecasts assume regulatory continuity in US EPA, EU Green Deal, and China's dual carbon goals; material policy shifts would require re-modeling. Geopolitical disruptions or raw material supply shocks represent specific risk factors that could revise these projections. Practitioners should keep alternative scenarios live as global trade policies and technological advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Japan Automotive Sunroof Market
Automotive Components
Automotive Key Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Polyamide in E-Mobility Market
Automotive Components
Automotive Connecting Rod Bearing Market
Automotive Components
Automotive Lightweighting Market
Automotive Components
Automotive Backing Plate Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Automotive Dynamic Spotlight Market
Automotive Components
Automobile Accessories Market
Automotive Components
Drive System Market
Automotive Components
Italy Automotive Actuators Market
Automotive Components
Asia Pacific Automotive Actuators Market