
 France Automotive Electric Actuators Market | 2026-2036
France Automotive Electric Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
France Automotive Electric Actuators Market Foresight
The transition from hydraulic to electromechanical actuation is narrowing the design envelope for chassis and powertrain systems. BorgWarner Inc. leverages its power electronics heritage to anchor high-voltage actuator platforms for hybrid architectures. Robert Bosch GmbH sustains broad manufacturing scale across brushless motor variants serving multiple French OEM programs. Valeo competes through integrated mechatronic modules that consolidate sensor, motor, and control functions into single assemblies.
France automotive electric actuators are electromechanical devices converting electrical energy into precise mechanical motion, typically achieving positional accuracy within 0.1 millimeters and operating across temperature ranges from minus 40 to 150 degrees Celsius to regulate engine airflow, thermal management circuits, and cabin comfort systems. Their primary purpose is replacing pneumatic and hydraulic control elements with programmable, feedback-capable motion systems that reduce vehicle weight and enable software-defined calibration. Brushless DC motors dominate the technology landscape due to superior torque density and maintenance intervals aligned with vehicle lifecycles, while piezoelectric actuators occupy niche precision applications in fuel injection and active valve train systems where microsecond response times command premium positioning. Passenger vehicles represent the largest application volume pool, though commercial trucks generate higher per-unit actuator counts in transmission and aftertreatment systems.
France's national regulator for type approval enforces EU homologation standards that mandate CO2 emissions reductions, directly accelerating electric actuator deployment in thermal management and engine breathing systems. The EU Green Deal's binding fleet targets and France's domestic Crit'Air low-emission zone classifications shape product specifications and aftermarket replacement demand. ANSM and CNIL oversight of embedded software and connected vehicle data adds compliance layers to actuator control firmware. Stakeholders must monitor how France's reindustrialization incentives for battery and electric motor production reshape supplier location decisions and local content requirements.
Market Dynamics
The EU Green Deal's binding fleet CO2 targets are compressing development cycles for thermal management actuators across French OEM supply chains, forcing electromechanical substitution of hydraulic engine controls within single vehicle generations.
Growth Catalysts
- Crit'Air Low-Emission Zones:France's urban access restrictions are accelerating actuator deployment in stop-start systems and active grille shutters to cut real-world emissions in city driving.
- Powertrain Electrification:Battery thermal management circuits require precision coolant valve actuators that pneumatic systems cannot deliver, expanding actuator counts per vehicle by 40-60% in hybrid architectures.
- Brushless DC Motor Maturation:Rare-earth magnet supply stabilization from Rhône-Alpes magnetics suppliers is reducing motor cost volatility and enabling platform-scale procurement commitments.
Market Restraints
- Copper and Neodymium Price Volatility:Input cost swings of 15-30% annually complicate long-term actuator pricing contracts with Stellantis and Renault procurement teams.
- Single-Source Semiconductor Dependency:Silicon carbide gate drivers for high-voltage actuator inverters concentrate among German and Dutch foundries, creating geographic supply risk.
- Piezoelectric Actuator Temperature Sensitivity:Crystalline deformation above 120°C limits fuel injection applications to port-injection architectures, excluding direct-injection high-pressure zones.
Strategic Opportunities
- Île-de-France Engineering Services:Unpenetrated demand exists for actuator calibration software outsourcing from Paris-region Tier 2 suppliers lacking embedded control expertise.
- Commercial Vehicle Aftertreatment:Euro VII pre-compliance investments by French truck fleets are opening retrofit actuator markets for selective catalytic reduction dosing systems.
- Mechatronics-AS-a-Service:Subscription-based actuator maintenance contracts tied to ANSM software validation requirements represent a nascent revenue model for fleet operators.
Industry Challenges
- Embedded Firmware Certification:CNIL data governance rules and ANSM functional safety standards are extending actuator control software validation timelines by 8-14 months.
- Legacy Hydraulic System Integration:Electromechanical retrofits into existing Stellantis manufacturing lines require custom mechanical adapters that erode unit economics on low-volume platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Automotive Electric Actuators Market |
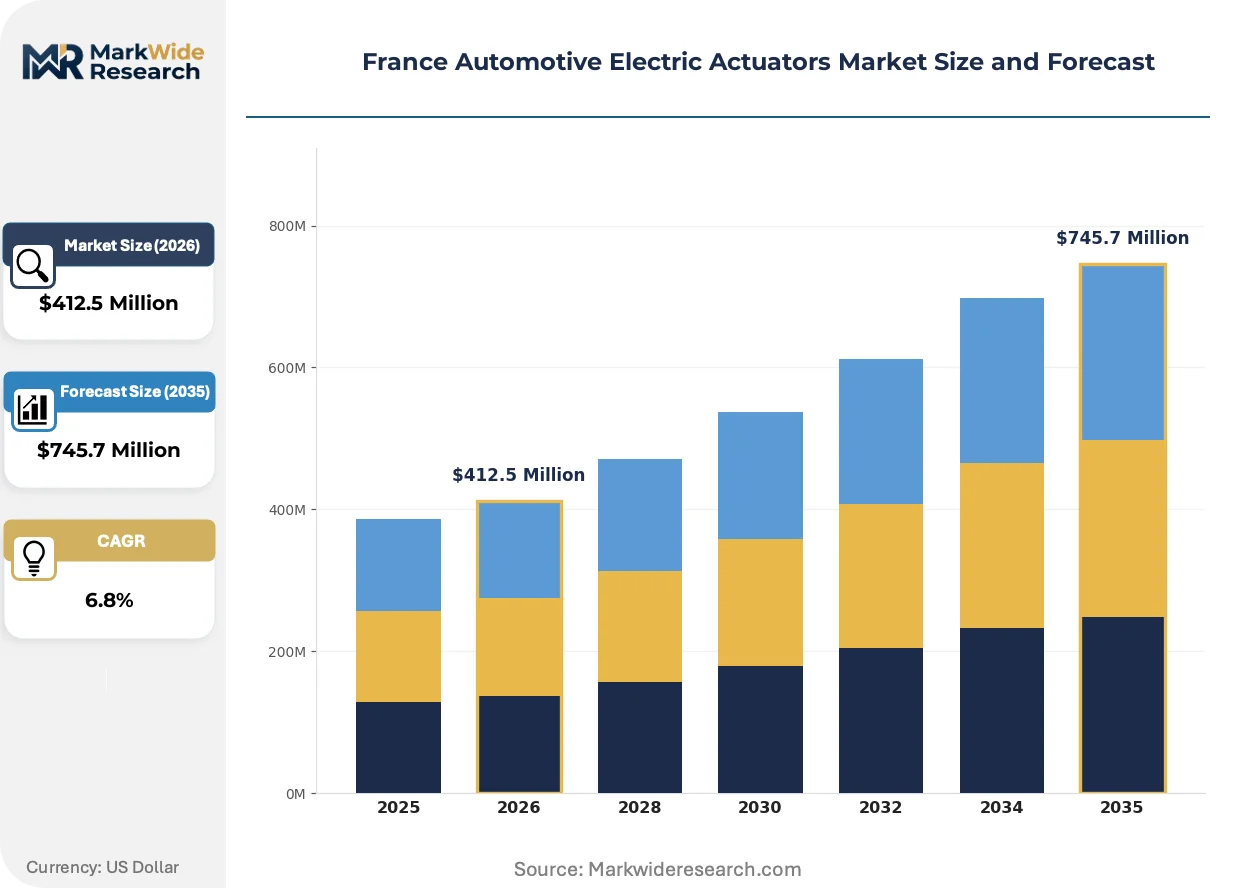
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Throttle Actuators, Valve Actuators, Seat Adjustment Actuators, Window Lifter Actuators, Mirror Adjustment Actuators Technology: Brushless DC Motors, Stepper Motors, Servo Motors, Linear Actuators, Piezoelectric Actuators Application: Passenger Vehicles, Commercial Trucks, Off-Road Vehicles, Two-Wheelers, Specialty Vehicles End User: OEMs, Tier-1 Suppliers, Dealerships, Aftermarket Service Providers |
| Companies Covered | Wabco Holdings Inc., BorgWarner Inc., Robert Bosch GmbH, Sonceboz SA, Hella KGaA Hueck & Co., Continental AG, Johnson Electric, Valeo, Denso Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Automotive Electric Actuators Market Shifts & Advancements
Software-defined vehicle architectures are collapsing the boundary between actuator hardware and control logic, enabling over-the-air calibration updates that were mechanically impossible in hydraulic systems.
Integrated smart actuators embedding position sensors and edge-computing microcontrollers are rendering obsolete the discrete sensor-actuator-controller triads that dominated 2010s chassis electronics. French OEMs are adopting these consolidated modules for electric power steering and active suspension programs. The consolidation is compressing supplier tier counts from three to two in thermal management subsystems.
France's transposition of the EU AI Act into national law is mandating algorithmic transparency for safety-critical actuator control loops in autonomous emergency braking and lane-keeping systems. Suppliers must now document training data provenance and decision boundary logic for ANSM type approval. The requirement is delaying launch schedules for Level 2+ hands-free driving features by 6-9 months.
Renault's consolidated procurement platform is aggregating actuator demand across Dacia, Alpine, and Renault brands into single-source negotiations, reversing the fragmented supplier relationships of the 2015-2020 period. Tier 1 suppliers report 30% reduction in RFQ response windows and compressed technical specification cycles. The concentration is most visible in powertrain thermal actuators where three suppliers now serve 80% of French OEM volume.
France Automotive Electric Actuators Market Segmentation
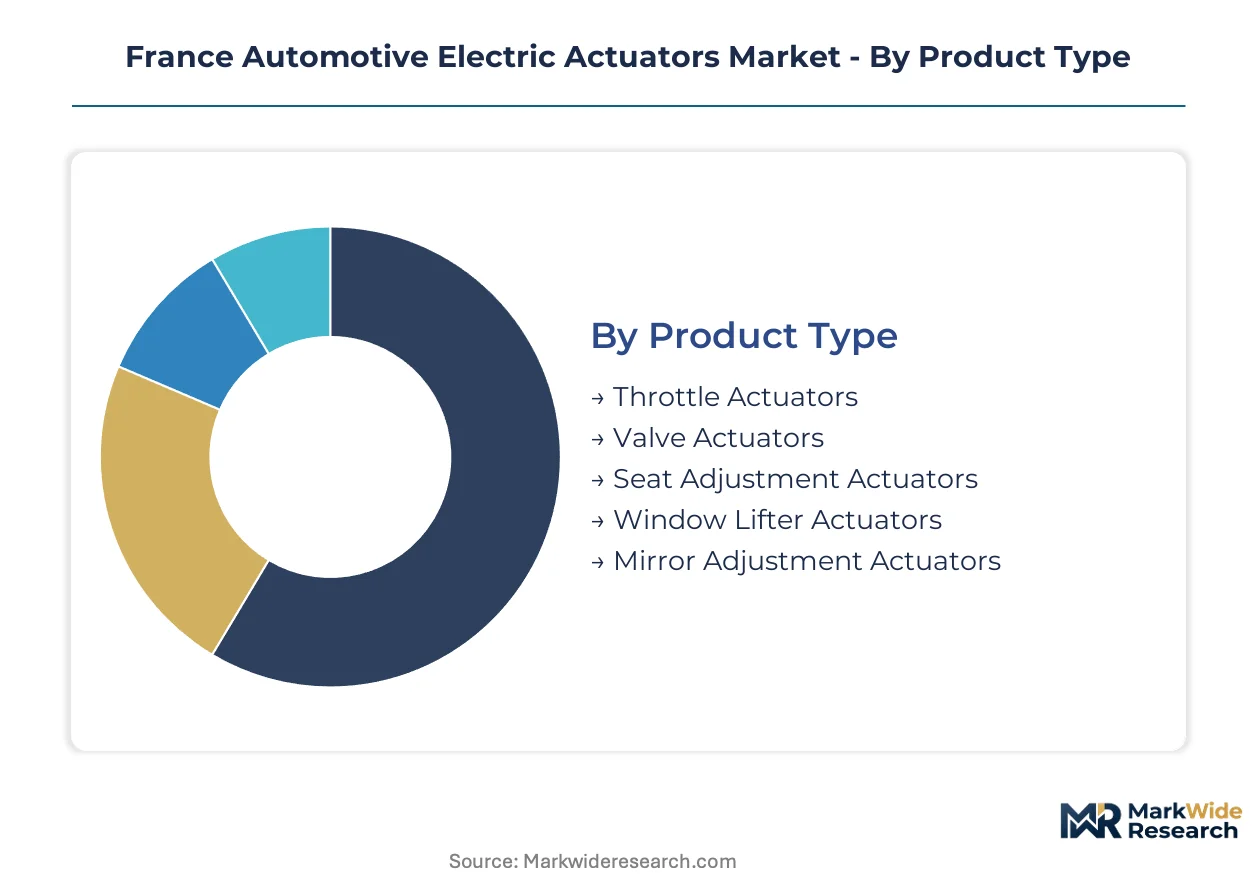
Segmentation of the France automotive electric actuators market reveals how technical specifications, procurement hierarchies, and vehicle architectures create distinct demand pockets. Understanding these divisions clarifies where supplier investments in brushless motor platforms or mechatronic integration generate differential returns.
Product Type:
Cost tier differentiation across actuator families reflects the precision requirements and failure-mode criticality of each automotive subsystem.
- Throttle Actuators:Electronically controlled butterfly valve mechanisms regulate engine air intake with positional feedback loops operating at millisecond response rates. Stellantis and Renault powertrain programs in Île-de-France specify these for downsized turbocharged engines where airflow precision directly impacts CO2 compliance margins.
- Valve Actuators:Coolant and refrigerant valve controls manage thermal management circuits in battery-electric and hybrid architectures. Rhône-Alpes manufacturing corridors concentrate demand as local suppliers integrate these into HVAC and powertrain cooling modules for French OEM electrification roadmaps.
- Seat Adjustment Actuators:Compact DC motor assemblies enable multi-way seat positioning with memory functions. Premium vehicle configurations in the Paris region drive specification complexity.
- Window Lifter Actuators:Cable-drive and scissor-mechanism motor units provide side glass automation. Fleet vehicle procurement emphasizes durability ratings over feature density.
- Mirror Adjustment Actuators:Micro-motor assemblies with folding and heating integration. Aftermarket replacement channels sustain volume beyond original equipment fitment.
Throttle actuators command the established base. The steepest expansion runs through valve actuators.
Technology:
Application demands for torque density, positional accuracy, and thermal tolerance determine motor technology selection across French supplier portfolios.
- Brushless DC Motors:Permanent magnet synchronous designs deliver superior power-to-weight ratios and maintenance-free operation aligned with vehicle lifecycles. ANSM type approval requirements for functional safety favor these in chassis and powertrain systems where failure modes carry regulatory exposure.
- Stepper Motors:Open-loop positioning systems achieve discrete angular increments without feedback sensors. Cost-sensitive HVAC damper applications in Dacia vehicle programs exploit their simpler control architectures.
- Servo Motors:Closed-loop feedback systems with encoder integration enable precise velocity and position control. Active suspension programs require their dynamic response characteristics.
- Linear Actuators:Rotary-to-linear motion conversion mechanisms for clutch release and parking brake applications. Commercial vehicle duty cycles stress their mechanical endurance ratings.
- Piezoelectric Actuators:Crystalline expansion elements generate nanometer-scale displacements with microsecond response times. Fuel injection precision demands limit deployment to port-injection architectures excluded from direct-injection high-pressure zones by temperature constraints.
Brushless DC motors anchor the installed base. The most rapid technology transition is occurring in servo motor adoption for autonomous driving actuator networks.
Application:
Vehicle category segmentation tracks how electrification intensity and regulatory exposure shape per-unit actuator counts and specification grades.
- Passenger Vehicles:Light-duty automobiles generate the largest absolute volume pool across French OEM production. Crit'Air low-emission zone classifications in Paris, Lyon, and Marseille accelerate stop-start system and active grille shutter actuator deployment to cut real-world urban emissions.
- Commercial Trucks:Heavy-duty vehicles carry higher per-unit actuator densities in transmission, aftertreatment, and cab comfort systems. Euro VII pre-compliance investments by French fleet operators are opening retrofit markets for selective catalytic reduction dosing actuators.
- Off-Road Vehicles:Agricultural and construction equipment operates in severe contamination and vibration environments. Sealing specifications exceed passenger car grades.
- Two-Wheelers:Motorcycles and scooters incorporate simplified actuator architectures for throttle and braking functions. Electrification trends in urban mobility segments are expanding motor controller integration.
- Specialty Vehicles:Ambulance, fire apparatus, and military configurations demand customized actuator protocols for mission-critical reliability.
Passenger vehicles dominate volume concentration. Commercial trucks are climbing the fastest on electrification-driven thermal management expansion.
End User:
Customer type segmentation captures how procurement authority, technical specification control, and aftermarket access differentiate revenue capture models.
- OEMs:Stellantis and Renault Group retain direct sourcing relationships for strategic actuator families where software-defined calibration interfaces with vehicle-level control architectures. Their consolidated procurement platforms are aggregating demand across brand portfolios into single-source negotiations.
- Tier-1 Suppliers:Valeo, BorgWarner, and Bosch manufacturing entities in France intermediate component supply with subsystem integration responsibility. Their embedded control expertise satisfies ANSM firmware validation requirements.
- Dealerships:Authorized retail networks handle warranty actuator replacement and software update distribution. CNIL data governance rules extend to connected vehicle diagnostics accessed during service events.
- Aftermarket Service Providers:Independent repair channels source replacement actuators for out-of-warranty vehicles. Crit'Air enforcement is sustaining demand for emissions-related actuator retrofits in aging French fleets.
Tier-1 suppliers concentrate design-in authority. Aftermarket service providers are gaining share fastest on vehicle parc expansion and regulatory retrofit obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's automotive electric actuator trade flows reflect a structural export surplus in precision mechatronic assemblies, with Île-de-France engineering houses supplying German and Italian OEM programs while importing rare-earth magnetics from Rhône-Alpes suppliers. Cross-border component movements within the EU single market dominate commercial patterns.
Île-de-France
Paris-region engineering clusters concentrate actuator calibration software development for Stellantis and Renault Group programs. ANSM type approval processes for embedded control firmware extend validation timelines. Nanterre and Velizy-Villacoublay host Tier-1 supplier engineering centers where thermal management actuator specifications are finalized.
Auvergne-Rhône-Alpes
Lyon-Grenoble manufacturing corridors anchor brushless DC motor production for hybrid powertrain thermal circuits. Crit'Air low-emission zone enforcement in Lyon metropolitan area accelerates stop-start system actuator deployment. Saint-Étienne magnetics suppliers stabilize rare-earth material flows for permanent magnet motors.
Provence-Alpes-Côte d'Azur
Marseille's port infrastructure handles actuator component imports from North African assembly operations. CNIL data governance oversight extends to connected vehicle diagnostics accessed at regional service centers. Aix-en-Provence hosts specialized testing facilities for high-temperature valve actuator validation.
Hauts-de-France
Douai and Maubeuge production facilities integrate electric actuators into light commercial vehicle platforms for Renault Group. EU Green Deal fleet CO2 targets compress development cycles for regional supplier networks. Valenciennes engineering centers focus on commercial vehicle aftertreatment actuator retrofit programs.
France Automotive Electric Actuators Market Competitive Landscape
On the supply side, the industry is consolidating around three dominant archetypes: integrated Tier-1 mechatronics suppliers with embedded control expertise, specialized motor manufacturers scaling brushless DC platforms, and diversified automotive electronics houses leveraging power electronics heritage. Competitive dynamics center on strategic partnerships for silicon carbide inverter sourcing and portfolio diversification into thermal management subsystems. Geographic proximity to French OEM engineering centers in Île-de-France and Rhône-Alpes functions as a positional advantage.
Among diversified automotive suppliers, BorgWarner Inc., Robert Bosch GmbH, and Valeo exemplify the integrated Tier-1 archetype. BorgWarner occupies a position tied to power electronics heritage for high-voltage hybrid architectures. Bosch represents scale-driven manufacturing breadth across brushless motor variants. Valeo anchors the mechatronics-integrated tier through consolidated sensor-motor-control assemblies. Continental AG and Denso Corporation sit within the same strategic tier, though with differentiated geographic emphases.
| Leading Market Players |
|---|
| Wabco Holdings Inc. |
| BorgWarner Inc. |
| Robert Bosch GmbH |
| Sonceboz SA |
| Hella KGaA Hueck & Co. |
| Continental AG |
| Johnson Electric |
| Valeo |
| Denso Corporation |
| Others |
Supply & Pricing Matrix
Rhône-Alpes magnetics corridor freight costs from Saint-Étienne to Île-de-France assembly plants compress margin structures for brushless DC motor suppliers while amplifying price premiums on rare-earth-dependent actuator tiers against standard ferrite-motor alternatives.
Pricing Analysis
Technology-generation pricing gaps separate legacy brushed-motor actuators from brushless DC platforms and emerging silicon-carbide inverter generations. Three-tier pricing structure across premium, standard, and economy levels tracks ANSM certification grade and thermal tolerance specifications. Pricing pressure stems from copper and neodymium input cost swings complicating long-term contracts with Stellantis procurement teams. Fleet vehicle procurement channels exhibit highest price sensitivity; premium passenger configurations tolerate specification premiums for integrated mechatronic modules.
Supply Chain Analysis
Upstream neodymium and dysprosium feedstock flows concentrate through Chinese rare-earth processing facilities and Australian mining operations before reaching Rhône-Alpes magnetics suppliers. Silicon carbide gate drivers and high-voltage inverter components draw from German and Dutch semiconductor foundries. Single-source semiconductor vulnerability creates geographic concentration risk for high-voltage actuator platforms. Distribution runs through Tier-1 mechatronics integrators with embedded control firmware expertise satisfying ANSM validation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded control firmware expertise represents the binding constraint across French OEM supply chains, with ANSM validation timelines extending 8-14 months and Tier-2 suppliers lacking calibration software capabilities.
For Market Incumbents: Harden software-defined calibration interfaces against emerging mechatronics-as-a-service competitors by consolidating sensor-motor-control assemblies into single-source modules. Anchor silicon carbide inverter partnerships with German foundries to secure high-voltage platform supply. Deepen backward integration into Rhône-Alpes rare-earth magnetics to buffer input cost volatility from Chinese processing concentration. For New Entrants and Emerging Players: Auvergne-Rhône-Alpes commercial vehicle aftertreatment retrofit channels offer penetrable white-space as Euro VII pre-compliance investments accelerate selective catalytic reduction actuator demand. Target Île-de-France engineering services outsourcing for actuator calibration software lacking embedded control expertise. Pursue ANSM firmware validation partnerships as primary go-to-market credential. For Investors and Strategic Acquirers: Specialized motor manufacturers with captive rare-earth magnet supply and ANSM-certified firmware capabilities represent acquisition targets with durable positioning. Long-term viability hinges on software-defined vehicle architecture transition sustaining actuator content expansion against hydraulic substitution completion. Watch Stellantis consolidated procurement platform negotiation outcomes as margin compression signal.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Partnership | Secures high-voltage actuator supply from German and Dutch foundries for hybrid architectures. |
| Mechatronics Module Consolidation | Compresses supplier tier counts from three to two in thermal management subsystems serving Renault. |
| Rare-Earth Magnet Backward Integration | Captures Rhône-Alpes magnetics supply to stabilize neodymium cost exposure in brushless DC motors. |
| ANSM Firmware Validation Investment | Accelerates actuator control software approval timelines for Stellantis platform integration. |
| Commercial Vehicle Aftertreatment Expansion | Captures Euro VII retrofit demand from French fleet operators for selective catalytic reduction dosing. |
Research Methodology
A spread of perspectives from Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and ANSM regulatory affairs specialists converged on the working assumptions driving segment-level demand estimates. Primary field engagement combined with secondary validation from vehicle production databases, IHS Markit registration data, customs trade flows, and EU Green Deal policy documentation. Bottom-up actuator content-per-vehicle calculations triangulated against top-down French OEM production forecasts.
Demand-supply balance dynamics across the analysis window anchored the quantitative framework, with segmentation modeling across vehicle class, propulsion architecture, content per vehicle, and OEM tier. CAGRs derived from fitted growth curves applied to technology-transition adoption rates and regulatory compliance deadlines. Brushless DC motor cost curves and rare-earth magnet price volatility scenarios informed projection sensitivity.
The forecast holds incumbent behavior within observed patterns; aggressive silicon carbide inverter capacity expansion by German foundries or accelerated Stellantis single-source consolidation would shift outcomes beyond modeled ranges. Cross-checking against IHS Markit vehicle production benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Emblem Market
Automotive Components
Australia Automotive Glass Fiber Composites Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Automotive Carbon Fiber Components Market
Automotive Components
Platinum Automotive Catalyst Market
Automotive Components
Automotive Silencer Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Automotive Bushing Market
Automotive Components
Automotive Brake Rotor Market
Automotive Components
Automotive Light Bars Market
Automotive Components
Electric Vehicle Fluid Lubricants Market
Automotive Components
Automotive Commutator Market
Automotive Components
Automotive Exhaust Silencer Market
Automotive Components
Automotive Heater Core Market
Automotive Components
Automotive Carbon Fiber Market