
 Automotive Metal Stamping Components Market | 2026-2036
Automotive Metal Stamping Components Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Metal Stamping Components Market Insights
Tool-and-die engineering talent scarcity is reorganizing how tier suppliers allocate capital across North American stamping operations. Magna International Inc. sustains one of the continent's largest independent stamping footprints through dedicated engineering centers in Ontario and Michigan. Gestamp Automoción anchors European supply to Volkswagen Group and Stellantis N.V. platforms with hot-stamping lines for passenger safety cells. Kenmode specializes in precision miniature stampings for sensor brackets and electrical terminals, occupying a defensible niche below tier-one volume thresholds.
Automotive metal stamping components are precision-formed sheet metal parts produced through progressive die, transfer press, or tandem line processes, typically achieving tolerances of 0.1 mm for body-in-white applications and serving as the structural skeleton of vehicle architectures. The primary purpose spans crash energy management, chassis rigidity, and powertrain mounting integrity across internal combustion, hybrid, and battery electric platforms. Steel remains the dominant material by volume, though aluminum structural parts represent the fastest-expanding margin pool as OEMs chase mass reduction targets. Body panels constitute the most mature product category, with tooling and prototyping stages capturing disproportionate value through die design IP and simulation software integration.
NHTSA Federal Motor Vehicle Safety Standards and EPA Corporate Average Fuel Economy requirements in the United States mandate thinner-gauge high-strength steel and aluminum substitution, directly shaping stamping alloy procurement and press force specifications. ECE R94/R95 crash test protocols in Europe and China's GB/T vehicle safety standards create parallel compliance obligations that stampers must satisfy for market access across production regions. Stakeholders must monitor how battery pack enclosure stampings reshape die investment priorities and whether in-house production of large aluminum castings displaces traditional stamped structural assemblies.
Market Dynamics
Electric vehicle platform architectures are forcing a fundamental reallocation of stamping capacity toward aluminum-intensive structural assemblies, collapsing the traditional steel-dominant tooling investment model that governed automotive metal forming for decades.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:NHTSA-aligned fuel economy mandates in the United States are accelerating high-strength steel and aluminum substitution in body-in-white stampings.
- Hot-stamping process adoption:Advanced high-strength steel forming techniques for passenger safety cells are expanding across European OEM platforms.
- China battery electric vehicle production:Domestic OEM stamping capacity expansion for battery pack enclosures and structural EV architectures is concentrating demand in Chinese manufacturing clusters.
Market Restraints
- Aluminum sheet price volatility:Primary aluminum ingot cost fluctuations compress margin pools for structural component stampers committed to lightweighting contracts.
- Tool-and-die engineering scarcity:North American talent shortages in progressive die design constrain capacity expansion regardless of capital availability.
- Large aluminum casting substitution:Gigacasting processes for rear underbody assemblies threaten to displace multi-part stamped structural weldments in premium EV platforms.
Strategic Opportunities
- India domestic EV manufacturing:PLI scheme incentives for automotive component localization create first-mover advantages for stamping capacity investments in Pune and Chennai corridors.
- Battery pack enclosure stampings:Sealed aluminum tray and lid assemblies represent an emerging product category with limited incumbent competition.
- Digital twin integration:Convergence of die simulation software with real-time press monitoring is enabling predictive maintenance contracts and tooling-as-a-service models.
Industry Challenges
- Progressive die design expertise:The retirement cohort of master toolmakers across Michigan and Ontario engineering centers is outpacing apprenticeship pipeline replenishment.
- Hot-stamping line capex intensity:Press hardening cell investments including laser cutting and tailored blank welding require committed volume contracts to justify equipment utilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Metal Stamping Components Market |
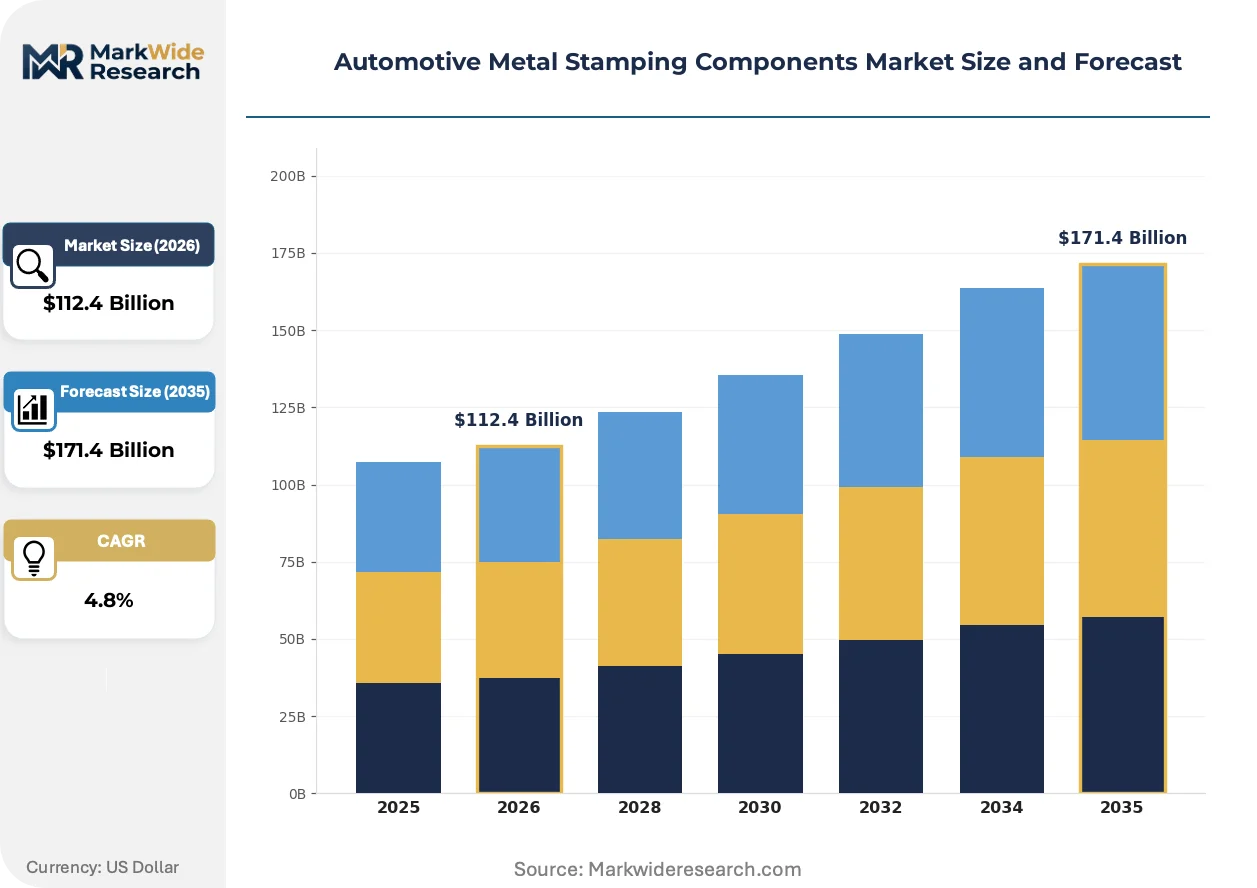
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $171.4 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Panels, Structural Parts, Brackets, Fuel Tanks Material: Steel, Aluminum, Copper, Others Manufacturing Stage: Prototyping, Mass Production, Tooling, Assembly End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Custom Fabricators |
| Companies Covered | AAPICO Hitech Public Company Limited, Magna International Inc., General Motors Company, D&H Industries, American Industrial Co., Ford Motor Company, Gestamp Automoción, Kenmode, Stellantis N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Metal Stamping Components Market Trends and Innovations
Process digitization and material science advances are compressing development cycles for stamped structural components while redefining which manufacturing capabilities command premium positioning.
Aluminum structural stampings are decomposing the traditional steel-body supply hierarchy by enabling single-piece sidewall rings and floor pan assemblies that previously required dozens of welded steel components. European luxury EV platforms are adopting these aluminum-intensive architectures fastest, with stampers investing in 800-ton servo press lines specifically for 6-series aluminum formability. The technology is decomposing established tier-one supplier relationships as OEMs directly source aluminum sheet and co-develop die designs with specialty stampers.
China's GB/T vehicle safety standards are mandating enhanced side-impact protection that favors hot-stamped ultra-high-strength steel B-pillars and roof rails. Domestic OEMs are qualifying local stampers for press hardening processes previously dominated by European and Japanese equipment suppliers. The regulation is compressing development timelines as crash-test certification cycles now overlap with die tryout phases rather than sequencing sequentially.
Fleet procurement of stamped chassis components is consolidating toward direct OEM-stamper relationships that bypass traditional tier-one integrators. Commercial vehicle and ride-hail platform operators are specifying modular stamped subframes with standardized mounting interfaces across multiple vehicle programs. This pattern is most pronounced in North American electric truck and van programs where volume predictability supports dedicated press line investments.
Automotive Metal Stamping Components Market Segmentation
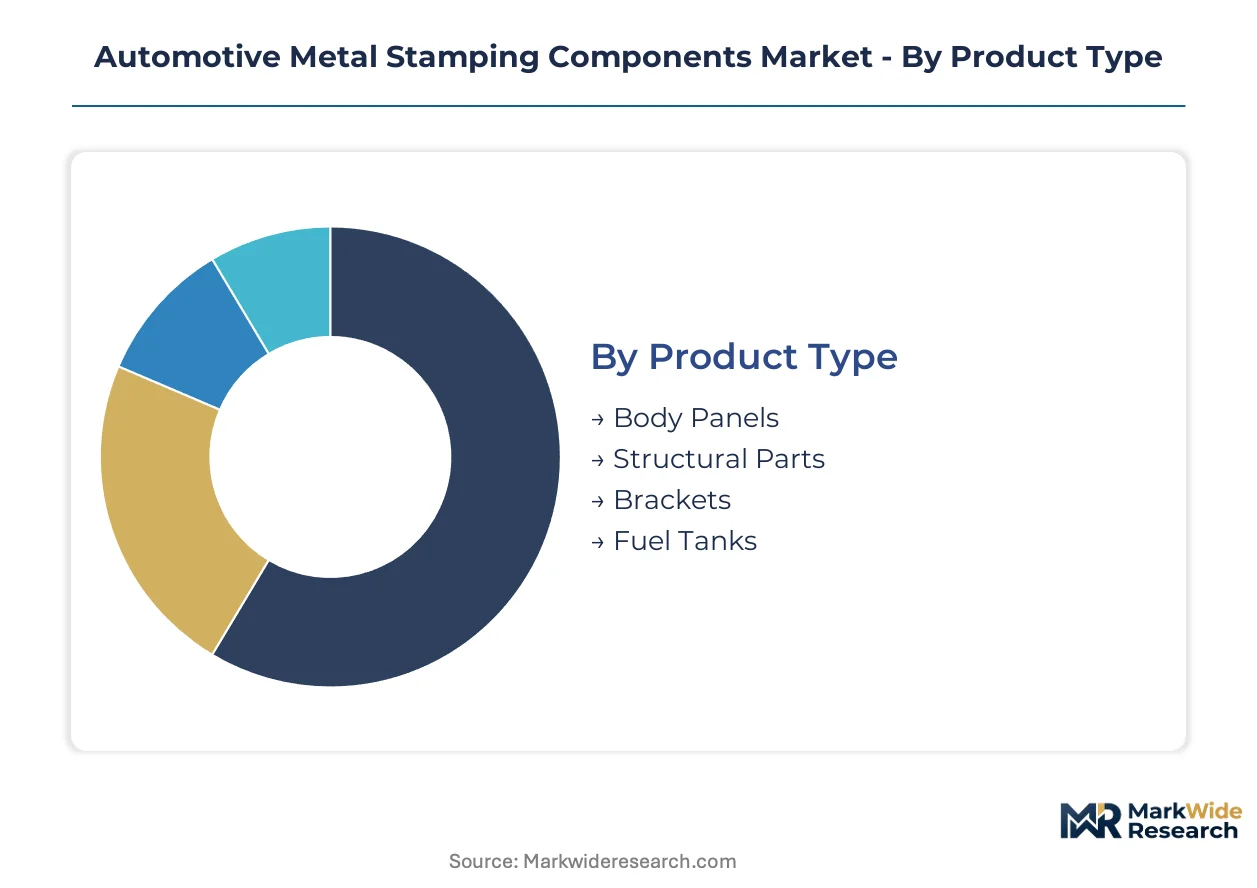
Stamping component procurement splits across fundamentally different technical specifications, material compliance regimes, and production economics. Each segmentation axis reveals distinct margin structures and capital intensity requirements that reshape supplier positioning.
Product Type:
NHTSA crashworthiness testing and EPA mass-reduction mandates differentiate product categories through divergent alloy specifications and die force requirements.
- Structural Parts:Crash energy management components including A-pillars, floor pans, and frame rails achieve tolerances of 0.1 mm for body-in-white integration. Demand concentrates in aluminum-intensive EV platforms across Germany, China, and the United States as OEMs pursue NHTSA five-star ratings and EPA fleet efficiency targets.
- Body Panels:Exterior skin stampings for hoods, doors, and fenders represent the most mature tooling category with established die design IP and simulation software integration. Volume clusters in Chinese manufacturing corridors serving domestic OEM battery electric vehicle architectures.
- Brackets:Precision-formed mounting hardware for powertrain and chassis assemblies.
- Fuel Tanks:Stamped steel and aluminum reservoir enclosures for internal combustion and hybrid platforms.
Structural parts handle the majority of throughput; body panels is the fastest mover on share.
Material:
Raw material procurement economics separate segments through divergent price volatility exposure and forming complexity premiums.
- Steel:Conventional mild steel and advanced high-strength grades dominate volume through established press lines and mature supplier networks. Demand concentrates in North American truck and commercial vehicle programs where EPA fuel economy standards still permit heavier gauge materials.
- Aluminum:5-series and 6-series sheet alloys enable 30-50% mass reduction for EV structural assemblies. Volume expansion concentrates in European luxury platforms and Chinese battery electric architectures requiring 800-ton servo press investments.
- Copper:Electrical busbar and terminal stampings for battery pack interconnections.
- Others:Magnesium and composite-hybrid experimental grades for specialty lightweighting applications.
Steel retains volume dominance; aluminum is climbing the fastest on share.
Manufacturing Stage:
Capital deployment patterns and revenue recognition timing distinguish stages across the production lifecycle.
- Mass Production:High-volume progressive die and transfer press operations serving committed OEM programs generate recurring revenue through multi-year supply agreements. Investment concentrates in dedicated press lines for Volkswagen Group and Stellantis N.V. platforms across Spain and Italy.
- Tooling:Die design, fabrication, and tryout phases capture disproportionate value through engineering IP and simulation software integration. Demand clusters in Ontario and Michigan engineering centers where tool-and-die expertise scarcity commands premium pricing.
- Prototyping:Short-run soft tooling and digital twin validation for new vehicle programs.
- Assembly:Welding and integration of multi-part stamped subassemblies into module deliveries.
Mass production handles the majority of throughput; tooling is expanding most quickly on margin contribution.
End User:
Procurement authority and volume predictability differentiate customer types across the supply hierarchy.
- OEMs:Direct stamping contracts from vehicle manufacturers are consolidating for EV platform architectures, bypassing traditional tier-one integrators. Procurement concentrates in North American electric truck programs and Chinese domestic OEM battery electric expansions.
- Tier-1 Suppliers:System integrators sourcing stamped subassemblies for chassis and body modules.
- Aftermarket Providers:Replacement body panels and structural repair components.
- Custom Fabricators:Low-volume specialty stampings for commercial vehicle upfitters and motorsport applications.
OEMs handle the majority of throughput; tier-1 suppliers are gaining share fastest as outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes automotive metal stamping components through battery electric vehicle architectures that demand aluminum-intensive structural assemblies, while the United States channels demand toward high-strength steel safety cells serving truck and commercial vehicle platforms. Germany anchors European consumption through press-hardened passenger safety systems for premium OEMs. India and Japan round out the major demand centers with diverging material priorities shaped by domestic regulatory frameworks.
China
Domestic OEMs are expanding dedicated stamping capacity for battery pack enclosures and floor pan assemblies across multiple EV platforms. GB/T vehicle safety standards mandate enhanced side-impact protection that favors hot-stamped ultra-high-strength steel B-pillars alongside aluminum structural components. Manufacturing clusters concentrate in Shanghai and the Yangtze River Delta where BYD and NIO have established captive stamping operations for proprietary battery architectures.
United States
EPA Corporate Average Fuel Economy standards and NHTSA crashworthiness mandates accelerate high-strength steel substitution in body-in-white stampings for truck and SUV platforms. The Inflation Reduction Act's domestic content provisions incentivize localized stamping capacity for electric commercial vehicles. Industrial corridors in Michigan and Ohio host engineering centers where tool-and-die expertise scarcity commands premium pricing for progressive die design.
Germany
Press hardening processes for ultra-high-strength steel passenger safety cells dominate stamping investment as Volkswagen Group and BMW pursue ECE R94/R95 crash test certification. The EU Green Deal's carbon border adjustment mechanism shapes aluminum sheet procurement from low-carbon primary sources. Manufacturing concentrates in Bavaria and Baden-Württemberg where Gestamp Automoción operates hot-stamping lines serving Stellantis N.V. and premium OEM platforms.
India
PLI scheme incentives for automotive component localization create first-mover advantages for stamping capacity investments targeting domestic EV manufacturing. BIS certification requirements for vehicle safety components mandate qualification cycles that favor established tool-and-die engineering relationships. Production corridors in Pune and Chennai are attracting dedicated press line investments from tier suppliers seeking to serve Tata Motors and Mahindra electric vehicle programs.
Japan
JIS standards for automotive steel grades maintain demand for advanced high-strength steel stampings in hybrid vehicle platforms where Toyota and Honda balance mass reduction with cost discipline. METI's battery supply chain security initiatives support localized stamping capacity for battery pack structural components. Manufacturing concentrates in Aichi Prefecture and the Chubu region around Nagoya where precision stamping expertise serves both domestic OEMs and export programs.
Automotive Metal Stamping Components Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across material-specific capabilities and regional engineering centers. The upper tier commands multi-year supply agreements through dedicated press line investments and captive die design IP, while specialists occupy defensible niches below volume thresholds. Three archetypes dominate: full-service stampers with OEM-integrated engineering centers, aluminum-focused specialists serving EV platforms, and precision miniature stampers for sensor and electrical subassemblies. Competitive dynamics center on capacity expansion for 800-ton servo press lines and strategic partnerships for battery pack enclosure development.
Among North American fabricators, Magna International Inc. and Kenmode occupy distinct positions within this tiered structure. Magna International Inc. represents the integrated engineering-center archetype through its Ontario and Michigan footprint. Kenmode exemplifies the precision specialist model serving sub-tier volume thresholds. European competition centers on Gestamp Automoción, which anchors the hot-stamping specialist tier serving Volkswagen Group and Stellantis N.V. platforms. These three companies illustrate how geographic clustering and capability specialization fragment competitive positioning across the value chain.
| Leading Market Players |
|---|
| AAPICO Hitech Public Company Limited |
| Magna International Inc. |
| General Motors Company |
| D&H Industries |
| American Industrial Co. |
| Ford Motor Company |
| Gestamp Automoción |
| Kenmode |
| Stellantis N.V. |
| Others |
Pricing and Supply Chain Analysis
Aluminum substitution for conventional steel grades in EV structural assemblies simultaneously redistributes supply geography toward Chinese primary smelters and compresses margin pools for stampers locked into lightweighting contracts. This dual pressure reshapes how procurement teams negotiate long-term offtake agreements versus spot aluminum sheet positions.
Pricing Analysis
Long-term offtake contracts dominate pricing structures for high-volume OEM programs, with three-tier pricing stratification across premium die-design IP, standard progressive die production, and economy-grade brackets. Price differentiation hinges on certification tier for NHTSA crashworthiness compliance and volume scale commitments. Pricing pressure stems from primary aluminum ingot volatility that erodes fixed-price contract margins. Fleet procurement teams at commercial EV manufacturers exhibit highest price sensitivity, while luxury European OEMs prioritize formability performance over unit cost.
Supply Chain Analysis
Port congestion on Asia-North America trade lanes elevates inbound logistics costs for aluminum sheet shipments from Chinese rolling mills to Michigan and Ontario stamping plants. Supply concentrates in China, Germany, and Mexico, with raw material flows drawing from Australian bauxite, Chinese primary aluminum, and German tool steel for die fabrication. Single-source vulnerability runs through Chinese 6-series aluminum alloy supply for EV structural stampings. Distribution runs through direct OEM-stamper relationships that bypass traditional tier-one integrators for battery pack enclosure programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform fragmentation across ICE, hybrid, and battery electric architectures creates specialist niches below volume thresholds of integrated tier-one stampers. Gigacasting substitution threats and aluminum price volatility reward focused capability investments over broad portfolio coverage.
For Market Incumbents: Compound defensive positioning through captive die design IP in Ontario and Michigan engineering centers where toolmaker scarcity commands premium pricing. Secure committed volume contracts for 800-ton servo press lines serving aluminum-intensive EV platforms before gigacasting processes displace multi-part structural weldments. Prioritize backward integration into aluminum sheet tolling arrangements to buffer primary ingot volatility.
For New Entrants and Emerging Players: Lead with battery pack enclosure stampings as the most penetrable white-space category, where sealed aluminum tray and lid assemblies face limited incumbent competition. Target India's PLI scheme corridors in Pune and Chennai for first-mover capacity investments serving Tata Motors and Mahindra electric programs. Deploy digital twin integration as a service-based go-to-market angle, offering predictive maintenance contracts to mid-tier stampers lacking in-house simulation capabilities.
For Investors and Strategic Acquirers: Capital is best deployed toward aluminum-focused specialists with qualified 6-series forming expertise and established OEM engineering relationships, positioned for sustained relevance across the mid-term transition window. Watch for inflection signals in gigacasting adoption rates at premium EV platforms, which would accelerate displacement risk for traditional stamped structural assemblies.
| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Stamping Line Investment | Press hardening cells serving Volkswagen Group and Stellantis N.V. platforms capture ECE R94/R95 certification premiums. |
| Aluminum Servo Press Capacity | 800-ton lines for 6-series sheet formability enable single-piece sidewall rings that decompose steel-body supply hierarchies. |
| Die Design Engineering Center | Ontario and Michigan facilities leverage toolmaker scarcity to command pricing premiums for progressive die IP. |
| Battery Pack Enclosure Qualification | Sealed aluminum tray stampings address emerging GB/T safety mandates with limited incumbent competition. |
| Digital Twin Integration | Convergence of simulation software with real-time press monitoring enables tooling-as-a-service revenue models. |
Research Methodology
The analysis maps structural parts, body panels, brackets, and fuel tank stampings, each validated through Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and tool-and-die engineering directors. Primary fieldwork combined with secondary sources including vehicle production databases, IHS Markit registration data, SEC filings from listed suppliers, and NHTSA crash test certification records. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including OEM production schedules and aluminum sheet consumption reports. The forecast framework models vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derive from regression analysis of historical shipment data correlated with regulatory phase-in timelines. Key inputs include EPA CAFE standard stringency trajectories and China EV penetration assumptions.
The analysis sits within stated boundaries; outcomes outside sustained aluminum price stability and EV platform rollout schedules would require recalibration. Forecasts reflect documented assumptions regarding gigacasting substitution rates and tool-and-die apprenticeship pipeline replenishment. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Exhaust Manifolds Market
Automotive Components
North America Automotive Glass Market
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
Automobile Fluid Pipe Products Market
Automotive Components
Automotive Part Cleaners and Degreasers Market
Automotive Components
Active Suspension Damper Actuator Systems Market
Automotive Components
Automotive Dynamic Spotlight Market
Automotive Components
Automotive Regenerative Braking System Market
Automotive Components
Automotive Gudgeon Pin Market
Automotive Components
Automotive Towbar Market
Automotive Components
Africa and Middle East Automotive Actuators Market
Automotive Components
Mexico Automotive Pneumatic Actuators Market
Automotive Components
Automotive Carbon Fiber Market
Automotive Components
North America Automotive Hydraulic Actuators Market
Automotive Components
Europe and North Africa Automotive Window Regulator Market
Automotive Components
Automotive Exhaust Silencer Market