
 Automotive Metal Market | 2026-2036
Automotive Metal Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Metal Market Intelligence
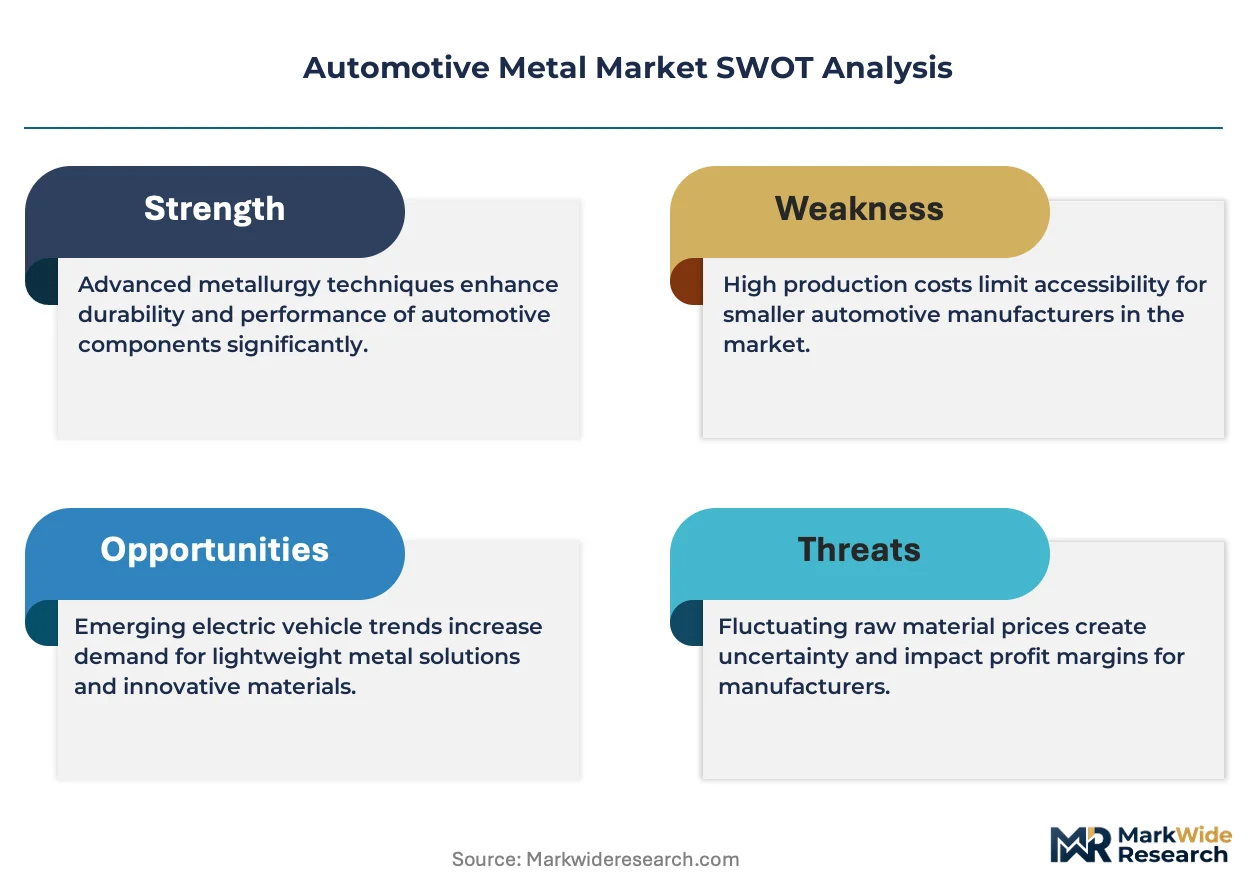
The push for vehicle lightweighting to meet emissions targets, such as those outlined in the EU Green Deal, is expanding the application of advanced high-strength steels and aluminum alloys. ArcelorMittal S.A. leverages its global production network to supply specialized automotive grades. Nucor Corporation competes on its electric arc furnace production model, offering lower-carbon steel options in the United States. POSCO specializes in developing next-generation gigasteel for improved crash performance and weight reduction.
Automotive metals encompass a range of ferrous and non-ferrous materials engineered for vehicle manufacturing. These materials are selected based on properties like high tensile strength, corrosion resistance, and formability for processes like stamping and casting. Their primary purpose is to provide structural integrity, crash safety, and performance. Steel continues to dominate body structure applications due to its cost-effectiveness, while aluminum is gaining share in chassis and engine components to reduce overall vehicle weight.
Regulatory frameworks from the US EPA, the EU's REACH regulation, and China's GB standards collectively govern material composition and end-of-life vehicle recycling. These rules directly influence material selection, pushing for greater use of recyclable and less hazardous metals. Navigating the divergent requirements for material traceability and carbon footprint reporting is now a central strategic challenge for all participants in the supply chain.
Market Dynamics
The central structural force shaping the automotive metal market is the dual mandate for decarbonization and vehicle lightweighting. Electric vehicle adoption accelerates this pressure, demanding materials that reduce mass to extend battery range while also possessing a certifiably lower carbon footprint from production.
Growth Catalysts
- Electric Vehicle Lightweighting:Demand from EV manufacturers for advanced high-strength steels and aluminum alloys to offset battery weight and improve energy efficiency is a primary catalyst. This is especially true for body-in-white structures and battery enclosures.
- Next-Generation Materials:The development of gigasteel offers automakers a path to enhance vehicle safety and reduce weight simultaneously. Its adoption in new vehicle platforms provides a significant performance advantage over traditional materials.
- Regulatory Emissions Targets:Mandates such as the EU Green Deal and US EPA vehicle emissions standards compel automakers to reduce the overall environmental impact of their products, directly influencing metal selection toward lighter and more recyclable options.
Market Restraints
- Input Cost Volatility:The production cost for specialized metals is subject to fluctuations in energy prices, particularly for electric arc furnaces, and the market prices of critical alloying elements like manganese, nickel, and magnesium.
- Substitution from Composites:In high-performance and luxury vehicle segments, advanced carbon fiber composites present a substitution threat to specialty aluminum and steel for non-structural components like body panels and aerodynamic elements.
- Divergent Regulatory Standards:Navigating conflicting material composition and end-of-life recycling regulations, such as the EU's REACH framework versus China's GB standards, creates compliance complexity and increases administrative costs for global suppliers.
Strategic Opportunities
- Battery Enclosure Systems:The shift to electric vehicles creates a significant opportunity in designing and supplying specialized aluminum and steel enclosures for battery packs, which require specific thermal management and crash-resistance properties.
- Domestic Supply Chain Incentives:The US Inflation Reduction Act (IRA) provides tax credits tied to domestic material sourcing for EVs. This creates a direct opportunity for North American metal producers to capture demand from automakers localizing their supply chains.
- Green Steel and Aluminum Premiums:Automakers' commitments to reduce Scope 3 emissions create an opportunity for metal producers to command premiums for certified low-carbon steel and aluminum produced using renewable energy or high-recycled content.
Industry Challenges
- High Capital Expenditure:Transitioning production to lower-carbon methods, such as building new electric arc furnaces or investing in advanced aluminum recycling infrastructure, requires substantial capital investment with long payback periods.
- Carbon Footprint Verification:A primary operational challenge is standardizing the measurement and third-party verification of a metal's carbon footprint across global supply chains, as required by regulations like the EU's CSRD.
- Metallurgical Talent Scarcity:The industry faces a shortage of skilled metallurgists and process engineers capable of developing and scaling the production of next-generation alloys required for advanced automotive applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Metal Market |
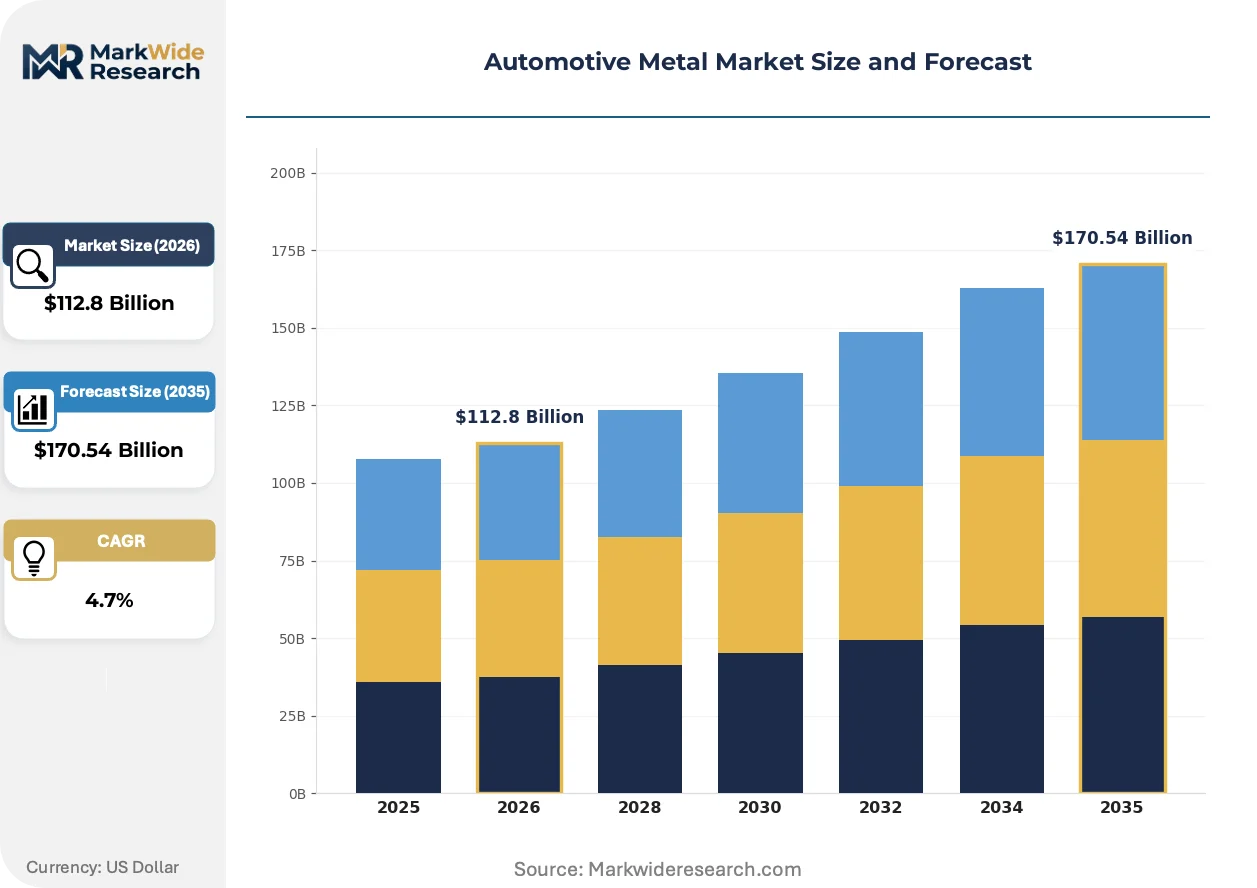
| Market Size in 2026 | $112.8 Billion |
| Market Size in 2035 | $170.54 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Copper, Zinc Application: Body Structure, Engine Components, Fasteners, Chassis End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Manufacturing Stage: Extrusion, Casting, Stamping, Welding |
| Companies Covered | POSCO, JFE Steel Corporation, ArcelorMittal S.A., Hyundai Steel, Nucor Corporation, China Baowu Steel Group Corporation Limited, Thyssenkrupp Steel Europe, Steel Dynamics, Inc., Nippon Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Metal Market Strategic Shifts & Innovations
Material science is increasingly intersecting with sustainability metrics, driving innovation beyond pure performance characteristics. The value of an automotive metal now depends on its lifecycle carbon footprint and recyclability credentials as much as its tensile strength or formability.
Gigasteel is an ultra-high-strength steel designed to provide maximum crash protection with minimal material thickness. EV manufacturers are rapidly adopting this material for critical safety cell components in new body-in-white architectures. In the design of next-generation vehicle platforms, gigasteel is overtaking conventional advanced high-strength steels by offering a superior strength-to-weight ratio that enables significant mass reduction.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a pivotal regulatory shift. This directive compels large companies to disclose detailed information on their supply chain's environmental and social impacts, including Scope 3 emissions. Automotive OEMs in the EU are most directly affected, now prioritizing metal suppliers who can provide transparent, verifiable data on the carbon intensity of their production processes.
A shift from purely transactional sourcing to collaborative co-development partnerships is altering procurement behavior. This change disrupts the traditional model where automakers would source standard-grade metals based primarily on price. This partnership model is most pronounced in Germany’s automotive sector, where carmakers and metal producers work together years in advance to engineer custom alloys for specific vehicle platforms.
Automotive Metal Market Segmentation
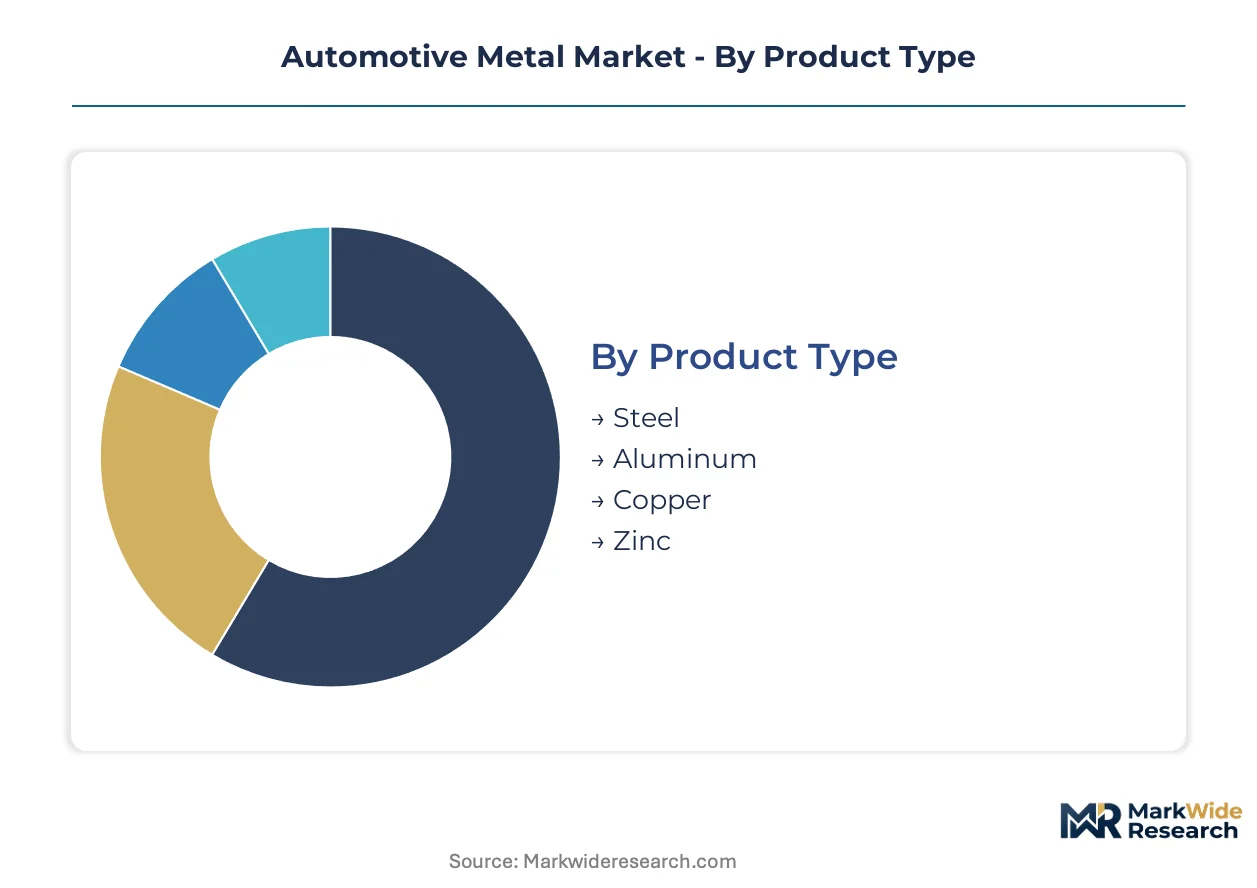
The automotive metal market is segmented to understand how material properties, vehicle applications, and supply chain dynamics influence procurement patterns and technological adoption. This segmentation provides clarity on where innovation and demand are concentrating within the industry.
Product Type:
Buyers in the automotive metal market differentiate their material choices primarily based on the performance characteristics required for specific vehicle components.
- Steel:This ferrous alloy dominates automotive body structures due to its high strength-to-cost ratio and established manufacturing processes. Demand for advanced high-strength steels (AHSS) and gigasteel is concentrating in Germany for new EV platforms, driven by crash safety and lightweighting mandates.
- Aluminum:A lightweight, corrosion-resistant non-ferrous metal increasingly used in chassis, engine blocks, and battery enclosures to reduce overall vehicle mass. North American EV manufacturers are driving demand for specialized aluminum alloys to extend battery range and meet US EPA emissions targets.
- Copper:Primarily utilized in electrical systems, wiring harnesses, and increasingly in electric vehicle battery packs and motors due to its high electrical conductivity. Its application volume is directly proportional to the electrification of vehicle powertrains.
- Zinc:Primarily used for corrosion protection as a coating on steel components, providing sacrificial protection against environmental degradation. It also finds application in certain die-cast parts and specialized alloys within the vehicle.
Steel leads volumes today; Aluminum is gaining share fastest.
Application:
The volume of metal required varies significantly depending on its final application within the vehicle architecture.
- Body Structure:This segment includes the vehicle frame, safety cell, and exterior panels, demanding materials with high tensile strength and impact absorption. Advanced high-strength steels and gigasteel are critical for meeting crash performance standards and reducing weight.
- Chassis:Components like suspension arms, subframes, and wheels fall into this category, requiring a balance of strength, fatigue resistance, and lightweight properties. Aluminum alloys are increasingly displacing steel in these applications to improve vehicle dynamics and fuel efficiency.
- Engine Components:This segment encompasses engine blocks, cylinder heads, and transmission housings, primarily using aluminum and cast iron for thermal management and durability. The shift to electric powertrains is reducing demand for traditional engine metals.
- Fasteners:Bolts, nuts, and rivets constitute this segment, primarily made from steel or specialized alloys for secure assembly and vibration resistance. These smaller components are essential for overall vehicle integrity.
Body structure applications consume the largest share of automotive metals, while chassis components expand rapidly.
End User:
Customer type dictates the scale and specification of metal procurement across the automotive supply chain.
- OEMs:Original Equipment Manufacturers directly purchase large volumes of metals for vehicle assembly, often engaging in long-term contracts for specialized grades. Automakers like Volkswagen and General Motors work directly with metal producers to co-develop custom alloys for new models.
- Tier-1 Suppliers:These companies supply major sub-assemblies and systems directly to OEMs, requiring specific metal forms and grades for their manufacturing processes. Companies like Magna International procure significant quantities of steel and aluminum for body-in-white and chassis systems.
- Aftermarket Providers:This segment includes companies supplying replacement parts and accessories for vehicles already in service. Their metal requirements are typically for standard grades used in repair and maintenance.
- Vehicle Assemblers:These entities focus on the final assembly of vehicles, often sourcing pre-fabricated components from Tier-1 suppliers rather than raw metals directly. Their metal needs are primarily for minor components and fabrication.
OEMs command the largest purchasing power, with Tier-1 suppliers following closely in material acquisition.
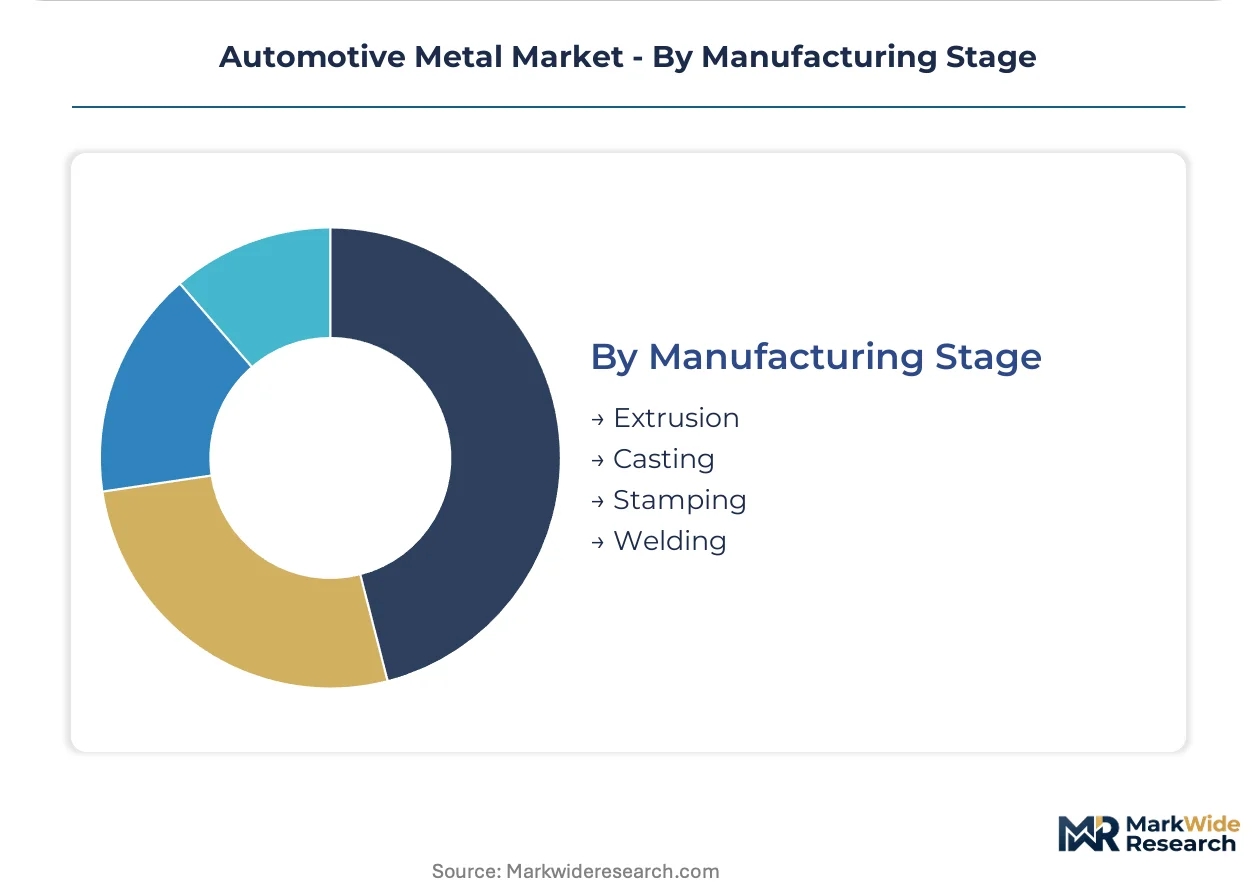
Manufacturing Stage:
The maturity and complexity of manufacturing processes influence the form and grade of automotive metals required.
- Stamping:This high-volume process involves forming metal sheets into complex shapes for body panels, structural components, and chassis parts. Advanced high-strength steels are specifically engineered for their formability and strength in stamping operations.
- Casting:Molten metal is poured into molds to create intricate shapes for engine blocks, transmission housings, and suspension components. Aluminum and iron are commonly cast due to their excellent flow characteristics and mechanical properties.
- Extrusion:Metal is forced through a die to create uniform cross-sectional profiles, commonly used for structural members, trim, and heat sinks, particularly with aluminum alloys. This process is critical for producing lightweight, hollow components.
- Welding:This process joins metal parts permanently, essential for assembling vehicle body structures and chassis components. The weldability of materials like steel and aluminum is a critical factor in their selection for automotive applications.
Stamping remains a foundational process for high-volume components, while casting offers design flexibility for complex shapes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled metallurgical and automotive engineering talent pools anchor regional demand for specialized automotive metals. These concentrations drive innovation in lightweighting and advanced material development across key production centers.
Germany
German automotive manufacturers demand advanced high-strength steels and aluminum alloys for new electric vehicle platforms. The EU Green Deal mandates stringent emissions targets, compelling automakers to prioritize low-carbon materials. In Bavaria and Baden-Württemberg, automotive clusters collaborate with metal producers to engineer custom alloys for next-generation vehicles.
United States
A strong base of metallurgical engineers drives demand for specialized aluminum and steel for EV battery enclosures and body-in-white structures. The US Inflation Reduction Act (IRA) encourages domestic sourcing of materials for electric vehicle manufacturing. Michigan's automotive heartland sees significant investment in localized supply chains for these advanced metals.
China
China's vast manufacturing workforce supports high-volume production of both traditional and electric vehicles, creating immense metal demand. The nation's GB standards influence material composition and recycling requirements for automotive components. The Yangtze River Delta region, particularly around Shanghai, remains a major hub for automotive metal processing and assembly.
Japan
Japanese advanced materials scientists focus on developing next-generation gigasteel for enhanced crash performance and weight reduction. JIS standards guide material specifications and quality control across the automotive supply chain. Aichi Prefecture, home to major automotive OEMs, leads in the adoption of these innovative steel grades.
South Korea
South Korea's high-tech manufacturing expertise fuels demand for specialized steel and aluminum in its rapidly expanding domestic EV production. The country's environmental regulations push for greater use of recyclable and less hazardous metals. Automotive manufacturing centers like Ulsan and Gyeonggi Province are key sites for advanced metal application.
Automotive Metal Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share across the automotive metal value chain. The industry structure shows consolidation among primary metal producers, while specialized fabricators maintain a fragmented landscape. Strategic archetypes include integrated steelmakers, aluminum specialists, and niche alloy developers. Dominant competitive moves involve capacity expansion for low-carbon production and strategic partnerships with automakers for co-development.
Scale-driven producers like ArcelorMittal S.A. and China Baowu Steel Group Corporation Limited occupy a position as global suppliers of diverse metal grades. Nucor Corporation, a North American operator, exemplifies the electric arc furnace production model, offering lower-carbon steel options. These companies anchor the supply of foundational materials essential for vehicle manufacturing platforms worldwide.
| Leading Market Players |
|---|
| POSCO |
| JFE Steel Corporation |
| ArcelorMittal S.A. |
| Hyundai Steel |
| Nucor Corporation |
| China Baowu Steel Group Corporation Limited |
| Thyssenkrupp Steel Europe |
| Steel Dynamics, Inc. |
| Nippon Steel Corporation |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and large integrated producers shape automotive metal supply behavior, influencing pricing discipline across various grades. This concentration impacts negotiation leverage for specialized alloys and commodity metals.
Pricing Analysis
Bundled service offerings, often including technical support and custom alloy development, command higher prices than transactional commodity sales. Price differentiation stems from material properties like gigasteel's strength-to-weight ratio and certified low-carbon production credentials. Pricing softness stems from input cost volatility, particularly for energy-intensive electric arc furnaces. OEMs are less price-sensitive for performance-critical materials, while aftermarket providers prioritize cost-effectiveness.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand for foundational materials like steel and aluminum, often through long-term contracts. Geographic supply concentration centers in China, Germany, and the United States, drawing heavily from global iron ore and bauxite sources. Commodity price volatility for critical alloying elements like manganese and nickel presents a structural risk. Tier-1 suppliers also play a significant role in distributing processed metal forms to vehicle assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive Metal Market presents a margin-expansion story, driven by the increasing demand for premium, low-carbon materials for electric vehicles. This shift allows for higher pricing for certified green steel and specialized aluminum alloys.
For Market Incumbents:Deploy strategic partnerships with automakers to co-develop next-generation alloys for new EV platforms. This mitigates the threat of composite substitution in high-performance segments. Incumbents should invest in electric arc furnace capacity to offer lower-carbon steel options, meeting EU CSRD requirements and securing green steel premiums. Expanding R&D into gigasteel production further strengthens market position.
For New Entrants and Emerging Players:Specialized material distributors provide an accessible entry point for new players offering niche alloys or certified low-carbon metals. Target battery enclosure systems, a rapidly expanding application, with innovative aluminum and advanced steel solutions. Focus on rapid prototyping and custom alloy development to meet specific OEM design requirements. A go-to-market angle emphasizing verifiable carbon footprint data attracts ESG-conscious automakers.
For Investors and Strategic Acquirers:Valuations sit cheapest among specialized alloy developers with proprietary formulations for lightweighting and crash safety. The long-term viability of the market rests on sustained EV adoption and stringent emissions regulations. Target producers with established electric arc furnace operations or advanced aluminum recycling capabilities. A signal to watch is the increasing adoption rate of gigasteel in mainstream vehicle platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Steel Capacity Expansion | Increases supply of low-carbon materials, meeting regulatory demands and securing price premiums from automakers. |
| Gigasteel Co-Development | Accelerates innovation for crash performance and lightweighting, offering a competitive edge in EV platforms. |
| Battery Enclosure Specialization | Captures significant demand from EV manufacturers for critical thermal management and safety components. |
| Supply Chain Localization | Leverages incentives like the US IRA, reducing geopolitical risks and shortening lead times for OEMs. |
| Carbon Footprint Verification | Establishes transparency and trust, enabling compliance with directives like the EU CSRD for global supply chains. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative modeling — were reconciled to ensure data robustness. This study engaged OEM platform engineers, Tier 1 procurement specialists, metal producers' R&D leads, and regulatory affairs experts. Secondary validation drew from vehicle production databases, trade association reports, corporate sustainability disclosures, and relevant regulatory filings. A bottom-up approach for market sizing was triangulated with top-down validation.
Historical market data was cross-referenced with expert panel input to project future trends across the analysis window. The analytical framework modeled market dynamics across product type, application, end user, manufacturing stage, and propulsion architecture. Compound annual growth rates were derived from a synthesis of historical growth patterns and anticipated shifts in demand. Key forecast inputs included electric vehicle adoption rates and material substitution trends.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to raw material price volatility and regulatory shifts. Forecasts reflect assumptions regarding technological advancements in composites and EV battery density. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Electric Vehicle Fluid Lubricants Market
Automotive Components
Automotive Glass Film Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Europe Automotive Heat Exchanger Market
Automotive Components
Europe Torque Vectoring Market
Automotive Components
Global Automotive Condenser Market
Automotive Components
Italy Automotive Sunroof Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Automotive Carbon Ceramic Brakes Market
Automotive Components
Beryllium Copper for Automobile Market
Automotive Components
Automotive Resonator Market
Automotive Components
Automotive Pedals Market
Automotive Components
Automotive Comfort Actuators Market
Automotive Components
Global Automotive Plastic Compounding Market
Automotive Components
Global Automotive Sun Visor Market
Automotive Components
Global Automatic Lubrication System Market