
 Global Automotive Powertrain Systems Market | 2026-2036
Global Automotive Powertrain Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Powertrain Systems Market Intelligence
China's massive investment in electric motor and battery manufacturing is narrowing the technology gap previously held by legacy powertrain producers. This shift creates a new competitive dynamic for established firms. Robert Bosch GmbH leverages its extensive R&D in hybrid systems to maintain a strong position. Meanwhile, Denso Corporation specializes in high-efficiency thermal management for electric powertrains, and BorgWarner expands its portfolio of integrated drive modules for electric vehicles.
Automotive powertrain systems comprise the components that generate and deliver power to the wheels, including the engine or motor, transmission, and drivetrain. These systems are defined by performance metrics such as torque output, fuel efficiency, or energy consumption in kWh per 100 km. While internal combustion engines still dominate volume, electric motor systems represent the fastest-growing product type. The transition is most pronounced in the passenger vehicles segment, with commercial vehicles presenting a complex but high-value opportunity for hybrid and hydrogen technologies.
Regulations from bodies like the US EPA, China's MEE, and frameworks such as the EU Green Deal directly influence powertrain design through stringent emissions and fuel economy standards. These mandates compel automakers and Tier-1 suppliers to accelerate investment in electric and hybrid technologies. Navigating the transition requires suppliers to manage a dual portfolio, balancing declining yet profitable internal combustion engine components with strategic investments in next-generation electric drive units.
Market Dynamics
The imperative to manage a dual portfolio defines the automotive powertrain market. Suppliers must sustain profitable internal combustion engine (ICE) component lines while simultaneously funding capital-intensive research and manufacturing for next-generation electric and hybrid systems, creating significant strategic and financial tension.
Growth Catalysts
- Stringent Emissions Mandates:Regulatory frameworks like the EU Green Deal and China's dual carbon goals directly compel automakers to shift production toward electric and hybrid vehicles, creating guaranteed demand for advanced powertrain components like high-efficiency electric motors and inverters.
- Battery Technology Advancement:Innovations in battery chemistry and thermal management systems are improving the energy density and charging speeds of electric vehicles. This enhancement makes EVs more practical for a wider range of consumers and applications, including light commercial vehicles.
- Government Incentives and Subsidies:National policies, particularly in China and parts of Europe, provide direct consumer rebates and manufacturer tax credits for electric vehicle purchases. These incentives accelerate the displacement of traditional ICE powertrains in the passenger car segment.
Market Restraints
- Raw Material Price Volatility:The production of electric motors and batteries depends heavily on materials like lithium, cobalt, and rare earth metals. Price fluctuations and supply chain concentration in specific geographies for these materials create significant cost uncertainty for manufacturers.
- Inadequate Charging Infrastructure:The limited availability of public high-speed charging stations, especially for commercial and heavy-duty vehicles, remains a significant barrier. This infrastructure gap slows the adoption of all-electric powertrains in long-haul logistics and fleet operations.
- High Upfront Cost:Despite falling battery prices, the initial purchase price of electric and advanced hybrid vehicles remains higher than their ICE counterparts. This cost differential is a major deterrent for price-sensitive consumers and fleet buyers in many markets.
Strategic Opportunities
- Hydrogen Fuel Cell Systems:For heavy-duty and long-haul commercial vehicle applications, hydrogen fuel cell powertrains offer a compelling alternative to battery-electric systems by providing longer range and faster refueling. This segment represents a significant white-space opportunity.
- Hybridization in Emerging Markets:In regions with underdeveloped EV charging infrastructure, such as India and Southeast Asia, hybrid powertrain systems offer a transitional pathway. These systems provide improved fuel efficiency without creating range anxiety for consumers.
- Powertrain Software and Services:The increasing complexity of electric drive units creates opportunities for high-margin, software-based services. This includes over-the-air performance upgrades, predictive maintenance analytics, and battery health management solutions for fleet operators.
Industry Challenges
- Talent and Skill Gaps:The transition from mechanical to electrical and software-centric engineering creates a severe shortage of qualified talent. Expertise in power electronics, battery management software, and systems integration is particularly scarce, hindering product development timelines.
- Supply Chain Reconfiguration:Shifting from a century-old ICE supply chain to one based on batteries, semiconductors, and electric motors requires a complete overhaul of sourcing strategies and supplier relationships. This process is complex, costly, and fraught with logistical risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Powertrain Systems Market |
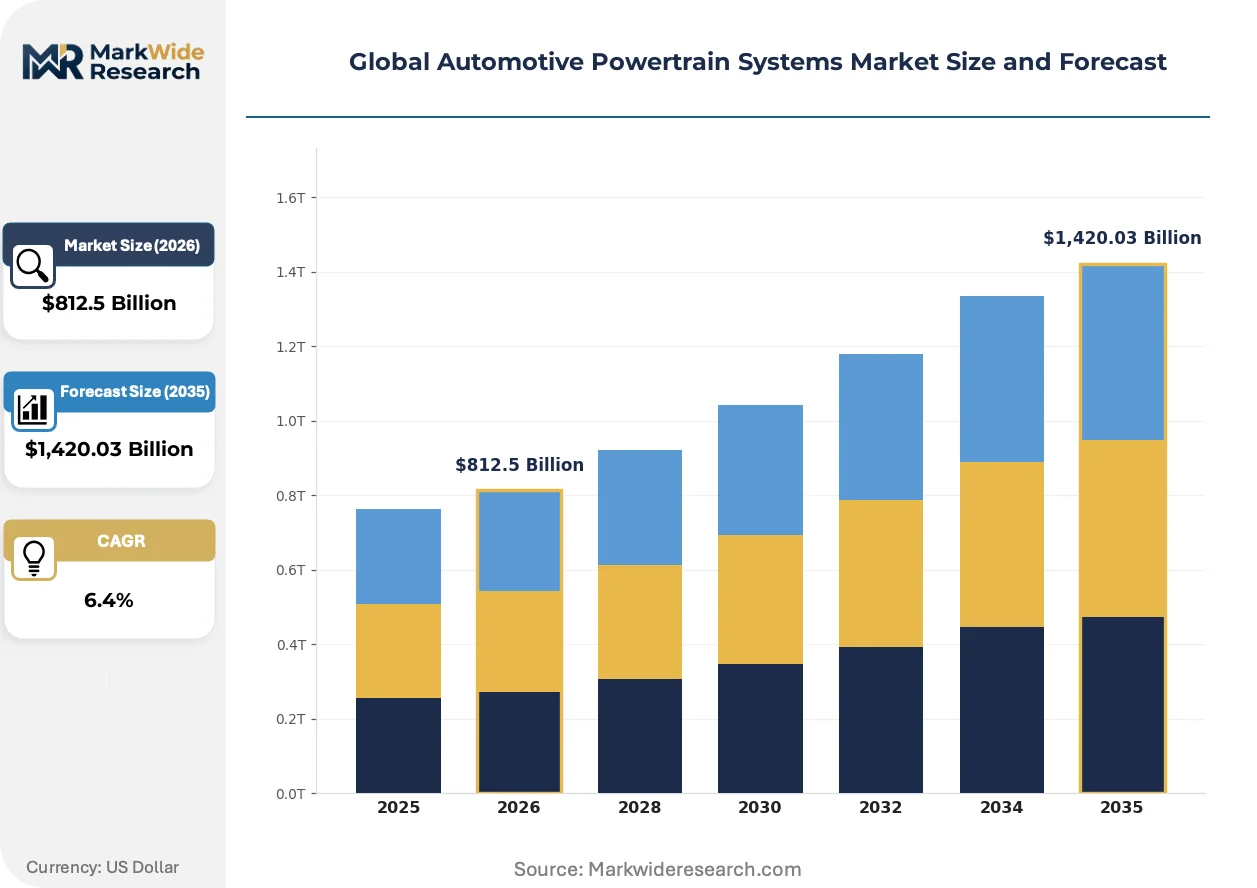
| Market Size in 2026 | $812.5 Billion |
| Market Size in 2035 | $1,420.03 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Combustion Engine, Electric Motor, Transmission System, Hybrid Drive, Fuel Cell, Turbocharger Technology: Gasoline, Diesel, Electric, Hybrid, Hydrogen, Continuously Variable Transmission Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Specialty Equipment, Industrial Vehicles, Recreational Vehicles End User: Vehicle Assemblers, Tier-1 Suppliers, Aftermarket Providers, Engine Developers, Fleet Operators, Energy Providers |
| Companies Covered | Robert Bosch GmbH, ZF Friedrichshafen AG, Denso Corporation, Magna International, Aisin Corporation, Toyota Motor Corporation, Hyundai Motor Company, BorgWarner, Schaeffler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Powertrain Systems Market Strategic Shifts & Innovations
The fundamental architecture of automotive powertrains is undergoing a profound transformation driven by electrification and software integration. This shift redefines component value, moving it from mechanical precision in engines and transmissions to efficiency and intelligence in electric drive units and their control systems.
Integrated drive modules (IDMs) combine the electric motor, power electronics, and gearbox into a single, compact unit. Electric vehicle manufacturers are rapidly adopting these modules to simplify vehicle assembly, reduce weight, and optimize overall system efficiency. The market's focus is migrating from sourcing discrete components to procuring these fully integrated systems from specialized Tier-1 suppliers.
Stringent emissions standards from regulators like the US EPA are forcing an accelerated pivot in the commercial vehicle sector. The agency's rules for heavy-duty vehicles mandate significant reductions in nitrogen oxides and particulate matter, making current diesel engine technology increasingly non-compliant. This regulatory pressure directly impacts the Class 8 truck segment, compelling investment in hybrid, battery-electric, and hydrogen fuel cell alternatives.
Fleet operators and consumers are increasingly focused on powertrain characteristics that can be upgraded via over-the-air (OTA) software updates. This behavioral shift disrupts the traditional model of fixed hardware performance, enabling automakers to offer post-sale enhancements for acceleration, efficiency, or charging speed. This trend is most advanced in the premium passenger EV segment across Europe and China.
Global Automotive Powertrain Systems Market Segmentation
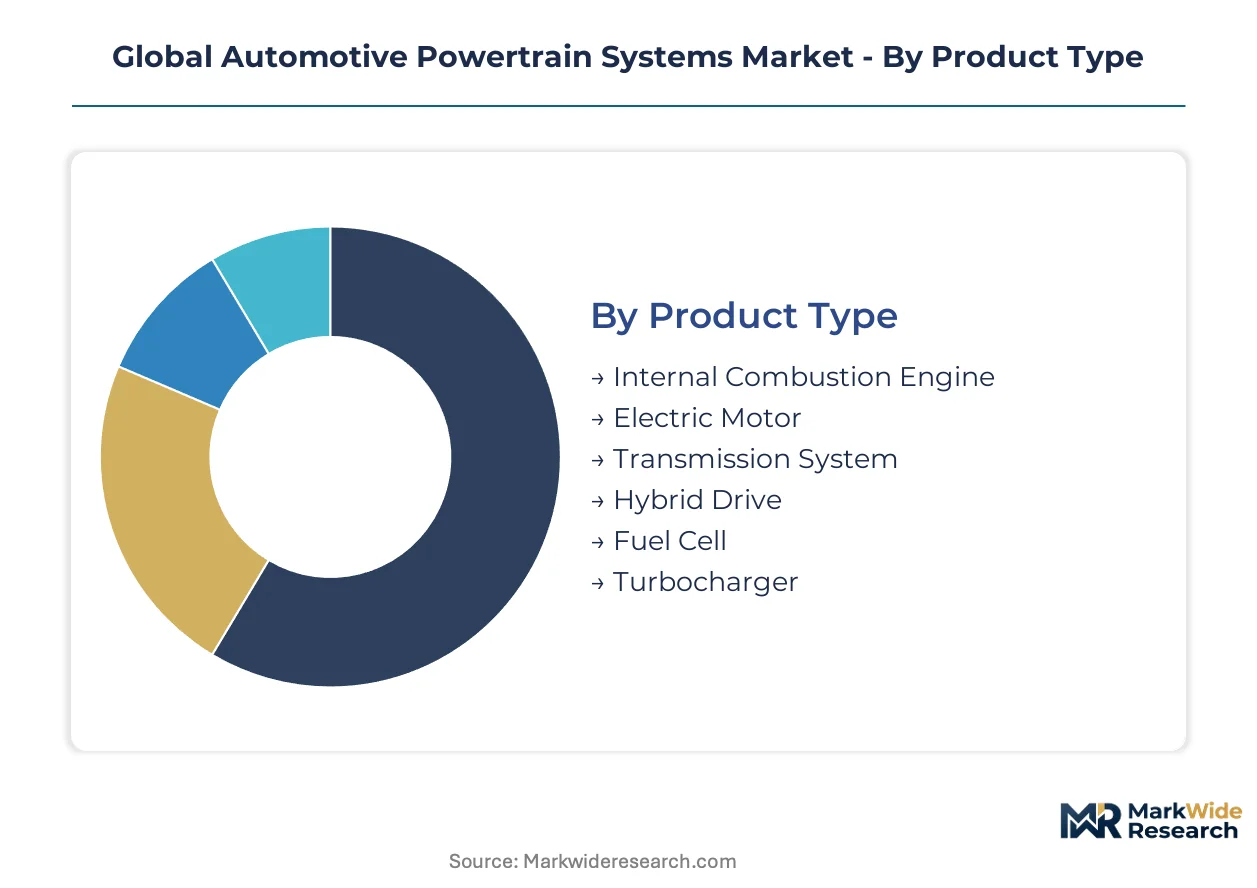
The automotive powertrain systems market is segmented to provide a granular understanding of its diverse components and end-user applications. This detailed classification helps stakeholders identify specific growth areas, technological shifts, and strategic investment opportunities across the value chain.
Product Type:
The after-sales service intensity for automotive powertrain systems varies significantly, driven by component complexity and maintenance cycles.
- Internal Combustion Engine:This system converts fuel combustion into mechanical power, typically involving pistons and crankshafts. Demand for these engines still dominates volume in many global markets, particularly where electric vehicle infrastructure is nascent.
- Electric Motor:An electric motor converts electrical energy into mechanical energy for propulsion, often integrated with a power electronics inverter. Demand for these motors is concentrating in manufacturing hubs across China and Germany, driven by stringent emissions regulations.
- Transmission System:This component manages power delivery from the engine or motor to the wheels, optimizing vehicle performance and fuel efficiency. Traditional mechanical transmissions are evolving to accommodate electric and hybrid powertrains.
- Hybrid Drive:Combining an internal combustion engine with an electric motor, hybrid drives optimize fuel efficiency and reduce emissions. Passenger vehicle applications in emerging markets like India show significant uptake.
- Fuel Cell:Fuel cell systems generate electricity through an electrochemical reaction between hydrogen and oxygen, emitting only water. This technology offers a compelling solution for heavy-duty commercial vehicles requiring long range.
- Turbocharger:A turbocharger increases engine power by forcing more air into the combustion chamber, improving efficiency and performance. These devices are common in modern gasoline and diesel internal combustion engines.
By volume, Internal Combustion Engines lead the market. By growth pace, Electric Motors represents the fastest-growing trajectory.
Technology:
Cost tier differentiation strongly influences technology adoption across various automotive segments.
- Gasoline:This technology employs spark-ignited internal combustion engines for propulsion, remaining a high-volume power source globally. Gasoline engines continue to benefit from established infrastructure and lower upfront costs.
- Diesel:Utilizing compression-ignition engines, diesel technology is prevalent in commercial vehicles and heavy-duty applications. Despite regulatory pressures, its torque and fuel efficiency remain critical for specific fleet operations.
- Electric:This technology utilizes battery-powered electric motors for vehicle propulsion, offering zero tailpipe emissions. Demand is concentrating in Europe and China due to government incentives and stringent emissions standards.
- Hybrid:Hybrid technology integrates an internal combustion engine with an electric motor, optimizing fuel efficiency and reducing emissions. Passenger vehicle applications in emerging markets like India show significant uptake.
- Hydrogen:This technology relies on fuel cells to generate electricity from hydrogen, targeting long-haul commercial transport. Hydrogen fuel cell systems offer extended range and rapid refueling for heavy-duty vehicles.
- Continuously Variable Transmission:CVTs provide seamless gear ratio changes for improved fuel economy in passenger cars. This technology enhances driving comfort by eliminating traditional gear shifts.
Supply chain reconfiguration is particularly pronounced for Electric and Hybrid technologies due to new material requirements.
Application:
Volume dynamics vary significantly across automotive powertrain applications, reflecting diverse operational requirements.
- Passenger Vehicles:Designed for personal transport, this segment drives demand for electric and hybrid powertrains. Demand is high in Europe and China due to consumer incentives and environmental regulations.
- Commercial Vehicles:This segment includes trucks and buses, presenting complex opportunities for hybrid and hydrogen technologies. Regulations from the US EPA and China's MEE are forcing a shift towards lower emissions powertrains.
- Off-Road Vehicles:These vehicles operate in challenging terrains, requiring robust powertrains with high torque output. Durability and reliability are paramount for off-road applications.
- Specialty Equipment:This category encompasses vehicles like agricultural machinery and construction equipment, demanding durable and efficient power solutions. Powertrain reliability is critical for continuous operation.
- Industrial Vehicles:Used in manufacturing and logistics, industrial vehicles often require electric or hybrid options for indoor operation. Forklifts and tuggers are prime examples in this segment.
- Recreational Vehicles:Including RVs and ATVs, this segment prioritizes powertrain performance and reliability for diverse leisure activities. Powertrain systems must handle varying loads and environments.
Higher margin opportunities exist within the Commercial Vehicles segment, particularly for advanced hybrid and hydrogen solutions.
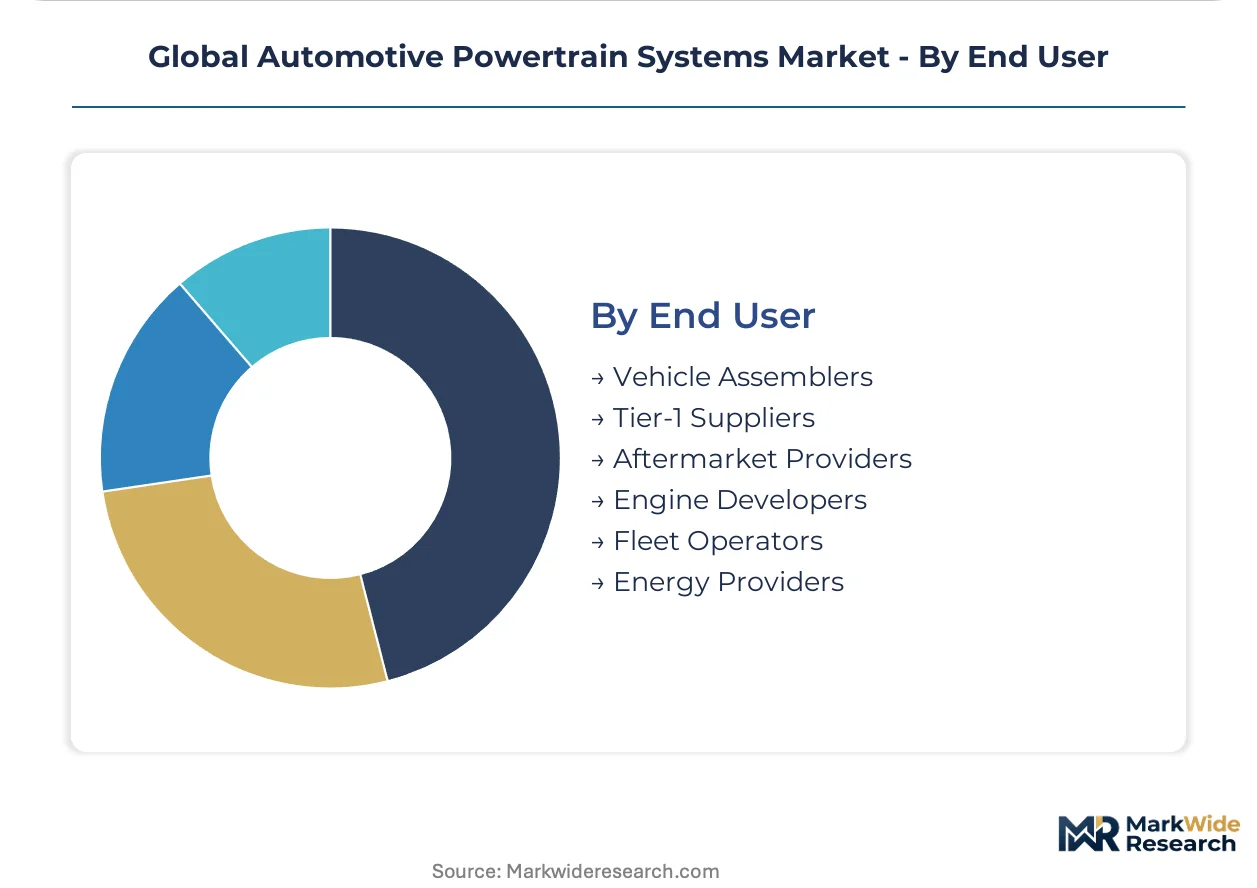
End User:
Customer type segmentation highlights distinct procurement behaviors and strategic priorities within the powertrain ecosystem.
- Vehicle Assemblers:These entities integrate powertrain systems into finished vehicles, driving demand for advanced electric drive units. Automakers in Germany and China are making significant investments in new production lines.
- Tier-1 Suppliers:These companies develop and manufacture major powertrain components and integrated modules, such as those from Robert Bosch GmbH and BorgWarner. These suppliers manage a dual portfolio of ICE and EV components.
- Aftermarket Providers:These businesses supply replacement parts and service for existing powertrain systems, adapting to new electric vehicle components. They ensure the longevity and maintenance of vehicle fleets.
- Engine Developers:This group focuses on designing next-generation power units, including advanced internal combustion engines and electric motors. Their work drives innovation in powertrain efficiency.
- Fleet Operators:These entities manage large vehicle fleets, increasingly seeking electric and hybrid solutions for operational efficiency and regulatory compliance. Total cost of ownership is a key consideration.
- Energy Providers:These companies deliver fuel or electricity for vehicle operation, adapting infrastructure to support electric and hydrogen powertrains. Their role is critical for widespread adoption of new technologies.
The maturity curve for end-user engagement with electric powertrains is steepest among Fleet Operators and Vehicle Assemblers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ministry of Ecology and Environment (MEE) mandates for lower emissions profoundly influence the global automotive powertrain market. These stringent regulations, coupled with significant government incentives, accelerate the shift towards electric motor and hybrid drive systems. This strategic pivot reshapes manufacturing landscapes and investment priorities across key automotive regions.
China
Demand for electric motors and battery systems is concentrating due to the country's dual carbon goals. The MEE's stringent emissions standards compel automakers to prioritize zero-emission vehicle production. Manufacturing hubs in the Yangtze River Delta are rapidly expanding capacity for advanced electric powertrain components.
Germany
Europe's transition to electric and hybrid powertrains drives significant demand for advanced components. The EU Green Deal mandates stringent emission reductions, accelerating this technological shift. Stuttgart and Munich remain key centers for automotive R&D, focusing on next-generation electric drive units and power electronics.
United States
Stringent US EPA regulations for heavy-duty vehicles compel investment in alternative commercial vehicle powertrains. Fleet operators seek hybrid and hydrogen solutions to meet these new compliance benchmarks. Detroit's automotive cluster is retooling production lines for electric truck and bus powertrains.
India
Passenger vehicle applications in India show significant uptake for hybrid powertrain systems. The country's PLI scheme encourages local manufacturing of advanced automotive components, including hybrid drive units. Chennai, a major automotive hub, is seeing increased investment in hybrid powertrain assembly facilities.
Japan
Innovation in high-efficiency thermal management for electric powertrains drives demand for specialized components. Japan's METI promotes research and development in fuel cell technologies, particularly for heavy-duty transport. Nagoya's automotive industry continues to lead in hybrid technology advancements and electric vehicle component production.
Global Automotive Powertrain Systems Market Key Industry Players
Established automotive suppliers and specialized EV component manufacturers split the market for automotive powertrain systems. The competitive landscape shows a blend of legacy players adapting to electrification and new entrants focusing solely on electric drive units, creating a dual portfolio challenge. Strategic archetypes include diversified Tier-1 component giants, specialized power electronics providers, and integrated module assemblers. Dominant competitive moves involve significant capital investment in R&D for electric technologies and strategic partnerships to secure critical material supply chains.
Diversified Tier-1 suppliers like Robert Bosch GmbH, a German entity, leverage their extensive R&D capabilities across hybrid systems. Denso Corporation, a Japanese manufacturer, occupies a position as a specialist in high-efficiency thermal management for electric powertrains. Meanwhile, BorgWarner Inc., a US-based firm, exemplifies the trend of expanding portfolios into integrated drive modules for electric vehicles, showcasing a strategic pivot from traditional ICE components.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Magna International |
| Aisin Corporation |
| Toyota Motor Corporation |
| Hyundai Motor Company |
| BorgWarner |
| Schaeffler AG |
| Others |
Cost & Logistics Intelligence
China's Yangtze River Delta manufacturing hubs, with their expanding capacity for electric powertrain components, exert significant influence over global pricing dynamics. This concentration of production capacity dictates the cost structure for various electric motor systems.
Pricing Analysis
Regional price spreads for automotive powertrain systems reflect varying regulatory pressures and local manufacturing costs. The dominant pricing model remains per-unit transactional, heavily influenced by performance metrics like torque output and kWh efficiency. Price differentiation stems from component quality grade and after-sales service bundling for complex units. Pricing softness for traditional internal combustion engine components reflects declining demand, while premium passenger EV assemblers show lower price sensitivity.
Supply Chain Analysis
Specialized Tier-1 suppliers like Robert Bosch GmbH and Denso Corporation hold significant contract manufacturing capacity for complex powertrain components. Geographic supply concentration for electric motor systems centers in China and Germany, while critical raw materials like lithium and rare earth metals draw from concentrated global sources. Single-source vulnerability for specific power electronics components poses a structural risk. Distribution runs through established channels to vehicle assemblers and aftermarket providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
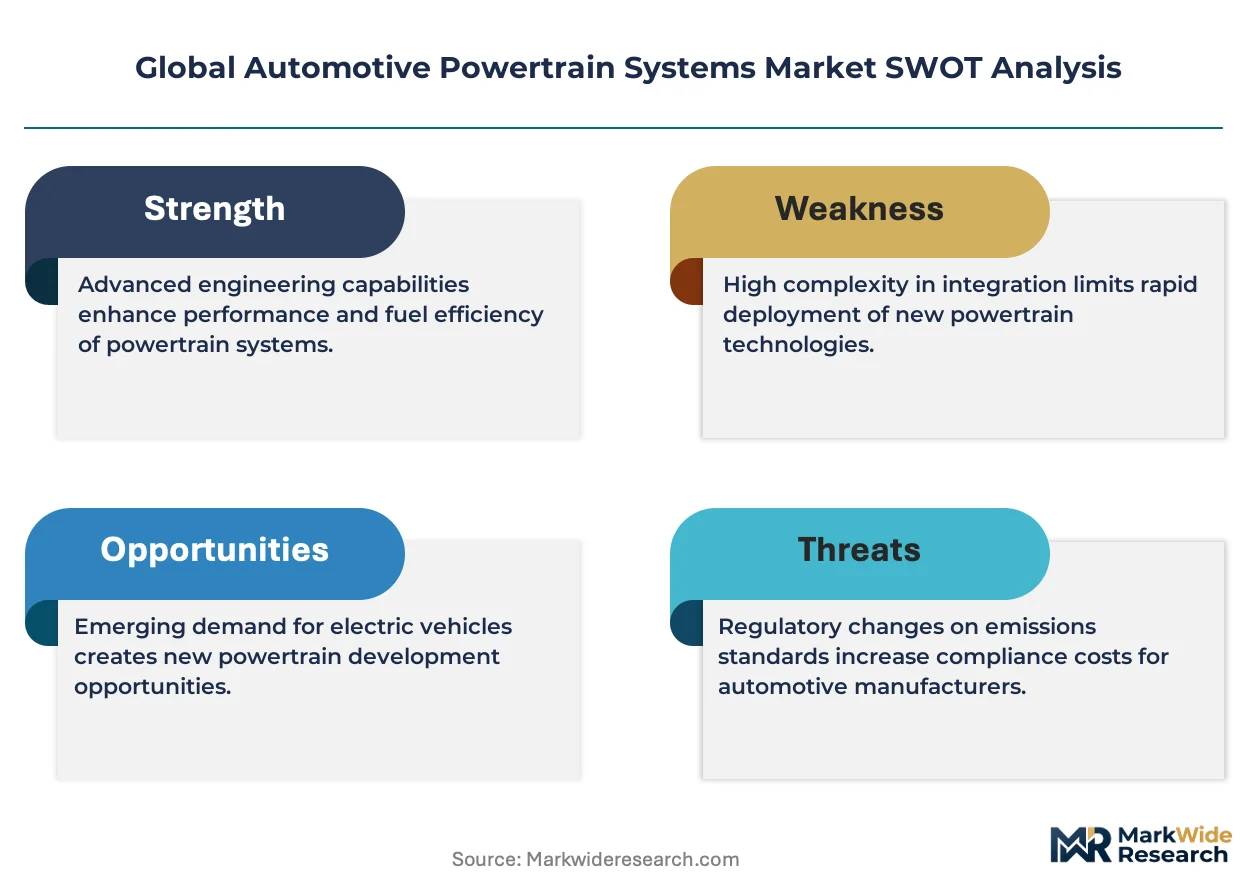
The automotive powertrain market requires a robust substitution defense as internal combustion engine systems face displacement by electric motor and hybrid drive technologies. This fundamental shift compels established players to re-evaluate their core business models.
For Market Incumbents: Entrench existing market share through aggressive investment in hybrid systems R&D, leveraging extensive technical expertise. Managing a dual portfolio of declining ICE components and growing EV units requires strategic capital allocation. The threat of rapid electric motor systems adoption necessitates strategic partnerships to secure critical material supply chains. Robert Bosch GmbH exemplifies this approach by maintaining a strong position in hybrid technologies.
For New Entrants and Emerging Players: Pursue white-space opportunities in hydrogen fuel cell systems for heavy-duty commercial vehicles, offering longer range and faster refueling. Software-based services for electric drive units, including predictive maintenance analytics, present another high-margin target. The commercial vehicles segment is most penetrable for specialized, integrated solutions. A compelling go-to-market angle involves offering complete integrated drive modules with advanced software capabilities.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy Tier-1 suppliers divesting their non-core internal combustion engine component divisions. The long-term viability of this market hinges on sustained global transition to electrification over the next decade. Specialized power electronics firms and battery management software developers represent attractive acquisition archetypes. A critical signal to watch is the accelerated buildout of public high-speed charging infrastructure across major markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Securing long-term battery supply ensures consistent production for electric vehicle assemblers. |
| Software-Defined Powertrain Investment | Developing advanced software for electric drive units enhances vehicle performance and offers OTA upgrade potential. |
| Geographic Manufacturing Footprint Expansion | Establishing production in key regions like Germany reduces logistics costs for European OEMs. |
| Charging Infrastructure Partnership | Collaborating on charging networks accelerates electric vehicle adoption for fleet operators. |
| Integrated Drive Module Development | Combining electric motor, power electronics, and gearbox simplifies vehicle assembly for manufacturers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews, validating findings against extensive secondary research. Key stakeholders included Tier-1 supplier procurement leads, OEM platform engineers, fleet operators, and energy providers. Secondary data sources comprised US EPA regulations, EU Green Deal documents, China MEE reports, and global vehicle production databases. This approach enabled robust bottom-up and top-down triangulation of market estimates.
Scenario-based modeling calibrated the forecast framework, integrating historical trends with future projections across the analysis window. Segmentation dimensions included product type, technology, application, end user, and regional manufacturing hubs. Compound annual growth rates were derived from a comprehensive analysis of drivers. Key industry-specific forecast inputs included battery cost trajectories and evolving regulatory compliance timelines.
Macroeconomic conditions sit as an overlay; deviation in global GDP or energy prices would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Quarterly review of raw material volatility and EV infrastructure buildout is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Torque Limiter Market
Powertrain
Global Automotive Dyno Market
Powertrain
Japan Automotive Engine Oils Market
Powertrain
Global Industrial Engine Market
Powertrain
Power Transmission Gearbox Market
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Clutch Hub Puller Market
Powertrain
Crankshaft Position Sensor Market
Powertrain
Internal Combustion Engine Market
Powertrain
Diesel Engine Management System Market
Powertrain
Car Oil Filter Market
Powertrain
Engine Support Bar Market
Powertrain
Transmission Oil Filters Market
Powertrain
Automotive Transmission System Market
Powertrain
LNG Engine Market
Powertrain
Positive Crankcase Ventilation Valve Market