
 Global Industrial Engine Market | 2026-2036
Global Industrial Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Engine Market Outlook
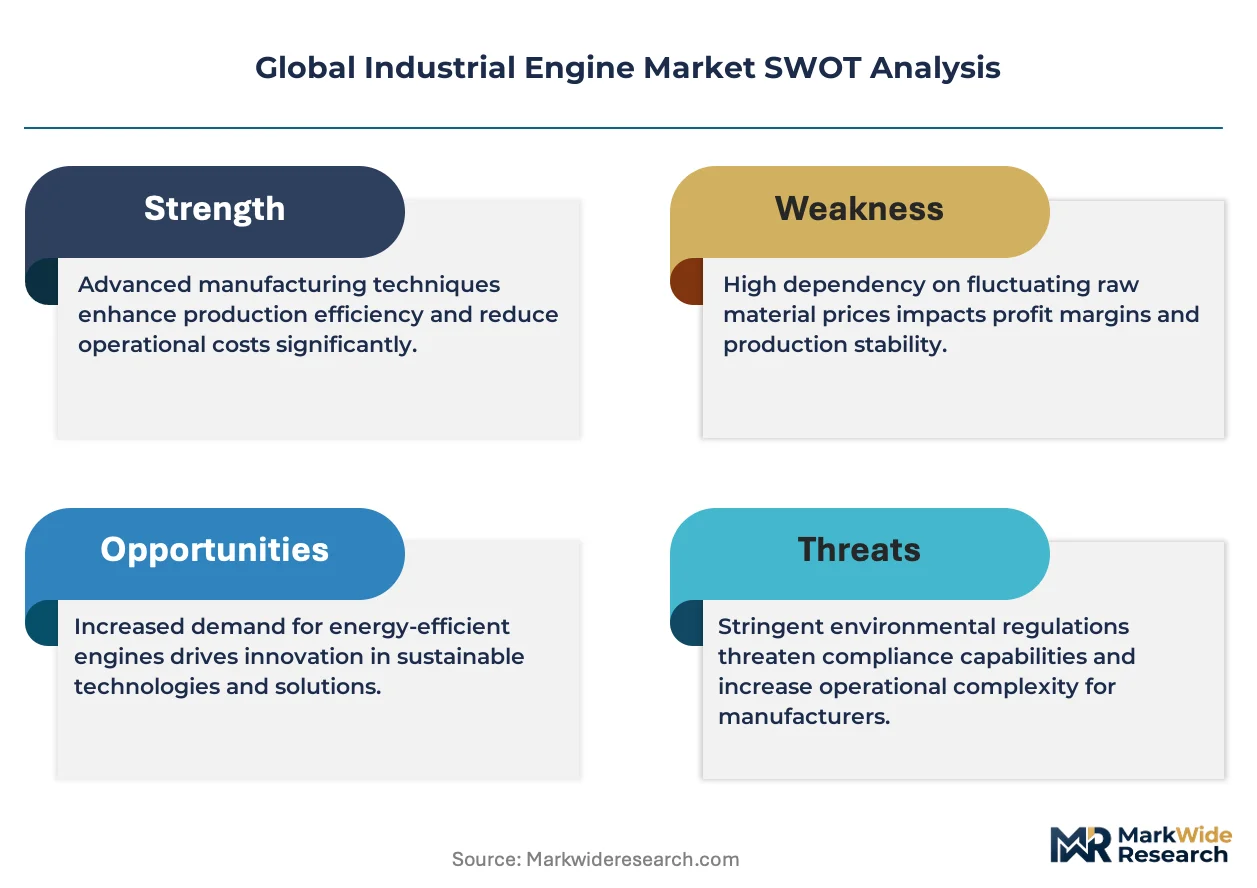
Performance-based maintenance contracts is recalibrating how industrial engine suppliers monetize long-term customer relationships. Cummins Inc. leverages its global service network to embed predictive maintenance into power system contracts. Caterpillar Inc. anchors aftermarket parts revenue through condition monitoring platforms tied to engine health. Wärtsilä Corporation differentiates by integrating remote diagnostics into marine and energy engine portfolios.
Industrial engines are reciprocating or rotary internal combustion power units rated typically from 25 kW to over 20 MW, designed for continuous or prime-duty operation in off-highway, stationary, and marine environments. Diesel engines occupy the largest share of installed base and aftermarket revenue due to torque density and fuel infrastructure maturity. Gas engines represent the fastest-expanding product type as methane and hydrogen fuel variants gain traction in power generation and marine propulsion.
EPA Tier 4 Final in the United States, EU Stage V in Europe, and China's MEE emission enforcement collectively tighten particulate and NOx limits, forcing engine makers to adopt aftertreatment systems and alternative fuels. ISO 8178 test cycles and IMO Tier III marine standards add compliance layers for cross-border equipment sales. Stakeholders must weigh fuel pathway bets against regulatory phase-ins that favor hydrogen combustion and carbon-intensity metrics over legacy diesel benchmarks.
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions standards are forcing fundamental redesigns of combustion architectures, compressing development cycles and elevating aftertreatment costs across the installed base.
Growth Catalysts
- China's MEE enforcement:State-backed infrastructure procurement sustains heavy demand for construction and mining machinery, pulling high-horsepower diesel and gas engine volumes through domestic OEMs.
- Methane fuel pathways:Gas engines rated for biogas and landfill gas are displacing diesel in distributed power generation, supported by carbon-intensity accounting frameworks in EU member states.
- Australian mining productivity targets:Fleet operators are upgrading to higher-horsepower engines to reduce cycle times and fuel burn per ton moved, tightening replacement intervals.
Market Restraints
- Aftertreatment cost stack:Selective catalytic reduction and diesel particulate filter systems add material cost and packaging volume, squeezing margin on sub-75 kW engines.
- Platinum group metal concentration:Catalyst substrates depend on South African and Russian palladium supply, exposing procurement to export restriction risk.
- Hydrogen infrastructure gap:Hydrogen combustion variants face fuel availability constraints that limit deployment to captive industrial sites with on-site electrolysis.
Strategic Opportunities
- Indonesia's nickel processing expansion:Smelter and refinery construction is creating demand for stationary prime-power engines in remote island locations with weak grid connectivity.
- IMO Tier III marine retrofit:Harbor craft and inland waterways in Germany and the Netherlands face engine replacement mandates, opening aftermarket volume for compliant propulsion systems.
- Digital twin integration:Physics-based engine modeling combined with IoT sensor streams enables predictive maintenance contracts that capture lifetime value beyond hardware sale.
Industry Challenges
- Emissions calibration complexity:Multi-mode engine maps for transient load profiles require specialized test cell capacity and simulation expertise that concentrates at tier-one suppliers.
- Legacy fleet interoperability:New aftertreatment hardware must interface with decade-old CAN bus architectures and diagnostic protocols, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Engine Market |
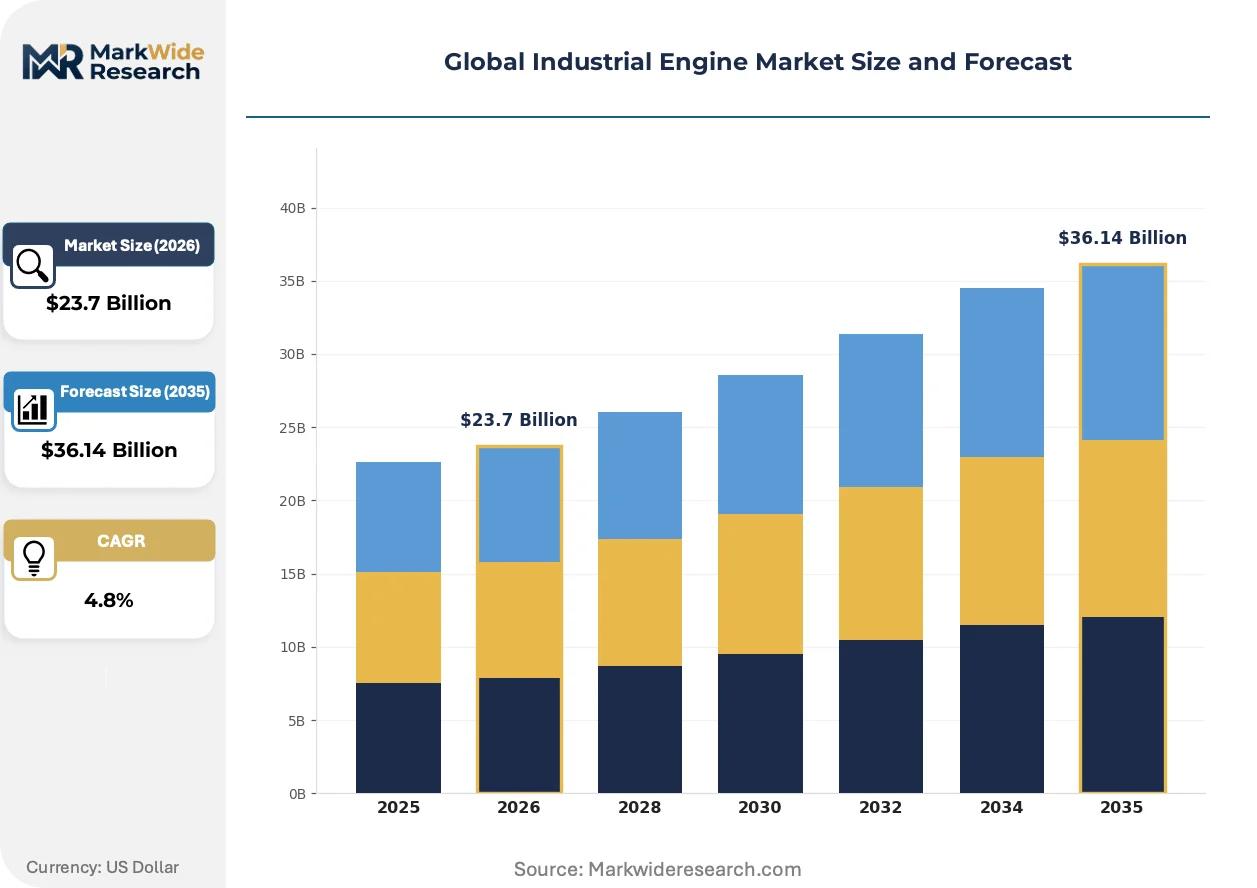
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Engines, Gas Engines, Turbine Engines, Hybrid Engines Application: Agriculture, Construction, Mining, Marine End User: OEMs, Aftermarket Providers, Equipment Manufacturers, Utility Companies Fuel Type: Petroleum, Biofuel, Natural Gas, Hydrogen |
| Companies Covered | Volvo Penta, Rolls-Royce Holdings PLC, Cummins Inc., MAN Energy Solutions, Deutz AG, Caterpillar Inc., INNIO, Kohler Co., Wärtsilä Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Engine Market Strategic Shifts
Combustion hardware, aftertreatment chemistry, and predictive analytics are converging to redefine how industrial engine suppliers capture value beyond the initial equipment sale.
Dual-fuel combustion architecture is rewriting the competitive logic of prime-power generation. Wärtsilä and MAN Energy Solutions have commercialized engines that switch between diesel and gas modes without load interruption. Data center operators in Northern Europe are specifying these units to hedge fuel price volatility while maintaining EPA Tier 4 Final compliance. The technology is compressing the addressable market for pure diesel standby sets in mission-critical applications.
EU Stage V and China's MEE enforcement are tightening particulate number limits in parallel, forcing convergence on gasoline particulate filter derivatives for large spark-ignited engines. Engine makers serving the European construction equipment market are redesigning cylinder heads and piston crowns to reduce raw particulate formation upstream of aftertreatment. The segment most affected is the 130-560 kW mobile generator set category, where rental fleets face accelerated replacement cycles to avoid non-compliance penalties.
Buyers are unbundling aftermarket service from original equipment procurement, compressing supplier margins on long-term maintenance contracts. Mining contractors in Western Australia now tender engine overhaul and parts supply separately from machine acquisition, forcing Caterpillar and Komatsu to compete with independent service providers on labor rates and parts availability. This pattern is most visible in mature extractive industries where fleet standardization enables multi-brand maintenance strategies.
Global Industrial Engine Market Segmentation
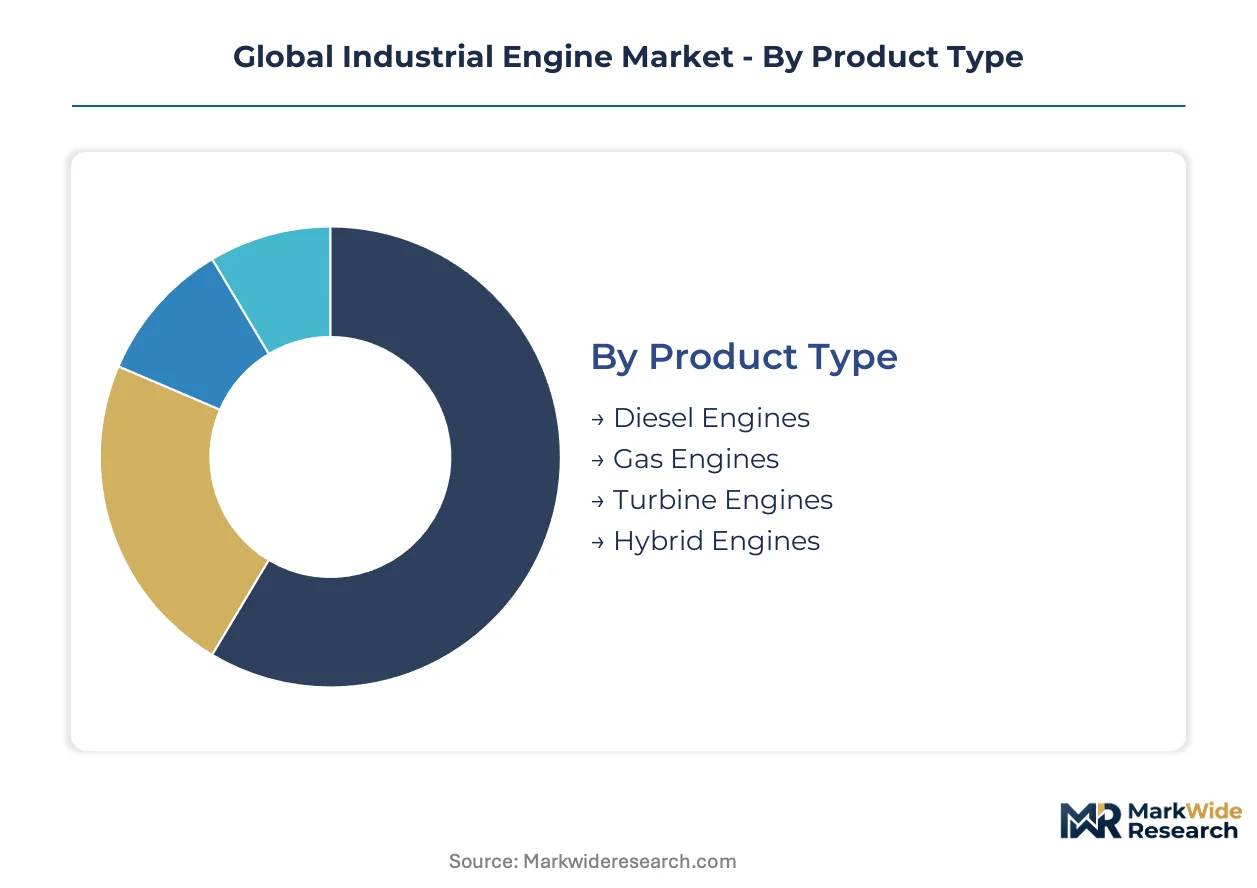
Industrial engine procurement patterns diverge sharply between standalone power systems and embedded propulsion units, with fuel pathway decisions and regulatory exposure reshaping how buyers evaluate segment trade-offs. Segmentation clarity enables suppliers to align combustion architectures, aftertreatment investments, and service contract structures with distinct buyer economics across mobile and stationary applications.
Product Type:
Integration depth separates standalone prime-power engines from embedded propulsion systems, with aftertreatment packaging and service attachment rates diverging accordingly.
- Diesel Engines:Compression-ignition architectures dominate torque-intensive mobile applications, with EPA Tier 4 Final and EU Stage V aftertreatment systems now standard above 56 kW. Australian mining fleets and Chinese construction OEMs anchor replacement demand for 300-750 kW displacement categories.
- Gas Engines:Spark-ignited and dual-fuel variants rated for natural gas, biogas, and hydrogen blends are displacing diesel in distributed power and marine propulsion. Northern European data center operators and Indonesian nickel smelters specify these units to hedge fuel price volatility and meet carbon-intensity accounting frameworks.
- Turbine Engines:Aeroderivative and industrial gas turbines serve megawatt-scale prime power and mechanical drive applications where rapid start capability outweighs thermal efficiency trade-offs.
- Hybrid Engines:Diesel-electric and gas-electric architectures integrate battery storage for load leveling and transient response in harbor craft and underground mining equipment.
Diesel engines lead volumes today; gas engines are gaining share fastest.
Application:
Load profile characteristics and duty cycle intensity determine engine sizing, fuel selection, and maintenance contract structures across mobile and stationary use cases.
- Mining:Continuous-duty haul truck and excavator power units operate at high brake mean effective pressure, driving 15,000-25,000 hour overhaul intervals and predictive maintenance adoption. Australian iron ore and copper producers anchor demand for 1,000+ kW engine categories.
- Construction:Transient-load excavators, loaders, and mobile generators require multi-mode engine maps and compact aftertreatment packaging. EU Stage V enforcement is compressing replacement cycles for 130-560 kW rental fleet equipment in Germany and France.
- Marine:IMO Tier III compliance mandates selective catalytic reduction or exhaust gas recirculation for harbor craft and inland waterway vessels, with German and Dutch operators facing replacement deadlines.
- Agriculture:Seasonal-duty tractors and harvesters prioritize initial cost over fuel efficiency, limiting aftertreatment penetration in sub-75 kW power categories.
Mining applications command the highest revenue per unit; marine retrofit activity is expanding most quickly.
End User:
Procurement authority and lifecycle cost accountability determine whether engine supply attaches to equipment purchase or unbundles into separate service competitions.
- OEMs:Original equipment manufacturers specify engine platforms during machine design, with Caterpillar and Komatsu integrating captive power systems and Cummins supplying multi-brand installations.
- Equipment Manufacturers:Specialized machinery builders for mining and marine applications source engines to proprietary specifications, often requiring custom calibration and packaging.
- Aftermarket Providers:Independent service networks compete for overhaul and parts supply contracts as mining contractors in Western Australia unbundle maintenance from equipment acquisition.
- Utility Companies:Grid operators and distributed power developers specify prime-power and standby engines for reliability mandates, with biogas and hydrogen fuel pathways gaining traction in EU member states.
OEMs dominate unit placements today; aftermarket providers are capturing expanding service revenue share.
Fuel Type:
Carbon-intensity accounting and infrastructure availability are reweighting fuel economics beyond thermal efficiency and energy density metrics.
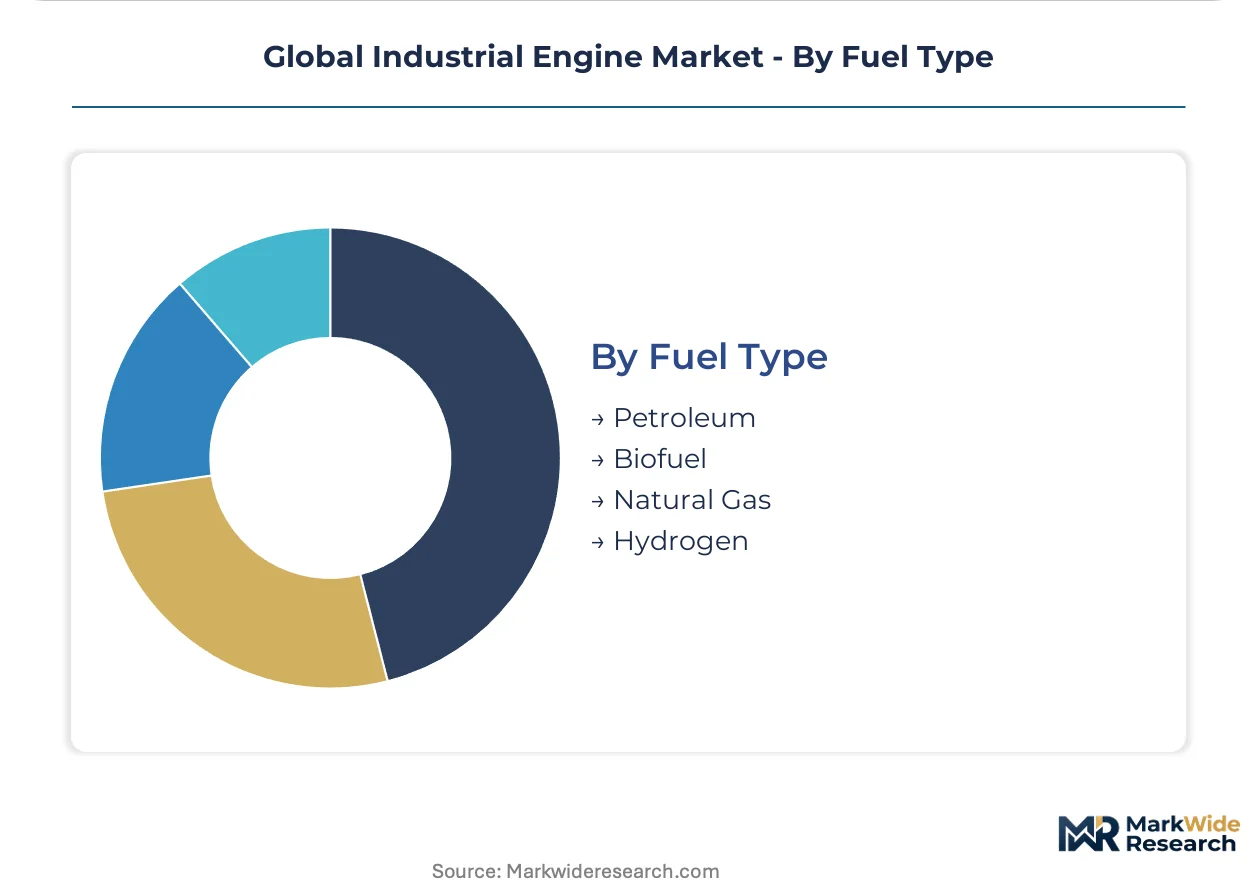
- Petroleum:Diesel and gasoline remain dominant in mobile applications where fuel distribution infrastructure and energy density requirements preclude alternatives.
- Natural Gas:Pipeline and liquefied supply chains support stationary power and marine propulsion, with dual-fuel engines enabling fuel switching based on price signals.
- Biofuel:FAME and HVO drop-in fuels reduce lifecycle carbon intensity without engine modification, gaining adoption in EU markets with renewable fuel mandates.
- Hydrogen:Combustion variants face fuel availability constraints, limiting deployment to captive industrial sites with on-site electrolysis or dedicated supply agreements.
Petroleum fuels anchor installed base today; hydrogen combustion variants are climbing the fastest despite infrastructure constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-backed infrastructure procurement pulls higher volumes than Australia's mining fleet upgrades, though both concentrate demand in the 300-750 kW engine category. Regulatory divergence between EPA Tier 4 Final, EU Stage V, and China's MEE enforcement creates distinct compliance costs across major demand centers.
United States
Data center operators in Northern Virginia and Texas specify dual-fuel engines to hedge natural gas price volatility. EPA Tier 4 Final mandates selective catalytic reduction for stationary prime-power units above 56 kW. Houston anchors aftermarket service density for oilfield power systems.
China
State-backed infrastructure programs sustain heavy procurement of construction and mining machinery through domestic OEMs. MEE enforcement tightens particulate number limits in parallel with EU Stage V trajectory. Yangtze River Delta clusters concentrate engine manufacturing for export-oriented equipment builders.
Germany
Harbor craft and inland waterway operators face IMO Tier III retrofit deadlines in Hamburg and Duisburg port complexes. EU Stage V compresses replacement cycles for 130-560 kW rental fleet equipment. Baden-Württemberg hosts test cell capacity for multi-mode engine map calibration.
Australia
Iron ore and copper producers in Western Australia's Pilbara region anchor demand for 1,000+ kW haul truck engines. Fleet operators unbundle maintenance contracts from equipment acquisition, forcing competition on labor rates. Queensland's Bowen Basin coal operations tighten replacement intervals for continuous-duty power units.
Indonesia
Nickel smelter construction in Sulawesi and Halmahera creates demand for stationary prime-power engines in remote island locations. Weak grid connectivity favors captive power systems rated for biogas and diesel fuel switching. Jakarta-based contractors specify dual-fuel architectures to manage fuel logistics across archipelago operations.
Global Industrial Engine Market Competitive Environment
Top-tier vendors anchor integrated power system supply, while mid-scale specialists compete on aftermarket service density. The market structure concentrates around three strategic archetypes: captive engine builders integrating proprietary platforms, multi-brand suppliers serving independent OEMs, and aftermarket service networks capturing unbundled maintenance contracts. M&A activity targets diagnostic software capabilities, and capacity expansion focuses on dual-fuel combustion test infrastructure.
Among diversified industrial conglomerates, Caterpillar Inc., Cummins Inc., and Wärtsilä Corporation occupy positions spanning captive integration and multi-brand supply. Caterpillar exemplifies the captive platform archetype through embedded machine power systems. Cummins represents multi-brand engine supply to independent equipment builders. Wärtsilä anchors marine and energy segment specialization with remote diagnostics integration. These three structures illustrate how competitive positioning diverges across mobile, stationary, and marine application vectors.
| Leading Market Players |
|---|
| Volvo Penta |
| Rolls-Royce Holdings PLC |
| Cummins Inc. |
| MAN Energy Solutions |
| Deutz AG |
| Caterpillar Inc. |
| INNIO |
| Kohler Co. |
| Wärtsilä Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between EPA Tier 4 Final-compliant power units and legacy diesel engines manifests in both pricing premiums and supply chain sourcing strategies. Premium aftertreatment architectures draw from South African palladium suppliers and German catalyst substrate manufacturers, while commodity engine tiers source from integrated Chinese foundry complexes.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for sub-75 kW engine categories. Three-tier pricing structure across premium, standard, and economy levels reflects aftertreatment complexity and calibration certification depth. Cost compression in the economy tier intensifies because mining contractors in Western Australia unbundle maintenance from acquisition, squeezing margin on parts-only supply. Rental fleet operators in Germany exhibit highest price sensitivity due to accelerated EU Stage V replacement cycles; marine operators in Indonesia show lowest sensitivity given captive fuel logistics and weak grid alternatives.
Supply Chain Analysis
Palladium and platinum supply rests on South African mining output and Russian export channels, with catalyst substrate production concentrated in Germany and Japan. Engine block castings draw from Chinese and Indian foundry networks; electronic control modules source from Taiwanese and South Korean semiconductor packaging. Single-source vulnerability concentrates in platinum group metal refining, where export restrictions from major suppliers disrupt aftertreatment manufacturing. Distribution runs through OEM captive networks for embedded propulsion systems and independent aftermarket channels for unbundled mining and marine service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in industrial engines hinges on predictive maintenance contract penetration and dual-fuel premium tier positioning. Aftertreatment cost stack compression through alternative catalyst formulations offers a parallel cost-down pathway.
For Market Incumbents: Deepen captive integration into remote diagnostics platforms to defend service attachment rates against independent aftermarket competitors. Secure palladium supply through offtake agreements with South African refiners to mitigate export restriction exposure. Prioritize dual-fuel test cell capacity in Northern Europe where data center operators hedge fuel price volatility. For New Entrants and Emerging Players: Independent service networks in Australian mining regions represent the most penetrable channel given unbundled procurement patterns. Target biogas-ready gas engine configurations for Indonesian nickel smelter projects with weak grid connectivity. Lead with fuel-switching calibration expertise as the go-to-market wedge against established diesel-centric suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where predictive analytics capabilities concentrate among tier-one suppliers and mid-scale specialists lack IoT integration depth. Long-term viability favors platforms with dual-fuel architecture and marine energy segment diversification. Acquisition targets should display aftermarket service density in mining or marine verticals. Watch hydrogen electrolysis project announcements at captive industrial sites as inflection signal for combustion engine displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Architecture Commercialization | Wärtsilä and MAN Energy Solutions anchor data center and marine contracts with diesel-gas switching capability. |
| Predictive Maintenance Platform Integration | Cummins embeds IoT sensor streams into power system contracts to capture lifetime value beyond hardware. |
| Aftertreatment Cost Stack Compression | Catalyst substrate redesigns reduce platinum group metal loading under EPA Tier 4 Final and EU Stage V mandates. |
| Biogas Fuel Pathway Certification | EU carbon-intensity accounting frameworks accelerate landfill gas and agricultural biogas engine deployments. |
| Marine Retrofit Service Network Expansion | German and Dutch harbor craft operators face IMO Tier III deadlines, opening aftermarket volume for compliant propulsion. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged maintenance directors at Australian iron ore operations, OEM procurement teams at Chinese construction equipment builders, aftermarket service heads at marine operators in Germany and the Netherlands, and plant engineers at Indonesian nickel smelters. Secondary validation drew from EPA certification filings, EU Stage V type-approval databases, IMO marine engine registers, and customs trade data for engine and catalyst substrate flows. Bottom-up unit economics and top-down market sizing triangulated volume and value estimates.
Comparable-period anchoring linked historical replacement cycle data to forward procurement intentions across the projection horizon. Segmentation modeling spanned product type, application intensity, fuel pathway, and regional regulatory cluster. CAGRs derived from installed base turnover rates, emissions mandate phase-in schedules, and infrastructure investment trajectories. Forecast inputs incorporated mining productivity targets in Western Australia, state-backed procurement programs in China, and data center power reliability specifications in Northern Virginia.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hydrogen infrastructure buildout pace and platinum group metal supply disruption scenarios. Assumptions reflect current regulatory trajectories for EPA Tier 4 Final, EU Stage V, and China's MEE enforcement, with revision risk from accelerated zero-emission mandates or trade restriction escalations. A small set of triggers—electrolysis project completions, catalyst substitution breakthroughs, and mining contract unbundling rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Variable Oil Pump Market
Powertrain
Clutch Market
Powertrain
Automotive Engine Air Filter Market
Powertrain
Turbocharger Actuators Market
Powertrain
Truck Auxiliary Power Units Market
Powertrain
Diesel Engine Catalyst Market
Powertrain
Continuously Variable Transmission (CVT) Market
Powertrain
Global Driveline Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Test Automation Systems for Powertrain Dynamometer Market
Powertrain
Clutch Hub Puller Market
Powertrain
Europe Hill-Start Assist System Market
Powertrain
Automotive Engine Market
Powertrain
Automotive Clutch Actuator Market
Powertrain
Automotive Cylinder Block Market