
 Global Automotive Electric Drivetrain System Market | 2026-2036
Global Automotive Electric Drivetrain System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Electric Drivetrain System Market Intelligence
Silicon carbide is broadening cost-performance boundaries in inverter modules across electric drivetrain architectures. BorgWarner Inc. leverages in-house wafer sourcing to anchor its power electronics division against commodity volatility. ZF Friedrichshafen AG competes through integrated e-axle platforms that consolidate motor, transmission, and inverter into single housings.
An automotive electric drivetrain system comprises the electromechanical assembly that converts stored electrical energy into mechanical torque for propulsion, typically integrating a traction motor operating at 400-800V with power-dense inverters and multi-speed reduction gearboxes. Its primary commercial purpose is to replace internal-combustion powertrains with zero-emission propulsion across passenger and commercial vehicle platforms. Motor generator units command the dominant share of component value pools given their direct impact on vehicle efficiency and thermal performance. Power electronics represents the fastest-expanding segment as silicon carbide and gallium nitride devices displace traditional silicon IGBTs.
The EU Green Deal and EPA tailpipe rules in the United States are mandating phased fleet electrification that locks in drivetrain procurement volumes through legally binding compliance deadlines. China's MIIT enforces GB standards for motor efficiency and electromagnetic compatibility that filter market access for foreign suppliers. Stakeholders must track how battery management system integration with vehicle-level software architectures reshapes tier-1 supplier boundaries and OEM make-versus-buy decisions.
Market Dynamics
Silicon carbide adoption is compressing inverter cost curves while OEMs consolidate motor-transmission sourcing under single supplier relationships to secure volume commitments against tightening fleet emissions mandates.
Growth Catalysts
- EU Green Deal fleet ceilings:Binding compliance deadlines through 2035 lock in multi-year procurement contracts for integrated drivetrain platforms across German, French, and Italian OEM manufacturing footprints.
- 800V traction architectures:Higher-voltage motor systems reduce copper mass and enable faster charging, accelerating penetration in premium passenger segments and long-haul commercial vehicles.
- China's MIIT efficiency mandates:GB standards for motor performance and electromagnetic compatibility filter market access, concentrating domestic demand on certified local and joint-venture suppliers.
Market Restraints
- Silicon carbide wafer supply concentration:Substrate fabrication capacity clusters in limited geographies, exposing inverter manufacturers to input volatility and allocation rationing during demand surges.
- Permanent magnet material dependency:Rare earth processing concentration creates strategic vulnerability for traction motor cost structures and supply security.
- Legacy thermal management integration:Existing vehicle cooling architectures impose physical constraints on power density gains in retrofit platform designs.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives for advanced automotive technology manufacturing attract drivetrain system assembly and localized motor production.
- Vehicle-to-grid bidirectional charging:Integration of traction inverters with grid-interactive power electronics creates new revenue streams in energy services and grid stabilization markets.
- Commercial vehicle electrification gaps:Heavy-duty truck and bus segments remain underpenetrated relative to passenger vehicles, offering volume expansion for integrated e-axle platforms.
Industry Challenges
- Power electronics firmware talent scarcity:Shortage of engineers skilled in silicon carbide gate driver design and thermal-electrical co-simulation delays product development cycles.
- Multi-domain system integration complexity:Synchronization of motor control, battery management, and vehicle dynamics software requires cross-functional coordination that strains tier-1 supplier organizational structures.
- Homologation timeline compression:Accelerated platform launch schedules compress electromagnetic compatibility certification and durability validation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Electric Drivetrain System Market |
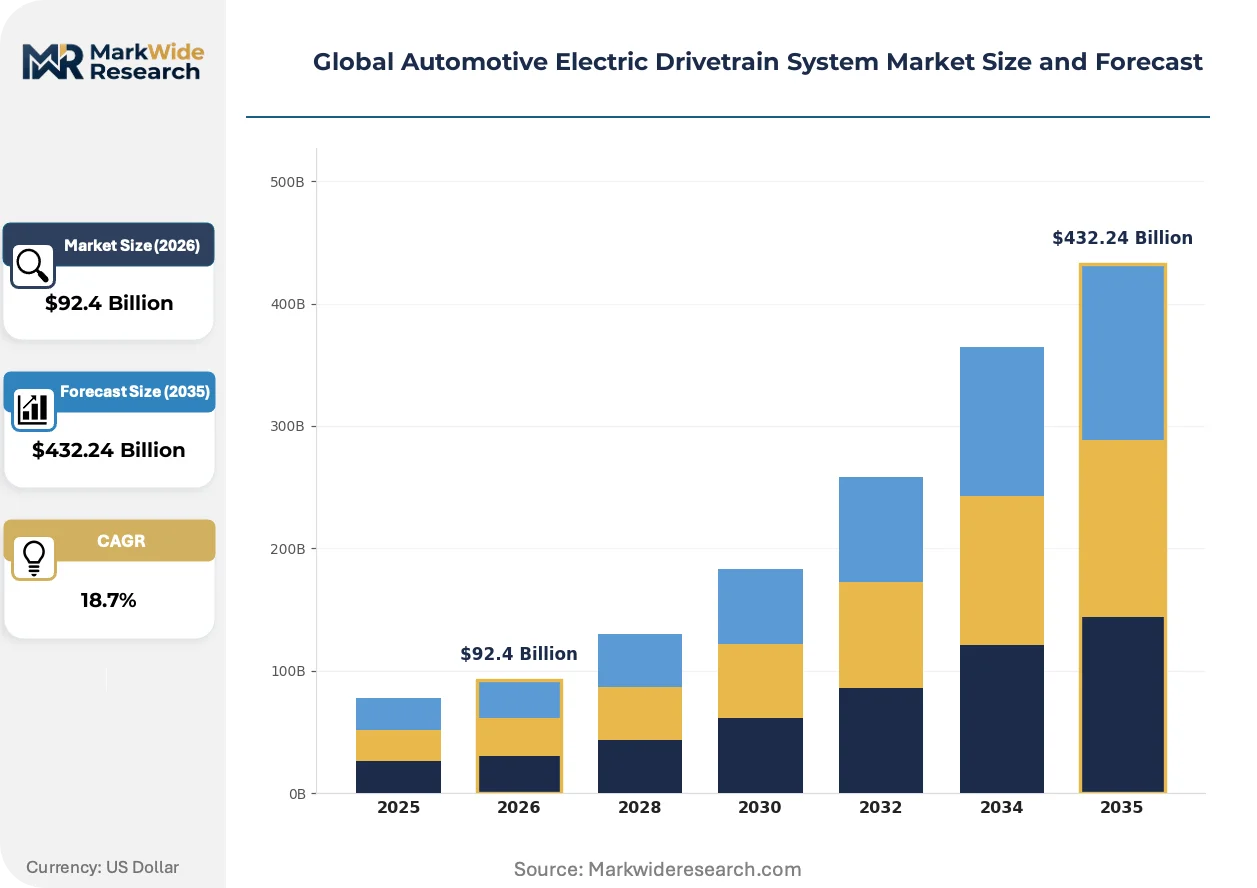
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $432.24 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motor Generator Unit, Power Electronics, Transmission System, Battery Management System Technology: Brushless DC Motor, Induction Motor, Switched Reluctance Motor, Synchronous Motor Application: Passenger Vehicles, Commercial Vans, Heavy-Duty Trucks, Electric Buses End User: OEM Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | BorgWarner Inc., ZF Friedrichshafen AG, Aisin Corporation, Magna International Inc., Schaeffler AG, Denso Corporation, Valeo SA, GKN plc, Bosch Mobility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Electric Drivetrain System Market Strategic Shifts & Innovations
Distributed inverter architectures are fragmenting traditional power electronics supply relationships while silicon carbide and gallium nitride devices rewrite thermal-performance tradeoffs across voltage classes.
Silicon carbide MOSFETs in traction inverters handle higher switching frequencies at lower thermal losses than silicon IGBTs. OEMs in the premium passenger segment are specifying 800V systems with SiC power modules as standard equipment. This semiconductor transition is decentralizing inverter sourcing decisions from centralized procurement teams to platform-specific engineering groups with direct supplier relationships.
The EPA tailpipe rules mandate fleet-average CO2 reductions that force powertrain portfolio reallocation toward full-electric architectures. US manufacturers are accelerating dedicated EV platform development to avoid compliance penalties. Heavy-duty pickup and commercial van segments face the steepest compliance cost increases and are driving demand for integrated e-axle systems that simplify vehicle assembly.
Fleet operators are consolidating drivetrain procurement under total-cost-of-ownership contracts that bundle hardware, software updates, and energy management services. This purchasing model displaces component-level sourcing through traditional tier-1 distribution channels. North American logistics and last-mile delivery operators are most advanced in adopting service-based contracts that transfer performance risk to system suppliers.
Global Automotive Electric Drivetrain System Market Segmentation
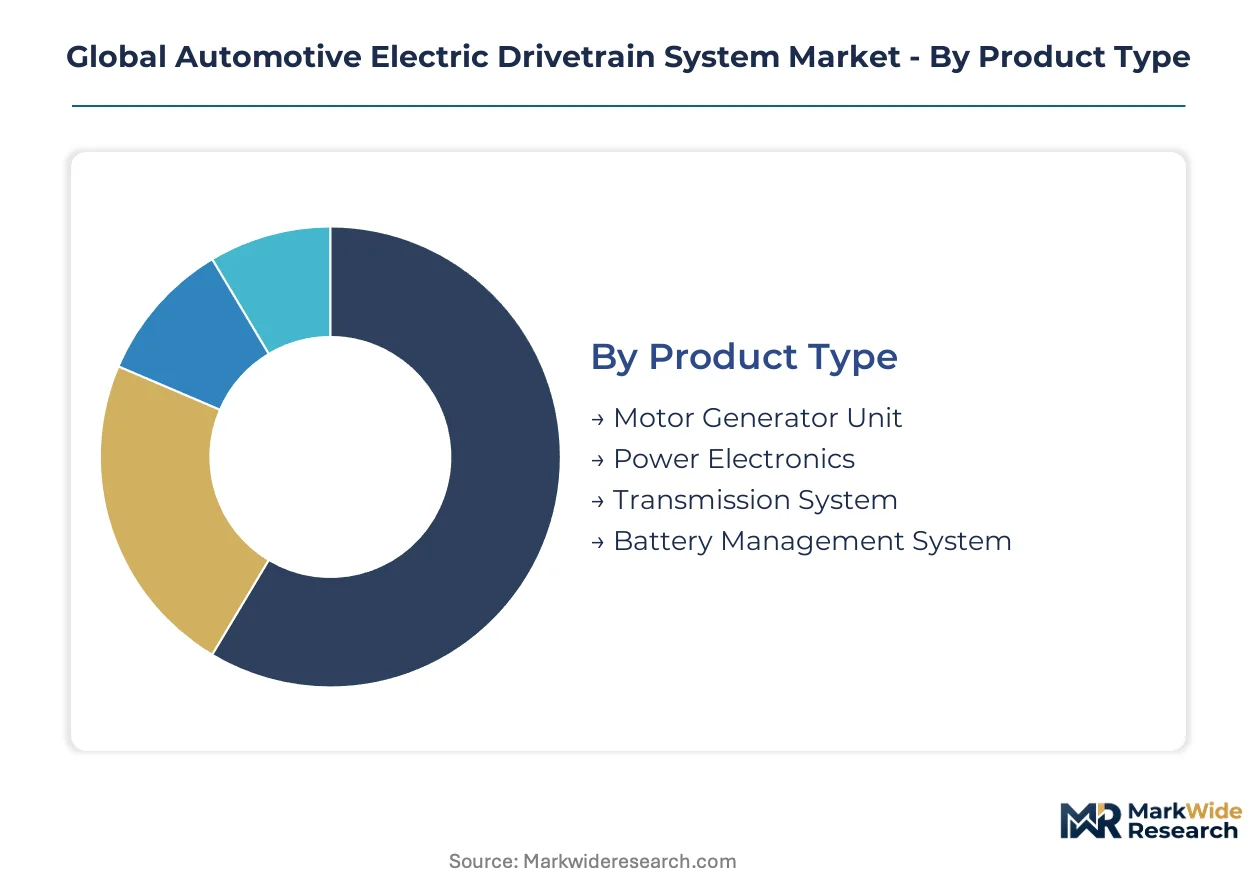
Drivetrain procurement patterns diverge sharply across voltage classes and thermal architectures. Segment boundaries determine supplier qualification requirements, firmware integration scope, and long-term service revenue potential.
Product Type:
Capital intensity peaks in motor generator units due to rare-earth magnet processing and precision winding equipment, while power electronics scale through semiconductor fabrication partnerships.
- Motor Generator Unit:Permanent magnet synchronous machines dominate efficiency benchmarks for 400-800V architectures. German and Chinese OEMs concentrate procurement of integrated rotor-stator assemblies to secure thermal performance warranties against EU Green Deal fleet ceilings.
- Power Electronics:Silicon carbide inverter modules enable switching frequencies above 20kHz with reduced thermal losses. Demand concentrates in premium passenger platforms where 800V charging capability commands price premiums; SiC wafer supply rationing constrains volume scaling.
- Transmission System:Multi-speed reduction gearboxes for e-axle integration.
- Battery Management System:Cell monitoring and thermal regulation electronics bundled with vehicle software architectures.
Most installed capacity flows through motor generator units. Expansion is steepest in power electronics.
Technology:
Patent density and manufacturing yield curves separate commercially viable motor topologies from laboratory-stage alternatives.
- Brushless DC Motor:Trapezoidal back-EMF machines with simplified control algorithms suit cost-sensitive compact passenger vehicles. China's MIIT efficiency certifications filter supplier access, concentrating domestic production in joint-venture facilities serving local OEMs.
- Induction Motor:Squirrel-cage rotors eliminate permanent magnet dependencies entirely. Tesla's design legacy drives residual demand in performance segments seeking rare-earth supply security.
- Switched Reluctance Motor:Doubly-salient pole structures with position-sensorless control potential.
- Synchronous Motor:Field-oriented control enables maximum torque per ampere across full speed range.
Permanent magnet synchronous architectures retain the dominant installed base. Induction motor procurement is climbing fastest amid magnet price volatility.
Application:
Payload duty cycles and charging infrastructure access determine thermal management specifications and motor sizing requirements.
- Passenger Vehicles:Compact to luxury sedans and SUVs with 150-500kW peak power demands. Urban China and European metropolitan clusters concentrate volume; EPA tailpipe rules and EU Green Deal deadlines lock in multi-year platform commitments.
- Heavy-Duty Trucks:Long-haul and regional freight with 500kW+ continuous power requirements. North American logistics corridors and EU TEN-T freight networks drive pilot deployments; battery energy density constraints limit range-competitive configurations.
- Commercial Vans:Last-mile delivery with stop-start duty cycles.
- Electric Buses:Depot-charged and opportunity-charged urban transit.
Passenger vehicles absorb the majority of production volume. Heavy-duty trucking is gaining share fastest as energy density improvements enable range-competitive platforms.
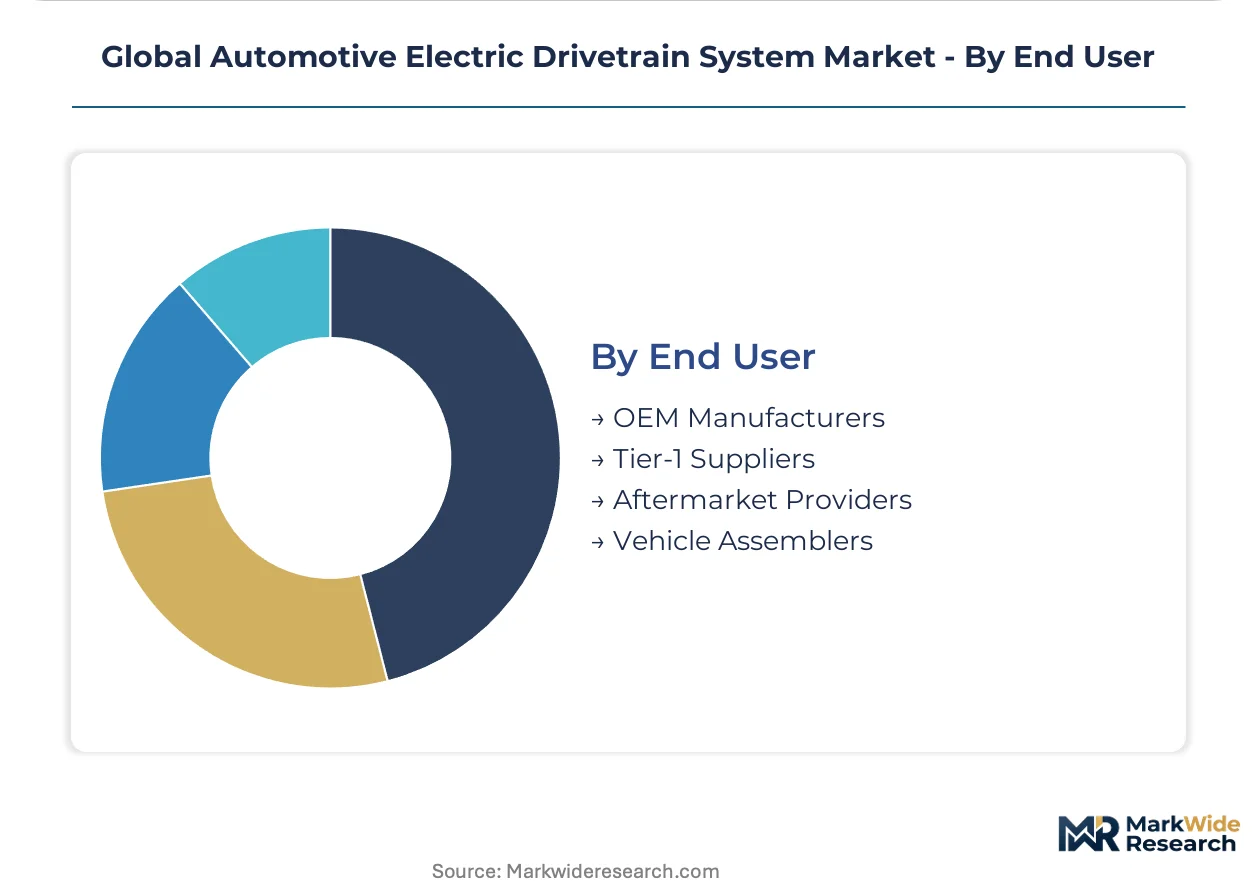
End User:
Make-versus-buy decisions hinge on software integration depth and platform exclusivity requirements.
- OEM Manufacturers:Vertically integrated drivetrain design for proprietary vehicle platforms. Volkswagen, BYD, and Ford maintain captive motor and inverter engineering to differentiate thermal performance and charging speed capabilities.
- Tier-1 Suppliers:BorgWarner, ZF Friedrichshafen, and Denso supply integrated e-axle platforms to multiple OEMs. Procurement consolidation under single-supplier relationships secures volume commitments against tightening fleet emissions mandates.
- Aftermarket Providers:Replacement motors and refurbished power electronics for existing fleets.
- Vehicle Assemblers:Contract manufacturers without proprietary drivetrain engineering.
Direct OEM procurement commands the largest value share. Tier-1 supplier outsourcing is expanding most quickly as platform complexity strains in-house engineering bandwidth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors manufacturing concentration for power electronics and battery management systems, with Shanghai and Suzhou hosting dense supplier ecosystems for 800V traction architectures. Procurement patterns diverge sharply across regulatory jurisdictions, with fleet emissions mandates in Germany, EPA tailpipe rules in the United States, and MIIT efficiency standards in China reshaping regional competitive dynamics.
China
Domestic OEMs and joint ventures concentrate drivetrain procurement in the Yangtze River Delta and Pearl River Delta clusters. MIIT enforces GB standards for motor efficiency and electromagnetic compatibility that filter market access for foreign suppliers. BYD and CATL-affiliated manufacturers in Shenzhen and Ningbo scale integrated e-axle production for export markets.
Germany
OEM manufacturers in Bavaria and Baden-Württemberg scale procurement of integrated motor-transmission units as the EU Green Deal tightens fleet emissions ceilings through 2035. Stuttgart and Munich engineering centers specify 800V silicon carbide inverters for premium passenger platforms. ZF Friedrichshafen and Bosch Mobility anchor supplier relationships through captive R&D partnerships.
United States
EPA tailpipe rules mandate fleet-average CO2 reductions that force powertrain portfolio reallocation toward full-electric architectures across Michigan and California manufacturing footprints. Detroit automakers accelerate dedicated EV platform development to avoid compliance penalties. Heavy-duty pickup producers in Texas and the Midwest drive demand for integrated e-axle systems.
Japan
Denso Corporation and Aisin Corporation concentrate inverter and motor production in Aichi Prefecture's Nagoya industrial corridor. METI carbon neutrality targets push OEMs toward solid-state battery integration with next-generation drivetrain architectures. Toyota City and nearby supplier parks specialize in rare-earth-reduced motor topologies for hybrid and full-electric platforms.
India
The PLI scheme for auto components attracts drivetrain system assembly to Tamil Nadu and Gujarat manufacturing corridors. Domestic OEMs and multinational joint ventures localize motor production to qualify for production-linked incentives. Chennai and Pune engineering centers develop cost-optimized power electronics for compact passenger and two-wheeler electrification.
Global Automotive Electric Drivetrain System Market Key Industry Players
Global majors compete with regional champions across technology integration depth and OEM relationship exclusivity. The supplier base organizes into three tiers: integrated platform specialists with full e-axle capabilities, component-focused power electronics houses, and captive OEM engineering divisions. Strategic moves concentrate on silicon carbide wafer sourcing partnerships and firmware talent acquisition to compress development cycles.
Among Germany-based integrated platform suppliers, ZF Friedrichshafen AG and Schaeffler AG exemplify the e-axle consolidation archetype, while BorgWarner Inc. represents North American competitors securing semiconductor supply chains through backward integration strategies. These three anchors illustrate how geographic proximity to OEM engineering centers shapes competitive positioning in procurement consolidation environments.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| ZF Friedrichshafen AG |
| Aisin Corporation |
| Magna International Inc. |
| Schaeffler AG |
| Denso Corporation |
| Valeo SA |
| GKN plc |
| Bosch Mobility |
| Others |
Cost & Logistics Intelligence
EU Green Deal fleet emissions ceilings gate qualified supply access and premium-tier pricing power, compressing procurement timelines for silicon carbide inverter modules while OEMs consolidate motor-transmission sourcing under single-supplier relationships.
Pricing Analysis
Input-cost pass-through from silicon carbide wafer supply rationing compresses margins across 800V traction architectures. Three-tier pricing structure across premium, standard, and economy levels separates SiC-enabled inverters from silicon IGBT alternatives and entry-level brushless DC motor systems. Price differentiation hinges on GB standard certification tier and volume scale commitments. Cost compression in standard-tier motor generator units is intensifying because rare-earth magnet price volatility feeds through rotor-stator assembly quotes. Fleet operators exhibit lowest price sensitivity given total-cost-of-ownership contracting models.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated e-axle platforms, displacing traditional tier-1 distribution networks. Substrate fabrication capacity clusters in Japan, the United States, and Germany, exposing inverter manufacturers to allocation rationing during demand surges. The supply chain draws from neodymium-dysprosium magnet processing, copper winding stock, and silicon carbide wafer supply. Single-source vulnerability concentrates in SiC substrate vendors. Distribution runs through captive R&D partnerships anchored near Stuttgart, Munich, and Nagoya engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as legally binding fleet electrification deadlines lock in multi-year procurement volumes across German, Chinese, and US manufacturing footprints.
For Market Incumbents: Anticipate silicon carbide gate driver talent scarcity by acquiring firmware engineering teams in Aichi Prefecture and Bavaria. Secure backward integration into SiC wafer sourcing through partnerships with Japanese substrate vendors. Defensive consolidation around integrated e-axle platforms protects against emerging Chinese joint-venture suppliers capturing EU procurement share.
For New Entrants and Emerging Players: Capture heavy-duty truck electrification gaps in North American logistics corridors where battery energy density improvements now enable range-competitive platforms. Target India's PLI scheme corridors in Tamil Nadu and Gujarat for cost-optimized power electronics assembly. Go-to-market through vehicle-to-grid bidirectional charging integration creates differentiated energy services revenue streams.
For Investors and Strategic Acquirers: Roll-up economics work for component-focused power electronics houses because firmware talent scarcity and SiC supply rationing compress development timelines for standalone entrants. Five-to-ten-year viability favors suppliers with captive semiconductor partnerships and OEM platform engineering relationships. Watch silicon carbide wafer allocation announcements as inflection indicators for inverter module pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Partnership | BorgWarner's in-house wafer sourcing anchors power electronics against commodity volatility. |
| Integrated E-Axle Platform Development | ZF Friedrichshafen consolidates motor, transmission, and inverter into single housings for OEM procurement. |
| 800V Traction Architecture Deployment | Premium passenger platforms specify SiC power modules to enable faster charging capabilities. |
| Vehicle-to-Grid Integration | Traction inverters with bidirectional power electronics unlock grid stabilization revenue streams. |
| Rare-Earth-Reduced Motor Topology | Toyota City suppliers specialize in induction and synchronous reluctance designs for supply security. |
Research Approach
Multiple input streams — OEM platform engineering disclosures, tier-1 supplier procurement data, and vehicle production databases — were reconciled through bottom-up and top-down triangulation. Primary interviews with drivetrain procurement directors, power electronics engineering leads, and aftermarket service heads informed component-level demand assumptions. Secondary validation drew from EPA tailpipe rule filings, EU Green Deal implementation documents, MIIT GB standard certifications, and IHS Markit registration data.
Historical volume trajectories were cross-referenced against expert panel inputs to anchor growth assumptions across the analysis window. Segmentation modeling spanned voltage class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from slope-intercept fitting against policy-mandated fleet electrification timelines. Industry-specific forecast inputs included silicon carbide device penetration curves and rare-earth magnet price indices.
Policy implementation delays, SiC substrate supply disruptions, and battery energy density breakthroughs are the dominant revision risks for projection accuracy. Forecasts reflect documented assumptions regarding OEM make-versus-buy decisions and tier-1 supplier consolidation patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automatic Transmission Market
Powertrain
Europe Hill-Start Assist System Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Japan Electro Hydraulic Power Steering Market
Powertrain
Electrically Powered Hydraulic Steering Market
Powertrain
Turbocharger Market
Powertrain
Automotive Retrofit Electric Vehicle Powertrain Market
Powertrain
Automotive Cylinder Block Market
Powertrain
Spark Plugs Market
Powertrain
Automotive Counter Shaft Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Motor Vehicle Carburetors Market
Powertrain
High Speed Engine Market
Powertrain
Automotive Fuel Feed Pumps Market
Powertrain
Power Transmission Gearbox Market