
 Japan Automotive Engine Oils Market | 2026-2036
Japan Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Automotive Engine Oils Market Foresight
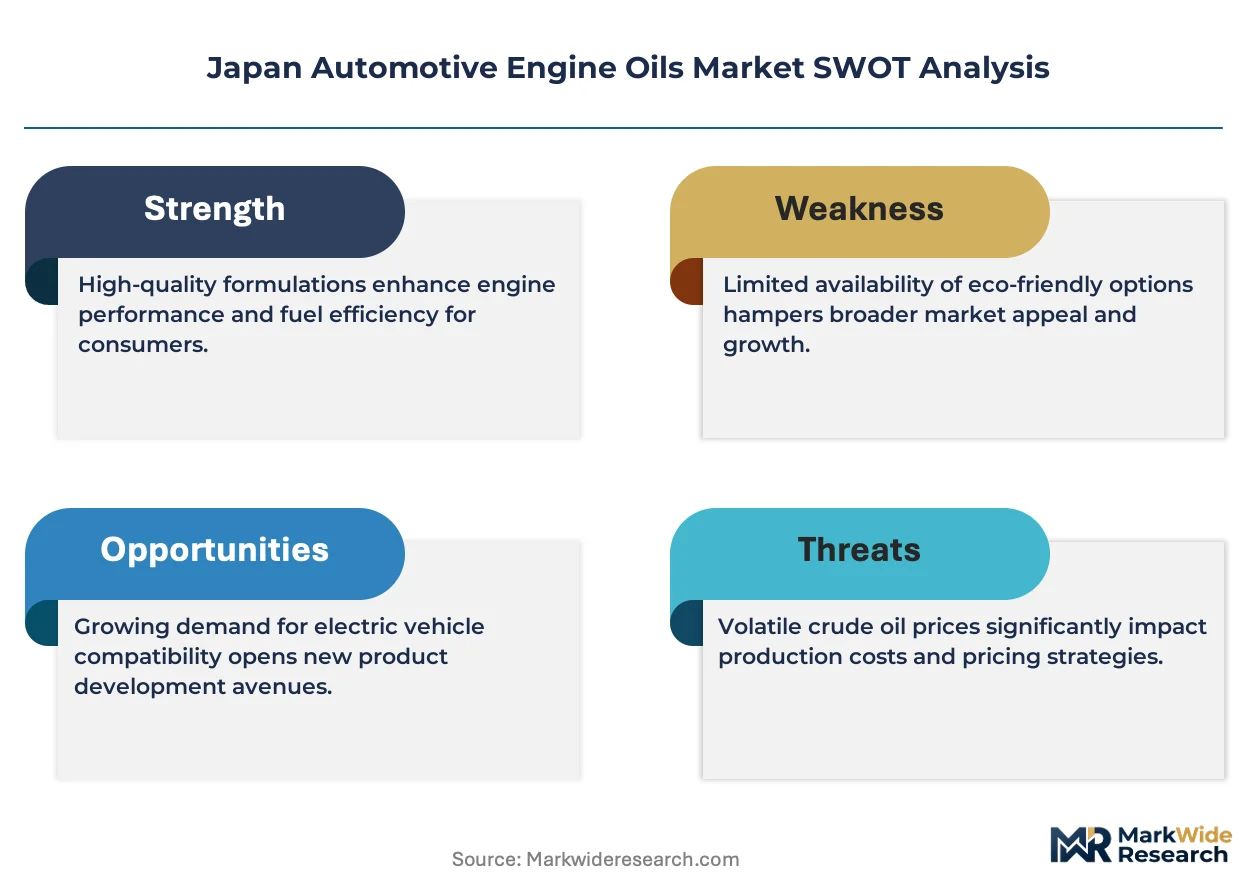
Hybrid vehicle servicing is broadening the addressable base for low-viscosity lubricants in Japan. ENEOS Corporation anchors domestic supply through integrated refining and retail networks across the archipelago. Idemitsu Kosan Co. Ltd competes via specialized formulations for Japanese OEM factory fill programs. Castrol (BP PLC) leverages global R&D scale to position premium synthetics in the aftermarket channel.
Japan automotive engine oils are formulated lubricants derived from base oils and additive packages, designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines operating across temperature extremes from Hokkaido winters to Kyushu summers. These fluids serve the essential commercial purpose of extending engine life while enabling compliance with stringent Japanese fuel efficiency targets. Synthetic grades command expanding share as OEM drain intervals lengthen and turbocharged direct-injection engines proliferate. The 0W-20 and 5W-30 viscosity grades dominate factory fill specifications, while bulk packaging to national service chains captures the highest volume throughput. Workshop and distributor channels retain structural importance due to Japan's inspection and maintenance culture.
METI enforces fuel economy standards that directly shape lubricant viscosity requirements and additive chemistry investments by domestic blenders. JIS standards and PMDA-aligned quality protocols govern product certification, creating compliance barriers for imported formulations. Stakeholders must monitor evolving carbon neutrality roadmaps and e-fuel compatibility specifications as Japan's mobility mix diversifies beyond conventional powertrains.
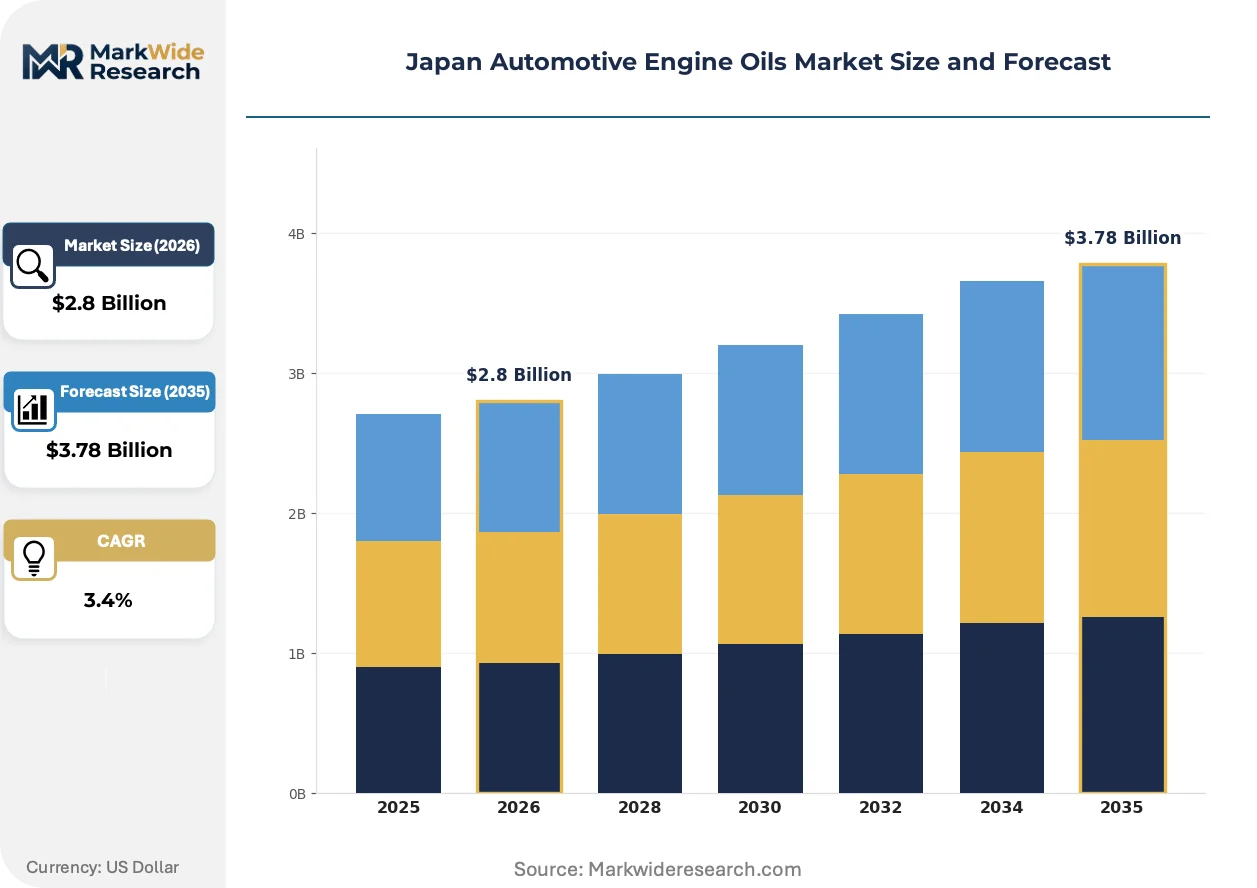
Market Dynamics
Japan's automotive engine oils sector is being fundamentally restructured by METI's tightening fuel economy mandates, which are compressing lubricant viscosity grades and forcing additive chemistry reinvestment across domestic blending infrastructure.
Growth Catalysts
- 0W-20 Low-Viscosity Grades:Factory fill specifications for hybrid powertrains are pulling demand toward ultra-thin lubricants that reduce cold-start friction and improve thermal efficiency in stop-start urban driving.
- Tokyo-Yokohama Fleet Density:Commercial operators in the Kanto corridor are consolidating procurement through national service chains, creating volume anchors for synthetic product lines.
- JIS K 2234 Certification Alignment:Quality protocols governing oxidation stability and deposit control are standardizing performance benchmarks that favor reformulated synthetic base stocks over conventional mineral oils.
Market Restraints
- Group III+ Base Oil Import Dependence:Domestic refiners lack sufficient API Group III/III+ capacity, forcing blenders to source high-performance base stocks from South Korean and Singaporean suppliers.
- Extended Drain Interval Compression:OEM recommendations stretching to 15,000 kilometers are reducing per-vehicle lubricant consumption volumes and compressing aftermarket revenue pools.
- PMDA-Aligned Quality Barriers:Import registration requirements for additive packages create procedural friction for foreign suppliers seeking aftermarket entry.
Strategic Opportunities
- Kyushu Industrial Expansion:Semiconductor and battery manufacturing growth around Fukuoka is generating fleet vehicle density underserved by premium synthetic distribution networks.
- E-Fuel Compatibility Testing:METI's carbon neutrality roadmap is creating specification uncertainty that rewards early movers developing lubricant formulations compatible with synthetic gasoline blends.
- Direct Workshop Digital Integration:Independent service bays in Osaka and Nagoya are adopting inventory management platforms that bypass traditional distributor tiers.
Industry Challenges
- Additive Chemist Talent Scarcity:Formulation expertise for low-SAPS (sulfated ash, phosphorus, sulfur) packages compatible with gasoline particulate filters is concentrating at a handful of domestic R&D centers.
- Legacy Distribution System Reconfiguration:Petroleum majors must unwind decades-long exclusive supply agreements with regional cooperatives to access emerging direct-digital channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Automotive Engine Oils Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Conventional, High Mileage, Bio-based Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Packaging Type: Quart Bottles, Gallon Containers, Drums, Bulk Distribution Channel: Retail Stores, Online Platforms, Workshops, Distributors |
| Companies Covered | Castrol (BP PLC), AKT Japan Co. Ltd, ENEOS Corporation, Motul, Japan Sun Oil Company, Ltd., Idemitsu Kosan Co. Ltd, Fuchs Japan Ltd., ExxonMobil Corporation, Cosmo Energy Holdings Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Automotive Engine Oils Market Shifts & Advancements
Japanese automotive lubricant development is pivoting toward chemistry platforms that reconcile thermal stability demands with friction reduction imperatives, while distribution channels fragment between consolidated fleet contracts and atomized service-bay procurement.
Polyalkylene glycol (PAG) and ester-based synthetic base stocks are absorbing the thermal stress generated by turbocharged direct-injection engines operating at higher specific power outputs. OEMs including Toyota and Honda are specifying these chemistries for factory fill in downsized powertrains. The technology is absorbing market share previously held by Group II mineral formulations, compressing the addressable base for conventional products.
METI's 2030 fuel economy standards are mandating fleet-average improvements that cascade into lubricant viscosity grade requirements. Blenders must reformulate additive packages to maintain wear protection at 0W-8 and 0W-16 specifications. Aftermarket channels in Hokkaido and Tohoku are responding with delayed product launches due to cold-flow performance validation requirements.
Workshop procurement is fragmenting as independent service bays adopt just-in-time inventory systems linked to distributor warehouses. National chains like Autobacs are consolidating volume through private-label synthetic programs. This shift is most visible in the Chubu region around Nagoya, where Toyota-affiliated service networks are piloting predictive maintenance scheduling tied to oil condition monitoring sensors.
Japan Automotive Engine Oils Market Segmentation
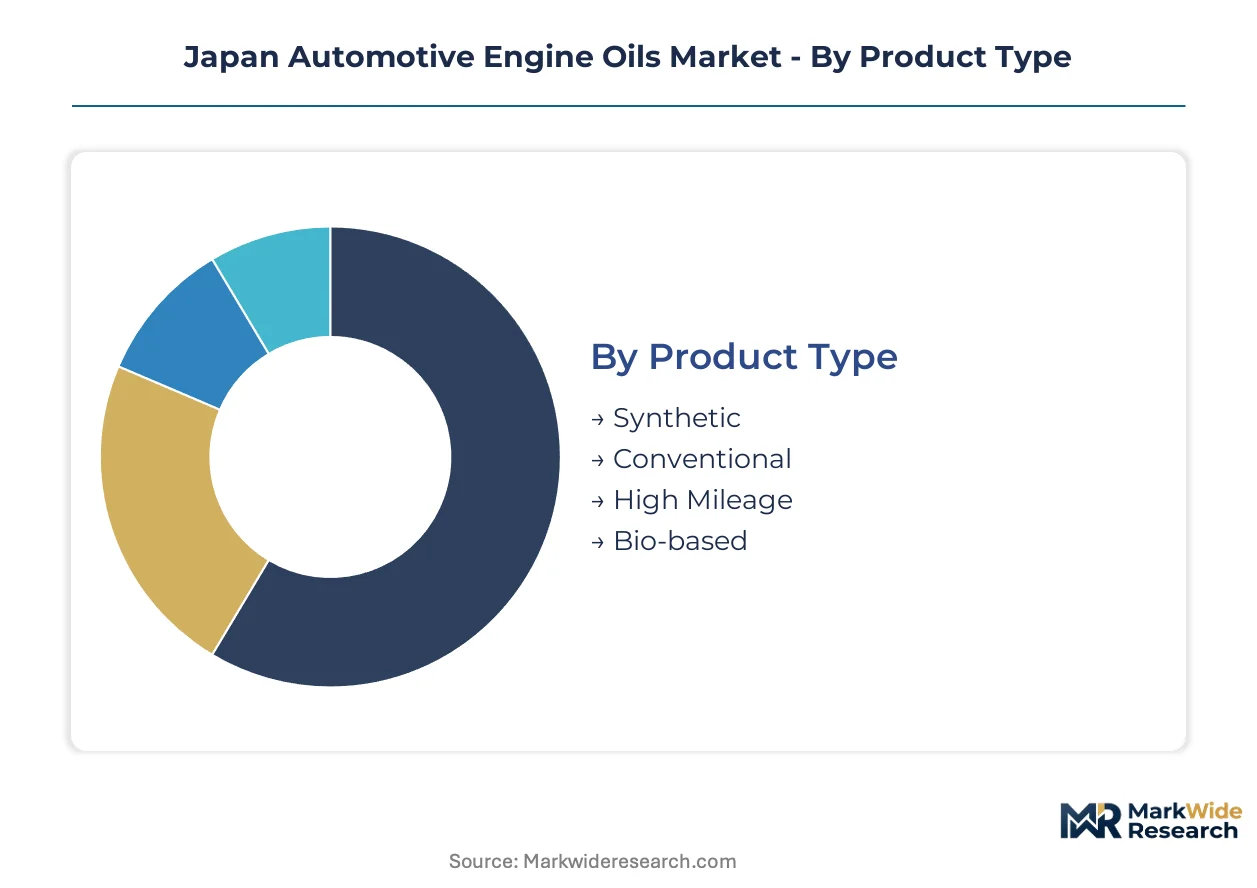
Segmentation in the Japan automotive engine oils market reveals how METI fuel economy mandates and OEM factory fill specifications cascade through purchasing decisions across product chemistry, viscosity grades, and channel structures. Buyers prioritize JIS-certified formulations that reconcile thermal stability with friction reduction imperatives.
Product Type:
Cost tier determines procurement patterns as fleet operators weigh upfront synthetic premiums against extended drain interval economics.
- Synthetic:Formulated from Group III/III+ base stocks with advanced additive packages delivering oxidation stability under turbocharged direct-injection thermal stress. Kanto corridor commercial fleets are consolidating procurement through national service chains, pulling volume toward 0W-20 and 5W-30 factory fill specifications.
- Conventional:Mineral-based formulations derived from Group I and Group II base stocks serving legacy vehicle parc and price-sensitive independent owners. Tohoku and Hokkaido aftermarket channels retain residual demand due to delayed product launches for ultra-low viscosity grades in colder climate zones.
- High Mileage:Seal conditioners and anti-wear additives target vehicles exceeding 75,000 kilometers, addressing compression loss and oil consumption in aging Japanese vehicle parc.
- Bio-based:Ester and vegetable-derived base stocks positioned for METI carbon neutrality roadmap alignment, currently constrained by oxidation stability validation requirements.
Volume sits with Synthetic; growth tilts toward Bio-based.
Viscosity Grade:
Application-specific thermal and cold-flow requirements segment demand across Japan's climatic and operational diversity.
- 0W-20:Ultra-low viscosity factory fill specification for hybrid powertrains and downsized turbocharged engines, reducing cold-start friction in stop-start urban driving. Toyota and Honda OEM programs anchor demand in the Chubu region around Nagoya.
- 5W-30:Versatile mid-viscosity grade bridging thermal protection and fuel economy compliance across conventional and mild-hybrid powertrains. Osaka-Kobe industrial corridor workshops specify this grade for mixed fleet servicing.
- 10W-40:Higher viscosity reserve for commercial diesel applications and high-load gasoline engines operating in Kyushu summer conditions.
- 15W-50:Maximum protection grade for performance vehicles and severe-duty applications, concentrated in specialty aftermarket channels.
Volume sits with 5W-30; growth tilts toward 0W-20.
Packaging Type:
Volume scale and customer procurement rhythm differentiate container formats across the value chain.
- Quart Bottles:Individual consumer format for DIY maintenance and emergency top-offs, dominant in Autobacs and retail auto parts channels.
- Gallon Containers:Small workshop format for independent service bays with moderate throughput, concentrated in urban prefectures.
- Drums:Intermediate bulk format for regional distributor warehouses serving multi-bay workshop clusters, prevalent in Chugoku and Shikoku.
- Bulk:Tanker-delivered format capturing highest volume throughput through national service chain contracts and fleet direct procurement, concentrated in Kanto corridor consolidation.
Volume sits with Bulk; growth tilts toward Gallon Containers.
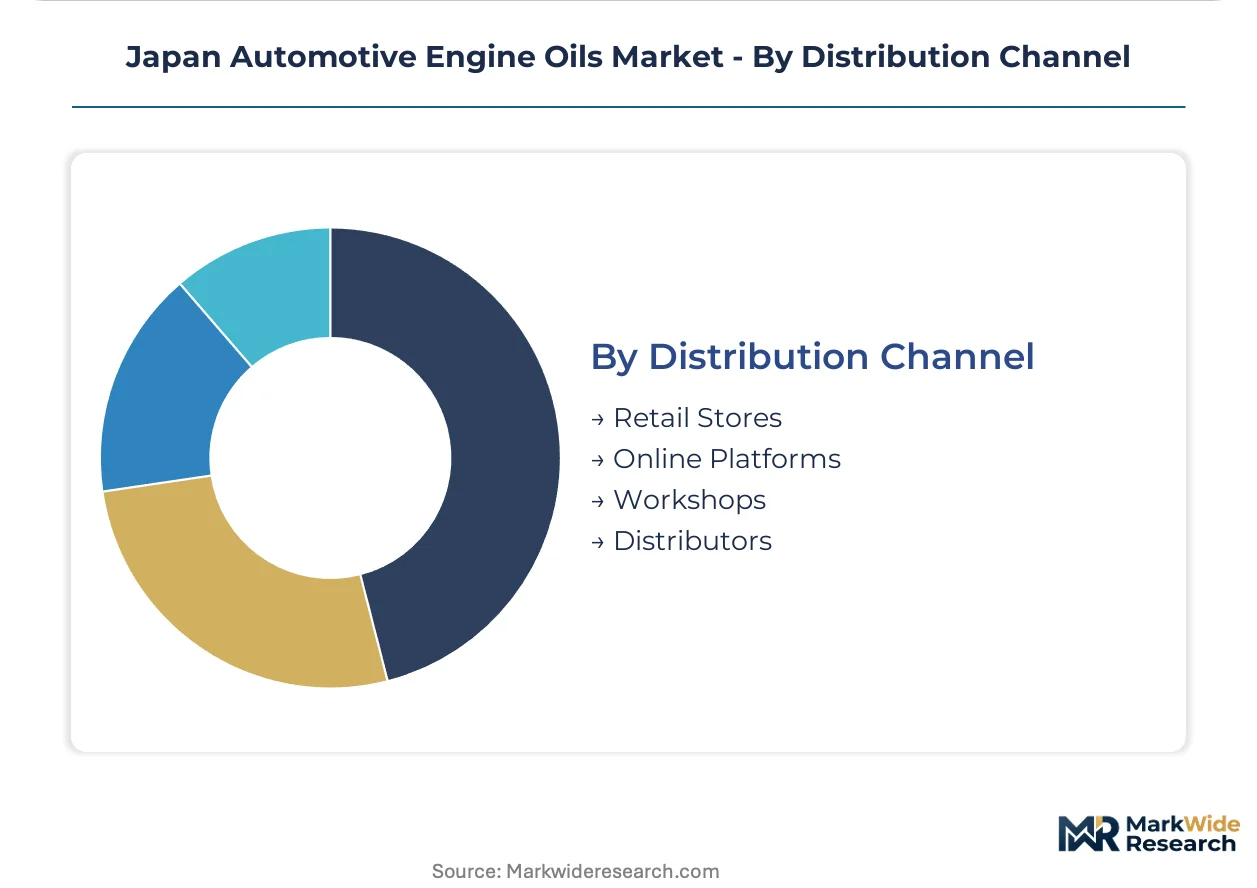
Distribution Channel:
Customer type and procurement integration level determine channel selection and margin capture.
- Retail Stores:Autobacs and auto parts superstores serving individual vehicle owners with private-label synthetic programs and branded premium lines.
- Online Platforms:E-commerce channels capturing growing share among digitally-native consumers and small fleet operators seeking price transparency.
- Workshops:Independent service bays and OEM-affiliated networks conducting just-in-time procurement through digital inventory integration, piloting predictive maintenance scheduling in Nagoya.
- Distributors:Regional petroleum cooperatives and national blending company networks managing bulk logistics and technical support for multi-site operators.
Volume sits with Distributors; growth tilts toward Workshops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's automotive engine oils market exhibits pronounced geographic clustering, with consumption concentrating in industrial corridors while domestic blending capacity struggles to match high-performance base oil requirements. Regional demand patterns reflect vehicle density, fleet operator consolidation, and climate-driven viscosity grade preferences.
Kanto/Tokyo
Commercial fleet operators in the Tokyo-Yokohama corridor drive synthetic lubricant volume through consolidated procurement contracts with national service chains. METI fuel economy enforcement tightens most aggressively in this region due to urban emissions exposure. Bulk tanker deliveries to multi-site operators capture the highest throughput in the national market.
Kansai/Osaka
Independent service bays in the Osaka-Kobe industrial zone are piloting digital inventory integration that bypasses traditional petroleum cooperative tiers. Workshop procurement fragmentation accelerates as just-in-time systems link directly to distributor warehouses. 5W-30 specifications dominate mixed fleet servicing across manufacturing and logistics vehicle pools.
Chubu/Nagoya
Toyota-affiliated service networks in the Nagoya metropolitan area are deploying predictive maintenance scheduling tied to oil condition monitoring sensors. Factory fill programs for hybrid powertrains anchor 0W-20 demand through OEM-certified channels. JIS K 2234 certification requirements standardize performance benchmarks for regional blenders.
Kyushu
Semiconductor and battery manufacturing expansion around Fukuoka is generating fleet vehicle density underserved by premium synthetic distribution networks. Summer thermal stress drives 10W-40 specifications for commercial diesel applications in high-load conditions. PMDA-aligned quality barriers create procedural friction for imported additive packages seeking regional entry.
Hokkaido
Cold-flow performance validation requirements delay ultra-low viscosity product launches in northern prefectures, preserving residual demand for conventional mineral formulations. Extended drain interval adoption proceeds more slowly due to severe winter operating conditions. Regional petroleum cooperatives retain stronger influence over workshop supply relationships than in southern industrial corridors.
Japan Automotive Engine Oils Market Competitive Landscape
Top-tier vendors anchor integrated refining and retail networks, while mid-tier specialists compete through OEM factory fill relationships and aftermarket channel penetration. The market structure reflects consolidation among domestic petroleum majors alongside persistent fragmentation in specialty synthetic segments. Three strategic archetypes dominate: vertically integrated refiners with captive distribution, global lubricant brands leveraging R&D scale, and regional blenders serving cooperative networks. Competitive moves center on additive chemistry reinvestment for low-SAPS formulations and direct-digital channel development to capture workshop procurement fragmentation.
Within the domestic integrated tier, ENEOS Corporation and Idemitsu Kosan Co. Ltd exemplify petroleum majors with refining assets and retail network control. Castrol (BP PLC) occupies a position representing global R&D scale applied to premium synthetic positioning in aftermarket channels. These three anchors illustrate how competitive advantage splits between captive supply security and technology-led brand differentiation.
| Leading Market Players |
|---|
| Castrol (BP PLC) |
| AKT Japan Co. Ltd |
| ENEOS Corporation |
| Motul |
| Japan Sun Oil Company, Ltd. |
| Idemitsu Kosan Co. Ltd |
| Fuchs Japan Ltd. |
| ExxonMobil Corporation |
| Cosmo Energy Holdings Co., Ltd. |
| Others |
Supply & Pricing Matrix
Commercial fleet consolidation around Tokyo and Yokohama is compressing procurement timelines and forcing blenders to hold finished lubricant inventory closer to demand nodes, elevating working capital costs that feed into contract pricing premiums. METI's viscosity grade mandates accelerate formulation turnover, shortening product lifecycles and preventing scale economies from fully amortizing across production runs.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Kanto corridor fleet operators demand 48-hour replenishment cycles for bulk synthetic deliveries. Pricing stratifies across JIS K 2234 certification tiers, with factory fill-qualified formulations commanding 15-20% premiums over aftermarket equivalents. Cost compression in conventional mineral segments is intensifying as Group II base oil oversupply from regional refiners compresses blending margins. Independent workshop operators in Osaka and Nagoya exhibit highest price sensitivity, while Toyota-affiliated service networks prioritize specification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Chiba and Osaka anchor a hub-and-spoke pattern that feeds bulk terminals across Honshu, Shikoku, and Kyushu. Domestic blending capacity draws from API Group III+ base oil imports originating in South Korea, Singapore, and Thailand, creating single-source vulnerability around Korean refinery turnaround schedules. Additive package supply rests on PMDA-registered formulations from Lubrizol, Infineum, and Afton, with import documentation delays averaging 6-8 weeks. Tariff exposure on South Korean base stocks under the Japan-Korea trade framework elevates cost volatility. Distribution runs through petroleum cooperative networks that ENEOS and Idemitsu have controlled for decades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's automotive lubricant sector sits at a technology inflection as PAG and ester-based synthetics displace Group II mineral formulations in OEM factory fill programs. This transition rewards early chemistry investments while punishing legacy capacity.
For Market Incumbents: Deepen captive supply security over Group III+ base oil streams through offtake agreements with South Korean and Singaporean refiners, insulating against tariff volatility and turnaround disruptions. Accelerate low-SAPS formulation R&D to meet gasoline particulate filter compatibility requirements in next-generation Toyota and Honda powertrains. Defend distributor relationships in Hokkaido and Tohoku where petroleum cooperative loyalty remains strongest against digital channel encroachment.
For New Entrants and Emerging Players: Semiconductor manufacturing fleet operators around Fukuoka represent an underserved buyer archetype with concentrated vehicle density and limited premium synthetic penetration. Target this segment through direct technical sales emphasizing thermal stability under Kyushu summer operating conditions. Bypass legacy cooperative tiers by integrating with emerging inventory management platforms piloted in Nagoya independent workshops. Prioritize JIS K 2234 certification investment to unlock OEM-affiliated service network access.
For Investors and Strategic Acquirers: The window for entry favors additive formulation specialists with proven low-SAPS chemistry portfolios and PMDA registration expertise. Long-term viability hinges on e-fuel compatibility positioning as METI's carbon neutrality roadmap crystallizes specification requirements. Monitor Fukuoka industrial corridor fleet density growth as an inflection indicator for regional distribution network valuation. Target acquisition candidates with established relationships to Toyota-affiliated service networks in the Chubu region.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Secures Group III+ feedstock access against Korean refinery volatility and tariff exposure. |
| Low-SAPS Additive Package Development | Positions formulations for gasoline particulate filter compatibility in Toyota and Honda factory fill programs. |
| Direct Workshop Digital Integration | Bypasses petroleum cooperative tiers to capture procurement fragmentation in Osaka and Nagoya service bays. |
| E-Fuel Compatibility Certification | Aligns with METI carbon neutrality roadmap and captures synthetic gasoline blend specification uncertainty. |
| Kyushu Distribution Network Expansion | Addresses underserved semiconductor manufacturing fleet density around Fukuoka with premium synthetic logistics. |
Research Methodology
Independent corroboration across lubricant blender technical directors, commercial fleet procurement managers, and petroleum cooperative distribution heads underwrites the qualitative findings in this study. Primary interviews with OEM platform engineers at Toyota and Honda, aftermarket service bay operators in Kansai and Chubu, and additive supplier regulatory affairs specialists were cross-referenced against JIS standard documentation, METI fuel economy compliance filings, and customs trade data on base oil imports. Bottom-up volume estimates from regional distributor throughput were reconciled with top-down market sizing derived from vehicle parc analysis and drain interval assumptions.
Historical reference periods spanning vehicle registration trends, lubricant consumption intensity per kilometer, and OEM specification evolution anchored the projection framework across the analysis window. Segmentation modeling incorporated product chemistry tiers, viscosity grade specifications, packaging format economics, and channel procurement integration levels. CAGRs were derived from regression analysis against METI fuel economy mandate trajectories and hybrid powertrain penetration curves. Forecast inputs included semiconductor manufacturing investment flows into Kyushu and predictive maintenance sensor deployment rates in Nagoya service networks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to e-fuel specification finalization and South Korean base oil supply disruptions. Outputs reflect documented assumptions around OEM drain interval recommendations and JIS certification alignment. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Engine Flush Market
Powertrain
UAE Automotive Engine Oils Market
Powertrain
Automotive Transmission Repair Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Automotive Driveline Market
Powertrain
Automotive Carburetor Market
Powertrain
India Automotive Engine Oils Market
Powertrain
Automotive Hydraulic Lash Adjuster Market
Powertrain
Automotive Turbocharger Market
Powertrain
Mechanical Reciprocating Engine Market
Powertrain
Fuel Pumps Market
Powertrain
Engines Market
Powertrain
Electric Powertrain Systems Market
Powertrain
Automotive Park Brake Lever (Handbrake) Market
Powertrain
Automotive Chain Tensioners Market