
 Automotive Powertrain Components Market | 2026-2036
Automotive Powertrain Components Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Powertrain Components Market Analytics
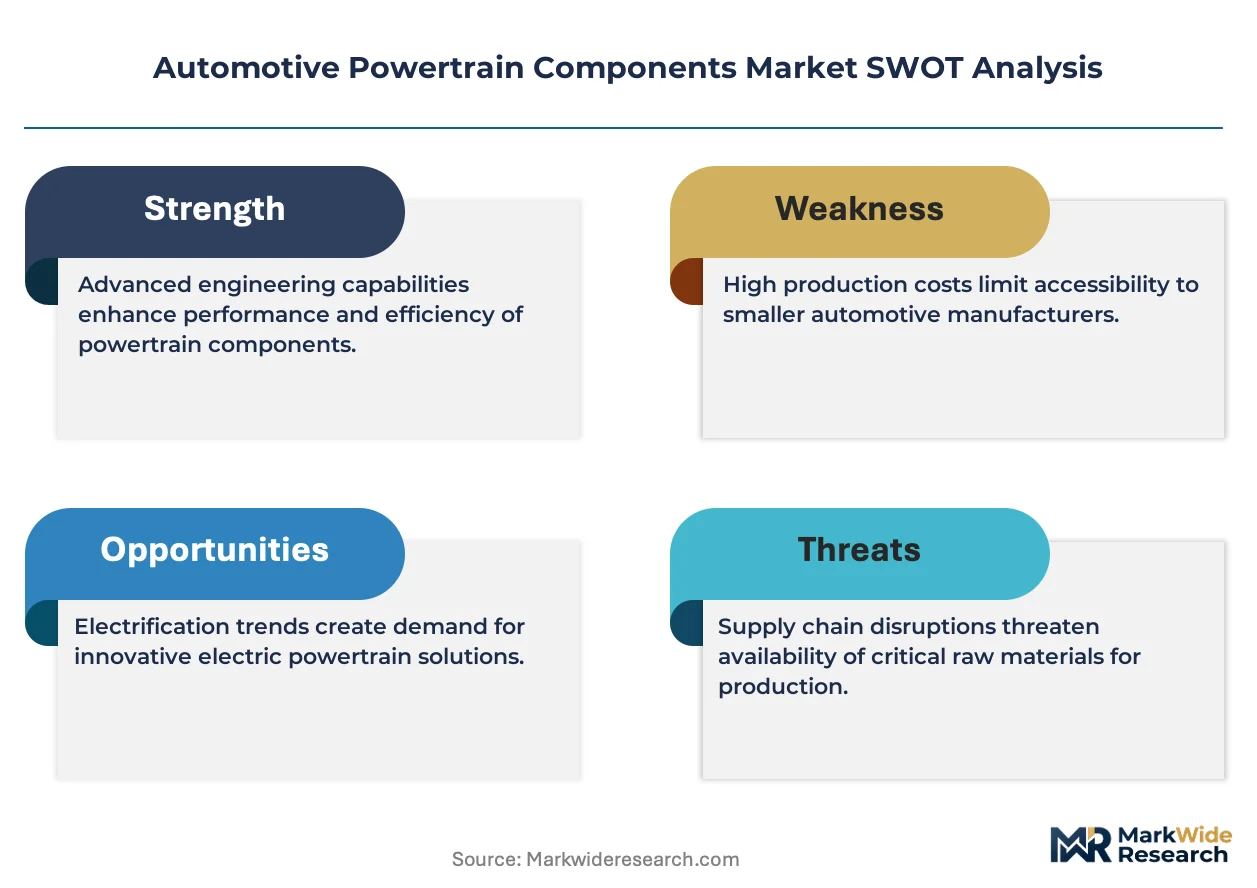
The powertrain supply base is pivoting away from interchangeable commodity hardware toward electrification-ready platforms that command engineering premiums. ZF Friedrichshafen leverages its integrated e-axle and transmission portfolio to capture value from hybrid transitions. BorgWarner sustains R&D intensity in electric propulsion while maintaining scale in turbocharging. Robert Bosch GmbH anchors its position through in-house semiconductor and motor control capabilities that differentiate module-level offerings.
Automotive powertrain components encompass the integrated mechanical and electromechanical systems—engines, transmissions, drivelines, and axles—that convert stored energy into vehicle motion, typically operating at thermal efficiencies between 20% and 45% depending on architecture and duty cycle. Engine segments remain the largest revenue pool but face margin compression as electrification shifts value toward electric motor and inverter assemblies. Transmission and driveline categories are restructuring around multi-speed e-axle designs for battery-electric platforms, while turbocharged and direct injection technologies retain relevance in hybrid applications where thermal combustion persists.
EPA tailpipe standards, the EU F-Gas Regulation, and China's MIIT new-energy vehicle mandates collectively reshape product specifications and market access thresholds across all fuel-type categories. Compliance with these frameworks demands concurrent investment in lightweight materials, thermal efficiency, and electrified subsystems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded development in powertrain architectures that fail cross-border homologation.
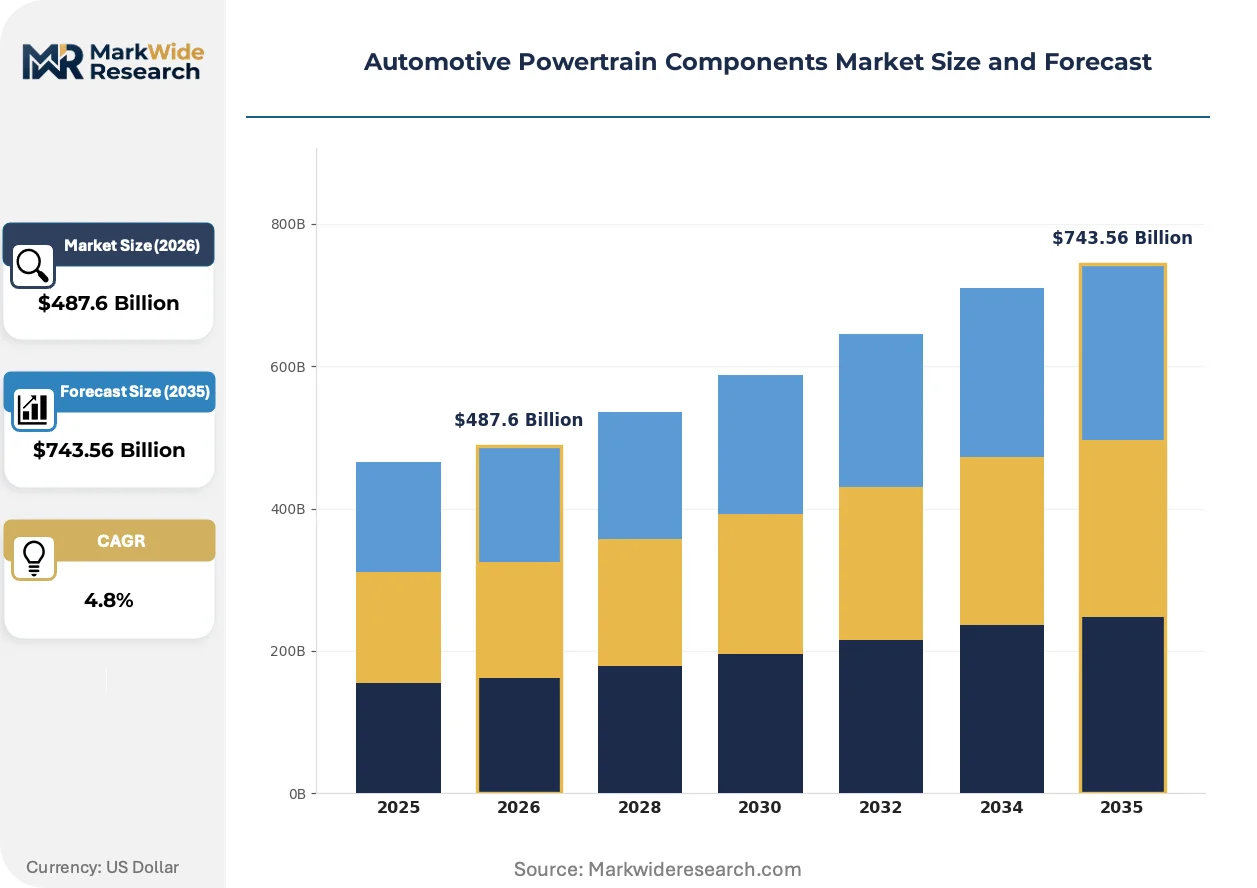
Market Dynamics
Electrification is compressing the addressable market for conventional engine hardware while simultaneously expanding the value pool for integrated electric drive units and thermal management systems across all vehicle architectures.
Growth Catalysts
- EU F-Gas Regulation:Mandates for lower-GWP refrigerants in vehicle thermal systems are accelerating redesign cycles for HVAC and battery cooling modules, creating replacement demand across hybrid and electric fleets.
- China MIIT new-energy vehicle mandates:Domestic production quotas for NEVs are pulling investment into local e-motor and inverter manufacturing capacity, concentrating engineering activity in Shanghai and Shenzhen clusters.
- 800-volt electrical architectures:Premium passenger vehicle platforms are adopting higher-voltage systems that require redesigned power electronics, silicon carbide inverters, and upgraded cable assemblies.
Market Restraints
- Neodymium and dysprosium price volatility:Rare-earth magnet supply concentration in Chinese processing facilities exposes e-motor manufacturers to input cost swings and quota restrictions.
- Legacy foundry capacity constraints:Gray iron and aluminum casting facilities in Germany and the United States face decommissioning pressure from EPA and EU industrial emissions rules, tightening supply for ICE block production.
- Homologation timeline divergence:Misaligned certification requirements between EPA tailpipe standards and China's MIIT testing protocols force redundant validation cycles for multi-market powertrain programs.
Strategic Opportunities
- Commercial vehicle fleet electrification in California:CARB Advanced Clean Trucks rules are mandating zero-emission sales percentages that outpace battery supply, opening window for range-extended hybrid powertrains.
- Vehicle-to-grid integration:Bidirectional charging hardware represents unpenetrated aftermarket and OE fitment opportunity as utilities in Germany and Japan pilot grid stabilization programs.
- Integrated thermal-fluid systems:Convergence of battery cooling, cabin HVAC, and power electronics thermal management into single-loop architectures enables module-level supplier margin expansion.
Industry Challenges
- Power electronics engineering scarcity:Shortage of specialists in wide-bandgap semiconductor application and motor control algorithm development constrains R&D velocity across tier-one suppliers.
- Legacy powertrain decommissioning:ICE-focused manufacturing assets require costly retooling or write-downs as product mix shifts, straining capital allocation for firms with concentrated transmission or engine operations.
- Software-hardware integration complexity:Coordination between inverter firmware, battery management systems, and vehicle control units demands new supplier-OEM interface protocols that lack industry standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Powertrain Components Market |
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $743.56 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Engine, Transmission, Driveline, Axle Fuel Type: Gasoline, Diesel, Electric, Hydrogen Vehicle Type: Passenger Car, SUV, Truck, Bus Technology: Hybrid, Turbocharged, Direct Injection, Variable Valve Timing |
| Companies Covered | ZF Friedrichshafen AG, BorgWarner Inc., Robert Bosch GmbH, Magna International Inc., Denso Corporation, Aisin Corporation, Continental AG, Schaeffler AG, JTEKT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Powertrain Components Market Evolving Landscape
Powertrain component engineering is converging around platform architectures that serve multiple electrification degrees, from mild hybrid to full battery-electric, reducing per-variant development overhead.
Multi-in-one e-axle systems are consolidating motor, gearbox, and inverter into single housing units. Tier-one suppliers in Germany and Japan are adopting these integrated modules for B-segment and C-segment vehicle programs. This physical integration is unifying what were three separate supply chains into single-source procurement relationships, compressing supplier count per vehicle and elevating engineering accountability.
EPA tailpipe standards and the EU F-Gas Regulation are tightening in parallel, forcing concurrent investment in combustion efficiency and refrigerant chemistry. Powertrain engineers must optimize thermal systems for both ICE waste heat rejection and battery thermal conditioning. Hybrid architectures face the steepest compliance burden, as they must satisfy dual certification paths for engine emissions and electric range verification.
Fleet procurement departments are consolidating supplier relationships around full-system integrators capable of delivering complete electrified drivelines. Single-source contracting for e-axle assemblies is displacing component-level sourcing of motors, inverters, and gearboxes separately. This pattern is most visible in North American commercial vehicle segments, where fleet operators prioritize total cost of ownership guarantees over component-level price negotiation.
Automotive Powertrain Components Market Segmentation
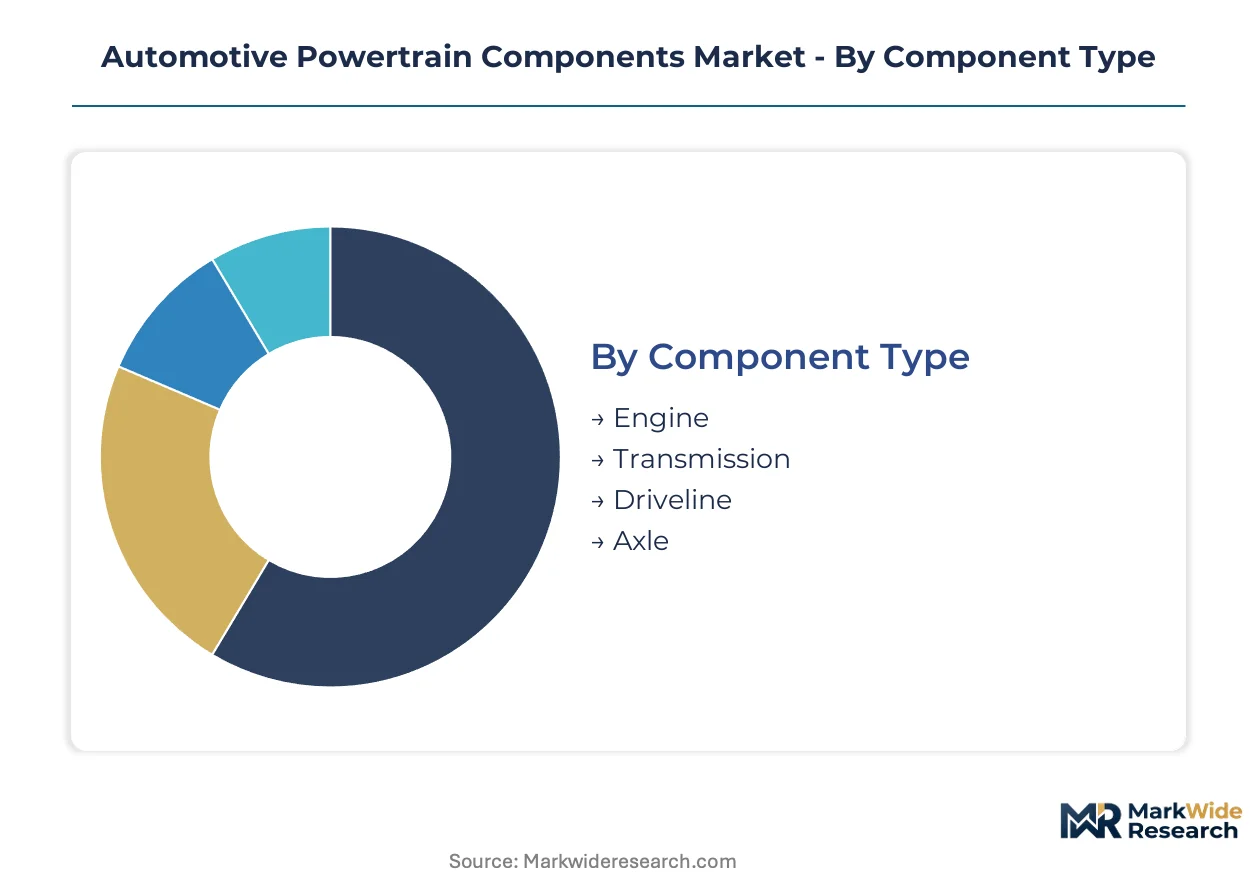
Powertrain component demand fragments across mechanical, electromechanical, and electronic subsystems, each with divergent margin profiles and supplier ecosystems. Segmentation clarity enables capital allocation toward electrification-ready platforms while managing legacy ICE exposure.
Component Type:
Supply concentration in integrated e-axle modules is compressing the supplier base for discrete transmission and driveline hardware.
- Engine:Cast aluminum and compacted graphite iron blocks with integrated thermal management passages serve hybrid applications where combustion persists. ICE engineering centers in Germany and the United States face decommissioning pressure as OEMs consolidate powertrain R&D into electrified architectures.
- Transmission:Multi-speed e-axle gearboxes with integrated differential functions are displacing conventional torque converter automatics. Demand clusters around Shanghai and Stuttgart engineering hubs developing 2-speed and 3-speed designs for 800-volt platforms.
- Driveline:Constant velocity joints and propeller shafts retain relevance in all-wheel-drive hybrids. Lightweight carbon fiber driveshafts command premiums in performance segments.
- Axle:Modular axle carriers with integrated motor mounts support skateboard battery platforms. Foundry capacity constraints in the United States limit casting supply for heavy-duty variants.
Today's leader: Engine. Tomorrow's challenger: Transmission.
Fuel Type:
Application-driven procurement patterns split investment between compliance-driven electrification and residual ICE efficiency programs.
- Gasoline:Downsized turbocharged direct injection engines with Miller cycle optimization retain volume in mild hybrid architectures. China's MIIT fuel consumption standards accelerate 48V belt-integrated starter-generator adoption.
- Diesel:Compression ignition with selective catalytic reduction faces fleet procurement contraction in California under CARB Advanced Clean Trucks rules. Remaining demand concentrates in European commercial vehicle segments.
- Electric:Permanent magnet synchronous and induction motor topologies dominate battery-electric platforms. Rare-earth magnet supply concentration in Chinese processing facilities exposes manufacturers to quota volatility.
- Hydrogen:Proton exchange membrane fuel cell stacks with integrated air compression systems serve heavy-duty trucking corridors in Germany and Japan. METI hydrogen roadmap targets concentrate engineering activity in Nagoya and Tokyo clusters.
Electric platforms are climbing the fastest; hydrogen holds steepest expansion trajectory in commercial segments.
Vehicle Type:
Volume distribution across passenger and commercial segments determines capital intensity requirements for component validation and manufacturing scale.
- Passenger Car:Front-wheel-drive compact platforms with integrated e-motor transaxles represent highest unit volumes. EPA tailpipe standards drive powertrain electrification faster than SUV segments due to fleet-average compliance mathematics.
- SUV:All-wheel-drive architectures with dual-motor e-axle configurations command module-level supplier premiums. Weight-class regulations in the United States favor electrified powertrains for mid-size crossovers.
- Truck:Light-duty pickup hybridization focuses on towing-cycle thermal management. Heavy-duty segments face CARB zero-emission mandates that outpace battery supply, opening range-extended hybrid windows.
- Bus:Depot-charged battery-electric and fuel cell configurations dominate municipal procurement in Germany and China. Route predictability enables optimized battery sizing versus dynamic duty cycles.
Passenger Car volumes anchor current revenue; Bus electrification is gaining share fastest in module supplier portfolios.
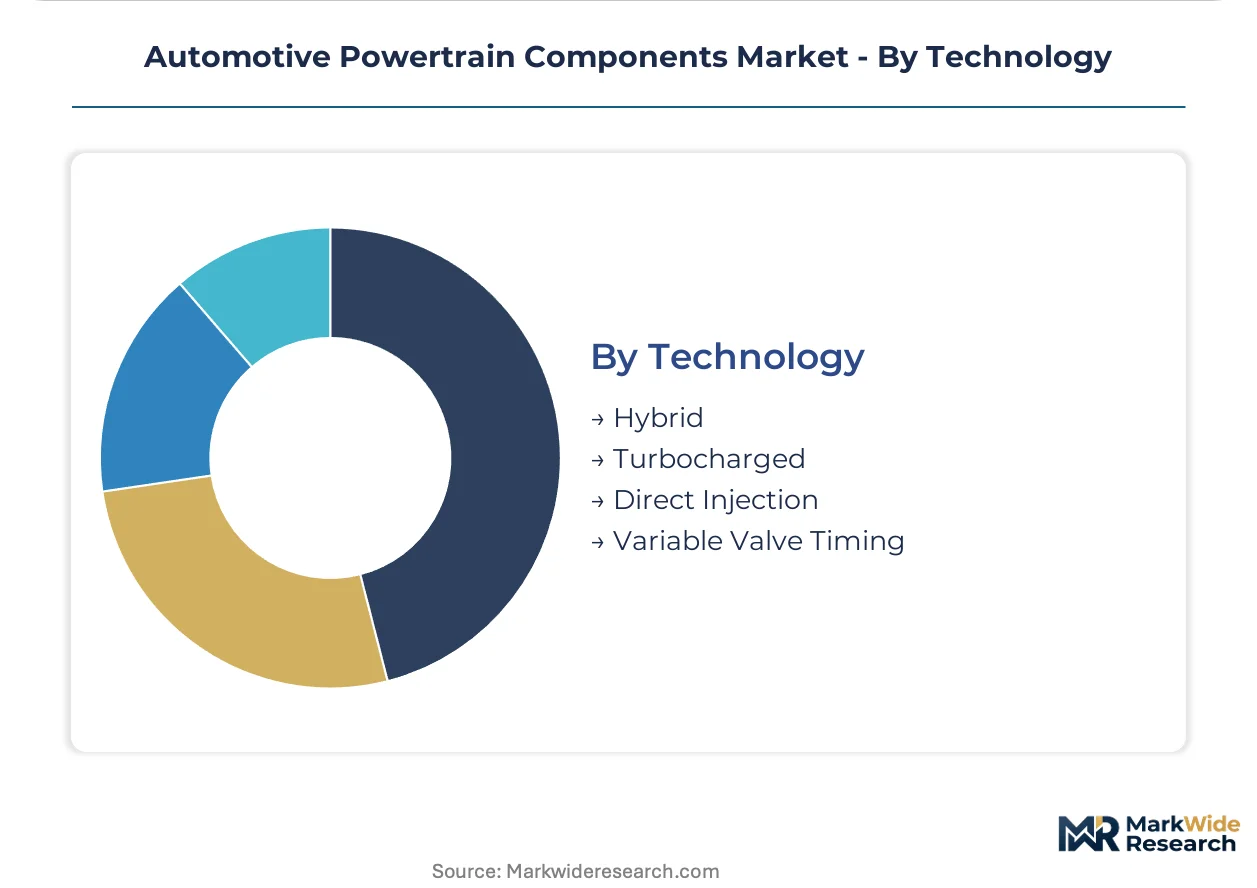
Technology:
Margin stratification separates mature combustion optimization from electrification-enabling systems commanding engineering premiums.
- Hybrid:Power-split and P2 parallel architectures with clutch-integrated e-motors bridge ICE and electric platforms. Dual certification burdens for engine emissions and electric range verification strain development resources.
- Turbocharged:Variable geometry and electric-assisted turbochargers maintain relevance in downsized hybrid engines. BorgWarner and Mitsubishi Heavy Industries concentrate production in Japan and Germany.
- Direct Injection:High-pressure gasoline and diesel injection systems face particulate emissions scrutiny under EU F-Gas Regulation adjacent standards. Piezoelectric injector supply concentrates in Bosch and Denso manufacturing networks.
- Variable Valve Timing:Cam phasing and cylinder deactivation technologies retain cost advantages in entry hybrid segments. Electromechanical actuation displaces hydraulic systems in premium architectures.
Hybrid systems dominate current module pricing; variable valve timing faces steepest margin compression from electrification displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Powertrain engineering talent clusters in Germany, China, and the United States anchor the industry's geographic footprint. These concentrations host the densest networks of OEM powertrain development centers and tier-one supplier technical facilities. Regulatory divergence between EPA, EU F-Gas, and MIIT frameworks forces parallel compliance investments across all three jurisdictions.
United States
Commercial vehicle fleet operators in California drive electrified powertrain procurement under CARB Advanced Clean Trucks mandates. EPA tailpipe standards tighten thermal efficiency requirements for remaining ICE applications. Detroit and Ann Arbor engineering clusters concentrate hybrid powertrain development for light-duty pickup segments.
Germany
Automotive OEM headquarters in Munich and Stuttgart sustain premium-tier powertrain R&D investment despite ICE phase-out timelines. EU F-Gas Regulation accelerates refrigerant system redesigns for thermal management modules. Baden-Württemberg foundry capacity faces decommissioning pressure from industrial emissions rules.
China
Domestic NEV production quotas under MIIT directives pull e-motor and inverter manufacturing investment toward Shanghai and Shenzhen. Battery-electric platform engineering concentrates in Yangtze River Delta clusters. Rare-earth magnet processing dominance in Jiangxi and Inner Mongolia shapes e-motor supply security calculations.
Japan
Hybrid powertrain expertise accumulated over two decades sustains technology licensing revenue streams. METI hydrogen roadmap targets concentrate fuel cell stack development in Nagoya and Tokyo corridors. JIS standards alignment with EPA test protocols reduces redundant validation burdens for multi-market programs.
South Korea
Battery-electric platform specialists in Seoul Capital Area supply integrated e-axle modules to global OEM programs. Government new-energy vehicle subsidies accelerate local inverter and power electronics capacity expansion. Busan-Ulsan manufacturing belt hosts dedicated BEV transmission production lines.
Automotive Powertrain Components Market Competitive Landscape
Capital-heavy foundry operators compete with asset-light system integrators for margin capture in electrified architectures. The supply base compresses around full-system providers capable of delivering complete e-axle assemblies rather than discrete components. Three archetypes dominate: diversified industrial conglomerates with captive semiconductor capabilities, transmission specialists pivoting toward multi-speed e-axle designs, and electric motor manufacturers securing rare-earth supply chains. Competitive moves center on foundry asset retooling and strategic partnerships for 800-volt platform qualification.
Within the integrated systems tier, ZF Friedrichshafen AG and BorgWarner Inc. exemplify the transition from mechanical transmission heritage toward electrified driveline portfolios. Robert Bosch GmbH anchors the semiconductor-integrated archetype through in-house motor control capabilities. These three entities represent divergent strategic responses to the same electrification imperative—vertical manufacturing depth, transmission engineering adaptation, and electronics integration respectively.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| BorgWarner Inc. |
| Robert Bosch GmbH |
| Magna International Inc. |
| Denso Corporation |
| Aisin Corporation |
| Continental AG |
| Schaeffler AG |
| JTEKT Corporation |
| Others |
Value Network & Pricing Analysis
Power electronics engineering talent concentration in Baden-Württemberg and Shanghai widens labor-cost spreads between integrated e-axle modules and discrete component sourcing. Tier-one suppliers leverage this differential to command engineering premiums for silicon carbide inverter and multi-speed gearbox bundles.
Pricing Analysis
Bundled e-axle assemblies versus unbundled motor-inverter-gearbox procurement defines the pricing split. Three-tier pricing structure across premium 800-volt platforms, standard 400-volt architectures, and economy mild-hybrid systems tracks certification complexity and thermal management content. Cost compression in entry hybrid tiers is intensifying because Chinese MIIT fuel consumption standards force 48V system adoption at scale. Fleet procurement departments show lowest price sensitivity for integrated thermal-fluid systems, while aftermarket distributors resist module-level premiums.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Detroit anchor hub-and-spoke patterns for just-in-sequence delivery to final assembly plants. Manufacturing concentration in Germany, China, and Japan feeds from rare-earth magnet processing in Jiangxi, aluminum casting in Baden-Württemberg, and silicon carbide wafer production in Aichi. Single-source vulnerability in Chinese dysprosium refining exposes e-motor manufacturers to quota volatility. Distribution runs through OEM-owned sequencing centers rather than independent wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive powertrain components market functions as a stable compounder. Regulatory compliance mandates across EPA, EU F-Gas, and MIIT frameworks generate replacement demand cycles that sustain revenue visibility.
For Market Incumbents: Lock in rare-earth supply agreements with Jiangxi processors before quota restrictions tighten. Retool foundry assets in Germany for aluminum e-axle housings rather than gray iron engine blocks. Electrification-ready platform engineering represents the priority defensive lever against emerging Chinese e-motor specialists.
For New Entrants and Emerging Players: Capture vehicle-to-grid bidirectional charging hardware fitment before utility pilots in Germany and Japan scale. California commercial vehicle fleet electrification under CARB rules presents the most penetrable white-space. Partner with established thermal management suppliers for integrated battery-cabin HVAC modules rather than competing on discrete components.
For Investors and Strategic Acquirers: Valuations sit cheapest among transmission specialists pivoting toward multi-speed e-axle designs with proven OEM qualification. Long-term viability centers on semiconductor-integrated power electronics capabilities. Watch 800-volt platform adoption rates across premium German OEM lineups as the inflection signal for margin expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces per-variant development overhead across mild hybrid to battery-electric architectures. |
| Battery Supply Agreement | Secures cell capacity for integrated thermal-fluid system bundling with e-axle modules. |
| Software-Defined Vehicle Investment | Unifies inverter firmware with battery management systems under single supplier accountability. |
| Geographic Manufacturing Footprint | Positions production near Shanghai and Stuttgart engineering clusters for 800-volt qualification. |
| Charging Infrastructure Partnership | Opens aftermarket vehicle-to-grid hardware channels through utility pilot programs in Germany. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA certification filings, and EU F-Gas regulatory disclosures. Bottom-up segment sizing and top-down macroeconomic cross-checks anchored forecast triangulation.
Segment-weighting approaches applied propulsion architecture, vehicle class, content per vehicle, and regional production cluster dimensions across the modeling period. CAGRs emerged from fitted growth curves against historical penetration patterns. Forecast inputs incorporated MIIT NEV quota trajectories and CARB Advanced Clean Trucks compliance timelines without year-specific assumptions.
Underlying measurement precision varies by segment; electric motor and inverter assemblies carry tighter precision than legacy transmission categories given faster technology turnover. Forecasts reflect documented assumptions around rare-earth supply continuity and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Diesel Engine Catalyst Market
Powertrain
Engine Actuators Market
Powertrain
Automotive Driveshaft Couplings Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
Canada Automotive Engine Oils Market
Powertrain
Global Automotive Drive Shaft Market
Powertrain
Automotive Transmission Repair Market
Powertrain
LNG Engine Market
Powertrain
Automotive Clutch Slave Cylinder Market
Powertrain
CNG Powertrain Market
Powertrain
Europe Automatic Transmission for Passenger Car Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Automotive Vacuum Brake Booster Market
Powertrain
Yaw Damper Market
Powertrain
Internal Combustion Engine Market
Powertrain
Modular Belt Drive Market