
 Clutch Hub Puller Market | 2026-2036
Clutch Hub Puller Market Size, Share, and Industry Trends Forecast 2026-2036
Clutch Hub Puller Market Insights
Chrome-vanadium alloy steel is rebalancing cost-performance tradeoffs in clutch hub puller production as manufacturers shift from conventional carbon steel. Barnett Tool & Engineering leverages proprietary heat-treatment processes to sustain premium positioning in motorcycle specialty tools. OTC Tools anchors its distribution through integrated service-bay equipment channels across North American automotive aftermarket networks. Jims Machine specializes in Harley-Davidson-compatible puller geometries that dominate cruiser motorcycle service segments.
A clutch hub puller is a mechanical extraction device designed to remove pressed-fit clutch hub assemblies from transmission shafts without component damage, typically employing hardened steel jaws rated for torque loads exceeding 150 ft-lb and precision-threaded forcing screws. The tool serves primary purpose in disassembly operations for motorcycle, automotive, and industrial powertrain maintenance where hub-to-shaft interference fits prevent manual removal. Mechanical pullers retain the largest installed base due to universal compatibility and zero auxiliary power requirements, while hydraulic pullers capture expanding share in heavy machinery end-use where seized components demand controlled force multiplication. Small and medium sizes concentrate volume in automotive repairs and marine services, whereas large and extra-large units command margin concentration in aerospace maintenance applications requiring certified calibration protocols.
The EPA regulates chromium emissions from electroplating operations used in corrosion-resistant puller finishes, while OSHA mandates guarding standards for high-torque hand tools in commercial repair environments. ISO 9001 quality management certification shapes supplier qualification criteria for aerospace maintenance procurement channels. Stakeholders must monitor evolving alloy sourcing constraints and tier-1 distributor consolidation to preserve component availability and service-level performance.
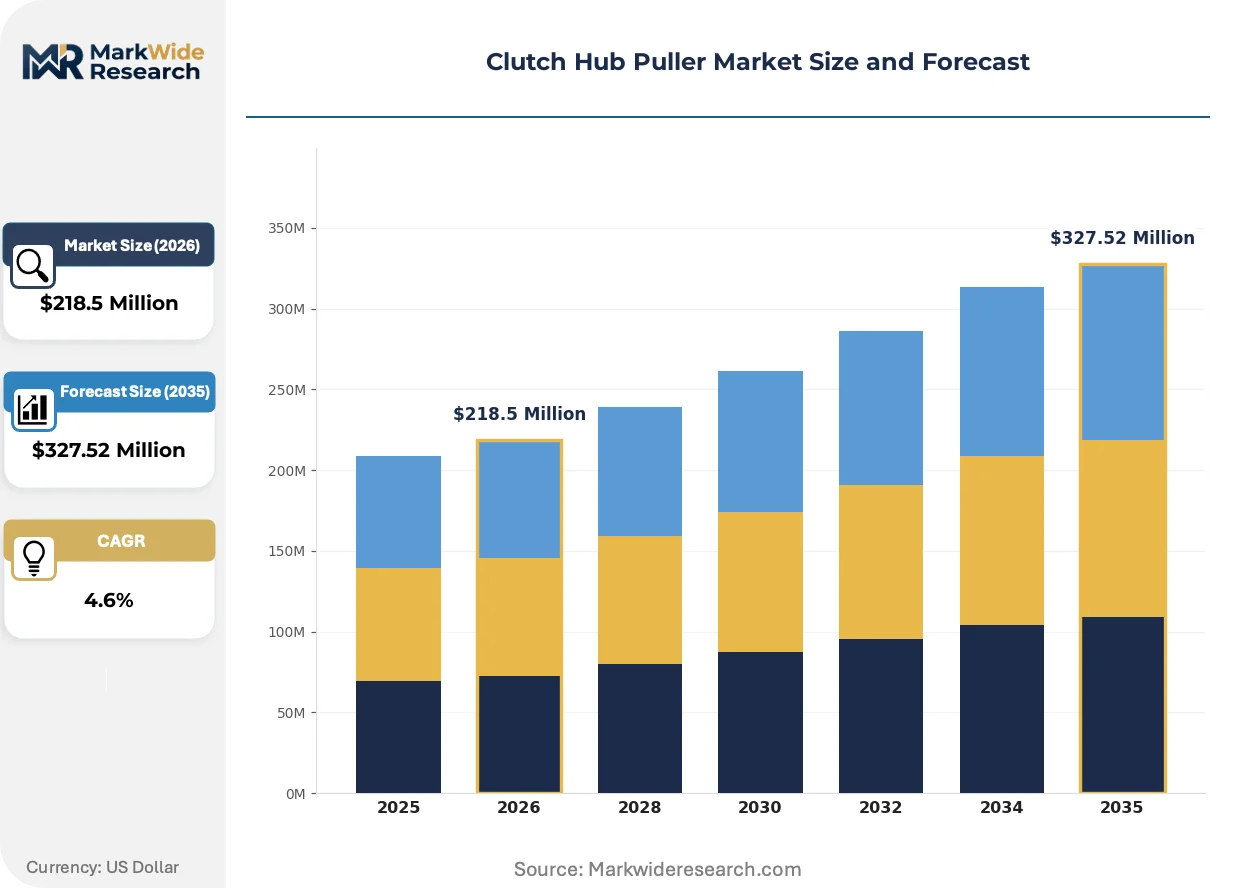
Market Dynamics
Chrome-vanadium alloy adoption is compressing production economics for clutch hub puller manufacturers, forcing carbon steel suppliers to defend position through volume pricing while heat-treatment specialists capture margin from performance differentiation.
Growth Catalysts
- EPA Chromium Emission Limits:Electroplating restrictions are accelerating dry-film lubricant adoption for corrosion protection, opening specialty coating channels for premium tool lines.
- Automotive Powertrain Complexity:Dual-clutch and automated manual transmission proliferation is expanding puller utilization rates in dealership service bays.
- ISO 9001 Certification Mandates:Aerospace maintenance procurement channels now require documented calibration protocols, concentrating demand among certified manufacturers.
Market Restraints
- Alloy Sourcing Concentration:Chrome-vanadium supply chains cluster in specific metallurgical regions, exposing fabricators to raw material disruption.
- OSHA Guarding Compliance Costs:High-torque hand tool safety mandates are elevating production overhead for smaller machine shop suppliers.
- Hydraulic Puller Substitution:Force-multiplication alternatives are capturing heavy machinery maintenance where seized components exceed mechanical puller torque ratings.
Strategic Opportunities
- Marine Service Underpenetration:Outboard motor and inboard transmission repair networks in coastal United States regions lack specialized puller distribution.
- CE Marking Harmonization:EU regulatory convergence is simplifying multi-country aftermarket entry for standardized tool geometries.
- Integrated Service-Bay Equipment Bundling:Lift and diagnostic system distributors are creating captive channels for complementary extraction tools.
Industry Challenges
- Heat-Treatment Skill Scarcity:Precision metallurgy expertise for proprietary hardening processes is concentrating among aging specialist workforces.
- Aerospace Calibration Timelines:NIST-traceable certification cycles extend 12-18 months, delaying new product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clutch Hub Puller Market |
| Market Size in 2026 | $218.5 Million |
| Market Size in 2035 | $327.52 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Puller, Mechanical Puller, Pneumatic Puller, Electric Puller End User: Automotive Repairs, Heavy Machinery, Aerospace Maintenance, Marine Services Size: Small, Medium, Large, Extra Large Material: Steel, Aluminum, Plastic, Composite |
| Companies Covered | Mastercool, Barnett Tool & Engineering, V T-win, Jims Machine, Lowbrow Customs, Evolution, Lisle Corporation, OTC Tools, Sunex Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clutch Hub Puller Market Trends and Innovations
Tool manufacturers are repositioning around material science differentiation and regulatory compliance automation, compressing traditional price-performance tradeoffs while expanding certified application coverage.
Modular jaw systems with interchangeable geometry sets are expanding into multi-platform service operations, allowing single puller bodies to address Harley-Davidson, metric motorcycle, and automotive transmission configurations. Independent repair shops in Germany and the United States are adopting these systems to reduce capital tied in single-purpose inventory. The technology is expanding into mobile service van operations where space constraints previously limited tool carrying capacity.
REACH substance restrictions on hexavalent chromium compounds are forcing electroplating process redesign across European manufacturing facilities, elevating capital requirements for corrosion-resistant finish application. Tool producers serving EU aftermarket channels are responding with physical vapor deposition alternatives that meet environmental standards without sacrificing wear resistance. This regulatory pressure is compressing finish cost differentials between premium and standard product tiers.
Certification-driven procurement is displacing price-primary purchasing in aerospace and fleet maintenance segments, where documented calibration chains now outweigh unit cost in supplier selection. Tier-1 distributors are consolidating technical documentation responsibilities to capture this preference shift. The pattern is most visible in United States defense contractor maintenance networks and German commercial aviation service operations.
Clutch Hub Puller Market Segmentation
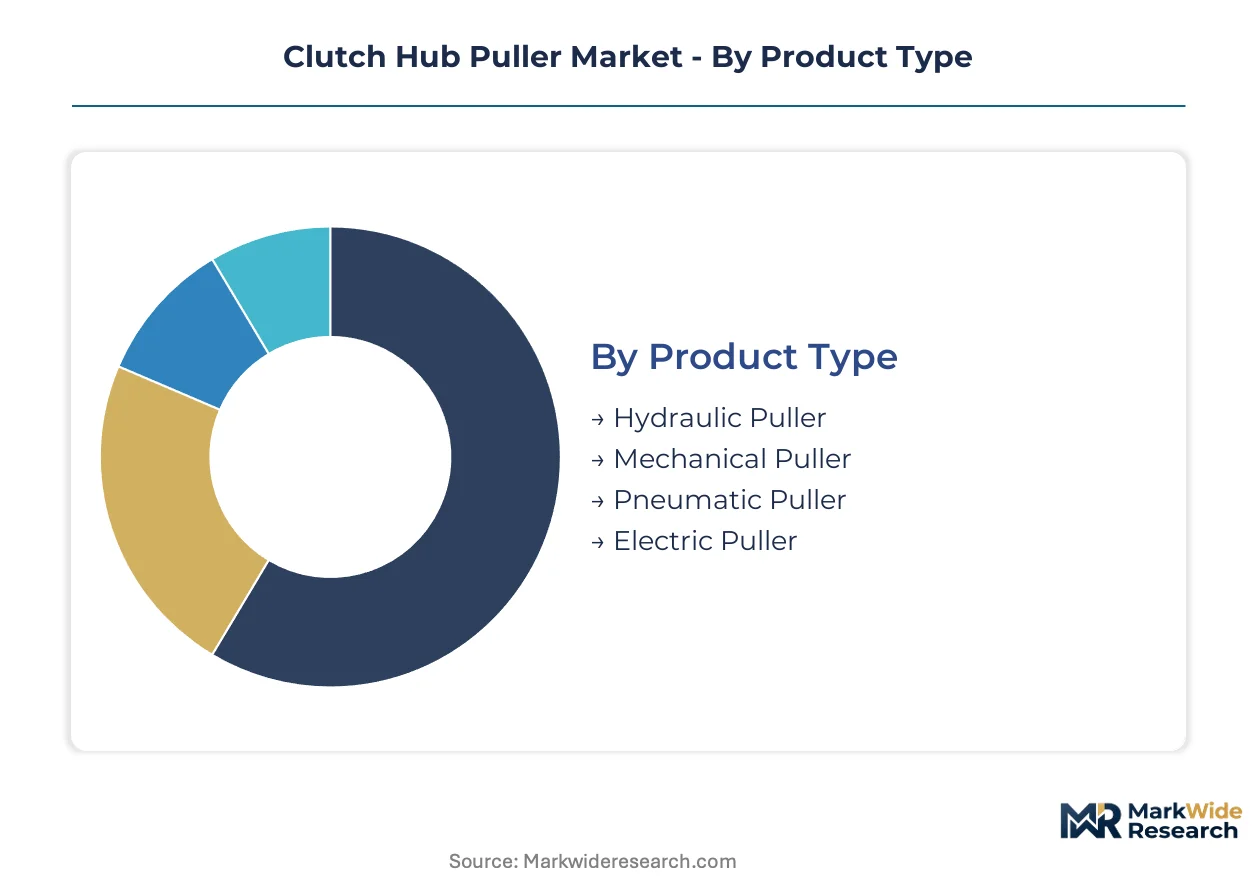
Clutch hub puller procurement channels diverge sharply across certification regimes, with aerospace and fleet maintenance demanding NIST-traceable calibration chains while independent repair shops prioritize universal compatibility. Material specifications and force delivery mechanisms further stratify supplier qualification requirements across end-use segments.
Product Type:
ISO 9001 documentation requirements concentrate among hydraulic and electric puller lines serving aerospace contractors, whereas mechanical variants face lighter certification burdens in general automotive aftermarket channels.
- Mechanical Puller:Hardened steel jaws and precision-threaded forcing screws deliver torque loads exceeding 150 ft-lb without auxiliary power requirements. Demand concentrates in United States independent repair shops and German dealership service bays where dual-clutch transmission proliferation expands utilization rates.
- Hydraulic Puller:Force-multiplication systems deploy controlled pressure for seized components exceeding mechanical puller ratings. Heavy machinery maintenance in China's industrial belt and Germany's Ruhr manufacturing corridor drives adoption where component seizure demands graduated extraction force.
- Pneumatic Puller:Compressed-air actuation suits high-volume fleet maintenance operations with existing shop air infrastructure.
- Electric Puller:Battery-powered units gain traction in mobile service van operations across United States coastal regions.
Mechanical Puller sits at the top of the volume ranking, with Hydraulic Puller climbing the fastest.
End User:
Cost tier stratification separates capital-intensive certified procurement from price-sensitive aftermarket purchasing, with aerospace and marine segments commanding premium positioning through documentation requirements.
- Automotive Repairs:Dealership service bays and independent shops drive standard-duty puller turnover across transmission and clutch replacement workflows. United States aftermarket networks and German automotive service chains concentrate procurement volume as powertrain complexity elevates tool utilization.
- Aerospace Maintenance:NIST-traceable calibration protocols and 12-18 month certification cycles create barriers to supplier entry. United States defense contractor networks and German commercial aviation operations mandate documented calibration chains that displace price-primary purchasing.
- Heavy Machinery:Seized component extraction demands force-multiplication capabilities in mining and construction equipment servicing.
- Marine Services:Outboard motor and inboard transmission repair networks in United States coastal regions show distribution gaps for specialized puller geometries.
Automotive Repairs commands the largest procurement base, though Aerospace Maintenance delivers the steepest margin expansion trajectory.
Size:
Application scale determines dimensional requirements, with precision automotive work favoring compact geometries and industrial extraction demanding extended reach and jaw capacity.
- Small:Compact dimensions suit motorcycle transmission service and confined engine bay access. Metric motorcycle repair operations in Germany and Harley-Davidson service segments in the United States drive specification diversity.
- Medium:Intermediate jaw span addresses standard automotive clutch hub diameters across passenger vehicle fleets.
- Large:Extended reach configurations serve commercial vehicle and industrial powertrain maintenance.
- Extra Large:Heavy-duty frames rated for aerospace turbine and marine propulsion system extraction command certified calibration protocols.
Medium size dominates unit shipments, with Small sizes expanding most quickly through modular multi-platform system adoption.
Material:
Supply concentration in chrome-vanadium metallurgical regions shapes fabrication economics, with REACH-compliant finish alternatives compressing cost differentials between premium and standard tiers.
- Steel:Chrome-vanadium alloy delivers optimal strength-to-weight ratios for high-torque applications. Heat-treatment specialists in Germany and the United States capture margin through proprietary hardening processes that sustain premium positioning.
- Aluminum:Lightweight properties suit mobile service operations where tool carrying capacity constraints govern selection.
- Plastic:Non-marring contact surfaces protect polished transmission shafts in specialty automotive restoration.
- Composite:Hybrid material structures balance corrosion resistance with weight reduction for marine environment exposure.
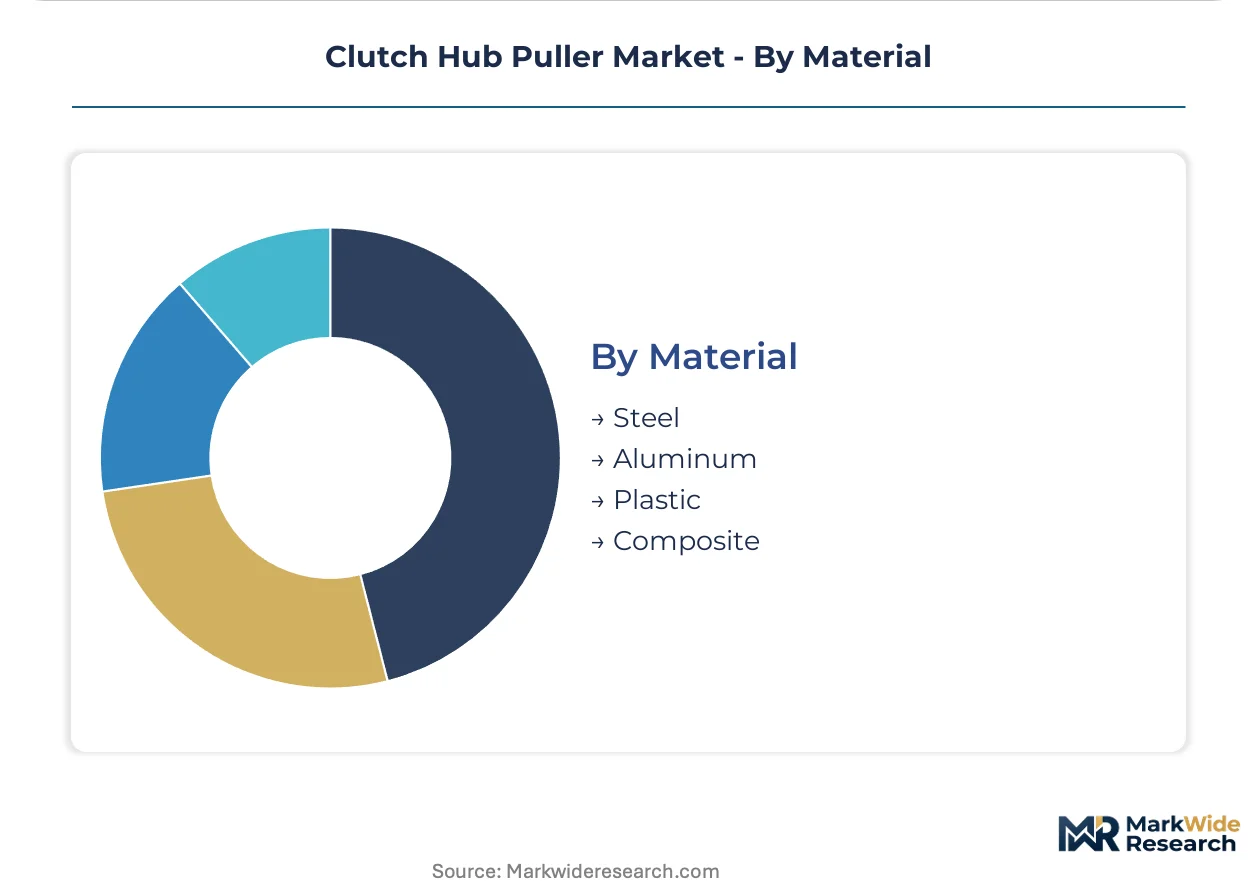
Steel retains the dominant fabrication share, with Aluminum gaining share fastest through service van equipment lightweighting priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr manufacturing corridor concentrates precision metallurgy expertise for clutch hub puller fabrication. United States aftermarket networks and Chinese industrial zones anchor procurement volume across automotive and heavy machinery segments. Regulatory divergence between EPA chromium limits and REACH substance restrictions shapes finish technology adoption.
United States
Dealership service bays and independent repair shops drive standard-duty mechanical puller turnover as dual-clutch transmission proliferation elevates tool utilization rates. EPA chromium emission limits from electroplating operations accelerate dry-film lubricant adoption for corrosion-resistant finishes. Chicago-Milwaukee industrial corridor hosts distributors bundling extraction tools with integrated service-bay equipment.
Germany
Commercial aviation maintenance operations and metric motorcycle repair networks concentrate demand for ISO 9001-certified hydraulic puller lines. REACH substance restrictions on hexavalent chromium compounds force electroplating process redesign toward physical vapor deposition alternatives. Stuttgart engineering cluster sustains proprietary heat-treatment specialists capturing margin through hardening process differentiation.
China
Heavy machinery maintenance in industrial belts demands force-multiplication hydraulic systems for seized component extraction. SAMR quality certification requirements shape supplier qualification for domestic aerospace procurement channels. Yangtze River Delta manufacturing zones concentrate chrome-vanadium alloy supply chains for fabricator feedstock security.
Japan
Precision automotive powertrain service operations favor compact mechanical puller geometries for confined engine bay access. METI industrial standards govern tool safety specifications for commercial repair environment compliance. Nagoya automotive supplier cluster integrates extraction tools into dealership service equipment procurement systems.
India
Two-wheeler transmission repair networks drive small-size puller specification diversity across metric motorcycle service segments. BIS quality certification mandates shape import substitution patterns for domestic tool fabrication capacity. Pune-Nashik industrial corridor hosts emerging suppliers targeting cost-optimized mechanical puller production.
Clutch Hub Puller Market Competitive Landscape
Global majors compete with regional champions across certification documentation and distribution channel control. The vendor base stratifies into three tiers: aerospace-certified specialists commanding premium positioning, automotive aftermarket generalists competing on universal compatibility, and motorcycle-focused niche players dominating cruiser service segments. Strategic archetypes include heat-treatment specialists leveraging proprietary metallurgy, integrated service-bay equipment distributors capturing captive channels, and modular system innovators reducing single-purpose inventory requirements. Competitive moves concentrate on tier-1 distributor consolidation and REACH-compliant finish technology licensing.
Among United States-based fabricators, OTC Tools and Lisle Corporation occupy positions within automotive aftermarket distribution networks. Jims Machine exemplifies the motorcycle specialization archetype through Harley-Davidson-compatible geometries. Barnett Tool & Engineering represents heat-treatment differentiation specialists sustaining premium positioning. These three anchors illustrate competitive positioning across certification regimes, platform specificity, and metallurgical capability vectors.
| Leading Market Players |
|---|
| Mastercool |
| Barnett Tool & Engineering |
| V T-win |
| Jims Machine |
| Lowbrow Customs |
| Evolution |
| Lisle Corporation |
| OTC Tools |
| Sunex Tools |
| Others |
Pricing and Supply Chain Analysis
Captive heat-treatment capacity anchors both supply security and premium pricing power for clutch hub puller fabricators serving aerospace and certified automotive channels. Proprietary metallurgy investments insulate margin structures from commodity steel volatility while compressing cost-performance differentials between chrome-vanadium and carbon steel tiers.
Pricing Analysis
Chrome-vanadium alloy cost pass-through dominates pricing structures across mechanical puller lines, with heat-treatment specialists capturing margin premiums through proprietary hardening processes. Price differentiation hinges on ISO 9001 certification grade and NIST-traceable calibration documentation, separating aerospace procurement from aftermarket automotive channels. Pricing pressure intensifies in standard-duty segments as REACH-compliant finish technologies compress cost differentials between premium and standard tiers. Independent repair shops exhibit highest price sensitivity, while defense contractor networks prioritize documented calibration chains over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with chrome-vanadium feedstock concentration in Germany's Ruhr corridor and China's Yangtze River Delta manufacturing zones. Fabrication draws from specialized alloy suppliers, precision forging operations, and REACH-compliant finish applicators. Tariff exposure on metallurgical imports from concentrated supply regions elevates input cost volatility for North American fabricators. Distribution runs through integrated service-bay equipment channels and tier-1 automotive aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
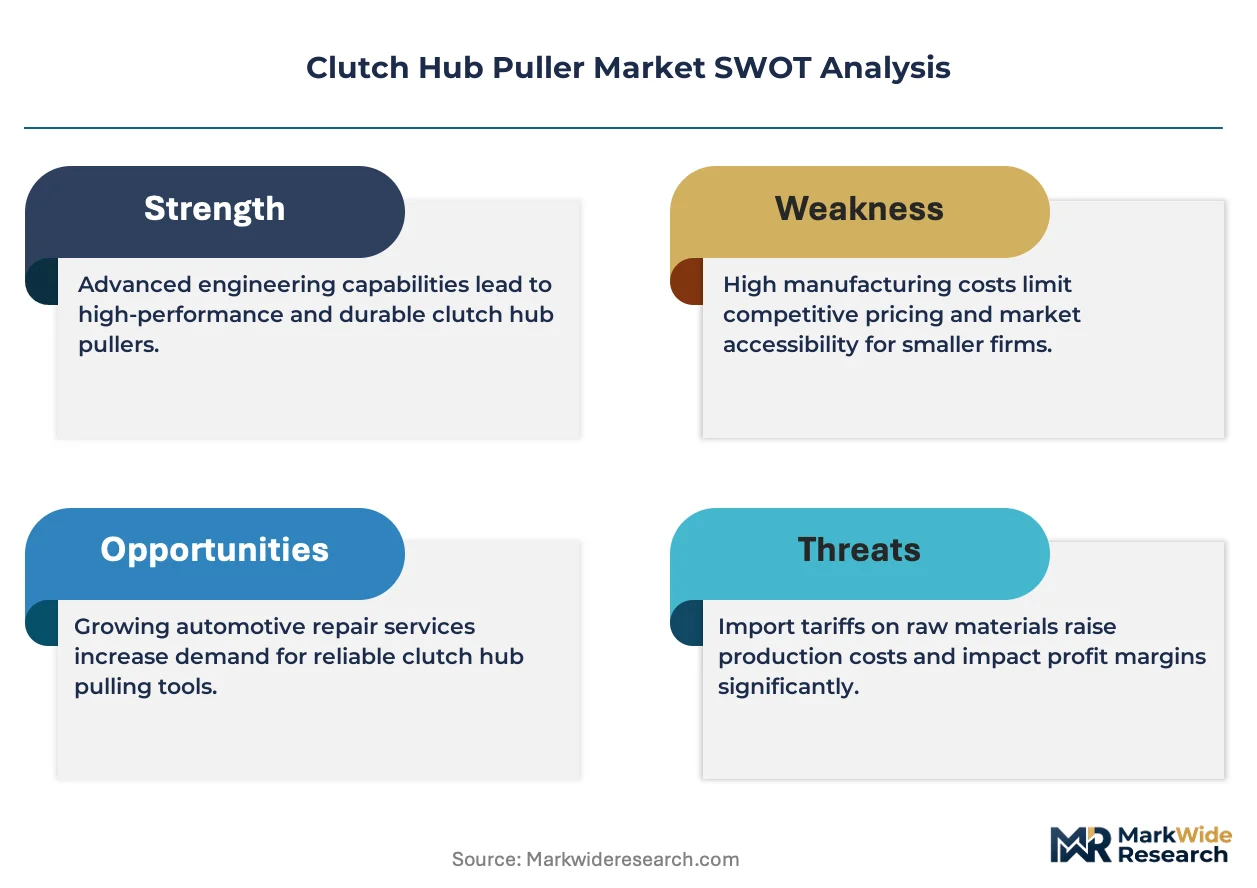
Margin expansion in clutch hub puller fabrication rests on REACH-compliant finish technology licensing and modular system architectures that reduce customer inventory carrying costs.
For Market Incumbents: Deepen proprietary heat-treatment capacity to defend margin position against carbon steel suppliers deploying volume pricing. Secure tier-1 distributor consolidation in United States automotive aftermarket networks to preempt hydraulic puller substitution in heavy machinery segments. Invest in NIST-traceable calibration infrastructure to capture aerospace procurement channel preference shifts. For New Entrants and Emerging Players: Modular jaw system technology offers entry leverage into mobile service van operations across United States coastal regions where space constraints limit tool carrying capacity. Target marine service underpenetration in outboard motor repair networks lacking specialized puller distribution. Pursue CE marking harmonization for simplified multi-country aftermarket entry. For Investors and Strategic Acquirers: Roll-up economics work for heat-treatment specialists with proprietary hardening processes because aging workforce concentration creates succession-driven exit opportunities. Five-to-ten year viability favors certified manufacturers with documented calibration capabilities over commodity fabricators. Watch EPA chromium emission limit enforcement intensity as inflection indicator for dry-film lubricant coating adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Finish Technology Licensing | Physical vapor deposition alternatives capture premium positioning as hexavalent chromium electroplating faces ECHA restrictions. |
| Modular Jaw System Development | Interchangeable geometry sets reduce single-purpose inventory for independent repair shops in Germany and United States. |
| NIST-Traceable Calibration Infrastructure | Documented certification chains displace price-primary purchasing in United States defense contractor maintenance networks. |
| Integrated Service-Bay Equipment Bundling | Chicago-Milwaukee distributors capture captive channels by positioning extraction tools alongside lift and diagnostic systems. |
| Marine Service Distribution Expansion | Coastal United States repair networks show underpenetration for specialized outboard motor and inboard transmission puller geometries. |
Research Methodology
Direct dialogue with maintenance directors at fleet operations, aftermarket service heads at dealership networks, procurement leads at aerospace contractors, and plant engineers at heavy machinery service facilities grounded qualitative insights. Secondary validation drew from EPA enforcement records, OSHA guarding standard filings, ISO 9001 certification registries, and customs trade data on chrome-vanadium alloy imports. Bottom-up channel checks and top-down metallurgical supply analysis were triangulated to cross-validate volume and value estimates.
Bottom-up modeling segmented the market by product type, end-user certification regime, size category, and material specification across the analysis window. CAGRs were derived from utilization rate projections in dual-clutch transmission service bays and force-multiplication adoption curves in heavy machinery maintenance. Forecast inputs incorporated EPA chromium limit phase-in timelines and REACH substance restriction enforcement patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to alloy sourcing disruption and tier-1 distributor consolidation patterns. Aerospace calibration timeline extensions or hydraulic puller technology advances could revise mechanical puller demand trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Advanced Gear Shifter System Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Engine Rocker Arm Market
Powertrain
Diesel Engine Management System Market
Powertrain
Fuel Pumps Market
Powertrain
Automotive Timing Chain and Belt Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
New Energy Vehicle Scroll Compressor Market
Powertrain
Positive Crankcase Ventilation Valve Market
Powertrain
Global Automotive Drive Shaft Market
Powertrain
Timing Belt Kits Market
Powertrain
Gear Oil Market
Powertrain
Variable Displacement Compressor Market
Powertrain
Global Automotive Engine and Engine Mounts Market