
 Internal Combustion Engine Market | 2026-2036
Internal Combustion Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Internal Combustion Engine Market Intelligence
The bundling of engines with integrated after-treatment systems and digital control units is expanding the value proposition for industrial and marine clients. Cummins Inc. specializes in high-horsepower diesel and natural gas engines for heavy-duty applications. Caterpillar Incorporated leverages its extensive global service network to support its engines in mining and construction. Robert Bosch GmbH dominates the supply of critical fuel injection systems and engine management components to numerous OEMs.
An internal combustion engine is a heat engine that generates motive power through the exothermic reaction of a fuel with an oxidizer inside a combustion chamber. These engines operate on cycles like the Otto or Diesel cycle, converting chemical energy into mechanical work. Diesel engines continue to lead in industrial and marine applications due to their torque and fuel efficiency. The market for smaller gasoline engines, particularly those with advanced fuel injection systems, remains significant in the automotive sector for OEMs.
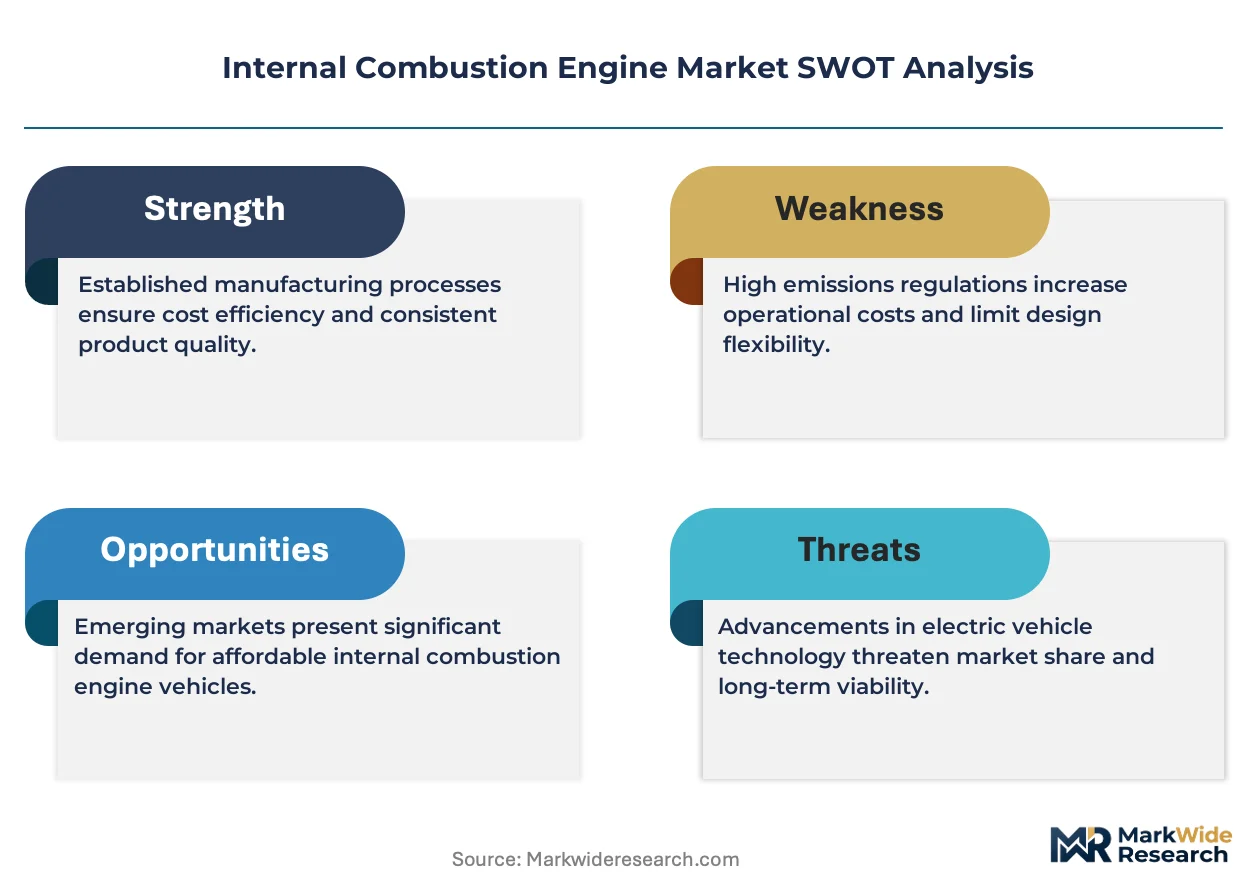
Emissions mandates, including the EPA's Tier 4 standards in the United States and the EU's Stage V regulations, dictate engine design and after-treatment technology. In parallel, China's dual carbon goals are pushing for higher efficiency and the adoption of alternative fuels like natural gas. Engine manufacturers must now balance investments in legacy engine efficiency improvements against the strategic pivot toward electrification.
Market Dynamics
The imperative to balance legacy engine efficiency with the strategic pivot to electrification defines the market's core dynamic. This dual-track investment is driven by tightening emissions regulations, such as the EPA's Tier 4 standards, which demand cleaner combustion from established technologies.
Growth Catalysts
- Infrastructure Expansion:Major infrastructure and agricultural development projects in India and Brazil are fueling demand for high-torque, heavy-duty diesel engines for construction and farm equipment.
- Emissions Regulations:The EU Green Deal and similar global mandates are accelerating the development and adoption of cleaner combustion technologies and advanced after-treatment systems for industrial applications.
- Power Generation Demand:The need for reliable backup and off-grid power is sustaining the market for diesel and natural gas generator sets, particularly in regions with unstable electrical grids.
Market Restraints
- Substitution from Electrification:The allocation of significant research and development capital toward battery-electric and fuel-cell powertrains directly limits investment in next-generation internal combustion engine innovation.
- High Compliance Costs:The escalating cost of sophisticated after-treatment components, such as selective catalytic reduction systems needed for EU Stage V compliance, increases the total price for end-users.
- Regulatory Fragmentation:Divergent timelines and standards between mature and emerging markets create design and supply chain complexities for original equipment manufacturers producing for a global customer base.
Strategic Opportunities
- Alternative Fuels:Engineering engines to operate on low-carbon or zero-carbon fuels, including hydrogen, ammonia, and advanced biofuels, offers a long-term viability pathway for combustion technology.
- Hybrid Powertrains:Integrating smaller, highly efficient engines into hybrid-electric systems for off-highway vehicles and marine vessels provides a transitional solution balancing performance with reduced emissions.
- Digital Service Integration:Bundling engines with telematics and predictive maintenance software creates opportunities for recurring revenue through data-driven service contracts focused on maximizing uptime and efficiency.
Industry Challenges
- Complex System Integration:Ensuring the seamless performance and durability of engines when combined with complex after-treatment systems and digital control units presents a significant engineering challenge for manufacturers.
- Specialized Talent Scarcity:A shortage of engineers with dual expertise in advanced combustion science and the software development required for modern engine management systems hinders product development cycles.
- Intense Capital Requirements:Retooling manufacturing facilities to produce engines compliant with multiple, evolving emissions standards like China's dual carbon goals requires substantial and continuous capital investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internal Combustion Engine Market |
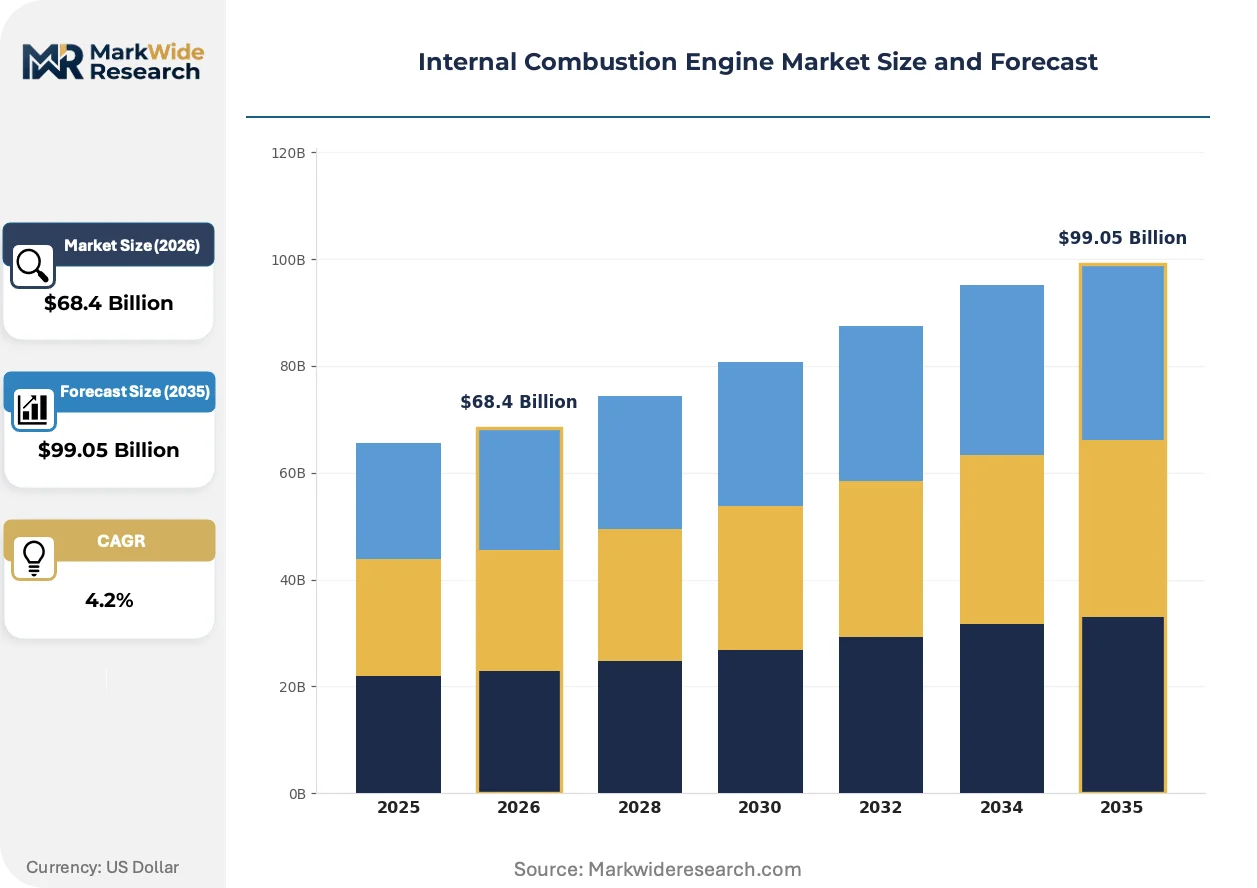
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $99.05 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Gasoline, Diesel, Natural Gas, Ethanol Application: Automotive, Marine, Industrial, Power Generation Fuel Supply System: Carbureted, Fuel Injected, Turbocharged, Supercharged End User: OEMs, Aftermarket Providers, Fleet Operators, Distributors |
| Companies Covered | Volkswagen Group, Toyota Motor Corporation, Robert Bosch GmbH, Cummins Inc., AB Volvo, Ford Motor Company, General Motors, Caterpillar Incorporated, Mitsubishi Heavy Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internal Combustion Engine Market Strategic Shifts & Innovations
The evolution of the internal combustion engine into a highly integrated, digitally managed power system is the central theme. This transformation is a direct response to global pressures for greater efficiency and environmental accountability, moving the engine far beyond its purely mechanical origins.
Advanced after-treatment technologies are fundamental to meeting modern emissions mandates. Systems combining Selective Catalytic Reduction (SCR) for NOx and Diesel Particulate Filters (DPF) for soot are now standard for heavy-duty applications. Off-highway and commercial vehicle OEMs are adopting these technologies rapidly. This integration of engine and exhaust controls is modularizing the powertrain, simplifying its installation for equipment manufacturers.
International Maritime Organization (IMO) regulations on sulfur and nitrogen oxide emissions are a primary force in the marine sector. These rules compel vessel operators to use low-sulfur fuels, install exhaust gas scrubbers, or switch to engines that run on alternatives like liquefied natural gas (LNG). The large-bore, two-stroke diesel engine segment is most affected, spurring a decisive shift toward dual-fuel designs.
A preference for total lifecycle cost management is altering buying behavior in industrial sectors. End-users in mining and power generation now prioritize long-term service agreements and uptime guarantees over initial unit price. This disrupts the traditional, transactional aftermarket parts channel, favoring OEMs with robust, data-enabled global service networks. This trend is most visible in North America and Europe, where operational efficiency is paramount.
Internal Combustion Engine Market Segmentation
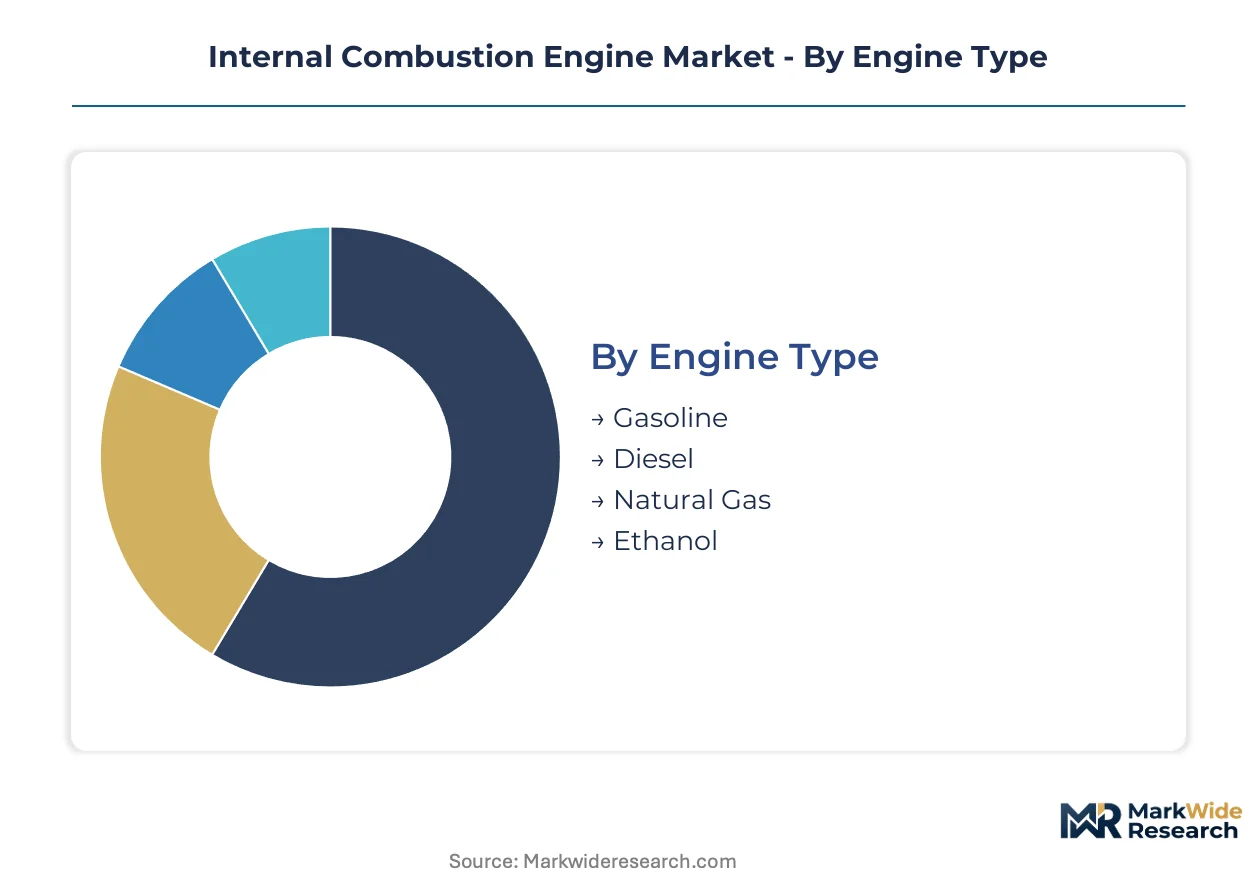
Understanding the internal combustion engine market requires a granular view of its diverse components and applications. Segmentation provides clarity on how different engine types and fuel systems cater to specific end-user needs across various industries. This detailed breakdown helps identify areas of concentrated demand and technological evolution.
Engine Type:
The internal combustion engine market balances standardized core engine block designs with highly customized fuel and ignition systems across various engine types.
- Gasoline:These engines ignite a compressed fuel-air mixture with a spark, typically operating on the Otto cycle. Demand remains significant in the automotive sector in North America and Europe, driven by evolving emissions standards.
- Diesel:Diesel engines use compression ignition, offering high torque and fuel efficiency for heavy-duty applications. Their demand concentrates in industrial and marine sectors in India and Brazil, supporting infrastructure expansion.
- Natural Gas:These engines operate on natural gas, offering lower carbon emissions. China's dual carbon goals promote their adoption in power generation.
- Ethanol:Engines designed for ethanol or flex-fuel blends use its higher octane rating. Brazil's automotive market utilizes these due to biofuel availability.
Most installed capacity flows through Diesel engines. Expansion is steepest in Natural Gas engines.
Application:
Engine application directly dictates performance requirements and regulatory compliance across diverse operational environments.
- Automotive:Internal combustion engines power passenger cars, light commercial vehicles, and trucks. Demand in Germany and Japan is driven by advanced fuel injection systems and stringent emissions mandates like EPA Tier 4.
- Industrial:This segment includes engines for construction equipment, agricultural machinery, and material handling. Heavy-duty diesel engines are critical for mining in Australia and infrastructure projects in India, valued for torque.
- Marine:Engines for propulsion and auxiliary power in commercial vessels. IMO regulations compel dual-fuel designs or exhaust gas scrubbers.
- Power Generation:Engines provide prime, standby, or distributed power in generator sets. Reliable backup and off-grid power sustains demand in regions with unstable grids.
The automotive sector commands the largest volume of engine deployments, while industrial applications drive demand for high-torque solutions.
Fuel Supply System:
Fuel supply system sophistication determines engine efficiency, power output, and emissions compliance across the market.
- Fuel Injected:These systems precisely meter and deliver fuel, enhancing combustion efficiency and reducing emissions. Modern gasoline and diesel engines in the United States and Europe widely incorporate electronic fuel injection to meet stringent standards.
- Turbocharged:Turbochargers use exhaust gases to force more air into the engine, increasing power and efficiency without significant size increase. Heavy-duty diesel engines for construction equipment in Brazil and China frequently feature turbocharging.
- Carbureted:Carburetors mechanically mix air and fuel, a simpler method. This older technology persists in some small engines.
- Supercharged:Superchargers mechanically force air into the engine, providing instant power. Niche high-performance automotive applications in Germany sometimes employ supercharging.
Advanced fuel injection and forced induction technologies are now standard for new engine designs, displacing older carbureted systems.
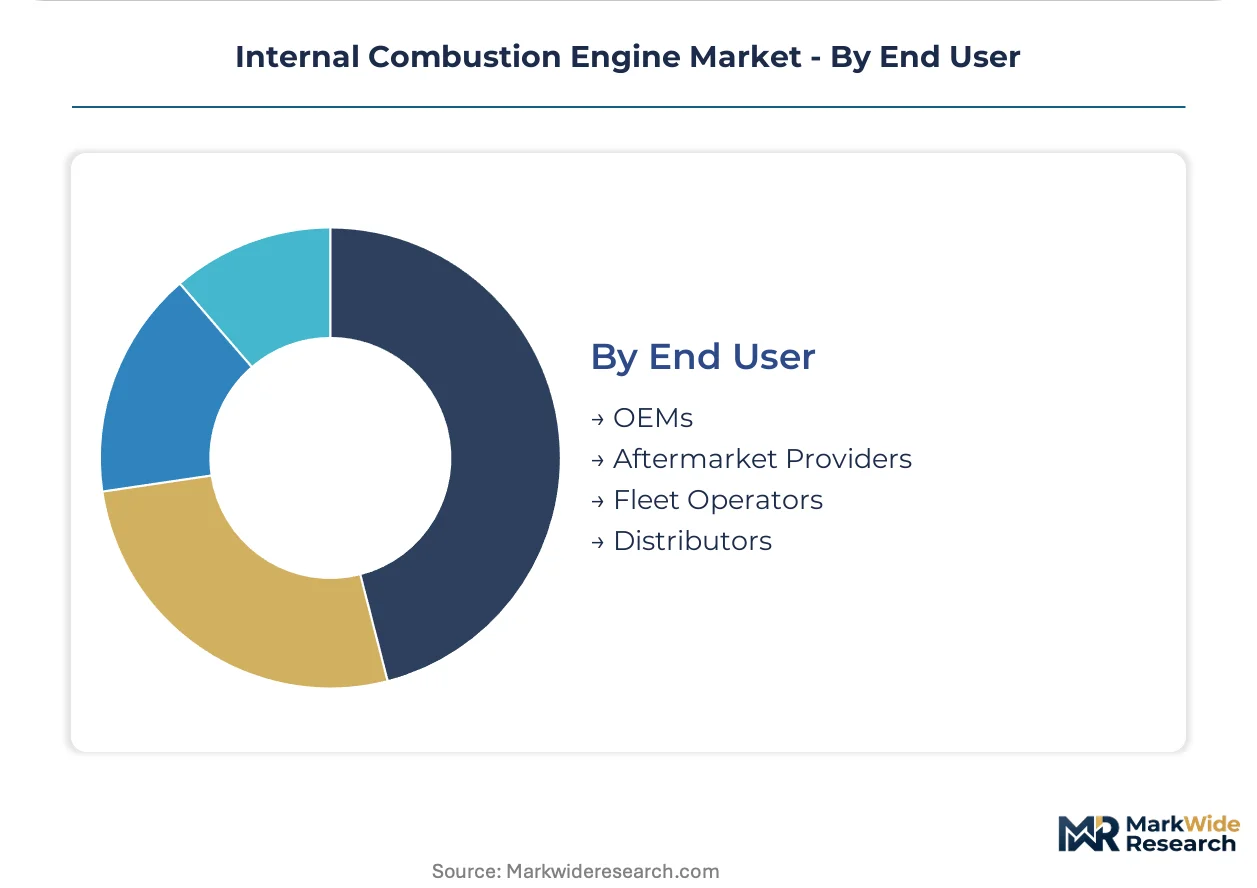
End User:
End-user procurement patterns vary significantly, from direct integration by manufacturers to service-focused acquisition by operators.
- OEMs:Original Equipment Manufacturers integrate internal combustion engines directly into final products like vehicles. Automotive OEMs in South Korea and India heavily influence engine design specifications.
- Fleet Operators:These entities manage many vehicles or equipment, prioritizing engine durability, fuel economy, and maintenance costs. Logistics companies in the UK and mining firms in Canada focus on total cost of ownership.
- Aftermarket Providers:Companies supply replacement parts, components, and services for engines in operation. Independent repair shops and parts distributors in Mexico serve a broad base of vehicle owners.
- Distributors:These businesses act as intermediaries, selling engines and components to various customers. Regional distributors in Southeast Asia facilitate access for agricultural and construction needs.
Original equipment manufacturers drive initial engine volumes, while fleet operators prioritize long-term service and operational efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The internal combustion engine market originated from foundational engineering advancements in Europe, notably Germany, before expanding globally to power diverse industrial and transportation applications. Modern regional dynamics now reflect a complex interplay of infrastructure development, stringent emissions mandates, and evolving energy policies. Key geographical markets demonstrate distinct growth trajectories and technological adoption patterns.
Germany
Demand for internal combustion engines in Germany stems from its robust automotive and industrial machinery sectors. The EU Green Deal significantly influences engine design, pushing for cleaner combustion and hybrid solutions. Major automotive clusters in Bavaria and Baden-Württemberg focus on developing highly efficient gasoline and diesel engines for global markets.
United States
The United States market prioritizes heavy-duty diesel engines for construction and agricultural equipment, alongside significant automotive applications. EPA's Tier 4 standards drive advanced after-treatment system integration across all engine types. Manufacturing hubs in the Midwest, like Detroit, continue to innovate in both gasoline and diesel engine technologies.
China
China exhibits strong demand for natural gas engines in power generation and heavy-duty industrial applications, driven by its dual carbon goals. The Ministry of Ecology and Environment (MEE) mandates increasingly stringent emissions controls for new engine deployments. Industrial zones in the Yangtze River Delta actively pursue higher efficiency and alternative fuel engine production.
India
India's market expansion for internal combustion engines is directly linked to massive infrastructure and agricultural development projects. The country's national emission standards, Bharat Stage (BS) norms, compel manufacturers to integrate cleaner technologies. Industrial clusters in Maharashtra and Gujarat are key centers for heavy-duty diesel engine manufacturing and distribution.
Brazil
Brazil's internal combustion engine market is heavily influenced by its agricultural sector and the widespread adoption of ethanol-fueled vehicles. The National Environmental Council (CONAMA) sets emissions standards for both automotive and off-highway engines. Production facilities in São Paulo and Minas Gerais specialize in flex-fuel and high-torque diesel engines.
Internal Combustion Engine Market Key Industry Players
The competitive structure tilts toward integrated solution providers and specialized component manufacturers within the internal combustion engine market. This market encompasses a range of players from large, diversified conglomerates to niche technology firms. Strategic archetypes include full-line engine manufacturers, critical component suppliers, and service-oriented aftermarket specialists. Dominant competitive moves involve strategic partnerships for new technology development and significant capital expenditure for regulatory compliance.
Specialists in critical components and heavy-duty solutions include Robert Bosch GmbH, which anchors the supply of advanced fuel injection systems and engine management units. Cummins Inc. represents a leading archetype for high-horsepower diesel and natural gas engines, particularly for heavy-duty industrial and power generation applications. Caterpillar Incorporated exemplifies a full-line engine manufacturer, leveraging its extensive global service network to support engines in mining and construction sectors.
| Leading Market Players |
|---|
| Volkswagen Group |
| Toyota Motor Corporation |
| Robert Bosch GmbH |
| Cummins Inc. |
| AB Volvo |
| Ford Motor Company |
| General Motors |
| Caterpillar Incorporated |
| Mitsubishi Heavy Industries, Ltd. |
| Others |
Cost & Logistics Intelligence
The imperative for industrial clients to minimize total lifecycle cost is reshaping how engine manufacturers price their integrated power solutions, driving a shift towards service-level agreements.
Pricing Analysis
Contract-based long-term service agreements now define engine procurement for heavy-duty industrial applications. Price differentiation stems from the level of after-sales service, uptime guarantees, and compliance with stringent regulations like EU Stage V. Pricing pressure on initial unit costs arises from end-users prioritizing total cost of ownership. Automotive OEMs and fleet operators in Europe exhibit higher price sensitivity for standard engines, while mining firms in Australia prioritize reliability and comprehensive service packages.
Supply Chain Analysis
Regional distribution centers facilitate the complex flow of internal combustion engines and their components across diverse markets. Supply concentration for advanced fuel injection systems and engine management units centers in Germany and Japan. The supply chain relies on critical after-treatment components, such as Selective Catalytic Reduction (SCR) systems, often sourced from specialized manufacturers. Regulatory fragmentation across geographies poses a structural risk, creating complexities for global OEMs. Distribution runs through direct OEM integration for new vehicles and a network of regional distributors for industrial and aftermarket needs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The internal combustion engine market presents opportunities for margin expansion through the strategic integration of digital service solutions, shifting revenue towards higher-value, recurring streams.
For Market Incumbents:Lock in long-term service contracts with industrial and marine clients, leveraging existing global service networks to mitigate the threat from electrification. Invest significantly in research and development for alternative fuel engine platforms, such as hydrogen or ammonia, addressing future emissions mandates. Deepen vertical integration for critical after-treatment components to control costs and ensure compliance with EPA Tier 4 standards.
For New Entrants and Emerging Players:Launch via strategic partnerships with equipment manufacturers in emerging markets, targeting segments with less stringent emissions mandates. Focus on modular, highly efficient engine designs for off-grid power generation in regions with unstable electrical grids, like parts of India. Penetrate the Brazilian agricultural sector with flex-fuel engine solutions, capitalizing on local biofuel availability and infrastructure expansion.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialized component manufacturers and software providers enabling advanced engine management systems, offering long-term viability. Focus on companies innovating in hybridization technologies or digital telematics for predictive maintenance over the next decade. The acquisition target archetype should be niche technology firms developing advanced fuel injection or after-treatment solutions. Increased capital expenditure by OEMs in hybrid powertrain development signals a key inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Hydrogen-Combustion Engines | Positions manufacturers for long-term viability under China's dual carbon goals. |
| Expand Digital Service Offerings | Creates recurring revenue streams and enhances uptime for fleet operators in North America. |
| Form Strategic After-treatment Partnerships | Ensures compliance with EU Stage V regulations and reduces high compliance costs. |
| Invest in Hybrid Powertrain Integration | Provides a transitional solution for off-highway vehicles, balancing emissions and performance. |
| Target Emerging Market Agricultural Sector | Captures demand for heavy-duty diesel engines driven by infrastructure growth in India. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary data validation. Primary research involved discussions with engine design engineers, OEM procurement managers, fleet operations directors, and after-treatment system specialists across multiple geographies. Secondary data sources included EPA regulatory documents, EU Green Deal policy papers, International Maritime Organization (IMO) emissions reports, and corporate financial filings, enabling bottom-up market sizing and top-down validation.
Historical performance across comparable periods informed the baseline for projections, extending through the forecast horizon. The analytical framework modeled segmentation dimensions including engine type, application, fuel supply system, end user, and regional regulatory compliance. Compound annual growth rates were derived from a growth model considering market drivers and restraints. Forecast inputs included infrastructure spending in India and EPA Tier 4 compliance rates in the United States.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid shifts in global emissions policies or unforeseen technological breakthroughs. Forecasts reflect assumptions regarding regulatory stability and the pace of energy transition. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Engine Market
Powertrain
Automotive Turbocharger Hose Market
Powertrain
Brazil Automotive Market
Powertrain
Canada Automotive Engine Oils Market
Powertrain
Automotive Fluid Reservoir Market
Powertrain
Automotive Power Distribution Block Market
Powertrain
Europe Hill-Start Assist System Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
Tachometer Market
Powertrain
Automotive Drivetrain Market
Powertrain
Global Automotive Drive Shaft Market
Powertrain
Transmission Shift Actuator Market
Powertrain
Turbine Housing for Automobile Market
Powertrain
Iridium Spark Plug Market