
 LNG Engine Market | 2026-2036
LNG Engine Market Size, Share, and Industry Trends Forecast 2026-2036
LNG Engine Market Intelligence
Marine engine distribution channels are being redrawn as shipyard-direct procurement is reshaping traditional distributor networks. Wärtsilä leverages its integrated propulsion systems to sustain long-term service contracts with major yards. MAN Energy Solutions anchors the two-stroke segment through its ME-GI platform. Caterpillar Inc. competes in the mid-power range with modular genset configurations for offshore support vessels.
An LNG engine converts liquefied natural gas into mechanical power through controlled combustion in piston or turbine architectures, operating at compression ratios between 10:1 and 14:1 for optimal thermal efficiency. These engines serve commercial shipping, grid-scale power plants, and heavy-duty transport where emissions compliance mandates fuel switching from diesel or heavy fuel oil. Dual-fuel configurations now lead marine installations by allowing operators to alternate between LNG and diesel without auxiliary systems. Four-stroke designs dominate power generation applications due to faster ramp rates and smaller footprint requirements. Spark-ignited variants occupy niche positions in on-road trucking where OEMs prioritize lower capital outlay over fuel flexibility.
The International Maritime Organization enforces sulfur emission limits that directly expand LNG engine retrofit demand across existing fleets. EPA and EU MRV regulations tighten methane leakage standards, forcing manufacturers to redesign combustion chambers and crankcase ventilation. Stakeholders must monitor how IMO's carbon intensity indicator reshapes vessel financing and engine specification decisions.
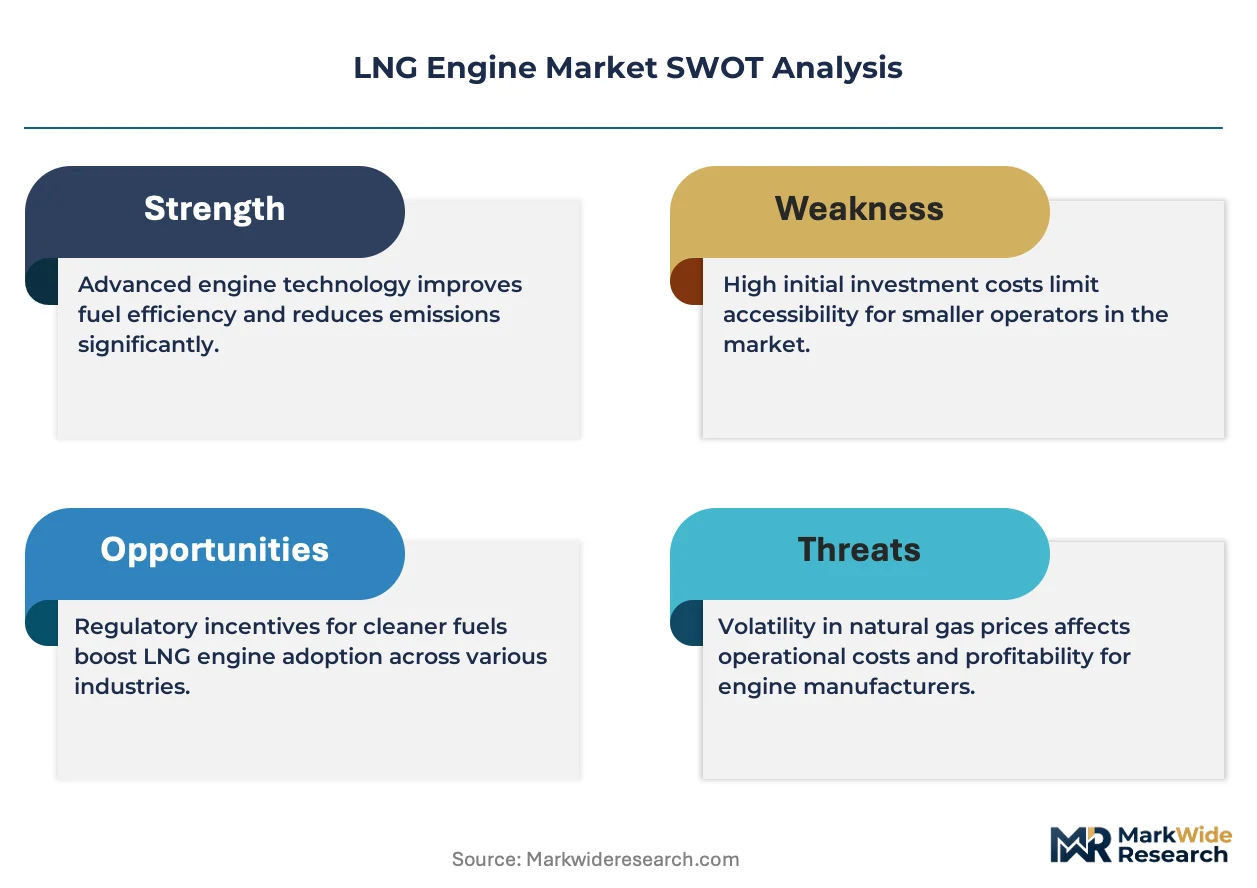
Market Dynamics
The International Maritime Organization's sulfur emission caps are forcing a wholesale fuel transition across commercial shipping fleets, with dual-fuel LNG engine installations accelerating as operators face compliance deadlines and carbon intensity disclosure requirements.
Growth Catalysts
- IMO 2020 Sulfur Regulations:The International Maritime Organization's sulfur cap mandates have triggered fleet-wide engine retrofits and newbuild specifications favoring LNG combustion systems over residual fuel oil.
- Dual-Fuel Combustion Advances:High-pressure direct injection technology now enables diesel-like efficiency in gas-only mode while maintaining fuel flexibility for operators navigating volatile bunker markets.
- South Korean Shipyard Concentration:Hyundai Heavy Industries and Samsung Heavy Industries anchor global LNG carrier and container vessel construction, concentrating engine demand in Ulsan and Geoje production clusters.
Market Restraints
- Bunkering Infrastructure Gaps:LNG fuel availability remains concentrated in Rotterdam, Singapore, and Houston, leaving trans-Pacific and African route operators dependent on dual-fuel fallback systems.
- High-Pressure Fuel System Costs:Type C cryogenic tanks and gas valve units add capital intensity that extends payback periods beyond traditional diesel engine economics.
- Methane Slip Regulatory Thresholds:EPA and EU MRV monitoring protocols are tightening unburned methane emission limits, forcing combustion chamber redesigns that compromise thermal efficiency gains.
Strategic Opportunities
- India Port Electrification:The country's Ministry of Ports, Shipping and Waterways is mandating shore power and cleaner auxiliary engines at Jawaharlal Nehru Port and Mundra, creating retrofit demand for harbor craft and tug fleets.
- Carbon Intensity Indicator Arbitrage:IMO's CII rating system is reshaping vessel financing, with LNG-fueled newbuilds commanding preferential lease terms from European maritime lenders.
- Power-to-X Convergence:Integration of LNG engines with ammonia-ready fuel systems and onboard carbon capture is positioning early adopters for 2030 fuel-blending mandates.
Industry Challenges
- Cryogenic System Technician Scarcity:Specialized training for high-pressure gas fuel handling and cryogenic pump maintenance outpaces maritime academy output in Europe and Southeast Asia.
- Type Approval Timeline Compression:Bureau Veritas and DNV classification protocols for novel combustion concepts now require 18-24 month validation cycles that delay newbuild deliveries.
- Aftermarket Service Network Reconfiguration:Shipyard-direct procurement is fragmenting traditional distributor relationships, forcing engine manufacturers to embed technical staff at builder facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LNG Engine Market |
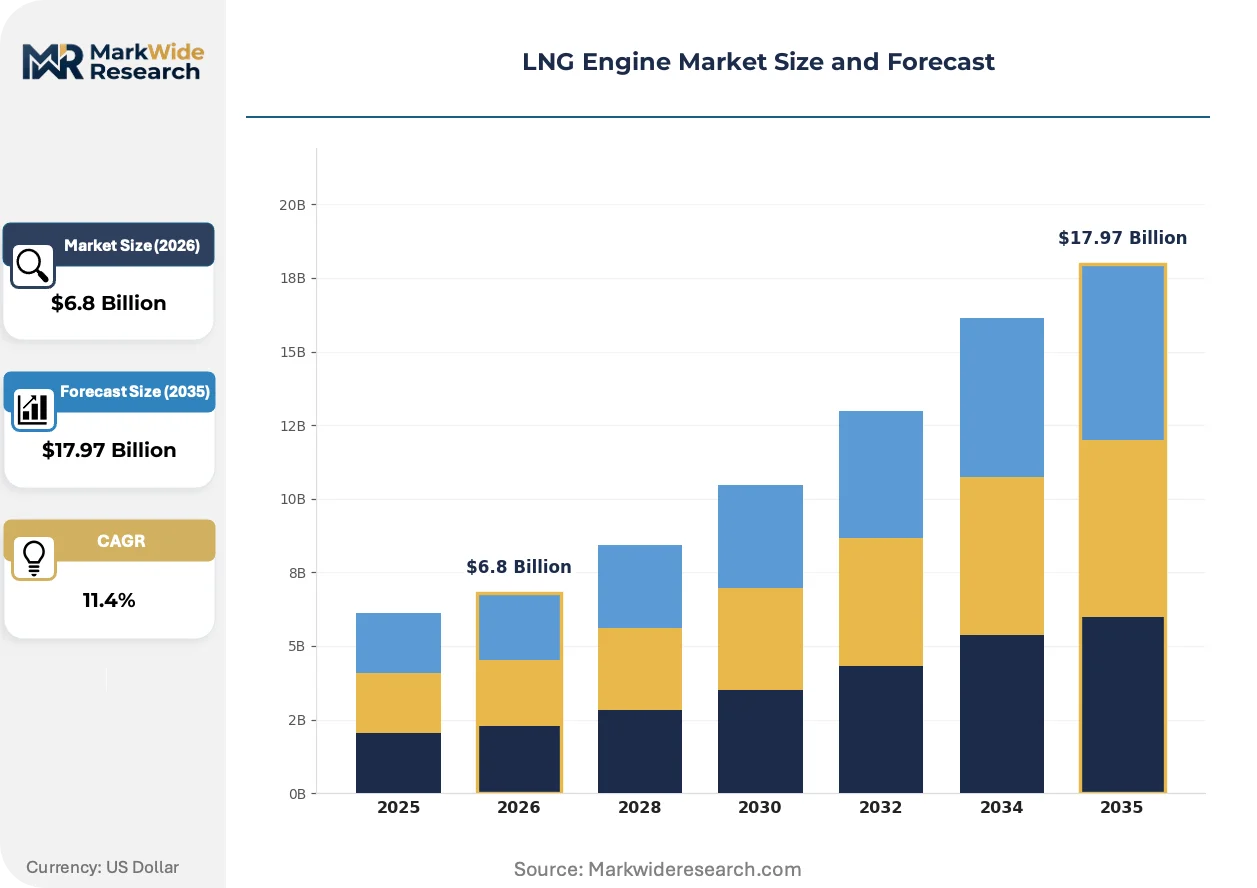
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Two-Stroke, Four-Stroke, Dual-Fuel, Spark-Ignited Application: Marine, Power Generation, Transportation, Industrial Power Output: Less than 1000 HP, 1000-2000 HP, 2000-3000 HP, More than 3000 HP End User: Shipping Companies, Utility Providers, OEMs, Oil & Gas |
| Companies Covered | MAN Energy Solutions, Rolls-Royce Holdings, Wärtsilä, Weichai Power, Yanmar Holdings, Caterpillar Inc., GE Aerospace, Kubota Corporation, Cummins Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LNG Engine Market Strategic Shifts & Innovations
Propulsion system architectures are converging around fuel-flexible platforms that accommodate evolving emission regulations without full engine replacement, compressing technology refresh cycles and reshaping supplier relationships.
High-pressure dual-fuel injection is collapsing the performance gap between LNG and diesel combustion in two-stroke marine engines. Container lines operating Asia-Europe routes are specifying ME-GI derivative systems for 15,000+ TEU vessels. The technology is collapsing capital allocation timelines by extending engine platform lifespans across multiple regulatory phases.
EU MRV and IMO DCS data disclosure mandates are hardening emission verification requirements for vessel operators. The European Commission's Fit for 55 package is accelerating fuelEU maritime implementation, forcing charterers to contractually specify engine efficiency guarantees. Deep-sea tanker fleets operating under Greek and Norwegian flags are responding with continuous combustion monitoring retrofits.
Shipowner procurement committees are unbundling engine supply from integrated propulsion packages. Independent technical managers at German and Singaporean container operators now specify engines separately from shaftline and automation systems. This pattern is most visible in the feeder vessel segment, where Greek family offices and Nordic leasing houses negotiate direct manufacturer contracts bypassing yard markup structures.
LNG Engine Market Segmentation
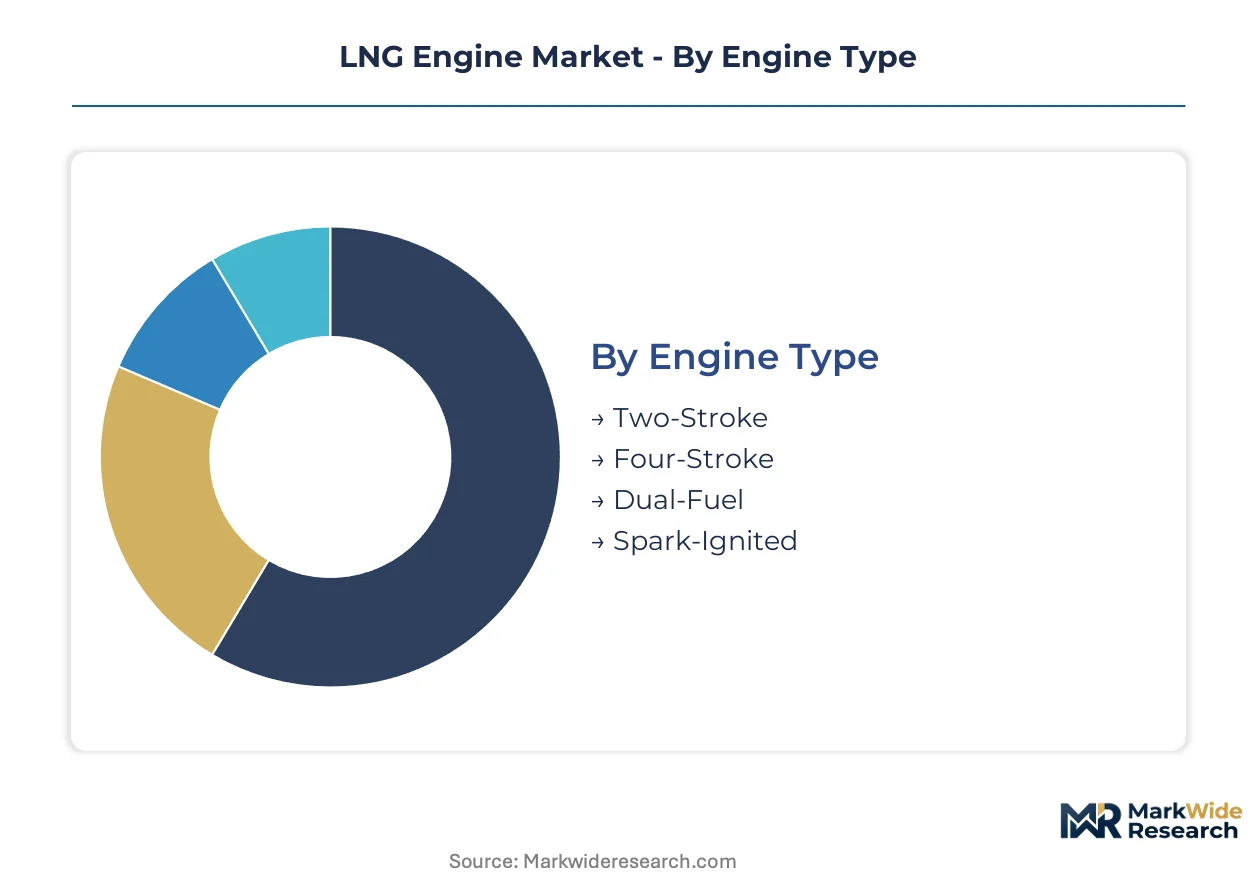
LNG engine procurement patterns diverge sharply across operational contexts, with marine operators prioritizing fuel flexibility while power utilities emphasize thermal efficiency and ramp rates. Understanding these segment boundaries clarifies why manufacturers maintain distinct product architectures despite underlying combustion commonality.
Engine Type:
Use-case spectrum spans massive two-stroke marine propulsion through compact spark-ignited trucking powertrains.
- Two-Stroke:These engines achieve thermal efficiencies above 50% through uniflow scavenging and high-pressure direct injection. Demand concentrates in South Korea's Ulsan and Geoje shipbuilding clusters, where Hyundai Heavy Industries and Samsung Heavy Industries specify ME-GI derivatives for 15,000+ TEU container vessels and LNG carriers.
- Dual-Fuel:High-pressure gas injection enables diesel-like efficiency in gas-only mode while preserving liquid fuel fallback for routes with sparse bunkering infrastructure. Operators on Asia-Europe container loops favor this architecture to navigate Rotterdam-Singapore-Houston fuel availability gaps.
- Four-Stroke:Faster start-up sequences and smaller footprints suit grid-scale power plants and offshore support vessels requiring rapid load following.
- Spark-Ignited:Simpler fuel system architecture with lower capital outlay dominates North American on-road trucking where OEMs prioritize purchase price over fuel flexibility.
The dominant share belongs to Dual-Fuel, while Spark-Ignited is closing the gap fastest in regional trucking applications.
Application:
Cost tier differentiation separates capital-intensive marine installations from modular industrial deployments.
- Marine:Deep-sea vessels face IMO sulfur caps and carbon intensity disclosure mandates that make LNG the compliance pathway of choice. Greek and Norwegian-flagged tanker fleets are retrofitting with continuous combustion monitoring to satisfy EU MRV protocols.
- Power Generation:Grid operators in India mandate cleaner auxiliary engines at Jawaharlal Nehru Port and Mundra, creating retrofit demand for harbor craft and tug fleets with four-stroke configurations.
- Transportation:Heavy-duty trucking applications favor spark-ignited architectures where fuel station density determines technology choice.
- Industrial:Manufacturing facilities with captive natural gas supply integrate LNG engines for combined heat and power without bunkering dependency.
Marine commands the largest installed base, though Power Generation is expanding most quickly in Asian port electrification programs.
Power Output:
Volume concentration sits in mid-range brackets serving feeder vessels and distributed generation.
- Less than 1000 HP:Compact gensets for harbor tugs and auxiliary power units where space constraints dominate specification decisions.
- 1000-2000 HP:Feeder container vessels and offshore support ships specify this bracket most heavily, with German and Singaporean technical managers unbundling engine supply from integrated propulsion packages.
- 2000-3000 HP:Mid-size LNG carriers and coastal power plants balance thermal efficiency against capital intensity.
- More than 3000 HP:Ultra-large container vessels and base-load power stations require this tier, though Type C cryogenic tanks and gas valve units extend payback periods beyond conventional diesel economics.
The 1000-2000 HP bracket holds the greatest shipment volume, while above-3000 HP systems are gaining share fastest in ultra-large vessel newbuilds.
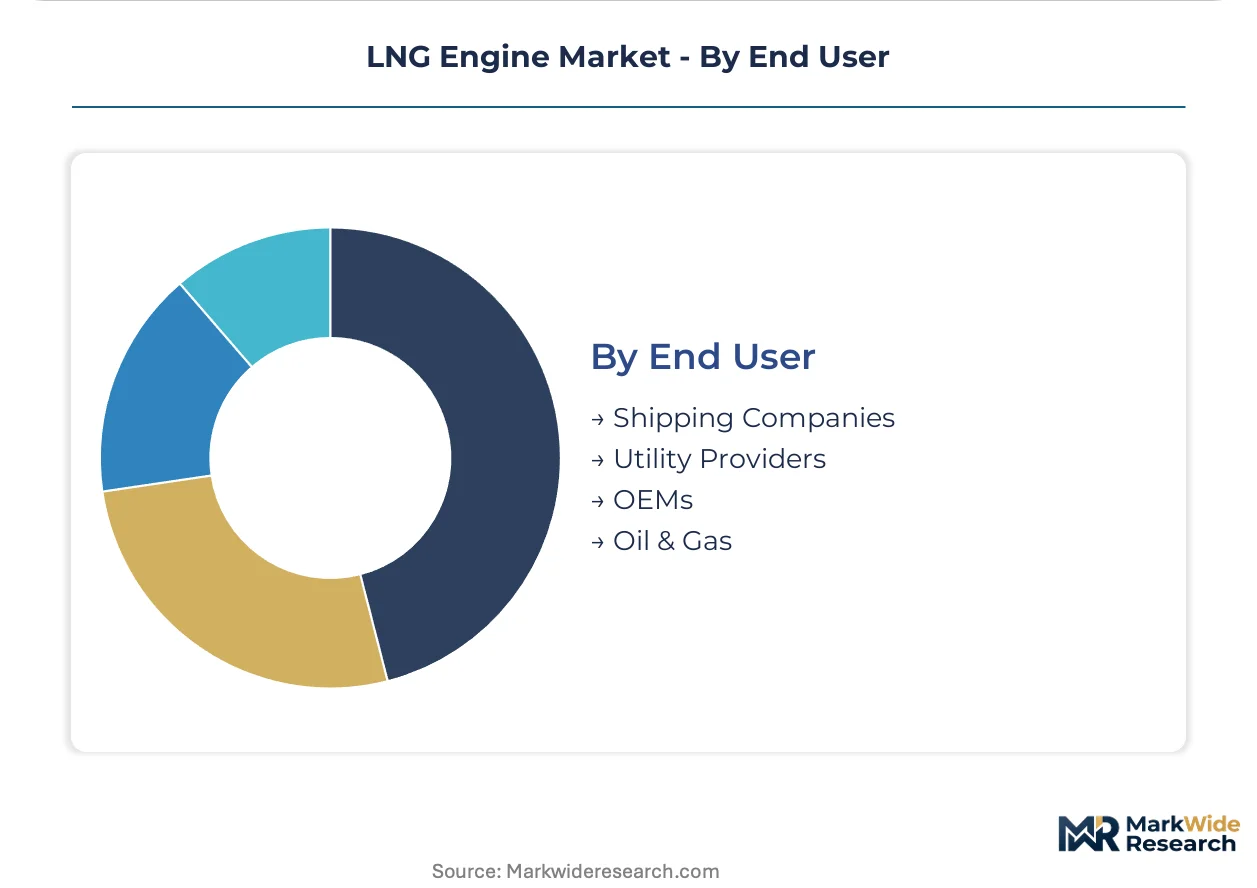
End User:
Customer type determines procurement channel structure and service contract terms.
- Shipping Companies:Container lines and tanker operators now specify engines separately from shaftline systems, with Greek family offices and Nordic leasing houses negotiating direct manufacturer contracts that bypass yard markup structures.
- Utility Providers:Grid operators prioritize continuous combustion monitoring retrofits to satisfy emerging fuel efficiency guarantee requirements in charter agreements.
- OEMs:On-road truck manufacturers integrate spark-ignited engines where lower capital outlay outweighs fuel flexibility considerations.
- Oil & Gas:Upstream operators specify dual-fuel systems for offshore platforms where fuel logistics complexity demands operational flexibility.
Shipping Companies represent the largest customer category, while Utility Providers are climbing the fastest as port electrification mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-backed decarbonization mandates and port infrastructure investments are steering LNG engine deployment patterns across major maritime economies. National regulators are tightening emission thresholds while subsidizing vessel retrofits and newbuild specifications.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries anchor global LNG carrier construction at Ulsan and Geoje shipyards. The Ministry of Oceans and Fisheries enforces domestic emission standards that exceed IMO baselines. Daewoo Shipbuilding & Marine Engineering at Okpo drives dual-fuel engine integration for ultra-large container vessels.
China
State-owned COSCO Shipping and China Merchants Energy bulk-order LNG engines for Belt and Road fleet modernization. MIIT mandates domestic emission compliance timelines that accelerate retrofit schedules. Shanghai Waigaoqiao Shipbuilding and Jiangnan Shipyard concentrate newbuild activity along the Yangtze River Delta.
United States
Jones Act carriers and cruise operators specify LNG engines to satisfy EPA Tier 4 marine standards. The Inflation Reduction Act allocates credits for vessel emission reductions and shore power infrastructure. Port of Houston and Port of Long Beach anchor bunkering investments along Gulf and Pacific corridors.
Germany
Container feeder operators and inland waterway fleets retrofit with LNG engines to meet EU MRV disclosure requirements and Fit for 55 fuel mandates. KBA enforces type approval protocols that compress manufacturer certification timelines. Hamburg and Bremen harbor clusters concentrate engine service and bunkering infrastructure.
Japan
Domestic shipping lines and power utilities deploy LNG engines for island-hopping routes and distributed generation. METI subsidizes vessel efficiency upgrades through maritime decarbonization programs. Nagoya and Kobe port authorities coordinate LNG bunkering pilot projects for regional trade lanes.
LNG Engine Market Key Industry Players
On the supply side, the industry is consolidating around integrated propulsion system providers with embedded service networks. Tier-one manufacturers anchor high-pressure dual-fuel architectures for deep-sea shipping, while mid-scale specialists occupy auxiliary power and industrial generation niches. Strategic archetypes include full-system integrators, engine-only suppliers, and aftermarket service platforms. Competitive moves center on shipyard-direct procurement relationships and combustion monitoring technology licensing.
Within the full-system integrator tier, Wärtsilä and MAN Energy Solutions exemplify the convergence of engine supply with automation and shaftline integration. Caterpillar Inc. occupies a position among mid-power modular specialists serving offshore support and harbor craft segments. These anchors reflect how procurement unbundling is fragmenting traditional distributor channels while rewarding manufacturers with embedded technical staff at builder facilities.
| Leading Market Players |
|---|
| MAN Energy Solutions |
| Rolls-Royce Holdings |
| Wärtsilä |
| Weichai Power |
| Yanmar Holdings |
| Caterpillar Inc. |
| GE Aerospace |
| Kubota Corporation |
| Cummins Inc. |
| Others |
Cost & Logistics Intelligence
Single-source dependency on South Korean cryogenic component suppliers determines both pricing tier spreads and supply chain shape, as Type C tank and gas valve unit bottlenecks force buyers into premium procurement channels or extended lead-time contracts.
Pricing Analysis
Certification level (IMO Tier III/EPA Tier 4/EU Stage V) creates the primary spread across engine quotations, with Bureau Veritas and DNV type-approved systems commanding substantial premiums over provisional certifications. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and combustion monitoring technology inclusion. Pricing pressure stems from shipyard-direct procurement eliminating traditional distributor markups, compressing margins for mid-power modular suppliers. Container lines and Greek family offices exhibit highest price sensitivity, while utility providers at Indian ports accept premium positioning for compliance certainty.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for cryogenic pump assemblies and high-pressure injection components. Manufacturing concentrates in South Korea, Germany, and Japan, with Hyundai Heavy Industries and MAN Energy Solutions facilities anchoring propulsion system output. The network draws from nickel-based superalloys, precision-machined cylinder heads, and specialized electronic control modules. Single-source vulnerability persists in gas valve unit production where two European suppliers control critical intellectual property. Distribution runs through shipyard-embedded technical staff rather than independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement unbundling is fragmenting the competitive landscape, creating specialized niches for combustion monitoring technology providers and cryogenic service platforms as shipowners separate engine specification from integrated propulsion packages.
For Market Incumbents: Build captive service moats by embedding technical personnel at Hyundai Heavy Industries and Samsung Heavy Industries facilities, securing long-term maintenance contracts that outlast initial equipment sales. Acquire combustion monitoring technology specialists to defend against unbundling trends that threaten integrated propulsion margins. Capacity addition in South Korea's Geoje cluster anchors proximity advantages for ultra-large vessel programs.
For New Entrants and Emerging Players: Pursue harbor craft and tug fleet retrofit opportunities at Jawaharlal Nehru Port and Mundra where Indian port electrification mandates create immediate demand for four-stroke auxiliary engines. Target the 1000-2000 HP feeder vessel segment where German and Singaporean technical managers already specify engines separately from shaftline systems. Partner with maritime academies to address cryogenic technician scarcity through certified training programs.
For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors aftermarket service platforms and combustion monitoring specialists over pure manufacturing plays. Long-term viability hinges on ammonia-ready fuel system integration capabilities and onboard carbon capture positioning for 2030 fuel-blending mandates. Watch for IMO carbon intensity indicator enforcement tightening as the signal for accelerated LNG newbuild financing preference.
| Strategic Initiative | Industry Significance |
|---|---|
| Shipyard-Direct Procurement Expansion | Bypasses traditional distributor markups at Hyundai Heavy Industries and Samsung Heavy Industries facilities. |
| Combustion Monitoring Technology Licensing | Satisfies EU MRV and IMO DCS data disclosure mandates for Greek and Norwegian-flagged tanker fleets. |
| Cryogenic Technician Training Partnerships | Addresses scarcity of high-pressure gas fuel handling specialists in Europe and Southeast Asia. |
| Ammonia-Ready Fuel System Integration | Positions early adopters for 2030 fuel-blending mandates under IMO decarbonization pathways. |
| Embedded Service Network Buildout | Secures long-term maintenance contracts through technical staff placement at builder facilities. |
Research Approach
Two parallel data streams informed the analysis: primary engagement with shipyard procurement officers, marine technical managers at container operators, classification society surveyors, and cryogenic system specialists; alongside secondary validation through IMO regulatory filings, DNV and Bureau Veritas type approval databases, and customs trade records for engine component flows. Bottom-up triangulation across manufacturer shipment disclosures and top-down reconciliation against vessel orderbook data anchored volume estimates.
Forecast inputs span engine type segmentation, power output brackets, application contexts, and end-user procurement channel structures across the projection horizon. CAGRs derive from regression analysis against bunker fuel price differentials, regulatory compliance deadline clustering, and shipyard capacity utilization at South Korean production clusters. Specific inputs include IMO carbon intensity indicator enforcement trajectories and EPA methane slip threshold tightening schedules.
Sensitivities concentrate around LNG bunkering infrastructure rollout pace, cryogenic component supply bottlenecks, and dual-fuel technology cost compression curves. Forecasts reflect assumptions regarding regulatory enforcement consistency and shipowner capital allocation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
EGR and Emissions Control Actuator Systems Market
Powertrain
Global Automotive GD Injector Market
Powertrain
Truck Auxiliary Power Units Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
Global Automotive Torque Vectoring Market
Powertrain
South Korea Electro Hydraulic Power Steering Market
Powertrain
Racing Clutches Market
Powertrain
Europe Turbocharger Market
Powertrain
Transmission Oil Filters Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Drive Shaft Market
Powertrain
Gear Reduction Starter Market
Powertrain
Car Active Purge Pump Market
Powertrain
Tuning Box Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
Automotive Camshaft Market