
 Automotive Transmission System Market | 2026-2036
Automotive Transmission System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Transmission System Market Analytics
Euro 7 emission standards is rebalancing engineering budgets across the supplier base. ZF Friedrichshafen AG leverages its integrated mechatronics portfolio to absorb compliance costs. Aisin Seiki anchors its position through captive production of torque converters and control modules. BorgWarner competes by specializing in electrified driveline architectures that bridge combustion and battery-electric platforms.
An automotive transmission system is a mechanical assembly that transfers power from an engine to the drive axle through specified gear ratios, torque multiplication, and rotational speed modulation, typically incorporating planetary gearsets, clutch packs, hydraulic circuits, or electric motor-generators with power densities exceeding 100 kW per liter in advanced units. Its primary purpose is to optimize vehicle performance, fuel efficiency, and drivability across varying load and speed conditions. Automatic transmissions retain the largest installed base and margin pool, while dual-clutch systems lead growth in performance passenger car segments due to shift-speed advantages. Hybrid transmission technology commands premium positioning as OEMs integrate electromechanical torque-fill functions to satisfy powertrain electrification mandates.
EPA tailpipe regulations, NHTSA fuel economy standards, and China's MIIT dual carbon goals collectively tighten allowable emissions bands and elevate transmission efficiency requirements across major production jurisdictions. Compliance timelines force simultaneous investment in legacy hardware refinement and electric-vehicle-compatible multi-speed architectures. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded development expenditures on transmission formats that face premature phase-out in select markets.
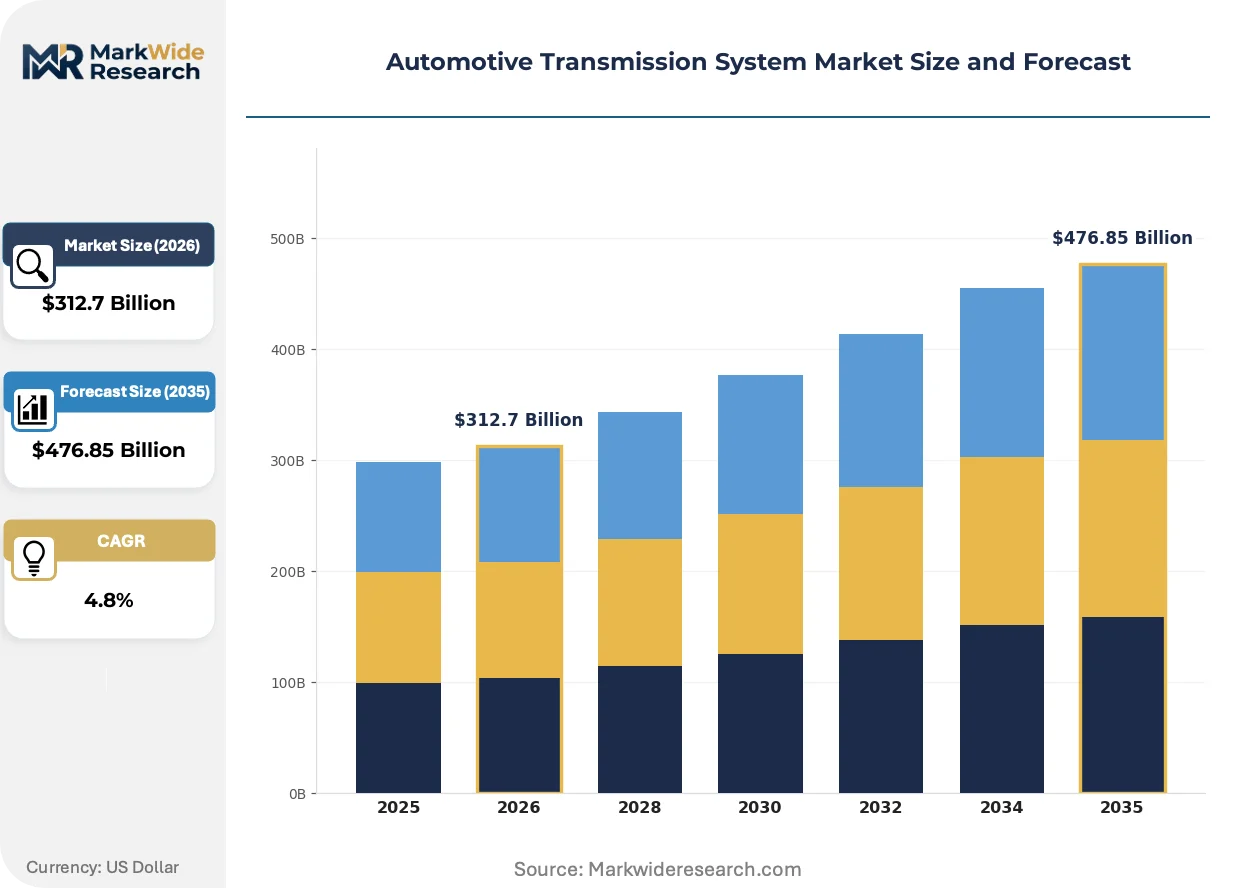
Market Dynamics
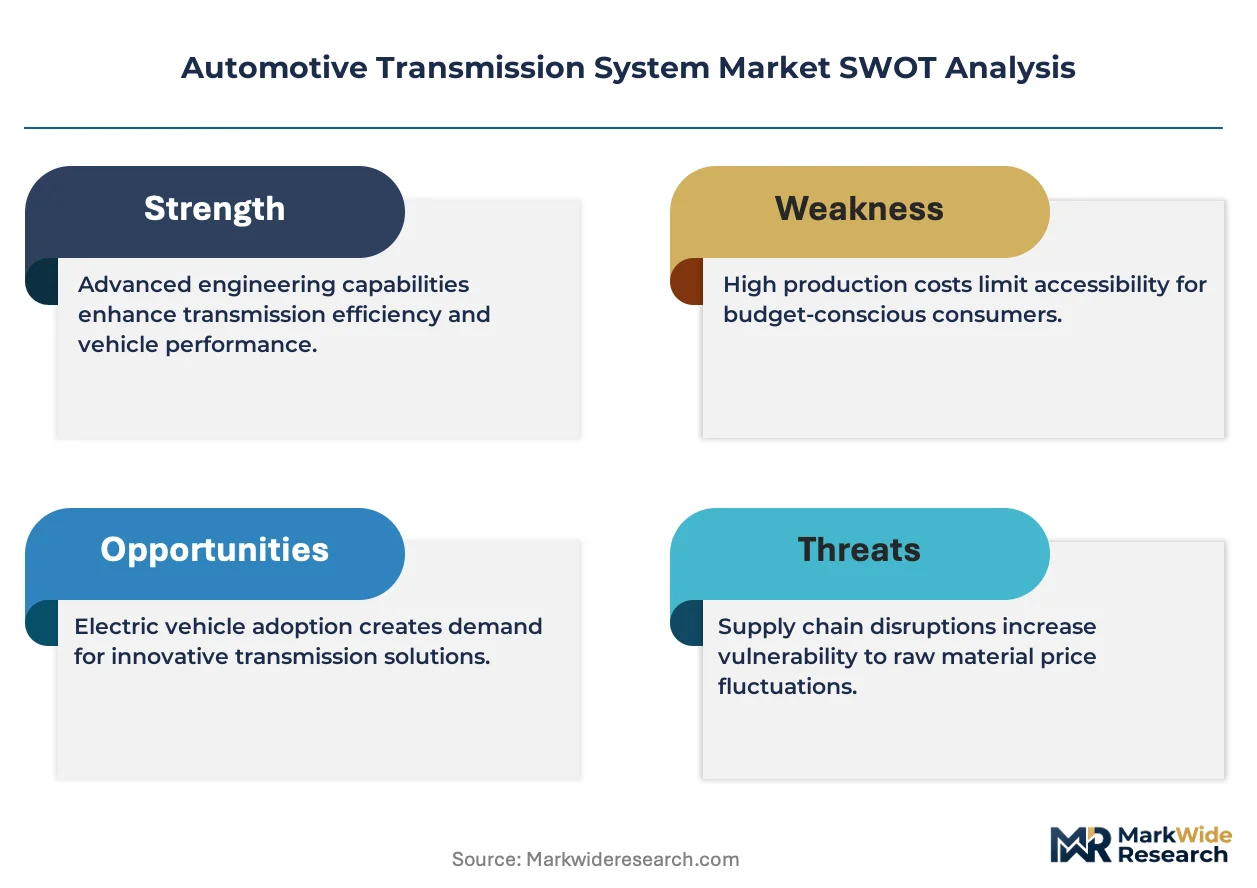
Powertrain electrification is fragmenting transmission architectures across OEM portfolios, forcing suppliers to engineer parallel hardware streams for internal combustion, hybrid, and battery-electric platforms simultaneously.
Growth Catalysts
- Multi-speed EV architectures:Electric vehicle manufacturers are adopting two-speed and three-speed gearboxes to optimize motor efficiency at highway speeds, expanding addressable content per vehicle beyond single-speed reduction units.
- Euro 7 emission standards:The European Union's tightened tailpipe limits are mandating faster gear-shift optimization and driveline efficiency gains that only advanced automatic transmissions can deliver.
- Hybrid torque-fill integration:Electromechanical coupling systems that blend engine and electric motor output are requiring dedicated transmission hardware, creating incremental demand for electrified driveline components.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings embedded in electric motor-generators are compressing margins on electrified transmission variants.
- Supplier concentration in precision forging:Germany and Japan control 70% of high-grade gear blank capacity, creating geographic chokepoints for transmission manufacturers outside these clusters.
- Single-speed BEV substitution:Battery-electric platforms from Tesla and Chinese OEMs are eliminating multi-gear hardware entirely in mass-market segments, capping long-term volume assumptions.
Strategic Opportunities
- India commercial vehicle upfit:Bharat Stage VI Phase 2 enforcement is accelerating replacement demand for automated manual transmissions in medium and heavy trucks.
- Software-defined shift calibration:Over-the-air update capability is enabling subscription-based performance tuning, creating recurring revenue streams from hardware already installed.
- MIIT dual carbon alignment:China's Ministry of Industry and Information Technology credits are incentivizing domestic OEMs to source locally-produced hybrid transmissions, opening captive supply opportunities.
Industry Challenges
- Mechatronics systems integration:Merging hydraulic valve bodies with electric motor control firmware requires embedded software talent scarce in traditional mechanical engineering organizations.
- Dual certification timelines:Simultaneous EPA and Euro 7 homologation cycles are stretching validation resources and compressing launch windows for global platform programs.
- Legacy toolpath obsolescence:Existing machining centers optimized for planetary gearsets cannot be retooled economically for electrified transmission housings with integrated cooling circuits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Transmission System Market |
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $476.85 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, CVT, Dual-Clutch End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Transmission Technology: Electronic, Hydromechanical, Electromechanical, Hybrid Application: Passenger Cars, Commercial Vehicles, Heavy-Duty Trucks, Light Trucks |
| Companies Covered | Aisin Seiki, ZF Friedrichshafen AG, Magna International, BorgWarner, JATCO, Allison Transmission, Continental AG, Eaton Corporation, Hyundai Transys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Transmission System Market Evolving Landscape
Electrified driveline hardware is diverging from century-old mechanical paradigms, with software-controlled torque paths replacing purely hydraulic shift logic and thermal management becoming a core engineering discipline.
Integrated electric axle drive units are electrifying the boundary between transmission and final drive. These compact assemblies combine motor, inverter, and multi-speed gearbox into a single housing, eliminating propeller shafts and differential carriers. Commercial vehicle manufacturers in Europe and North America are specifying these units for electric bus and medium-duty truck platforms, collapsing supplier tiers as axle specialists absorb transmission functions.
NHTSA fuel economy standards are tightening fleet-average obligations through 2032, compelling Detroit Three automakers to deploy wide-ratio ten-speed automatics across light truck segments previously served by six-speed units. The regulatory pressure is accelerating hardware refresh cycles and obsoleting transmission families that reached amortization only recently, forcing suppliers to recover development costs over compressed production runs.
Fleet procurement departments are consolidating supplier relationships around full-system integrators capable of delivering transmission, e-axle, and thermal management as a single contract. Tier One suppliers with captive electronics and casting capabilities are displacing component specialists in competitive bids. This concentration is most visible in North American full-size pickup and SUV programs, where OEMs now award multi-billion dollar driveline contracts to single-source partners rather than multi-vendor assemblies.
Automotive Transmission System Market Segmentation
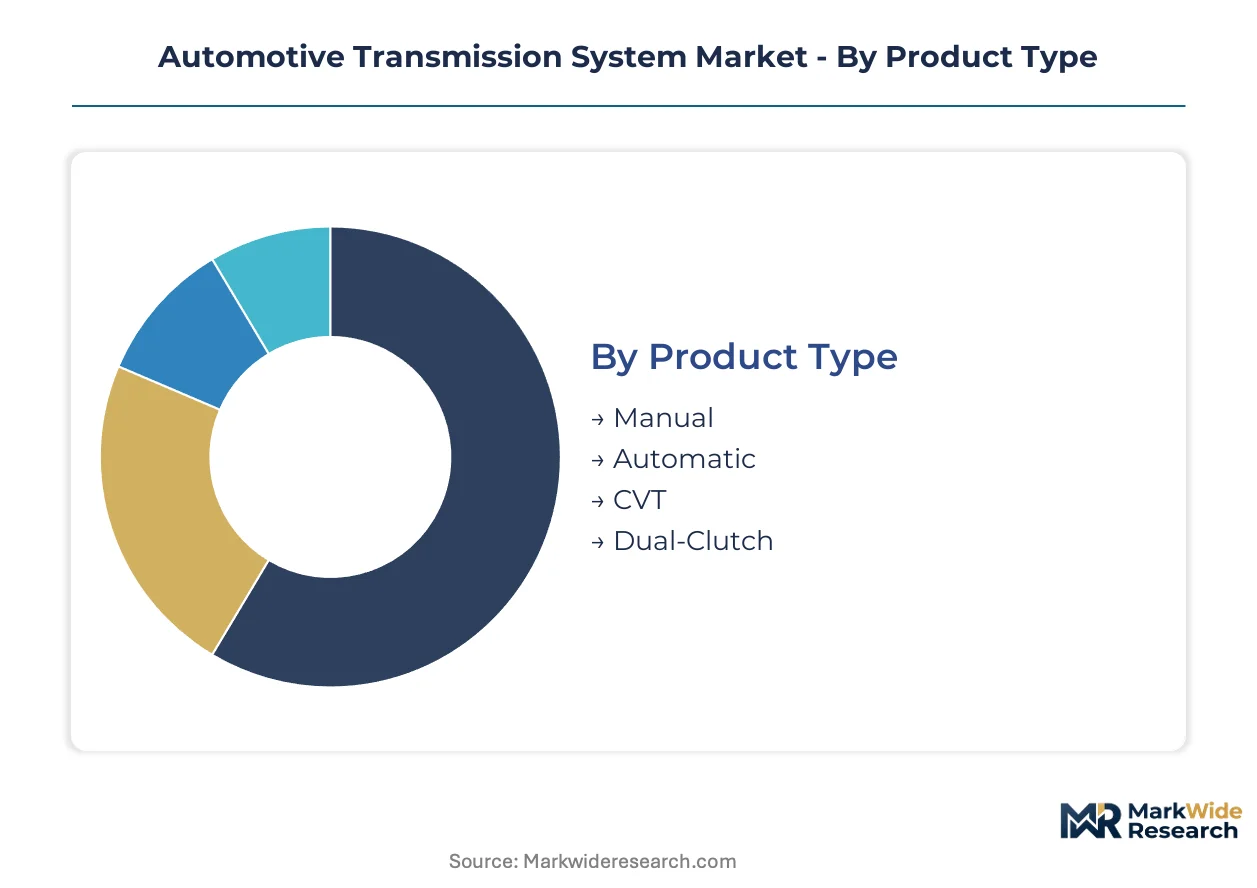
Transmission architectures diverge sharply based on integration depth with powertrain electronics and thermal management systems. Each segment category reflects distinct engineering trade-offs between mechanical refinement, software control, and electrification compatibility.
Product Type:
Standalone mechanical transmissions persist in cost-sensitive applications, while embedded electromechanical systems dominate electrified platforms.
- Automatic:Planetary gearsets with torque converter lockup and electronic shift control retain the largest installed base across light trucks and SUVs. EPA fuel economy standards are forcing ten-speed architectures that multiply hardware content per unit.
- Dual-Clutch:Wet and dry clutch packs delivering sub-100-millisecond shifts anchor performance passenger car portfolios. Germany and Japan concentrate development capacity for precision-forged gearsets and mechatronic valve bodies.
- Manual:Synchronized mesh gearboxes with cable or hydraulic actuation now concentrate in emerging market commercial vehicles and enthusiast passenger segments.
- CVT:Steel push-belt or chain-driven variable pulley systems optimize engine operating points for hybrid torque-fill applications.
Automatic transmissions lead volumes today; dual-clutch systems are gaining share fastest in premium passenger segments.
End User:
Cost tier stratification separates captive in-house production from outsourced procurement decisions across the supply base.
- OEMs:Vertically integrated powertrain divisions at major automakers design proprietary transmission families for platform exclusivity. NHTSA fleet compliance deadlines are accelerating internal development of multi-speed electrified architectures.
- Tier-1 Suppliers:Full-system integrators with captive casting, forging, and electronics capabilities compete for billion-dollar driveline contracts. ZF Friedrichshafen AG and Aisin Seiki anchor this tier through integrated mechatronics portfolios.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations sourcing transmission hardware through supply agreements rather than captive production.
- Aftermarket Providers:Remanufacturing specialists and performance tuning shops serving replacement demand and upgrade markets.
OEMs lead volumes today; Tier-1 suppliers are expanding share fastest as outsourcing accelerates.
Transmission Technology:
Maturity gradients separate century-old hydraulic systems from emerging electromechanical torque paths requiring embedded software talent.
- Hybrid:Electromechanical coupling systems blending internal combustion and electric motor output through dedicated planetary gearsets. Euro 7 emission standards are mandating this architecture for compliance.
- Electromechanical:Motor-generator integration with multi-speed reduction gearboxes replacing conventional automatic architectures in electrified platforms.
- Electronic:Solenoid-controlled hydraulic valve bodies with powertrain control module calibration enabling over-the-air shift strategy updates.
- Hydromechanical:Purely hydraulic shift logic with mechanical governors persisting in heavy-duty commercial applications.
Electronic systems lead volumes today; hybrid architectures are climbing the fastest as electrification mandates tighten.
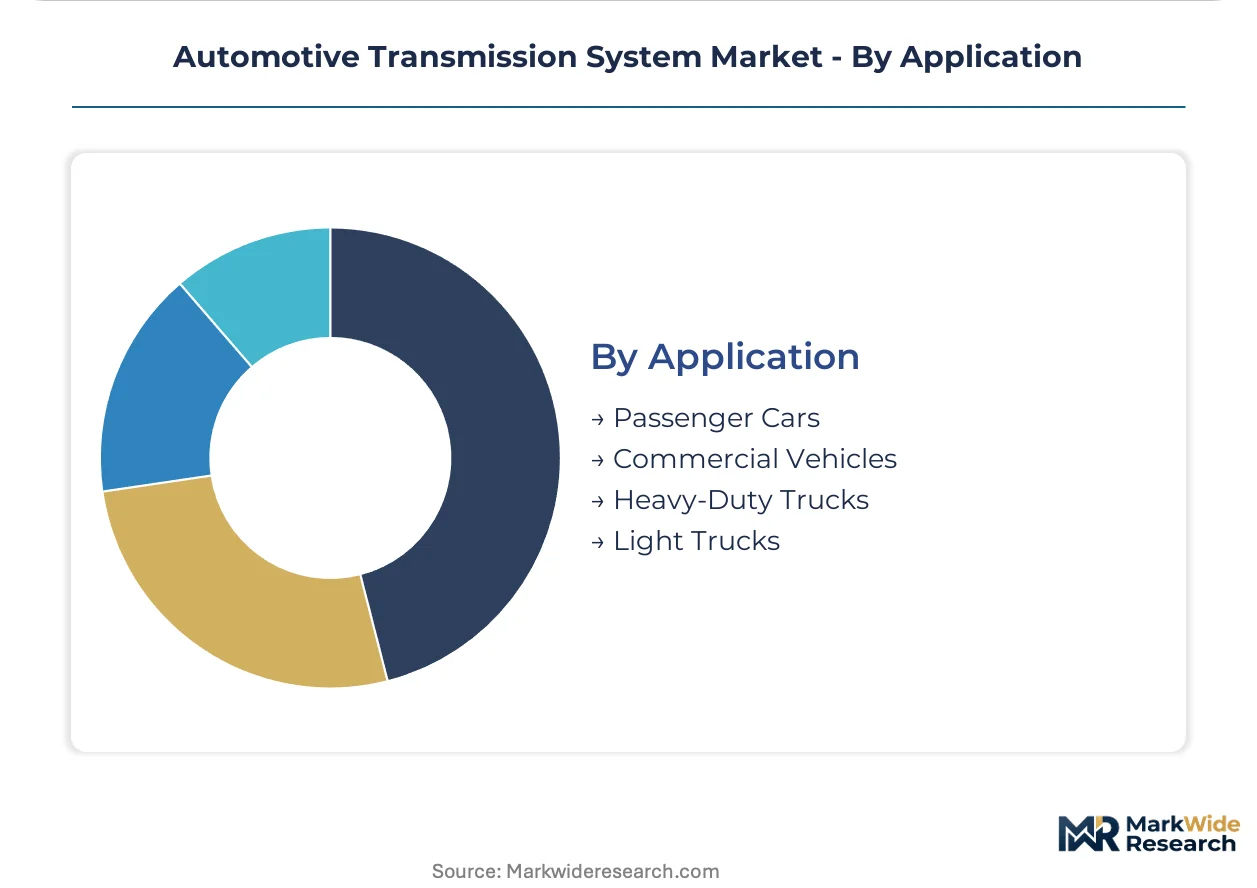
Application:
Volume concentration separates mass-market passenger segments from specialized commercial duty cycles with divergent torque and durability requirements.
- Passenger Cars:Transverse and longitudinal automatic transmissions, dual-clutch systems, and CVTs serving global compact through luxury vehicle segments. MIIT dual carbon goals in China are accelerating hybrid transmission adoption.
- Light Trucks:Longitudinal automatics with towing capacity ratings dominating North American full-size pickup and SUV portfolios. NHTSA fuel economy standards are forcing hardware refreshes from six-speed to ten-speed units.
- Commercial Vehicles:Automated manual and fully automatic transmissions for medium-duty delivery and regional haul applications. Bharat Stage VI Phase 2 in India is accelerating replacement demand.
- Heavy-Duty Trucks:Multi-range automated transmissions with integrated retarders serving long-haul and vocational duty cycles.
Passenger cars lead volumes today; light trucks are expanding share fastest as electrified pickup platforms multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transmission engineering talent concentrates in southwestern Germany, Aichi Prefecture in Japan, and Michigan's Detroit-Warren corridor, anchoring the industry's three dominant development clusters.
United States
Detroit Three automakers are accelerating ten-speed automatic deployment across light truck portfolios to meet NHTSA fuel economy standards through 2032. The EPA tailpipe regulations are forcing hardware refreshes that obsolete recently amortized six-speed families. Michigan's Warren-Troy corridor hosts concentrated supplier engineering centers serving these compliance-driven programs.
Germany
Premium OEMs in Baden-Württemberg and Bavaria are driving dual-clutch transmission refinement for performance electric vehicle applications. Euro 7 emission standards are mandating faster shift optimization and driveline efficiency gains. Stuttgart and Friedrichshafen anchor integrated mechatronics development, with precision forging clusters concentrated in the southwestern industrial belt.
Japan
Hybrid transmission production for global export platforms dominates Aichi Prefecture and Kanagawa manufacturing corridors. METI carbon neutrality targets are accelerating electromechanical torque-fill integration into next-generation architectures. Toyota City and Yokohama host captive powertrain divisions with integrated torque converter and control module production.
China
Domestic OEMs in Shanghai and Guangdong are sourcing locally-produced hybrid transmissions to capture MIIT dual carbon credits. MIIT regulations are incentivizing indigenous supply chain development for electrified driveline components. The Yangtze River Delta and Pearl River Delta concentrate forging capacity and motor-generator integration facilities.
India
Commercial vehicle manufacturers in Maharashtra and Tamil Nadu are upgrading to automated manual transmissions ahead of Bharat Stage VI Phase 2 enforcement. The Central Pollution Control Board timelines are accelerating replacement demand in medium and heavy truck segments. Pune and Chennai host transmission assembly operations serving domestic and export markets.
Automotive Transmission System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered supplier structure. The market consolidates around full-system integrators with captive casting, forging, and electronics capabilities. Three archetypes dominate: integrated mechatronics conglomerates, driveline-focused specialists, and axle-drive integrators absorbing transmission functions. Competitive moves center on strategic partnerships for electrified platform development and geographic expansion into regulatory-driven replacement markets.
Within the integrated mechatronics tier, ZF Friedrichshafen AG and Aisin Seiki occupy anchor positions through captive production portfolios. BorgWarner exemplifies the driveline specialist archetype bridging combustion and electrified platforms. Among Japan-based suppliers, JATCO and Hyundai Transys represent scale-driven manufacturing positions serving global OEM procurement consolidation.
| Leading Market Players |
|---|
| Aisin Seiki |
| ZF Friedrichshafen AG |
| Magna International |
| BorgWarner |
| JATCO |
| Allison Transmission |
| Continental AG |
| Eaton Corporation |
| Hyundai Transys |
| Others |
Value Network & Pricing Analysis
Precision forging specialists concentrated in southwestern Germany and Aichi Prefecture command wage premiums that propagate through three-tier pricing structures across premium, standard, and economy transmission tiers. Labor-cost differentials between these engineering clusters and emerging manufacturing zones in Mexico and Thailand drive spreads between mechatronics-integrated units and purely mechanical alternatives.
Pricing Analysis
Bundled full-system contracts encompassing transmission hardware, control electronics, and thermal management carry premiums over unbundled component procurement. Price differentiation rests on certification grade for EPA and Euro 7 compliance plus after-sales software update entitlements. Cost compression in economy-tier automated manual transmissions is intensifying because Indian and Chinese OEMs are localizing supply chains. Fleet procurement departments at North American light-truck manufacturers exhibit lowest price sensitivity due to NHTSA compliance penalties.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Detroit Three and German premium automakers, while tiered distribution serves aftermarket remanufacturers. Geographic supply concentration centers on Germany, Japan, and China for precision-forged gear blanks, control module electronics, and rare-earth motor magnets. Raw material dependencies draw from neodymium-dysprosium alloys, high-grade steel billets, and copper winding stock. Single-source vulnerability in torque converter clutch plate supply creates chokepoint exposure. Distribution runs through captive supplier parks adjacent to major OEM assembly complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive transmission system market functions as a regulatory compounder where Euro 7 and NHTSA fleet standards are mandating hardware refresh cycles that sustain replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Hedge against single-speed BEV substitution by accelerating multi-speed electromechanical architectures for commercial vehicle platforms. Deepen backward integration into precision forging capacity in Germany and Japan to defend margin position against rare-earth cost volatility. Prioritize embedded software talent acquisition to address mechatronics integration scarcity.
For New Entrants and Emerging Players: Regional aftermarket providers in India's Bharat Stage VI Phase 2 enforcement corridor represent underserved buyer archetypes with immediate replacement demand. Automated manual transmission upfit opportunities in medium-duty trucks offer lowest competitive density. Pursue joint development agreements with domestic OEMs seeking MIIT dual carbon credit capture.
For Investors and Strategic Acquirers: Full-system integrators with captive electronics and casting capabilities are the most active acquirer in this space, consolidating component specialists into billion-dollar driveline contracts. Long-term viability hinges on electrified platform compatibility across hybrid and battery-electric architectures. Target acquisition archetypes include axle-drive specialists absorbing transmission functions and software-defined calibration shops. Monitor EPA tailpipe regulation stringency as inflection indicator for ten-speed automatic demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces engineering validation costs across Euro 7 and EPA dual certification timelines. |
| Battery Supply Agreement | Secures motor-generator capacity for hybrid transmission production in Aichi Prefecture. |
| Software-Defined Vehicle Investment | Enables over-the-air shift calibration subscriptions from installed transmission hardware. |
| Geographic Manufacturing Footprint | Positions capacity in India ahead of Bharat Stage VI Phase 2 replacement demand. |
| Charging Infrastructure Partnership | Integrates e-axle thermal management with fast-charging protocols for commercial vehicles. |
Research Methodology
Bottom-up vehicle production modeling reconciled against top-down supplier capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 procurement directors, aftermarket distributors, and dealership service operations were cross-validated against secondary sources including vehicle registration databases, IHS Markit production forecasts, EPA certification filings, and MIIT dual carbon credit disclosures. This triangulation ensures demand-side consumption patterns align with supply-side manufacturing footprints.
Historical trendline analysis of transmission content per vehicle across propulsion architectures established baseline growth trajectories. The analytical framework models volume and value across the projection horizon through segmentation by vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from regression analysis of technology adoption curves and regulatory compliance deadlines. Industry-specific forecast inputs include Euro 7 implementation timing and NHTSA fuel economy standard phase-in schedules.
Inputs from OEM production schedules and supplier capacity announcements were available through the study window; gaps in Chinese domestic OEM procurement data introduce uncertainty bands around MIIT credit-driven demand assumptions. Forecasts reflect documented assumptions regarding electrification penetration rates and rare-earth price stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Fuel Cock Market
Powertrain
Transmission Sales Market
Powertrain
Reciprocating Engine Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
North America Electro Hydraulic Power Steering Market
Powertrain
South Africa Automotive Engine Oils Market
Powertrain
Automotive Engine Cylinder Block Market
Powertrain
Tachometer Market
Powertrain
Continuous Variable Transmission Market
Powertrain
Electric Powertrain Systems Market
Powertrain
Diesel Engine Catalyst Market
Powertrain
Automotive Crankshaft Market
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Hydraulic Lash Adjuster Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
United States Electro Hydraulic Power Steering Market