
 Crankshaft Position Sensor Market | 2026-2036
Crankshaft Position Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Crankshaft Position Sensor Market Analysis
Single-source procurement of magnetic sensing elements is realigning toward dual-source strategies as automakers mitigate supply risk. Robert Bosch GmbH leverages in-house semiconductor fabrication to control Hall Effect sensor yields across European assembly lines. Sensata Technologies anchors North American supply through dedicated foundry partnerships with Detroit-based tier-1 suppliers. Continental AG competes on module integration, embedding crankshaft position sensing within broader powertrain control units.
A crankshaft position sensor detects angular position and rotational speed of a crankshaft using electromagnetic, optical, or Hall Effect principles, typically operating at temperatures from minus forty to one hundred fifty degrees Celsius with signal resolution below one degree crank angle. The device enables precise ignition timing, fuel injection sequencing, and misfire detection in internal combustion and hybrid powertrains. Hall Effect Sensors command the dominant share of OEM installations due to immunity to vibration-induced signal degradation and compatibility with direct-fit mounting configurations. Aftermarket Providers represent a faster-expanding channel as aging vehicle parc in North America and Europe drives replacement demand for universal-fit optical and variable reluctance alternatives. Digital technology architectures are displacing analog signal processing in new platform designs, concentrating margin pools with suppliers offering ASIC-integrated hybrid solutions.
NHTSA mandates on onboard diagnostics and EPA emission enforcement shape sensor accuracy thresholds for US-bound vehicles, while EU Green Deal trajectories and Euro 7 preparation by EMA member authorities accelerate digital sensor migration across European fleets. REACH substance restrictions on rare-earth magnet content are forcing material substitutions in magnetic sensor variants, compressing margins for non-integrated suppliers. Stakeholders must monitor powertrain electrification pacing, as hybrid architectures sustain crankshaft position sensor demand longer than full battery-electric transitions but require redesigned mounting and thermal specifications.
Market Dynamics
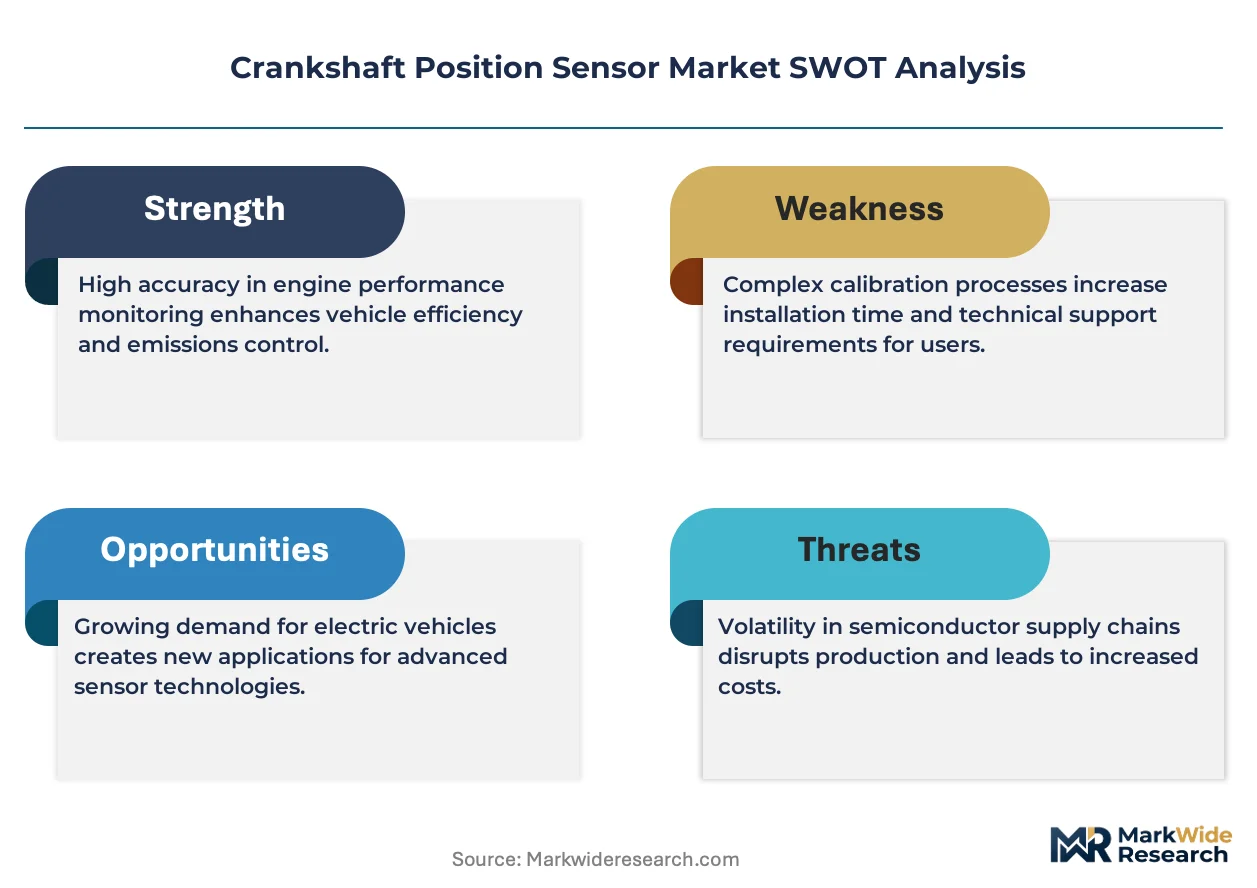
EPA Tier 3 and Euro 7 emission benchmarks are compressing sensor accuracy tolerances across powertrain architectures, forcing automakers to upgrade from analog to digital signal processing platforms and dual-source magnetic sensing elements.
Growth Catalysts
- Emission Benchmark Stringency:EPA Tier 3 and Euro 7 standards mandate sub-degree crank angle resolution for precise ignition timing control in internal combustion engines.
- Hybrid Powertrain Persistence:Hybrid architectures sustain crankshaft position sensor demand longer than full battery-electric transitions, requiring redesigned thermal specifications.
- Aftermarket Channel Expansion:Aging vehicle parc in Germany, Japan, and the United States drives replacement demand for universal-fit optical and variable reluctance alternatives.
Market Restraints
- Rare-Earth Magnet Cost Volatility:REACH substance restrictions on neodymium and dysprosium content in magnetic sensor variants compress margins for non-integrated suppliers.
- Single-Source Supply Concentration:Historical reliance on sole-source procurement of Hall Effect sensing elements creates vulnerability to foundry capacity constraints.
- Full Electrification Substitution:Battery-electric powertrains eliminate crankshaft position sensing entirely, capping long-term addressable market expansion.
Strategic Opportunities
- ASIC-Integrated Hybrid Solutions:Digital technology architectures concentrate margin pools with suppliers offering application-specific integrated circuit sensor modules.
- Module Integration Convergence:Embedding crankshaft position sensing within broader powertrain control units creates value-capture opportunities in European precision manufacturing clusters.
- Foundry Partnership Models:Dedicated semiconductor fabrication alliances with Detroit-based tier-1 suppliers secure captive supply of Hall Effect sensor yields.
Industry Challenges
- Signal Processing Talent Scarcity:Shortage of analog-to-digital conversion specialists and ASIC design engineers constrains new platform development timelines.
- Dual-Source Reconfiguration Friction:Automakers face qualification delays and tooling duplication costs when migrating from single-source to dual-source magnetic sensing procurement.
- Thermal Specification Recertification:Hybrid powertrain mounting positions require revalidation of minus forty to one hundred fifty degrees Celsius operating ranges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crankshaft Position Sensor Market |
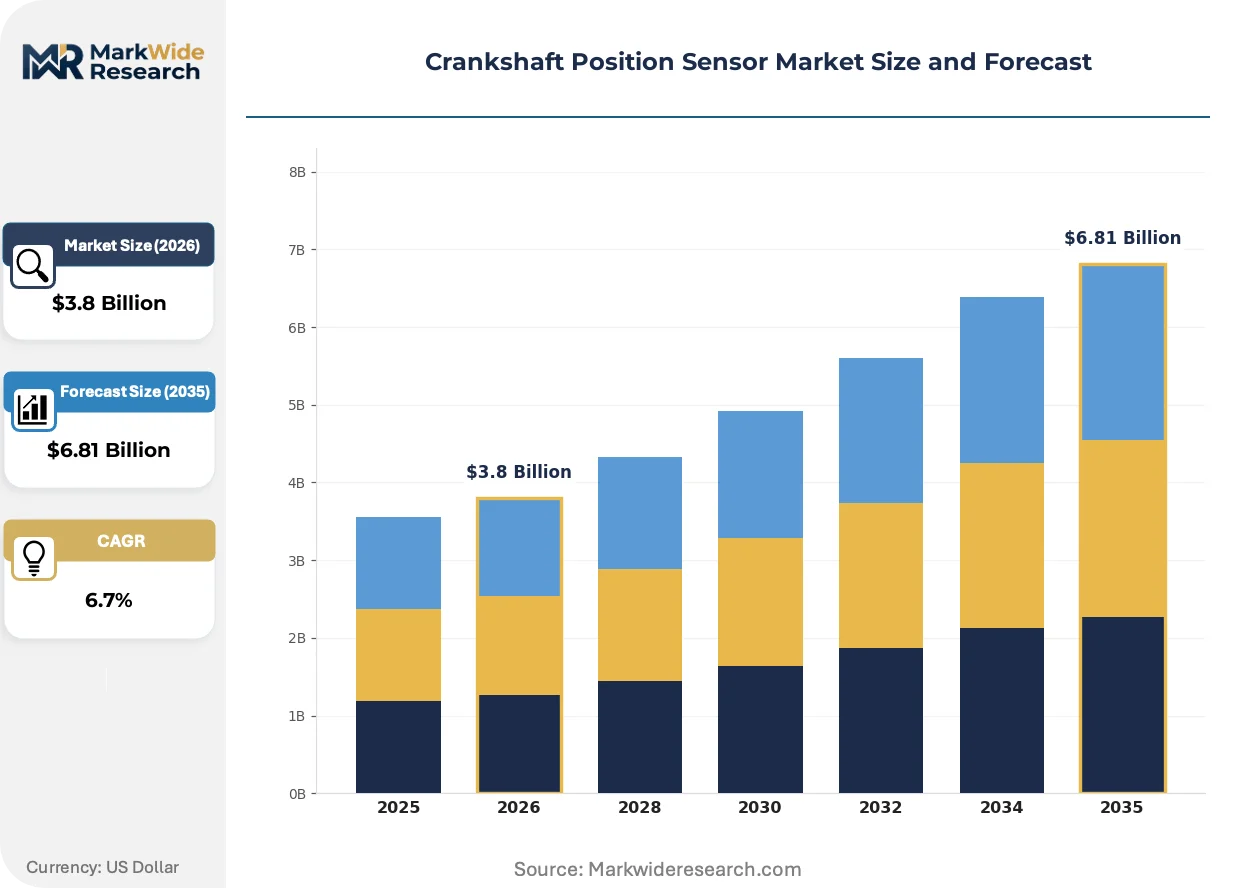
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Sensors, Optical Sensors, Hall Effect Sensors, Variable Reluctance Sensors End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Analog, Digital, Emerging Technologies, Hybrid Installation Type: Direct Fit, Universal Fit, Replacement, Customized Solutions |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Continental AG, Valeo SA, Delphi Technologies, HELLA GmbH & Co. KGaA, Mitsubishi Electric Corporation, Sensata Technologies, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crankshaft Position Sensor Market Emerging Trajectories
Digital signal architectures are displacing analog processing in new platform designs, concentrating technical capability with semiconductor-integrated suppliers while regulatory emission enforcement accelerates sensor accuracy upgrades across powertrain portfolios.
Smart sensor modules with embedded diagnostic capability are integrating temperature compensation algorithms and self-calibration routines directly into the sensing element. Tier-1 suppliers in Germany and Japan are adopting these modules for 2026 powertrain platforms. This integration is compressing the addressable market for standalone signal conditioning components and analog interface suppliers.
REACH substance restrictions on rare-earth magnet content are forcing material substitutions in magnetic sensor variants across European supply chains. ECHA regulatory timelines are compressing reformulation windows for Hall Effect sensor manufacturers. Sensor suppliers with in-house magnet alloy development capabilities in Germany and Switzerland are securing preferential qualification status with EMA member authorities preparing Euro 7 enforcement frameworks.
Automotive OEMs are consolidating supplier panels for crankshaft position sensing elements, reducing qualified vendor lists from six to two sources per platform. Tier-1 powertrain control module manufacturers in the United States and Japan are responding by offering exclusive foundry capacity commitments. This consolidation is most visible in Detroit and Nagoya manufacturing corridors where direct-fit mounting configurations dominate platform specifications.
Crankshaft Position Sensor Market Segmentation
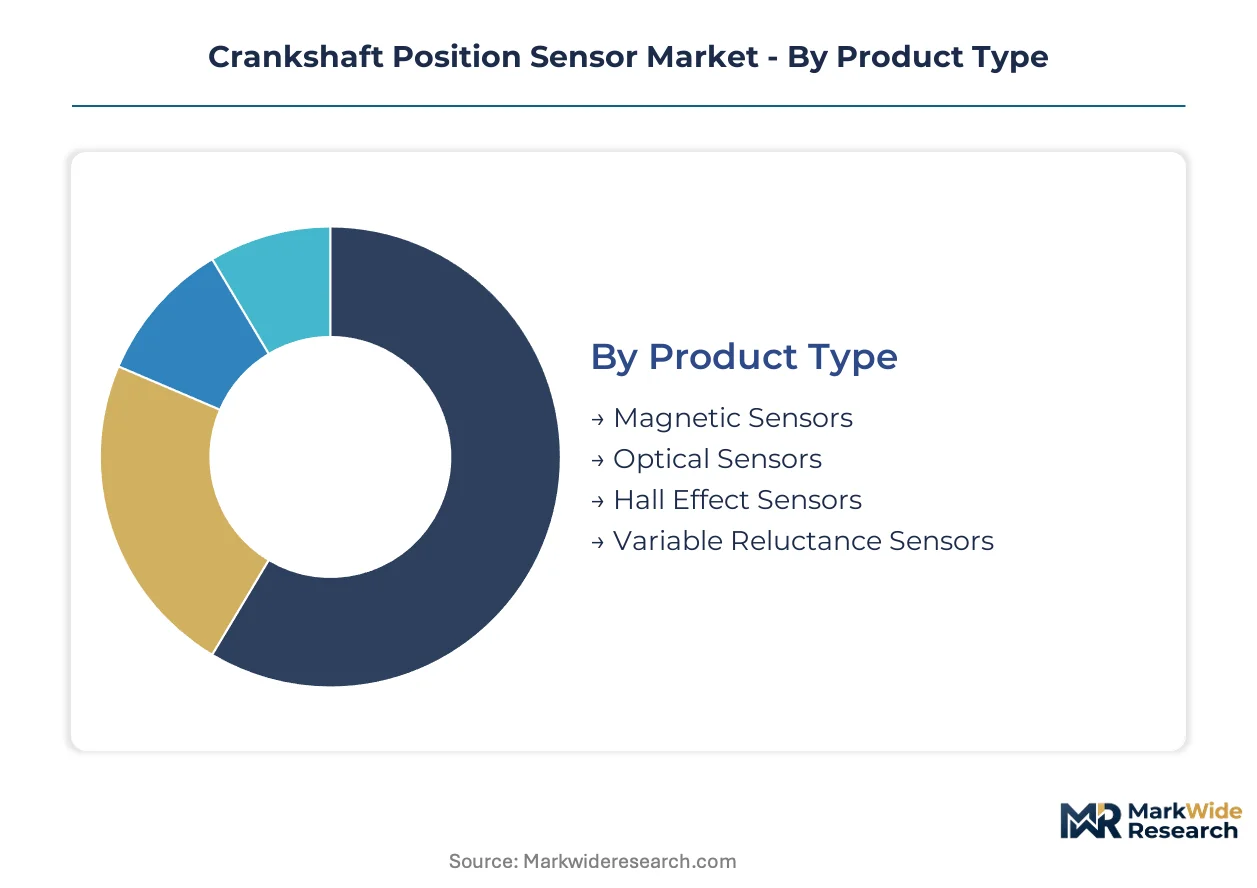
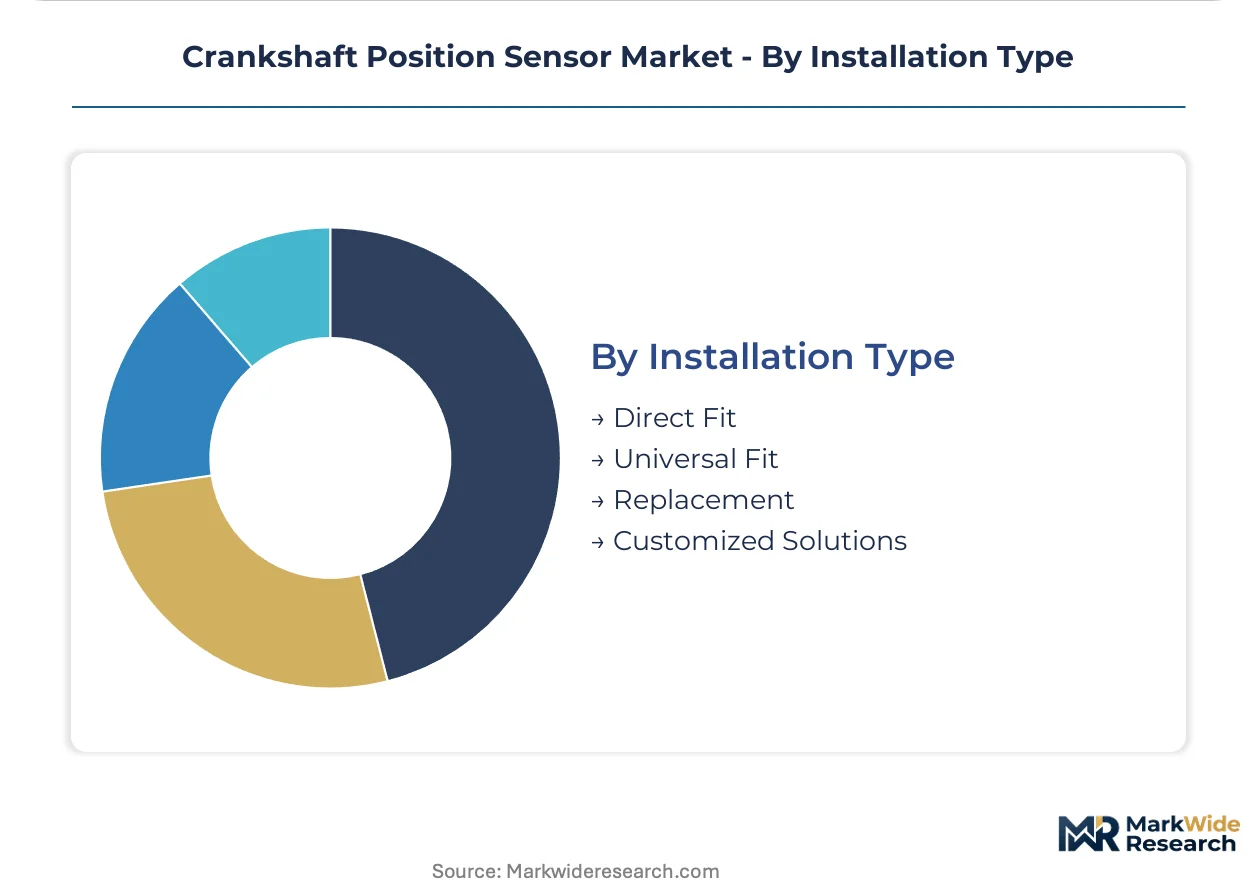
Crankshaft position sensor procurement patterns diverge sharply across product architectures and installation contexts. Upgrade cycles from analog to digital signal processing and the shift from single-source to dual-source magnetic element procurement reshape segment priorities for automakers and tier-1 suppliers.
Product Type:
Replacement demand and emission compliance timelines determine which sensing technologies retain platform qualification status across powertrain generations.
- Hall Effect Sensors:These solid-state devices detect crankshaft position through voltage variations induced by magnetic field disruption, delivering sub-degree angular resolution with immunity to oil contamination and vibration. OEM procurement in Germany, Japan, and the United States concentrates on Hall Effect variants as EPA Tier 3 and Euro 7 mandates tighten ignition timing precision requirements.
- Magnetic Sensors:Electromagnetic induction principles enable these units to generate signal output without external power, though they exhibit sensitivity to installation air gap tolerances. Demand clusters in cost-optimized powertrain architectures where signal conditioning electronics are bundled upstream into engine control modules.
- Variable Reluctance Sensors:These legacy units rely on toothed reluctor wheels and coil windings, dominating aftermarket replacement channels for aging vehicle parc in North America and Europe.
- Optical Sensors:Photoelectric detection delivers the highest resolution but requires pristine operating environments; niche applications include racing powertrains and specialized industrial engines.
Hall Effect sensors sit at the top of the volume ranking, with variable reluctance alternatives climbing the fastest in aftermarket channels.
End User:
Procurement authority and volume scale separate direct OEM relationships from intermediary tier-1 and aftermarket distribution channels.
- OEMs:Original equipment manufacturers specify sensor accuracy thresholds, thermal operating ranges, and diagnostic protocol compatibility for new powertrain platforms. Direct OEM contracts in Stuttgart, Toyota City, and Detroit concentrate qualification resources on Hall Effect and digital hybrid architectures.
- Tier-1 Suppliers:These powertrain control module manufacturers aggregate sensor procurement across multiple OEM platforms, leveraging foundry partnerships to secure captive semiconductor supply.
- Aftermarket Providers:Universal-fit optical and variable reluctance alternatives serve replacement demand from independent repair networks.
- Vehicle Assemblers:Contract manufacturers without in-house powertrain design authority execute sensor installation per OEM specification sheets.
Tier-1 suppliers command the largest procurement volumes, with aftermarket providers expanding most quickly as vehicle parc ages.
Technology:
Signal processing architecture determines margin capture potential and regulatory compliance headroom across emission enforcement jurisdictions.
- Digital:ASIC-integrated modules with embedded temperature compensation and self-calibration routines enable direct compliance with EPA onboard diagnostic mandates. European tier-1 suppliers in Germany and Switzerland prioritize digital platforms for Euro 7 preparation.
- Hybrid:Combined analog sensing elements with digital output stages bridge legacy system compatibility and modern diagnostic requirements. These configurations dominate mid-cycle powertrain updates where full platform redesign is uneconomical.
- Analog:Continuous voltage output architectures face phase-out as emission accuracy thresholds tighten; residual demand concentrates in emerging market vehicle segments with less stringent enforcement.
- Emerging Technologies:Magnetoresistive and tunneling magnetoresistance variants undergo qualification for next-generation hybrid thermal specifications.
Digital architectures lead installed base value, with hybrid solutions gaining share fastest in mid-cycle platform updates.
Installation Type:
Mounting configuration and sourcing flexibility separate original platform specifications from service-channel alternatives.
- Direct Fit:OEM-specified mounting geometries, connector pinouts, and calibration data match specific engine architectures exactly. Direct fit procurement in Nagoya and Detroit manufacturing corridors requires dual-source qualification of Hall Effect sensing elements.
- Universal Fit:Adjustable mounting brackets and programmable signal conditioning enable cross-platform compatibility. Aftermarket demand in Germany and the United States drives volume for optical and variable reluctance alternatives with adaptable air gap tolerances.
- Replacement:Like-for-like part number substitution maintains warranty compliance and diagnostic protocol continuity.
- Customized Solutions:Specialized thermal packaging and shielding configurations serve hybrid powertrain mounting positions with revised operating range requirements.
Direct fit captures the highest unit volumes, with universal fit expanding most rapidly in independent service channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's precision manufacturing corridor anchors OEM procurement for Hall Effect crankshaft position sensors, with tier-1 supplier networks extending into Nagoya and Detroit. EPA Tier 3 and Euro 7 emission mandates reshape sensor accuracy requirements across these three dominant production clusters.
United States
Detroit-based tier-1 suppliers aggregate procurement volumes across multiple OEM platforms, leveraging dedicated foundry partnerships for captive semiconductor supply. NHTSA onboard diagnostic mandates and EPA emission enforcement compress sensor accuracy tolerances for domestic powertrain architectures. The Southeast manufacturing corridor, particularly Tennessee and South Carolina assembly plants, executes sensor installation per OEM specification sheets for hybrid powertrain programs.
Germany
EMA member authorities preparing Euro 7 enforcement frameworks accelerate digital sensor migration across European fleets manufactured in Baden-Württemberg and Bavaria. REACH substance restrictions on rare-earth magnet content force material substitutions in magnetic sensor variants, compressing reformulation windows for Hall Effect manufacturers. Stuttgart and Munich precision clusters host suppliers with in-house magnet alloy development capabilities securing preferential qualification status.
Japan
Toyota City and Nagoya manufacturing corridors concentrate qualification resources on Hall Effect and digital hybrid architectures for domestic OEM platforms. METI industrial standards shape thermal operating range specifications for hybrid powertrain mounting positions requiring redesigned sensor packaging. Chubu region tier-1 suppliers offer exclusive foundry capacity commitments as automakers consolidate qualified vendor lists from six to two sources per platform.
China
Yangtze River Delta and Pearl River Delta production bases supply cost-optimized powertrain architectures where signal conditioning electronics bundle upstream into engine control modules. MIIT emission standards and GB technical regulations drive incremental sensor accuracy upgrades for domestic vehicle segments. Shanghai and Shenzhen industrial zones concentrate aftermarket manufacturing for universal-fit optical and variable reluctance alternatives serving replacement demand.
South Korea
Seoul Capital Area powertrain control module manufacturers anchor Hall Effect sensor procurement for Hyundai-Kia platform architectures. MFDS automotive component standards intersect with corporate emission reduction targets to accelerate digital signal processing adoption. Busan-Ulsan manufacturing corridors specialize in direct-fit mounting configurations with dual-source qualification requirements for export-bound vehicle programs.
Crankshaft Position Sensor Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue ASIC-integrated hybrid solutions and module convergence opportunities. The supplier base stratifies across semiconductor-integrated specialists, tier-1 powertrain control module manufacturers, and aftermarket component distributors. Three archetypes dominate: in-house fabrication specialists controlling Hall Effect yields, module integrators embedding sensing within broader control units, and foundry-dependent suppliers securing captive capacity through partnership structures. Competitive moves concentrate on dual-source reconfiguration and foundry partnership consolidation.
Among German-based diversified suppliers, Robert Bosch GmbH and Continental AG exemplify contrasting strategic positions within the module integration archetype. Sensata Technologies anchors North American supply through dedicated semiconductor fabrication alliances. These three entities represent the dominant geographic and structural configurations shaping competitive dynamics across Stuttgart, Detroit, and Nagoya manufacturing corridors.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Continental AG |
| Valeo SA |
| Delphi Technologies |
| HELLA GmbH & Co. KGaA |
| Mitsubishi Electric Corporation |
| Sensata Technologies |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Semiconductor fabrication specialists concentrated in Taiwan and South Korea command wage premiums that widen spreads between economy-grade variable reluctance sensors and premium Hall Effect modules with integrated ASIC architectures.
Pricing Analysis
Input-cost pass-through from rare-earth magnet volatility and foundry capacity constraints shapes contract structures across procurement tiers. Three-tier pricing structure across premium, standard, and economy levels separates ASIC-integrated digital modules from hybrid signal processors and legacy analog units. Cost compression in economy tiers intensifies because REACH substance restrictions force magnet alloy reformulation without offsetting volume scale. Tier-1 powertrain control module manufacturers exhibit lowest price sensitivity due to captive foundry partnerships, while aftermarket distributors face acute margin pressure from universal-fit commoditization.
Supply Chain Analysis
Workforce availability for analog-to-digital conversion engineering concentrates in Stuttgart, Nagoya, and Detroit precision manufacturing corridors, constraining expansion timelines for hybrid sensor platform development. Supply concentrates in Germany, Japan, and the United States for Hall Effect sensing element fabrication, with China anchoring aftermarket optical and variable reluctance production. Raw material dependencies rest on neodymium-dysprosium magnet alloys, silicon wafer substrates, and specialized epoxy encapsulants. Single-source vulnerability permeates Hall Effect semiconductor foundry capacity, particularly for EPA Tier 3 and Euro 7 qualification-grade components. Distribution runs through tier-1 powertrain control module manufacturers aggregating across multiple OEM platforms before downstream vehicle assembly integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on ASIC integration density capturing value from emission-mandated accuracy upgrades, while material substitution in magnetic elements compresses cost structures for qualified suppliers.
For Market Incumbents: Lock in dual-source qualification status with EMA member authorities preparing Euro 7 enforcement frameworks by accelerating in-house magnet alloy development capabilities. Deepen backward integration into semiconductor fabrication to secure captive Hall Effect sensor yields against foundry capacity constraints. Consolidate supplier panel positions as automakers reduce qualified vendor lists from six to two sources per platform, defending against module integrators embedding sensing within broader powertrain control units. For New Entrants and Emerging Players: Capture aftermarket channel expansion in aging vehicle parc segments across Germany and the United States where universal-fit optical and variable reluctance alternatives face less stringent qualification barriers. Target white-space in hybrid powertrain customized thermal packaging solutions requiring redesigned minus forty to one hundred fifty degrees Celsius operating range specifications. Pursue exclusive foundry partnership models with Detroit-based tier-1 suppliers seeking to diversify beyond incumbent semiconductor fabrication alliances. For Investors and Strategic Acquirers: Tier-1 powertrain control module manufacturers are the most active acquirers in this space, consolidating sensor module integration capabilities to capture value from OEM vendor panel rationalization. Long-term viability over the mid-term projection horizon rests on hybrid architecture persistence sustaining crankshaft position sensor demand longer than full battery-electric transitions. Target acquisition candidates with ASIC design engineering talent pools and established dual-source qualification pathways. Monitor powertrain electrification pacing as the critical inflection signal—material acceleration in battery-electric penetration caps addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ASIC-Integrated Module Development | Captures margin concentration from EPA Tier 3 and Euro 7 emission accuracy mandates. |
| Dual-Source Foundry Partnership | Secures captive semiconductor supply against single-source vulnerability in Hall Effect fabrication. |
| Magnet Alloy Reformulation | Enables REACH compliance for rare-earth content restrictions across EMA member authority jurisdictions. |
| Module Integration Convergence | Embeds crankshaft position sensing within broader powertrain control units for European OEM procurement. |
| Aftermarket Channel Expansion | Serves replacement demand from aging vehicle parc in North American and European independent repair networks. |
Methodological Framework
Direct dialogue with OEM platform engineers, tier-1 supplier procurement directors, aftermarket distribution channel managers, and semiconductor foundry operations specialists grounded qualitative assessment in operational reality. Primary insights combined with secondary validation from EPA emission enforcement documentation, EMA Euro 7 preparation frameworks, REACH substance restriction filings, vehicle production databases, and tier-1 supplier SEC disclosures. Bottom-up and top-down triangulation cross-checked sensor unit volume assumptions against powertrain platform production schedules and content-per-vehicle estimates.
Bottom-up modeling aggregated segment-level unit economics across Hall Effect, magnetic, variable reluctance, and optical product architectures, while top-down analysis calibrated aggregate market value against OEM procurement spend patterns. Segmentation dimensions spanned product type, end user category, signal processing technology, and installation configuration across the projection horizon. CAGRs derived from regression analysis of historical platform adoption curves and regulatory enforcement timeline impacts. Forecast inputs incorporated hybrid powertrain penetration trajectories and REACH substance restriction compliance cost curves.
Powertrain electrification acceleration, rare-earth magnet supply disruption, and EMA Euro 7 enforcement delay are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about hybrid architecture persistence sustaining sensor demand and dual-source procurement migration timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Europe Internal Combustion Engines Market
Powertrain
Turbocharger Actuators Market
Powertrain
Clutch Hub Puller Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
Clutch Friction Plate Market
Powertrain
UAE Automotive Engine Oils Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Automotive Brake Booster Market
Powertrain
Automotive Vacuum Brake Booster Market
Powertrain
Fuel Pumps Market
Powertrain
Automotive Power Steering Cooler Market
Powertrain
Automotive Transmission Fluid Market
Powertrain
Automotive Power Modules Market
Powertrain
Engine Actuators Market
Powertrain
Crankshaft Oil Market
Powertrain
Continuous Variable Transmission Market