
 Global Automotive Differential System Market | 2026-2036
Global Automotive Differential System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Differential System Market Intelligence
A strategic shift from single-source to multi-source component procurement by automotive OEMs is realigning the supplier landscape. This move diversifies supply chains and intensifies competition among established providers. ZF Friedrichshafen AG leverages its expertise in integrated e-drivetrain systems for electric vehicles. Meanwhile, Eaton specializes in high-performance locking and limited-slip differentials for niche vehicle segments, while Dana Limited competes across a broad portfolio for light and commercial vehicles.
An automotive differential system is a gear train that allows a vehicle's drive wheels to rotate at different speeds during a turn. It primarily functions to distribute engine torque effectively while preventing tire scrub and driveline stress. While open differentials remain standard in economy passenger cars, the market shows a clear migration towards torque vectoring differential systems for performance applications. This trend is supported by the adoption of electronic control technology, which offers superior dynamic handling over older mechanical designs.
Regulations like the US EPA's fuel economy standards and China's dual carbon goals pressure automakers to improve drivetrain efficiency. The EU's CO2 emissions targets further accelerate the adoption of lighter, lower-friction components, including advanced differentials. Consequently, suppliers must decide whether to focus R&D on optimizing mechanical systems for legacy vehicles or on developing integrated electronic units for emerging electric vehicle architectures.
Market Dynamics
The fundamental transition from mechanical gear trains to software-defined mechatronic systems is the central force shaping the automotive differential market. This shift is driven by the rise of electric vehicles and the industry-wide adoption of electronic controls for enhanced vehicle dynamics.
Growth Catalysts
- EU CO2 Emissions Targets:Regulations in Europe mandating lower vehicle emissions pressure automakers to adopt lighter, more efficient drivetrain components, including advanced low-friction differential systems to improve overall vehicle efficiency.
- Torque Vectoring Technology:The adoption of torque vectoring differentials in performance and all-wheel-drive vehicles offers superior handling and stability, creating strong pull from consumers and OEMs in these premium segments.
- Chinese Automotive Manufacturing:Concentrated demand from China's massive vehicle production ecosystem provides significant volume opportunities for differential system suppliers who can meet local technical and cost requirements.
Market Restraints
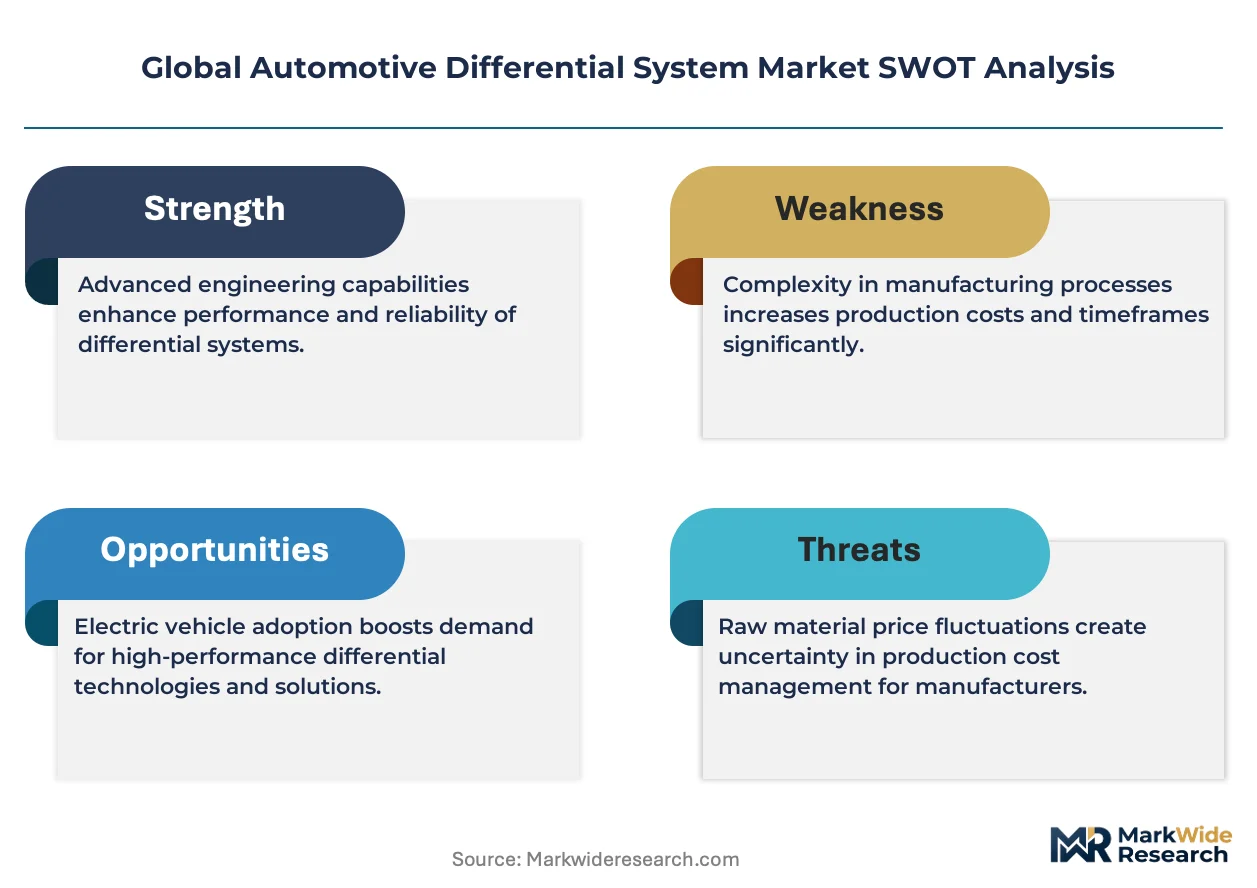
- High Development Costs:The significant research and development investment required for electronic differentials and integrated e-axles creates a high barrier to entry compared to mature, low-cost mechanical differential technologies.
- ECU Supply Bottlenecks:A reliance on a concentrated group of semiconductor and electronic control unit (ECU) manufacturers creates supply chain vulnerability and potential production delays for advanced differential systems.
- Integration Complexity:The technical challenge of ensuring seamless software and hardware integration between the differential control unit and other vehicle systems can extend development timelines and increase validation costs for OEMs.
Strategic Opportunities
- Commercial EV E-Axles:Developing fully integrated e-axle systems that combine the motor, power electronics, and differential into a single unit presents a significant opportunity for suppliers targeting the growing electric truck and bus market.
- Software and ADAS Integration:There is a clear opportunity to create value by developing sophisticated control software that integrates differential torque management with ADAS and vehicle stability systems for enhanced safety and performance. *Performance Aftermarket Upgrades: A robust aftermarket exists for enthusiasts seeking to upgrade stock open or limited-slip differentials in sports cars and off-road vehicles to high-performance locking or torque-vectoring units.
Industry Challenges
- Specialized Talent Scarcity:A shortage of mechatronics and software engineers with expertise in developing and validating complex electronic drivetrain controls presents a significant operational hurdle for both suppliers and OEMs.
- Validation and Calibration Burden:The extensive time and resources required to test, validate, and calibrate differential control software for every unique vehicle model and powertrain combination is a major challenge for program execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Differential System Market |
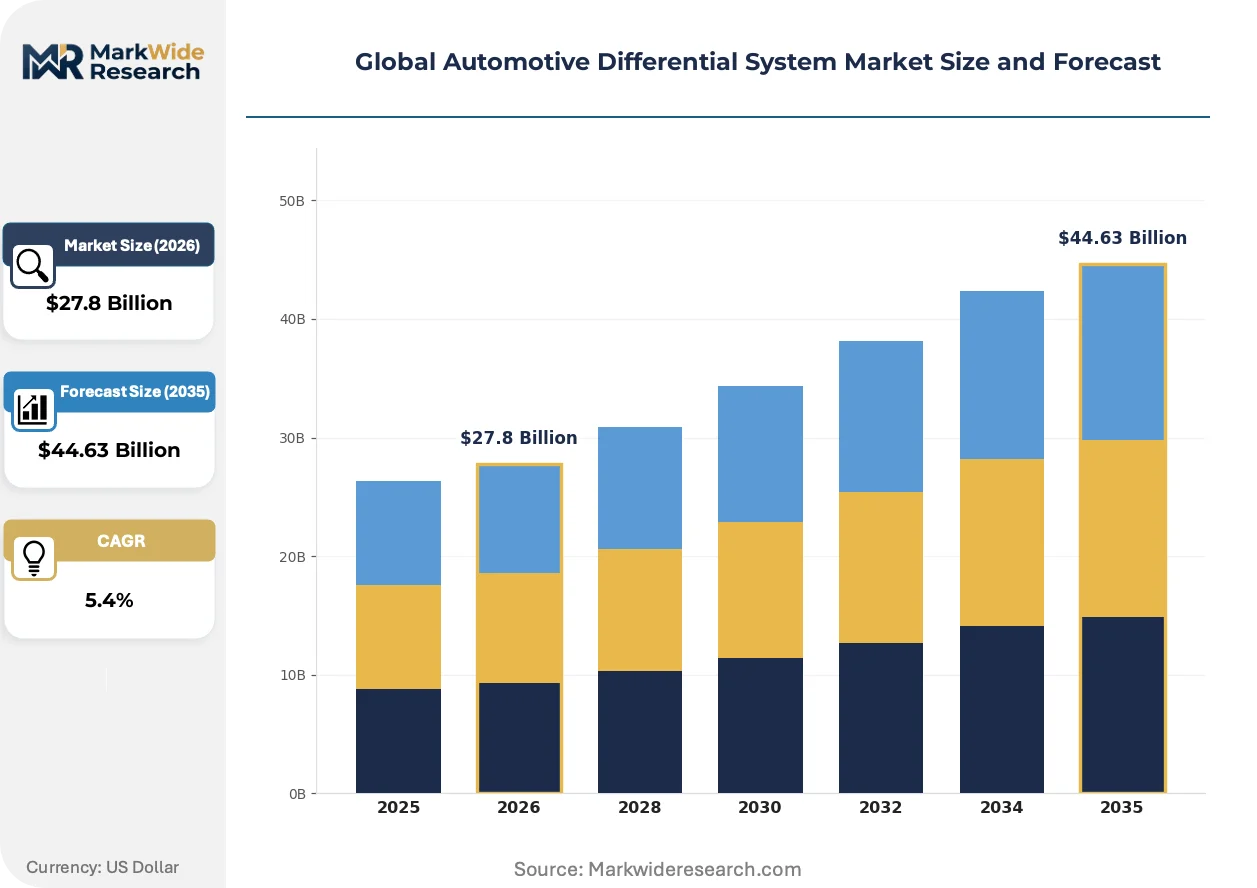
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $44.63 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Differential, Limited Slip Differential, Locking Differential, Torque Vectoring Differential Technology: Mechanical, Electro-Hydraulic, Electromagnetic, Electronic Control Vehicle Class: Passenger Cars, Light Commercial Vehicles, Heavy Duty Trucks, Off-Road Vehicles Distribution Channel: OEM, Aftermarket, Wholesalers, Authorized Dealers |
| Companies Covered | ZF Friedrichshafen AG, Eaton, Dana Limited, BorgWarner Inc., GKN Automotive Limited, American Axle & Manufacturing, Inc., JTEKT Corporation, Linamar Corporation, Schaeffler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Differential System Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from purely mechanical systems to software-enabled mechatronics. This transition prioritizes electronic control and system integration to meet new demands for efficiency and dynamic handling in both conventional and electric vehicles.
Torque vectoring technology, which dynamically allocates power to individual wheels for improved traction and cornering, is a key innovation. Originally confined to high-end sports cars, its adoption by premium electric vehicle manufacturers is accelerating its development. This technology is expanding into more mainstream passenger vehicle segments as electronic architectures become standard, enhancing safety and driveability for a broader consumer base.
China's dual carbon goals and its stringent GB standards for vehicle efficiency are forcing significant design changes. These national policies compel automakers to optimize every drivetrain component, including the differential, for minimal energy loss. Suppliers serving the Chinese market are most affected, facing pressure to accelerate R&D into lower-friction bearings, lightweight alloys, and more efficient gear geometries.
A strategic shift in component sourcing by automotive OEMs is altering the supplier landscape. Automakers are increasingly unbundling the differential system, moving from single-sourcing a complete assembly to multi-sourcing individual components like gears, housings, and control modules. This change, most visible among global OEMs, is intended to diversify supply chains and intensify cost competition among specialized Tier-2 and Tier-3 providers.
Global Automotive Differential System Market Segmentation
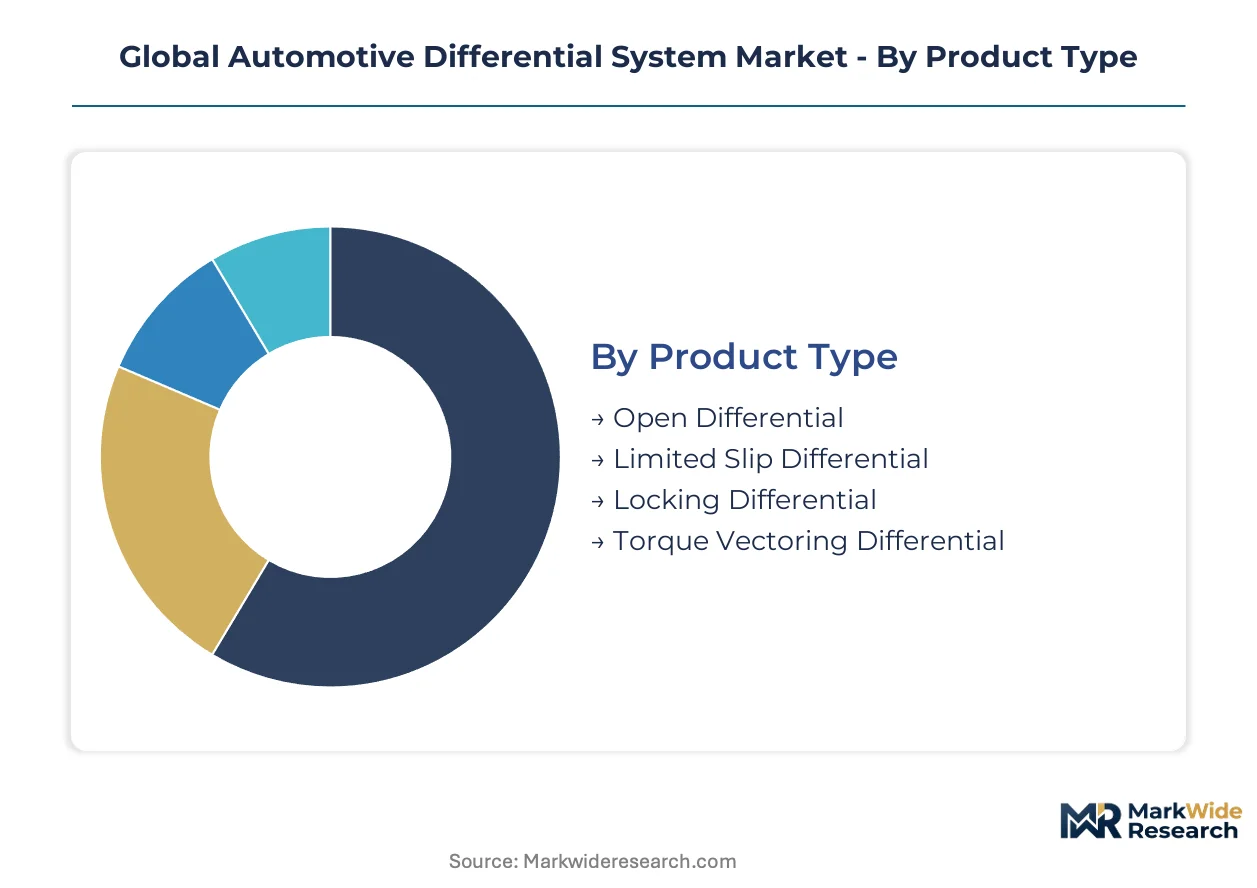
The automotive differential system market segments along critical dimensions, reflecting both technological evolution and diverse application needs. Understanding these distinctions allows stakeholders to identify specific demand pockets and align product development with emerging industry requirements.
Product Type:
The supply of automotive differential systems concentrates across distinct product types, each serving specific vehicle performance requirements.
- Open Differential:This standard mechanical unit allows wheels on the same axle to rotate at different speeds, primarily found in economy passenger cars for basic cornering functionality. Demand for open differentials remains high in cost-sensitive vehicle segments and emerging markets like India, driven by affordability.
- Torque Vectoring Differential:These advanced systems actively distribute torque between wheels for enhanced handling and stability, utilizing electronic controls for precise power allocation. Adoption is accelerating in premium electric vehicles and performance cars across Europe, driven by consumer desire for superior dynamic handling.
- Limited Slip Differential:This differential type restricts wheel slip by transferring power to the wheel with more traction, improving grip in varied conditions. It finds application in sports cars and certain light commercial vehicles.
- Locking Differential:Designed to provide maximum traction by mechanically locking both wheels on an axle to rotate at the same speed, this product type is essential for serious off-road vehicles.
Open Differential absorbs the bulk of installed capacity; Torque Vectoring Differential is expanding most quickly.
Technology:
Cost tiering significantly differentiates the various technologies underpinning automotive differential systems.
- Electronic Control:This technology relies on sophisticated software and sensors to manage differential functions, offering precise torque distribution and integration with vehicle stability systems. Its adoption is accelerating in electric vehicles globally, driven by the need for advanced powertrain management.
- Electro-Hydraulic:These systems combine hydraulic actuators with electronic control for robust and precise differential locking or limited-slip functions, often found in heavy-duty commercial vehicles. Demand is consistent in mining and construction equipment, where durability is paramount.
- Mechanical:Traditional gear-based systems that rely on physical mechanisms to allow differential wheel speeds, forming the foundation of most basic differentials. This technology remains prevalent in entry-level passenger cars.
- Electromagnetic:Utilizing electromagnetic clutches to control torque transfer, these systems offer quick response times and compact designs. They are increasingly used in all-wheel-drive passenger cars.
Mechanical systems represent the foundational technology; Electronic Control solutions are climbing the fastest.
Vehicle Class:
Application requirements dictate the functional specifications for differential systems across various vehicle classes.
- Passenger Cars:This segment encompasses a wide range of vehicles from compact sedans to luxury SUVs, requiring differentials that balance efficiency, comfort, and performance. The sheer volume of passenger car production, particularly in China, drives substantial demand for diverse differential types.
- Light Commercial Vehicles:These vehicles, including vans and pickup trucks, prioritize durability, payload capacity, and traction for diverse operational demands. Regulations like the US EPA's fuel economy standards pressure manufacturers to adopt more efficient differential designs for these vehicles.
- Heavy Duty Trucks:Designed for extreme loads and continuous operation, heavy-duty trucks require robust and reliable differential systems capable of enduring significant stress.
- Off-Road Vehicles:This class demands differentials with superior traction capabilities, often incorporating locking or limited-slip mechanisms for challenging terrains.
Passenger Cars drive the largest volume; Off-Road Vehicles are gaining share fastest.
Distribution Channel:
Customer type influences the procurement and delivery mechanisms for automotive differential systems.
- OEM:Original equipment manufacturers integrate differential systems directly into new vehicle production lines, requiring high-volume supply and stringent quality control standards. This channel forms the primary market for advanced e-axle components for electric vehicles.
- Aftermarket:This channel serves vehicle owners seeking replacement parts, repairs, or performance upgrades for their existing vehicles, encompassing a wide array of differential products. Enthusiast demand for high-performance locking differentials fuels this segment's growth in North America.
- Wholesalers:These intermediaries purchase differential components in bulk from manufacturers and distribute them to smaller repair shops, retailers, and other aftermarket players.
- Authorized Dealers:Dealerships sell and service specific vehicle brands, often sourcing genuine differential parts directly from the OEM or its designated suppliers for repairs and maintenance.
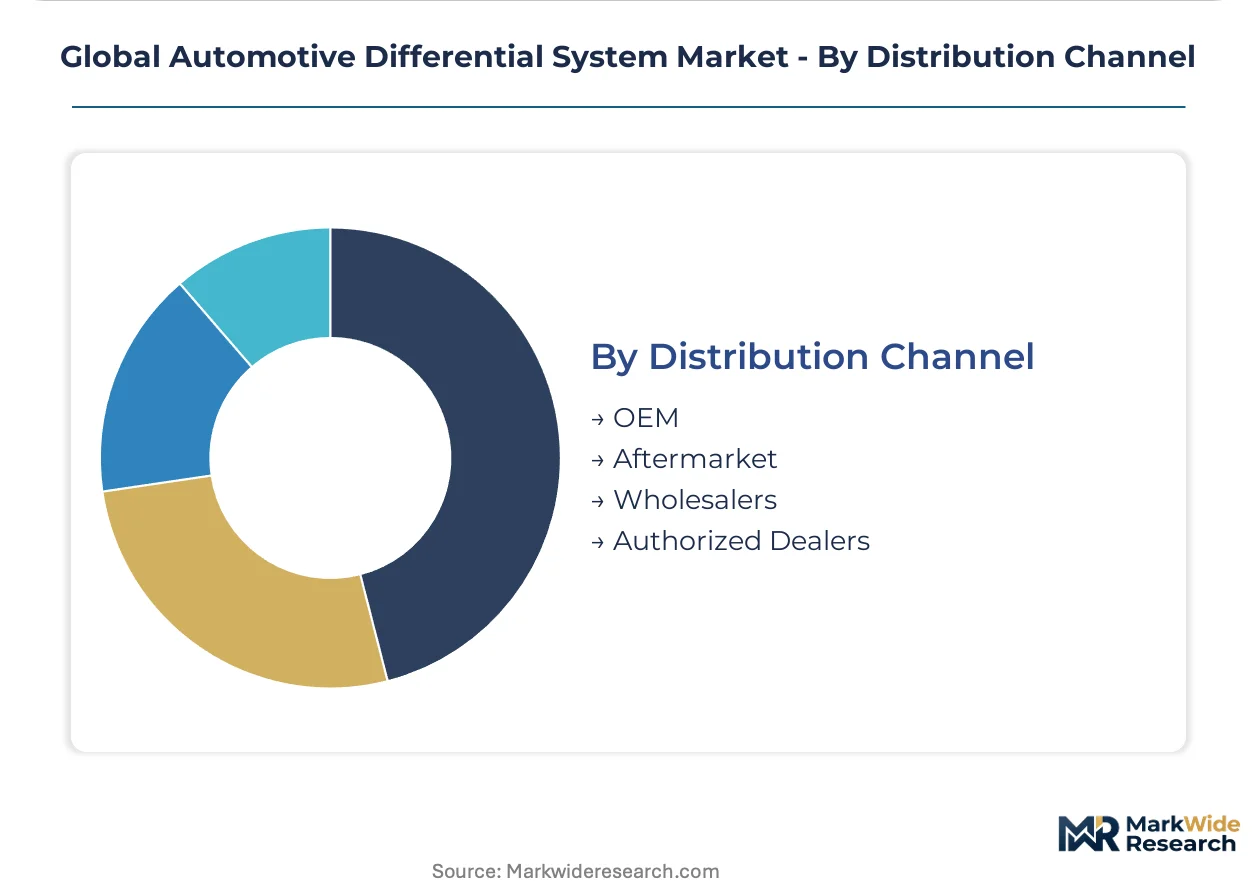
OEM channels account for the majority of new installations; Aftermarket sales show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive differential system market exhibits strong regional variations in demand and technological adoption. China's vast automotive manufacturing base anchors a significant portion of global demand for these systems. Regional regulations and consumer preferences heavily influence product type and technology deployment across key geographies.
China
China's substantial automotive manufacturing sector drives significant demand for diverse differential systems. The country's dual carbon goals and stringent GB standards compel automakers to optimize drivetrain components for energy efficiency. Shanghai's automotive industrial zone sees accelerated development of advanced e-axle components for local EV production.
Germany
German premium vehicle manufacturers create strong pull for torque vectoring and advanced electronic differentials. The EU's CO2 emissions targets pressure local OEMs to integrate lighter, lower-friction components into their vehicle architectures. Bavaria's automotive cluster focuses on R&D for integrated electronic units and high-performance differential solutions.
United States
United States demand for differential systems stems from its large light commercial vehicle market and robust performance aftermarket. US EPA's fuel economy standards push manufacturers towards more efficient differential designs for trucks and SUVs. Detroit's automotive hub remains central to the development and integration of advanced differential technologies.
Japan
Japanese automakers prioritize advanced differential technologies for both efficiency and dynamic handling in their diverse vehicle lineup. METI's vehicle efficiency initiatives encourage innovation in compact and responsive electromagnetic differential systems. Nagoya's automotive manufacturing region is a key center for developing next-generation drivetrain components.
India
India's market for automotive differential systems is characterized by high demand for open differentials in economy passenger cars. BIS standards for vehicle components guide local manufacturing practices and quality control for essential drivetrain parts. Chennai's automotive production belt serves as a significant base for cost-effective differential assembly and supply.
Global Automotive Differential System Market Key Industry Players
Strategic partnerships dominate the current landscape, reflecting the complex integration demands of modern differential systems. The market exhibits a tiered structure, with established Tier 1 suppliers competing against specialized technology developers and cost-focused component manufacturers. Archetypes include integrated e-drivetrain specialists, high-performance differential providers, and broad-portfolio component suppliers. Diversification of supply chains and technology licensing are key competitive moves shaping vendor relationships.
On the premium-tier vector, ZF Friedrichshafen AG exemplifies an integrated e-drivetrain specialist, leveraging its extensive expertise in complex electric vehicle systems and advanced mechatronics. Eaton, a US-based corporation, represents a provider focused on high-performance locking and limited-slip differentials, serving niche vehicle segments with specialized traction solutions. Dana Limited, another prominent US-based company, occupies a position as a broad-portfolio supplier for both light and commercial vehicle applications, adapting its offerings to diverse market demands and evolving powertrain architectures.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Eaton |
| Dana Limited |
| BorgWarner Inc. |
| GKN Automotive Limited |
| American Axle & Manufacturing, Inc. |
| JTEKT Corporation |
| Linamar Corporation |
| Schaeffler AG |
| Others |
Cost & Logistics Intelligence
Automotive OEMs' strategic shift towards multi-source component procurement directly influences pricing dynamics, intensifying competition among established differential system providers. This move diversifies supply chains and encourages more competitive bidding for large-volume contracts.
Pricing Analysis
Warranty and service bundling often differentiate premium differential systems, especially in the aftermarket. The dominant pricing structure for OEM contracts follows a long-term, negotiated offtake model, while the aftermarket operates on per-unit transactional pricing. Price differentiation stems from volume scale for OEMs and customization level for high-performance applications. Pricing pressure intensifies from global OEMs seeking cost efficiencies to meet US EPA fuel economy standards. Economy passenger car manufacturers exhibit the highest price sensitivity, contrasting with premium electric vehicle brands.
Supply Chain Analysis
Reverse logistics for differential systems, including remanufacturing and refurbishment, remains a niche but growing segment, primarily serving the aftermarket. Geographic supply concentration for differential components centers on China for volume manufacturing, Germany for advanced mechatronics, and Japan for precision engineering. Raw material dependencies include specialized gear steels, lightweight alloys, and semiconductor components for electronic control units. ECU supply bottlenecks present a significant structural risk. Distribution of new differential systems primarily occurs through OEM direct integration, with aftermarket sales flowing via wholesalers and authorized dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive differential system market is undergoing a profound technology-transition phase, with electronic control units and e-axles rapidly displacing traditional mechanical gear trains.
For Market Incumbents:
To counter the threat of new software-defined mechatronic systems, established players must accelerate investment in integrated e-axle development. Diversify supply chains for critical electronic control unit components to mitigate single-source vulnerabilities. Leverage existing manufacturing scale and OEM relationships to offer comprehensive e-drivetrain solutions. Focus R&D on advanced software integration for torque vectoring and ADAS compatibility.
For New Entrants and Emerging Players:
Underserved commercial EV e-axle segments represent a significant entry point for specialized innovators. Target niche high-performance aftermarket upgrades with advanced locking or torque vectoring differentials. Develop robust software platforms for differential control that can integrate seamlessly with diverse vehicle architectures. A go-to-market strategy focusing on modular, easily adaptable e-axle designs for electric trucks and buses can capture early market share.
For Investors and Strategic Acquirers:
Distressed-cycle entries favor specialized software developers in European and North American automotive clusters, offering opportunities to acquire critical control algorithm expertise. The long-term viability of the differential market is secured by the shift to electric vehicles and software-defined architectures. Target acquisition archetypes include firms specializing in advanced ECU design, torque vectoring software, or lightweight material innovations. Practitioners should monitor OEM investment in internal e-axle development for early signals of market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Integrated E-Axle Development | This initiative positions suppliers for the growing electric vehicle market by offering complete powertrain solutions. |
| Diversify ECU Component Sourcing | Mitigating supply chain risks ensures production continuity for advanced electronic differential systems. |
| Develop Advanced Torque Vectoring Software | Enhancing vehicle dynamics and safety creates a competitive advantage in premium and performance segments. |
| Target Commercial EV E-Axle Market | Capturing demand from the rapidly expanding electric truck and bus sector provides significant growth opportunities. |
| Form Strategic Partnerships with Software Specialists | Collaborations accelerate the integration of differential control with broader vehicle stability and ADAS systems. |
Research Approach
Vehicle production databases, regulatory body publications from the US EPA and EU Commission, and global patent databases formed the secondary backbone of this analysis. This foundational data was rigorously validated through primary interviews with OEM procurement managers, Tier 1 R&D leads, aftermarket distributors, and mechatronics engineers. The study employed a comprehensive approach, triangulating insights from both bottom-up market sizing and top-down industry validation.
The analytical lens utilized a bottom-up approach for market sizing, validated against top-down industry perspectives across the analysis window. This framework modeled the market across key segmentation dimensions including product type, technology, vehicle class, distribution channel, and regional adoption patterns. Compound annual growth rates were derived from historical trends and future projections, with EV adoption rates and regulatory emission targets serving as critical forecast inputs.
Revisions become necessary when significant geopolitical trade policies or rapid shifts in EV powertrain architectures materialize, impacting component availability or demand. Forecasts reflect assumptions regarding technological advancements and market acceptance of new differential systems. Practitioners should monitor semiconductor supply chain disruptions and evolving regional regulations for early signals of potential market shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Brake Shoe Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market
Automotive Parts
South Korea Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Forging Market
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
North America Automotive Foams Market
Automotive Parts
Germany Automotive Parts Zinc Die Casting Market
Automotive Parts
Mexico Automotive Actuators Market
Automotive Parts
South Korea Automotive Airfilters Market
Automotive Parts
Colombia Passenger Vehicles Lubricants Market
Automotive Parts
Car Rack Market
Automotive Parts
Car Phone Holder Market
Automotive Parts
Global Intelligent All-Wheel Drive System Market
Automotive Parts
Canada Automotive Parts Zinc Die Casting Market
Automotive Parts
Fluid Couplings Market