
 Torque Limiter Market | 2026-2036
Torque Limiter Market Size, Share, and Industry Trends Forecast 2026-2036
Torque Limiter Market Outlook
Composite polymer housings are repositioning product economics across the torque limiter category, cutting unit weight by half versus cast-iron alternatives while maintaining torsional rigidity. Rexnord Corporation leverages backward integration into precision-machined steel components to sustain margin control across North American distribution. Chr. Mayr GmbH + Co. KG anchors its competitive stance through specialized electromagnetic torque-limiting technology for servo-driven automation.
A torque limiter is a mechanical or electromechanical safety device engineered to disconnect or slip when transmitted torque exceeds a calibrated threshold, typically specified in Newton-meters with repeat accuracy within three percent of set value. Its primary industrial purpose is protecting capital equipment—gearboxes, conveyors, and servo axes—from catastrophic overload damage during jam events or collision scenarios. Mechanical torque limiters retain the largest installed base across heavy machinery, yet electronic torque limiters are capturing the fastest expansion as Industry 4.0 architectures demand real-time torque telemetry and predictive maintenance integration. Application demand in renewable energy, particularly wind turbine pitch and yaw drives, is deepening specification requirements for corrosion-resistant sealed units rated for twenty-year service intervals.
The EU Machinery Directive and ISO 13849 functional safety standards are mandating verified torque-limiting performance in Category 3 and 4 safety circuits, forcing redesigns of legacy mechanical-only product lines. OSHA lockout/tagout enforcement in United States metalworking and automotive plants is sustaining replacement demand for retrofittable torque-limiting clutch modules. Japan's METI energy-efficiency benchmarks for industrial motor systems are indirectly stimulating precision torque control adoption to minimize inertial losses. Stakeholders must monitor how converging functional-safety and energy-efficiency regulations will reshape certification requirements and supplier qualification timelines.
Market Dynamics
Conveyor systems in automated warehousing are accelerating specification intensity for torque limiters, while EU Machinery Directive compliance deadlines force redesigns of legacy mechanical-only product lines ahead of Category 3 and 4 safety circuit mandates.
Growth Catalysts
- EU Machinery Directive enforcement:Category 3 and 4 safety circuit mandates are compelling facility upgrades across metalworking and automotive plants, sustaining replacement demand for retrofittable torque-limiting clutch modules.
- Wind turbine pitch drives:Renewable energy operators are specifying corrosion-resistant sealed units rated for twenty-year service intervals, deepening technical requirements for offshore and onshore installations.
- German precision engineering clusters:Automotive OEM supply chains in Baden-Württemberg and Bavaria are driving specification intensity through integrated gearbox-torque limiter procurement protocols.
Market Restraints
- Alloy steel price volatility:Precision-machined steel component costs fluctuate with nickel and chromium spot markets, compressing margin control for manufacturers without backward integration into in-house production.
- Electronics supply concentration:Hall-effect sensors and signal conditioning chips for electronic torque limiters concentrate in Taiwanese and South Korean foundries, exposing lead time risk.
- Mechanical torque limiter displacement:Electronic alternatives with real-time telemetry are capturing specification share in servo-driven automation, eroding the installed base of ball-detent and shear-pin designs.
Strategic Opportunities
- India warehousing automation:PLI scheme incentives for logistics infrastructure are accelerating conveyor system deployments where torque limiter specification remains underpenetrated relative to Western adoption rates.
- ISO 13849-1 certification convergence:Functional safety standard harmonization across EU member states is creating a unified qualification pathway for suppliers able to demonstrate verified torque-limiting performance.
- Electromagnetic-servo convergence:Integration of electromagnetic torque-limiting technology with predictive maintenance platforms is opening white space in Industry 4.0 architectures demanding real-time overload telemetry.
Industry Challenges
- Functional safety engineering talent:Shortage of engineers proficient in ISO 13849-1 Category 3/4 validation is extending supplier qualification timelines and delaying product certification cycles.
- Legacy system integration friction:Retrofitting torque limiters into existing gearbox assemblies requires custom adapter fabrication, complicating aftermarket deployment in brownfield industrial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Torque Limiter Market |
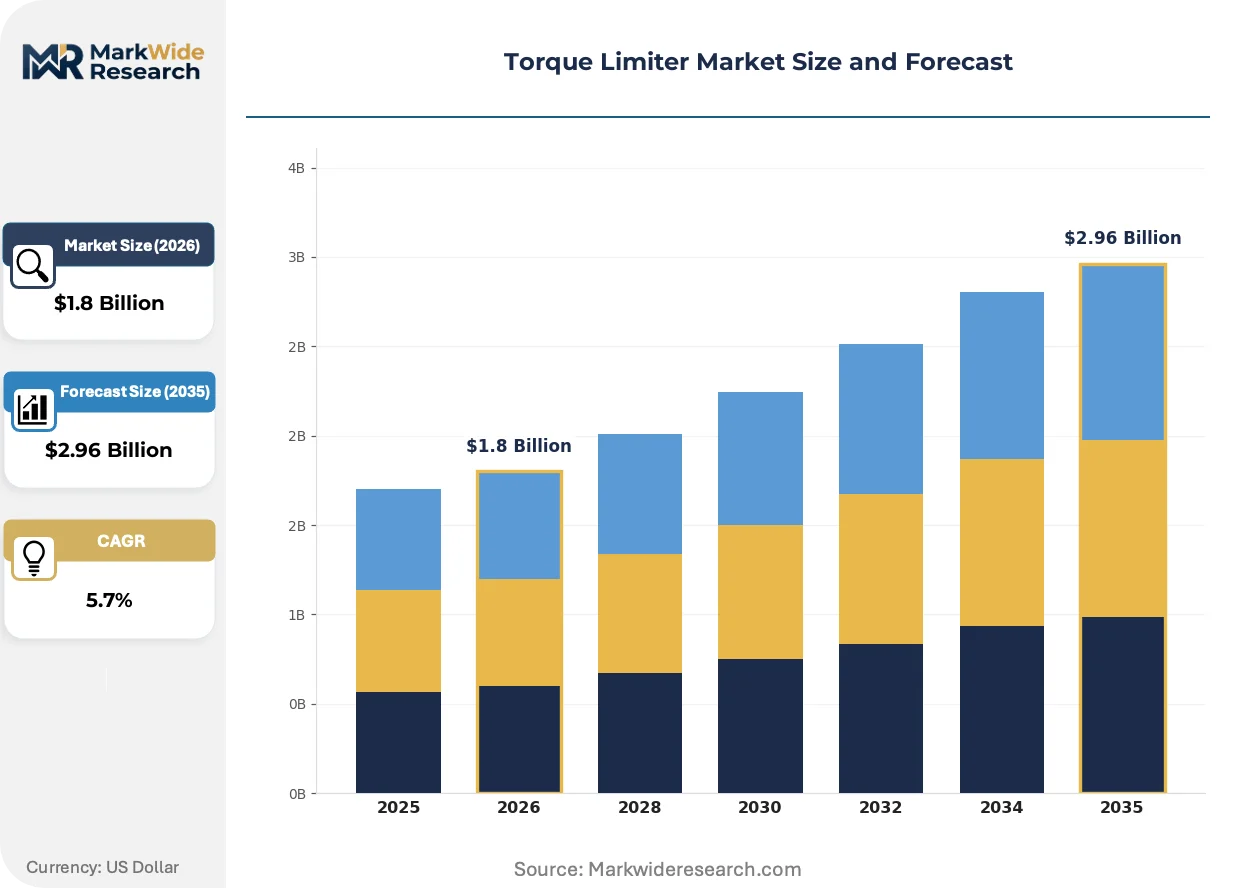
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Torque Limiters, Electronic Torque Limiters, Slip Torque Limiters, Adjustable Torque Limiters Application: Industrial Machinery, Automotive, Conveyor Systems, Renewable Energy End User: Manufacturers, OEMs, Maintenance Providers, Repair Shops Installation: Inline Installation, Parallel Installation, Modular Installation, Standard Installation |
| Companies Covered | Rexnord Corporation, Regal Rexnord Corporation, Chr. Mayr GmbH + Co. KG, KTR Systems GmbH, Nexen Group, Inc., Altra Industrial Motion, Tsubakimoto Chain Co., MIKI PULLEY CO., LTD., Ringfeder Power Transmission, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Torque Limiter Market Strategic Shifts
Composite polymer housings and electromagnetic actuation architectures are actively repositioning product economics and performance benchmarks across mechanical overload protection systems.
Composite polymer formulations reinforced with glass fiber are decentralizing the traditional cast-iron housing supply chain by cutting unit weight by half while maintaining torsional rigidity. Material handling OEMs in automated warehousing are specifying these housings for high-cycle conveyor applications. This shift is decentralizing sourcing patterns away from foundry-dependent suppliers toward polymer compounders with injection molding capacity.
REACH restrictions on per- and polyfluoroalkyl substances are compelling seal material reformulations for corrosion-resistant torque limiters in wind turbine pitch drives. European manufacturers are qualifying hydrogenated nitrile rubber alternatives to maintain twenty-year service interval ratings. Offshore wind projects in the North Sea and Baltic are most affected, with developers demanding pre-certified seal packages to avoid installation delays.
Buyer consolidation among warehouse automation integrators is compressing switching cycles and unbundling after-sales service from hardware procurement. Large system integrators are standardizing on preferred torque limiter specifications across multi-site deployments. This pattern is most visible in German automotive supplier parks and Benelux distribution hubs, where procurement teams negotiate framework agreements covering predictive maintenance subscriptions alongside component supply.
Torque Limiter Market Segmentation
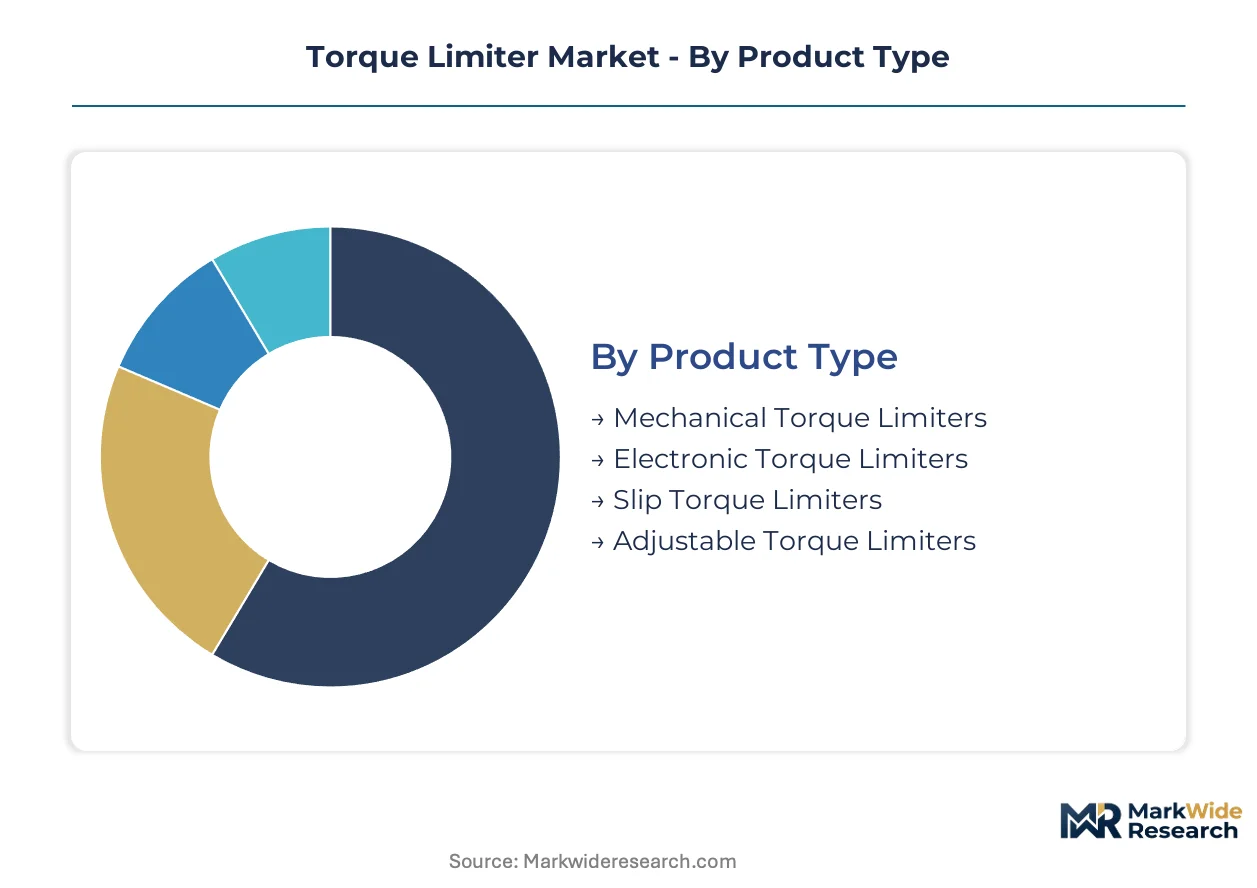
Torque limiter procurement patterns diverge sharply across product architectures, installation geometries, and buyer sophistication levels. Specification intensity varies from commodity replacement cycles in mechanical designs to embedded safety-system integration in electronic variants.
Product Type:
Buyer differentiation in this category tracks safety certification requirements and telemetry integration needs rather than unit cost alone.
- Mechanical Torque Limiters:Ball-detent, shear-pin, and friction-plate architectures dominate heavy machinery with calibrated slip thresholds and repeat accuracy within three percent. German automotive OEM supply chains in Baden-Württemberg specify these for integrated gearbox protection, though specification share erodes in servo-driven automation where electronic alternatives penetrate.
- Electronic Torque Limiters:Hall-effect sensor arrays with real-time torque telemetry and predictive maintenance integration are capturing specification share in Industry 4.0 architectures. Wind turbine pitch drive operators in the North Sea and Baltic demand corrosion-resistant sealed variants rated for twenty-year service intervals, deepening technical requirements beyond mechanical alternatives.
- Slip Torque Limiters:Continuous-slip designs maintain drive engagement during overload events, finding application in material handling where jam recovery without full disconnection matters.
- Adjustable Torque Limiters:Field-calibrated units serve maintenance providers and repair shops requiring rapid threshold modification across heterogeneous equipment fleets.
Volume sits with mechanical designs; growth tilts toward electronic architectures.
Application:
End-use concentration follows capital equipment renewal cycles and regulatory compliance deadlines rather than greenfield expansion rates.
- Industrial Machinery:Metalworking and automotive plants under OSHA lockout/tagout enforcement sustain replacement demand for retrofittable clutch modules. Brownfield integration friction complicates aftermarket deployment where custom adapter fabrication extends lead times.
- Conveyor Systems:Automated warehousing deployments in Benelux distribution hubs and German supplier parks are accelerating specification intensity. Large system integrators standardize on preferred torque limiter specifications across multi-site deployments, compressing switching cycles.
- Automotive:Precision engineering clusters drive integrated gearbox-torque limiter procurement protocols through OEM supply chain mandates.
- Renewable Energy:Offshore wind projects demand pre-certified seal packages to avoid installation delays, with REACH restrictions on per- and polyfluoroalkyl substances compelling hydrogenated nitrile rubber reformulations.
Industrial machinery commands installed base scale; conveyor systems exhibit the steepest expansion trajectory.
End User:
Procurement authority in this category fragments between original equipment specification and aftermarket service capture.
- Manufacturers:In-house production of precision-machined steel components sustains margin control for integrated gearbox-torque limiter assemblies.
- OEMs:Framework agreements covering predictive maintenance subscriptions alongside component supply are consolidating in German automotive supplier parks.
- Maintenance Providers:Field-calibrated adjustable torque limiters serve heterogeneous equipment fleets requiring rapid threshold modification.
- Repair Shops:Retrofit demand concentrates where legacy mechanical-only product lines face EU Machinery Directive Category 3 and 4 compliance deadlines.
Specification authority rests with OEMs; aftermarket revenue pools concentrate with maintenance providers.
Installation:
Physical integration geometry determines supply chain configuration and field service requirements.
- Inline Installation:Direct shaft-to-shaft mounting dominates new equipment specification where space constraints permit.
- Parallel Installation:Offset shaft arrangements serve retrofit applications in brownfield facilities with legacy gearbox assemblies.
- Modular Installation:Adapter-based systems reduce custom fabrication requirements for heterogeneous equipment fleets.
- Standard Installation:Conventional mounting patterns retain volume in cost-sensitive replacement cycles.
Inline designs anchor new equipment specification; modular formats gain traction in retrofit-intensive aftermarket channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Baden-Württemberg and Bavaria concentrate precision engineering capacity for integrated gearbox-torque limiter assemblies. Tax incentives for automotive supply chain localization in these zones accelerate specification intensity among Tier-1 suppliers.
Germany
Automotive OEM supply chains in Stuttgart and Munich drive procurement protocols for Category 3 safety circuits under EU Machinery Directive mandates. ECHA REACH restrictions on PFAS compounds compel seal material reformulations for corrosion-resistant units. Offshore wind developers in the North Sea demand pre-certified hydrogenated nitrile rubber packages to avoid installation delays.
United States
OSHA lockout/tagout enforcement in Michigan and Ohio metalworking plants sustains replacement demand for retrofittable clutch modules. The Inflation Reduction Act's clean energy manufacturing credits stimulate wind turbine component localization. Precision-machined steel backward integration clusters in Wisconsin and Illinois sustain margin control for domestic fabricators.
China
MIIT industrial motor efficiency benchmarks indirectly stimulate precision torque control adoption to minimize inertial losses. Dual carbon goals accelerate renewable energy deployment in Jiangsu and Guangdong provinces. Yangtze River Delta warehousing automation integrators standardize on preferred torque limiter specifications across multi-site deployments.
Japan
METI energy-efficiency standards for industrial motor systems drive servo-driven automation specification. JIS-certified functional safety engineers concentrate in Nagoya and Osaka precision engineering clusters. Hall-effect sensor supply concentration in Taiwanese foundries exposes Japanese electronic torque limiter assemblers to lead time risk.
India
PLI scheme incentives for logistics infrastructure accelerate conveyor system deployments in Maharashtra and Karnataka. BIS safety standard harmonization lags EU Machinery Directive adoption, creating specification gaps in warehousing automation. Mumbai-Pune industrial corridor maintenance providers field-calibrate adjustable units for heterogeneous equipment fleets.
Torque Limiter Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated gearbox OEMs capturing specification authority while aftermarket service pools concentrate with independent maintenance networks. The vendor base organizes around three archetypes: precision-machined steel specialists with backward integration into component production, electromagnetic technology developers serving servo-driven automation, and polymer housing compounders with injection molding capacity. Dominant competitive moves include strategic partnerships with warehouse automation integrators and geographic expansion into Indian logistics infrastructure zones.
Within the electromagnetic-specialist tier, Chr. Mayr GmbH + Co. KG and KTR Systems GmbH occupy positions defined by German functional safety engineering concentration. Among scale-driven fabricators with precision steel capability, Rexnord Corporation and Regal Rexnord Corporation exemplify North American backward integration patterns. Japanese precision component developers Tsubakimoto Chain Co. and MIKI PULLEY CO., LTD. represent the servo-automation supply chain concentration in Nagoya and Osaka industrial corridors.
| Leading Market Players |
|---|
| Rexnord Corporation |
| Regal Rexnord Corporation |
| Chr. Mayr GmbH + Co. KG |
| KTR Systems GmbH |
| Nexen Group, Inc. |
| Altra Industrial Motion |
| Tsubakimoto Chain Co. |
| MIKI PULLEY CO., LTD. |
| Ringfeder Power Transmission |
| Others |
Value Chain & Pricing Dynamics
Alloy steel input costs trace from nickel and chromium spot markets through three-tier pricing structures across premium, standard, and economy levels, with precision-machined component fabricators in Wisconsin and Illinois commanding margin premiums through captive supply of steel components while polymer compounders with injection molding capacity undercut foundry-dependent rivals on unit weight.
Pricing Analysis
Short lead-time premiums separate expedited electronic torque limiter deliveries from standard mechanical unit availability, with pricing stratifying across ISO 13849-1 certification tiers, volume scale commitments, and predictive maintenance subscription bundling. Cost compression in economy mechanical tiers intensifies because alloy steel price volatility compresses fabricators without backward integration. Maintenance providers exhibit highest price sensitivity due to heterogeneous fleet retrofit requirements, while wind turbine OEMs accept premium positioning for twenty-year service interval ratings.
Supply Chain Analysis
Domestic-content mandates under the Inflation Reduction Act's clean energy manufacturing credits are reshaping sourcing patterns for wind turbine component localization, drawing precision-machined steel supply from Germany, the United States, and Japan. Hall-effect sensors and signal conditioning chips feed from Taiwanese and South Korean foundries. Single-source vulnerability concentrates in semiconductor inputs for electronic torque limiter architectures. Distribution runs through warehouse automation integrators negotiating framework agreements across multi-site deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over precision-machined steel component supply and electromagnetic torque-limiting technology development determines margin sustainability across safety-critical specification tiers.
For Market Incumbents: Anchor competitive position through certification investment in ISO 13849-1 Category 3 and 4 validation capabilities, defending against electronic torque limiter displacement of mechanical installed bases by deepening backward integration into polymer housing compounders with injection molding capacity.
For New Entrants and Emerging Players: Maintenance providers in India's Mumbai-Pune industrial corridor represent the most penetrable buyer archetype, with field-calibrated adjustable torque limiter demand outpacing local supply capacity; penetrate through BIS safety standard harmonization partnerships that bridge specification gaps against EU Machinery Directive adoption lags.
For Investors and Strategic Acquirers: Consolidation of warehouse automation integrator procurement authority is the leading indicator that aftermarket service revenue pools will concentrate with predictive maintenance platform owners; target electromagnetic-specialist developers with servo-driven automation integration capabilities as acquisition candidates, watching for framework agreement announcements covering predictive maintenance subscriptions alongside component supply as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Steel Components | Captive supply of nickel-alloy machined parts insulates margin control from spot market volatility. |
| ISO 13849-1 Category 3/4 Certification Investment | Verified functional safety performance unlocks EU Machinery Directive compliance-driven replacement cycles. |
| Predictive Maintenance Platform Integration | Real-time torque telemetry bundling captures recurring revenue from warehouse automation integrators. |
| Polymer Housing Compounder Acquisition | Injection molding capacity decentralizes sourcing away from foundry-dependent cast-iron supply chains. |
| India Logistics Infrastructure Partnership | PLI scheme-aligned conveyor system deployments access underpenetrated specification growth corridors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews involving maintenance directors at automotive plants, OEM procurement teams in Baden-Württemberg, aftermarket service heads, plant engineers specifying conveyor systems, and electromagnetic technology developers. Bottom-up and top-down approaches reconciled volume estimates against EU Machinery Directive compliance timelines and wind turbine pitch drive installation schedules.
Granularity-level modeling captured product type splits across mechanical, electronic, slip, and adjustable architectures; application segmentation across industrial machinery, conveyor systems, automotive, and renewable energy; and end-user differentiation among manufacturers, OEMs, maintenance providers, and repair shops. CAGRs derived from regression analysis of specification intensity trends and regulatory compliance deadline clustering, incorporating alloy steel price indices and Hall-effect sensor lead time fluctuations as industry-specific inputs across the projection horizon.
Revisions become necessary when REACH restrictions expand beyond PFAS compounds to additional seal materials, when semiconductor supply concentration shifts, or when BIS safety standard harmonization accelerates in India. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Japan Electro Hydraulic Power Steering Market
Powertrain
Automotive Fuel Injection Pump Market
Powertrain
France Automotive Engine Oils Market
Powertrain
Diesel Engine Management System Market
Powertrain
Automotive Fuel Feed Pumps Market
Powertrain
Automotive Clutch Slave Cylinder Market
Powertrain
Automotive Drivetrain Market
Powertrain
North America Automotive Engine Oils Market
Powertrain
Automotive Oil Sump Market
Powertrain
Automotive Cylinder Block Market
Powertrain
Engine Support Bar Market
Powertrain
Gear Oil Market
Powertrain
Industrial Diesel Turbocharger Market
Powertrain
Global Industrial Brakes and Clutches Market
Powertrain
Global Powertrain Market
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market