
 Diesel Engine Management System Market | 2026-2036
Diesel Engine Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Diesel Engine Management System Market Outlook
The EU Green Deal's 55% emissions reduction target for 2030 is realigning procurement criteria across European commercial vehicle OEMs. Robert Bosch GmbH leverages its vertically integrated sensor-to-software stack to dominate common rail system supply. Continental AG anchors its position through R&D intensity in powertrain electrification interfaces. Denso Corporation competes on manufacturing scale across Asian truck and bus platforms.
A diesel engine management system integrates electronic control units, fuel injection hardware, exhaust after-treatment actuators, and sensor arrays to optimize combustion timing, air-fuel ratio, and emissions output in compression-ignition engines. The architecture typically processes crankshaft position data at sub-millisecond resolution while modulating piezoelectric injector dwell within microsecond tolerances to meet NOx and particulate thresholds. ECU and sensor assemblies command the largest value share within the component dimension, reflecting firmware complexity and multi-parameter calibration requirements. Common rail technology leads the technology split due to its pressure-flexibility for varying load cycles, while exhaust gas recirculation systems represent the fastest-growing category as manufacturers integrate cooled EGR with selective catalytic reduction to satisfy Euro VII and EPA Phase 2 standards.
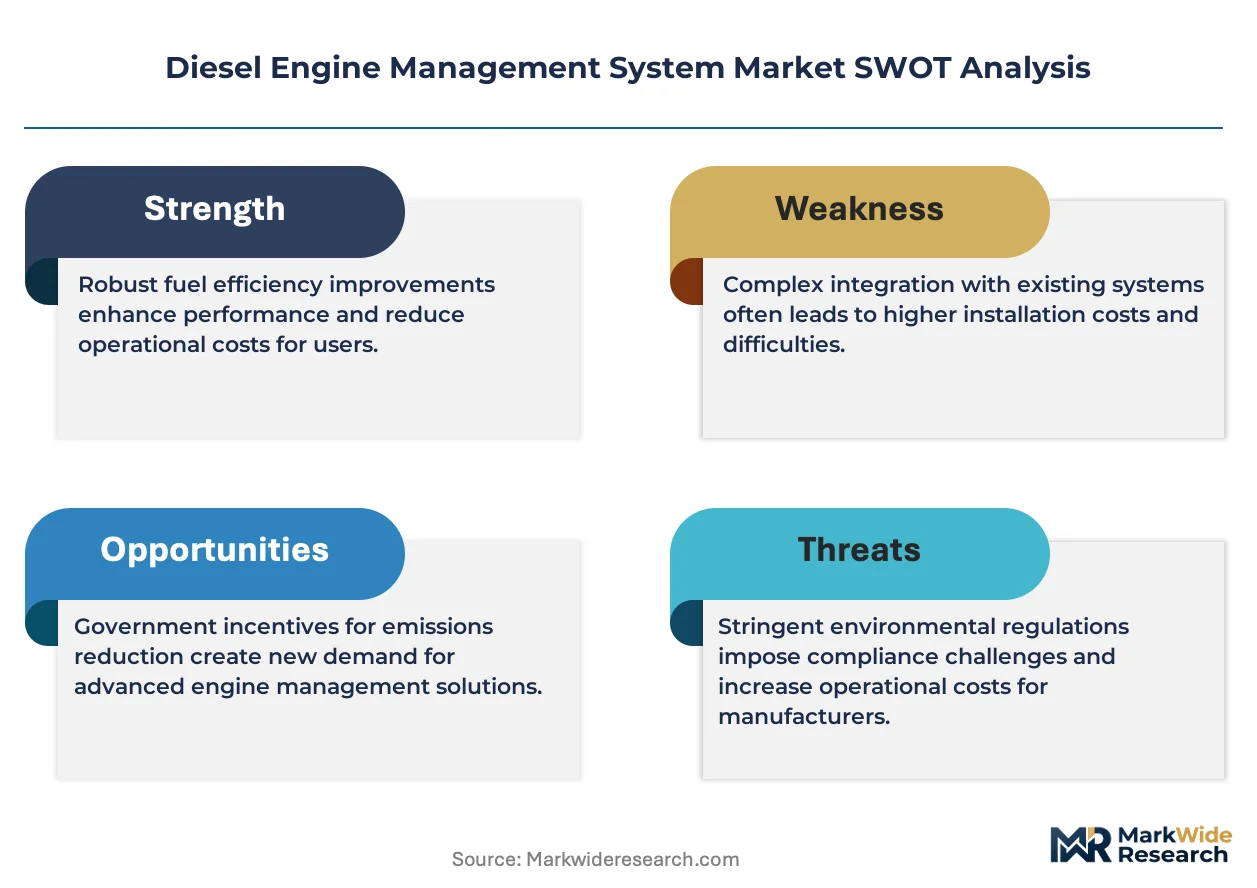
EPA Phase 2 greenhouse gas rules and the EU F-Gas Regulation constrain refrigerant and insulation choices in engine bay thermal management, while India's BIS emission norms and China's MIIT fuel consumption standards dictate product validation protocols for regional market entry. Compliance documentation now spans multi-jurisdiction type approval, creating fixed cost barriers for component suppliers without certified test facilities. Stakeholders must monitor regulatory divergence between European CO2-based frameworks and North American NOx-focused enforcement to anticipate engineering resource allocation and platform redesign cycles.
Market Dynamics
Common rail direct injection technology is converging with electrified powertrain interfaces, forcing incumbent suppliers to recalibrate hardware-software architectures for hybrid diesel platforms while emissions enforcement tightens across multiple jurisdictions.
Growth Catalysts
- EPA Phase 2 GHG Standards:US commercial fleets face mandatory CO2 reduction timelines, accelerating replacement cycles for pre-2010 engine management hardware and opening retrofit demand channels.
- India BIS VI Implementation:Domestic truck and bus OEMs require upgraded ECU calibration and after-treatment integration, expanding addressable market for certified system suppliers.
- Closed-loop combustion feedback:Cylinder pressure sensors enable real-time injection timing adjustments, delivering NOx compliance margins without fuel economy penalties.
Market Restraints
- Piezoelectric actuator supply concentration:Precision injector component manufacturing clusters in Germany and Japan, creating single-source vulnerability for tier-two assemblers.
- Platinum group metal cost volatility:Diesel oxidation catalyst formulations depend on palladium and platinum spot markets, compressing margin predictability for exhaust after-treatment suppliers.
- Battery-electric substitution in urban bus:Transit authority procurement in China and Europe is pivoting to full-electric platforms, eliminating diesel engine management content from this end-use vertical.
Strategic Opportunities
- Brazil ANVISA commercial vehicle renewal:Stricter emission enforcement in Mercosur markets creates first-mover advantage for common rail system providers with local assembly partnerships.
- Predictive maintenance analytics:ECU-embedded machine learning models enable fleet operators to optimize injector replacement intervals, creating recurring software revenue streams.
- EU F-Gas Regulation thermal management:Low-global-warming-potential refrigerant mandates require redesigned engine bay packaging, opening engineering service contracts for system integrators.
Industry Challenges
- Embedded firmware talent scarcity:Real-time control algorithm development requires specialized automotive software engineers, with competition intensifying from autonomous vehicle and battery management sectors.
- Multi-jurisdiction type approval complexity:Simultaneous EPA, EU Green Deal, and China MIIT certification timelines strain validation facility capacity and extend product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diesel Engine Management System Market |
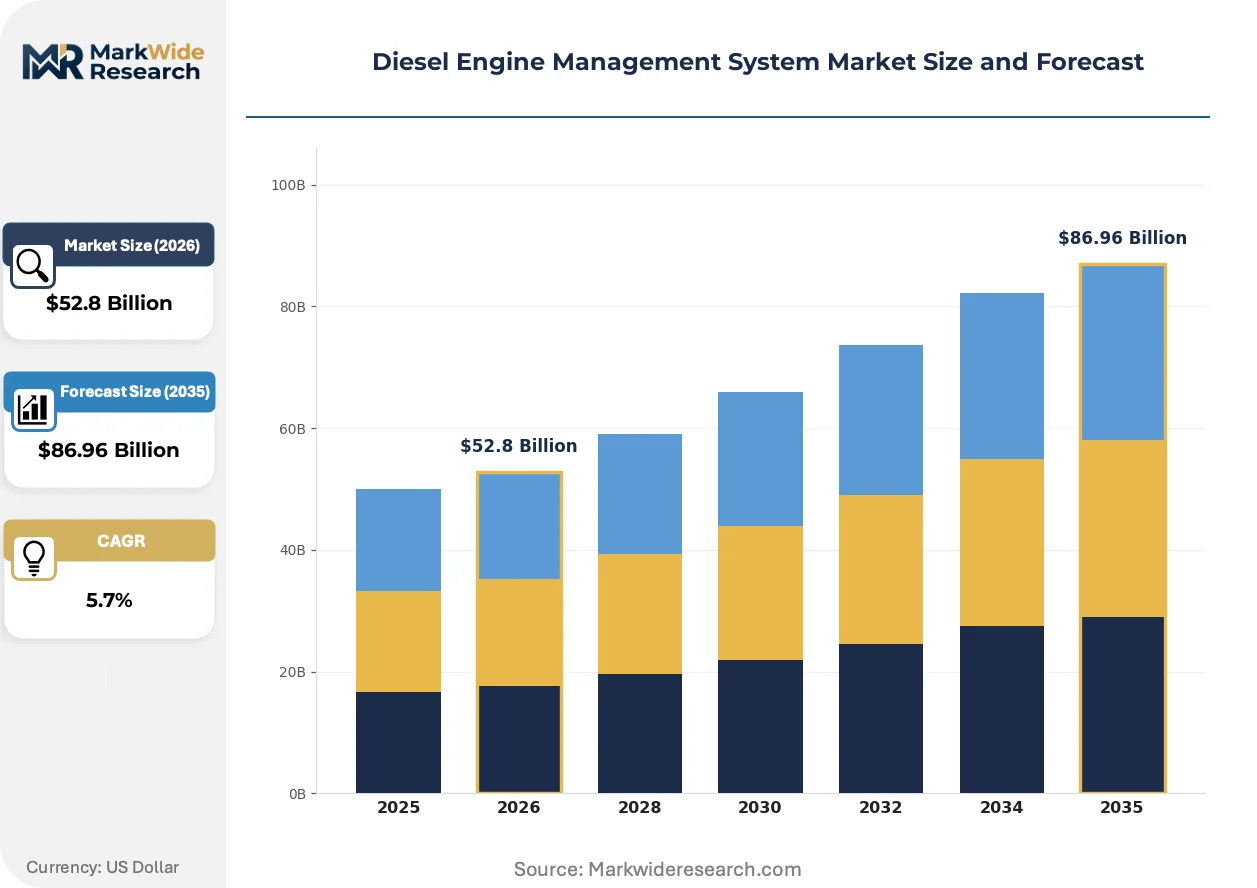
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $86.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: ECU, Sensors, Actuators, Fuel Pumps Technology: Common Rail, Turbocharged, Exhaust Gas Recirculation, Direct Injection Application: Commercial Vehicles, Agricultural Equipment, Marine, Construction Machinery Engine Type: Inline, V-Type, Opposed, Rotary |
| Companies Covered | Robert Bosch GmbH, Continental AG, Delphi Technologies, Denso Corporation, BorgWarner Inc., Infineon Technologies, Hella KGaA Hueck & Co., NGK Spark Plug, Hitachi Automotive Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diesel Engine Management System Market Strategic Shifts
Electrification interfaces are rewriting diesel engine management specifications, as hybrid architectures demand seamless torque coordination between compression-ignition engines and electric motors while software-defined vehicle platforms accelerate over-the-air calibration updates.
Model-based development toolchains are converging with hardware-in-the-loop validation environments, compressing ECU firmware release cycles from 18 months to under 9 months for tier-one suppliers. European and North American commercial vehicle OEMs now mandate virtual calibration prior to physical prototype builds, reducing late-stage engineering change orders. This acceleration is converging with cloud-based fleet data platforms, enabling continuous emission compliance monitoring that extends system supplier accountability beyond point-of-sale.
The EU Green Deal's 55% emissions reduction target is tightening Euro VII draft specifications, forcing manufacturers to integrate cooled exhaust gas recirculation with selective catalytic reduction in single after-treatment modules. Engine management suppliers must now coordinate thermal management across combustion, EGR, and SCR domains within unified control strategies. Heavy-duty truck platforms in Germany, France, and Italy face the steepest engineering resource demands as these integrated architectures enter validation.
Fleet operators are consolidating supplier relationships around full powertrain system integrators capable of warrantying engine, transmission, and after-treatment as unified packages. This concentration is displacing component-level procurement for engine management units, favoring suppliers with captive injection, turbocharging, and emission control capabilities. The shift is most visible in US Class 8 truck segments where total cost of ownership contracts now span 500,000-mile service intervals.
Diesel Engine Management System Market Segmentation
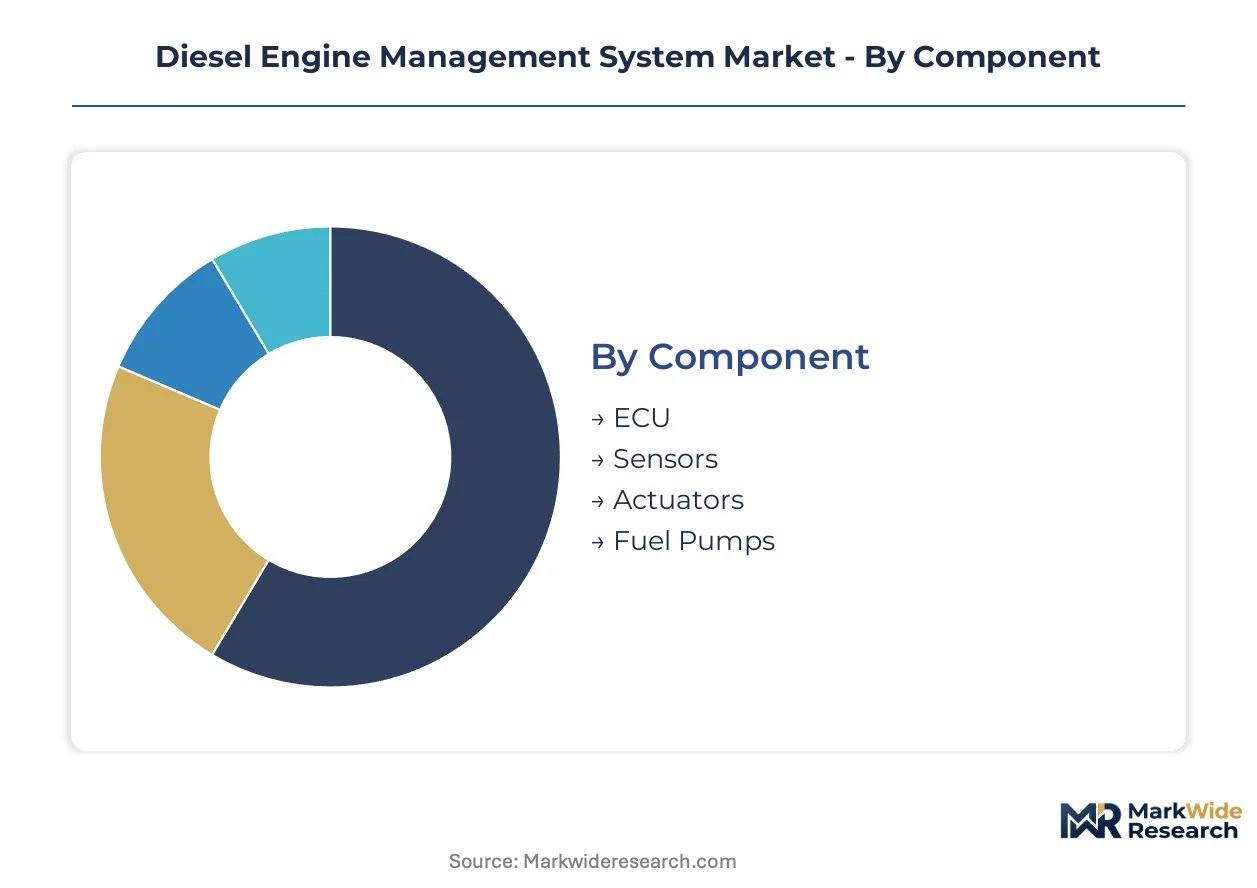
Engine management procurement cycles vary sharply across component tiers and technology generations, with EPA Tier 4 retrofit mandates and Euro VII pre-buy activity creating asynchronous replacement waves across fleet segments. Understanding these segment-specific upgrade rhythms enables suppliers to align production capacity with verified demand windows rather than aggregate market signals.
Component:
Replacement intensity concentrates in electronic control modules and sensor arrays as commercial fleets face mandatory firmware upgrades to satisfy evolving emissions protocols.
- ECU:Embedded control modules integrate real-time combustion algorithms with after-treatment coordination, processing crankshaft position data at sub-millisecond resolution. Demand clusters in German and US Class 8 truck platforms where Euro VII and EPA Phase 2 calibration complexity drives unit value. ECU procurement accelerates where fleet operators consolidate around single-source powertrain integrators.
- Sensors:Cylinder pressure, crankshaft position, and exhaust gas temperature arrays feed closed-loop combustion feedback systems. Agricultural equipment OEMs in the US Midwest and German commercial vehicle manufacturers anchor regional demand as precision agriculture and emissions enforcement tighten tolerance requirements simultaneously.
- Actuators:Piezoelectric injector drivers and EGR valve positioners modulate hardware states within microsecond tolerances.
- Fuel Pumps:High-pressure common rail supply modules deliver pressure-flexibility across variable load cycles.
ECU sits at the top of the volume ranking, with Sensors climbing the fastest.
Technology:
Cost tier differentiation separates premium common rail architectures from legacy mechanical systems as developing markets enforce emission parity with mature regulatory regimes.
- Common Rail:Accumulator-type fuel distribution enables pressure-decoupled injection timing, delivering NOx compliance without fuel economy penalties across transient load profiles. Chinese heavy-duty truck manufacturers and Indian commercial vehicle OEMs drive procurement volume as BIS VI and China VI standards displace pump-line-nozzle legacy hardware.
- Exhaust Gas Recirculation:Cooled EGR systems reduce combustion temperatures to suppress NOx formation upstream of after-treatment. European heavy-duty platforms in Germany, France, and Italy integrate EGR with selective catalytic reduction as Euro VII draft specifications mandate combined thermal management strategies.
- Turbocharged:Variable geometry turbochargers optimize air-fuel ratios across altitude and load variations.
- Direct Injection:Precision spray-guided combustion architectures improve thermal efficiency in medium-duty applications.
Common Rail commands the largest installed base, while Exhaust Gas Recirculation expands most quickly as integrated after-treatment architectures proliferate.
Application:
Customer type fragmentation separates fleet-scale procurement from owner-operator replacement patterns, with commercial vehicle aggregators consolidating supplier relationships around full-system integrators.
- Commercial Vehicles:Class 8 trucks and transit buses require coordinated engine-transmission-after-treatment warranty packages spanning 500,000-mile service intervals. US fleet operators and European logistics companies drive consolidation toward captive injection and turbocharging suppliers capable of unified powertrain accountability.
- Construction Machinery:Non-road mobile machinery faces Stage V emissions enforcement in Europe and Tier 4 Final requirements in North America, forcing excavator and loader OEMs to source integrated engine management systems with validated cold-start performance across altitude extremes.
- Agricultural Equipment:Combine harvesters and tractors demand ruggedized sensor packaging for dust-intensive operating environments.
- Marine:Commercial vessel propulsion systems face IMO Tier III NOx limits in emission control areas.
Commercial Vehicles dominates procurement volume, with Construction Machinery gaining share fastest as non-road emission enforcement tightens globally.
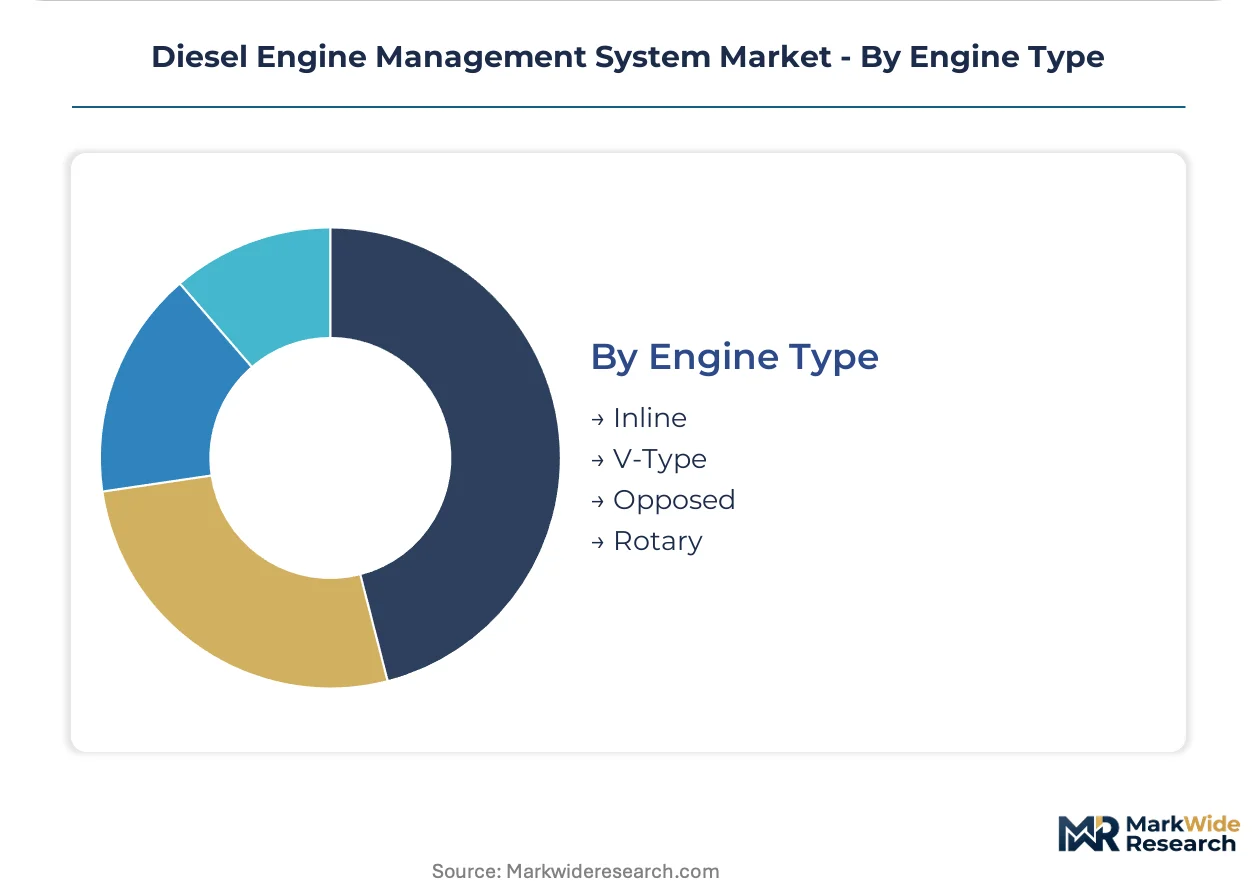
Engine Type:
Supply concentration in inline and V-type architectures reflects manufacturing scale advantages and aftermarket service network density.
- Inline:Straight-cylinder configurations dominate medium-duty commercial and agricultural applications where packaging constraints and service accessibility prioritize longitudinal engine bay layouts. German and Japanese OEMs anchor production networks with standardized bore-spacing platforms enabling component commonality across displacement variants.
- V-Type:Compact cylinder bank angles deliver power density for heavy-duty trucking and marine propulsion where torque-per-liter metrics drive competitive positioning. US Class 8 manufacturers specify V8 and V12 architectures for long-haul routes with steep grade profiles.
- Opposed:Horizontal cylinder arrangements suit specialized marine and stationary generator applications.
- Rotary:Wankel-derived compression-ignition concepts occupy niche aerospace and range-extender hybrid prototypes.
Inline configurations lead production volume, with V-Type architectures showing the steepest expansion trajectory in heavy-duty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered common rail direct injection technology during the 1990s, establishing the engineering foundations that now dominate heavy-duty diesel architectures worldwide. This historical lineage shapes current procurement patterns as regulatory enforcement tightens across multiple jurisdictions.
United States
Class 8 truck fleets in Michigan and Ohio are accelerating replacement cycles to satisfy EPA Phase 2 greenhouse gas timelines. The regulation mandates CO2 reductions through 2027, forcing pre-2010 engine management hardware into obsolescence. Detroit and Columbus anchor manufacturing clusters where tier-one suppliers coordinate powertrain integration.
Germany
Commercial vehicle OEMs in Baden-Württemberg and Bavaria face Euro VII draft specifications requiring cooled EGR-SCR integration. The EU Green Deal's 55% emissions target realigns procurement criteria toward unified after-treatment modules. Stuttgart and Munich host vertically integrated sensor-to-software development centers.
China
Heavy-duty truck manufacturers in Shandong and Hubei provinces are displacing pump-line-nozzle systems with common rail hardware to meet China VI standards. MIIT fuel consumption protocols dictate validation requirements for domestic market entry. Weifang and Wuhan concentrate injection system assembly partnerships.
India
Domestic bus and truck OEMs in Maharashtra and Tamil Nadu require upgraded ECU calibration for BIS VI implementation. The PLI scheme for automotive components incentivizes local assembly of emission-critical subsystems. Pune and Chennai anchor tier-one supplier technical centers serving regional platforms.
Brazil
Commercial vehicle renewal programs in São Paulo and Minas Gerais states are tightening ANVISA emission enforcement for Mercosur markets. Stricter inspection regimes create first-mover opportunities for common rail providers with localized manufacturing. São Paulo's industrial corridor hosts the primary assembly partnerships.
Diesel Engine Management System Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the diesel engine management value chain, creating a tiered structure where integrated powertrain suppliers hold pricing leverage over component specialists. The vendor base clusters around three strategic archetypes: vertically integrated system integrators, semiconductor-centric control module specialists, and regional injection hardware fabricators. Consolidation pressure intensifies as fleet operators demand unified warranty coverage spanning engine, transmission, and after-treatment domains. Dominant competitive moves include backward integration into sensor manufacturing and strategic partnerships for predictive maintenance software deployment.
Among German-based integrated suppliers, Robert Bosch GmbH and Continental AG exemplify the system integrator archetype through their captive injection and control module capabilities. Denso Corporation represents the Asia-Pacific manufacturing scale vector, anchoring regional production networks across Japanese and Chinese truck platforms. These three entities occupy positions where full powertrain accountability commands premium procurement relationships.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Delphi Technologies |
| Denso Corporation |
| BorgWarner Inc. |
| Infineon Technologies |
| Hella KGaA Hueck & Co. |
| NGK Spark Plug |
| Hitachi Automotive Systems |
| Others |
Value Chain & Pricing Dynamics
Embedded firmware engineers concentrated in Stuttgart and Detroit command wage premiums that compress margin spreads between premium-tier integrated systems and standard ECU modules. Labor-cost differentials between German development centers and Asian manufacturing hubs force tier-one suppliers to stratify pricing across three performance tiers calibrated to certification complexity and firmware customization depth.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates full powertrain integrators from component specialists. Price differentiation stems from EPA/Euro VII certification grade and captive injection manufacturing scale. Pricing pressure intensifies in the standard tier as Chinese OEMs internalize ECU calibration capabilities. Fleet operators show lowest price sensitivity for unified warranty packages, while owner-operator segments drive commoditization in aftermarket replacement modules.
Supply Chain Analysis
India's PLI scheme for automotive components and China's MIIT domestic-content requirements are reshaping sourcing patterns for emission-critical subsystems. Manufacturing concentrates in Germany, China, and Japan, with piezoelectric actuator fabrication anchored in Stuttgart and Nagoya. The supply chain draws from palladium spot markets and precision-machined injector nozzles. Single-source vulnerability in platinum-group-metal catalyst formulations creates exposure to commodity volatility. Distribution runs through tier-one powertrain integrators capable of warranting full engine-after-treatment packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in diesel engine management hinges on software-defined calibration services displacing hardware-only procurement, with predictive maintenance analytics enabling recurring revenue streams that offset unit-volume pressure from electrification substitution.
For Market Incumbents: Cement control over firmware development talent pools in Stuttgart and Detroit to defend against battery-electric powertrain suppliers poaching embedded control engineers. Deepen backward integration into cylinder pressure sensor manufacturing to reduce exposure to single-source German and Japanese component vendors. Battery-electric substitution in urban bus segments threatens hardware volumes, making software monetization the priority defensive lever. For New Entrants and Emerging Players: Capture aftermarket retrofit demand in Brazil's ANVISA enforcement corridor and India's BIS VI implementation window where certified system suppliers remain underrepresented. Mercosur markets offer lowest competitive density for common rail providers with localized assembly partnerships. A calibration-services-first go-to-market model bypasses capital-intensive injection hardware fabrication barriers. For Investors and Strategic Acquirers: Tier-one powertrain integrators with captive sensor-to-software stacks are the most active acquirers in this space, consolidating component specialists to meet fleet demands for unified warranty coverage. Long-term viability centers on suppliers' ability to pivot diesel combustion expertise toward hybrid-electric torque coordination algorithms. Watch for inflection in EPA Phase 2 retrofit completion rates as a signal of replacement-cycle exhaustion versus sustained upgrade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Software Deployment | ECU-embedded machine learning enables fleet operators to optimize injector replacement intervals in US Class 8 trucks. |
| Backward Integration into Sensor Manufacturing | Cylinder pressure sensor fabrication in-house reduces single-source dependency on German and Japanese precision component suppliers. |
| Common Rail System Localization | Assembly partnerships in São Paulo and Pune satisfy ANVISA and BIS VI domestic-content mandates for Mercosur and Indian markets. |
| Hybrid Powertrain Interface Development | Torque coordination algorithms for diesel-electric architectures address EPA Phase 2 and Euro VII integrated thermal management requirements. |
| Low-GWP Refrigerant Thermal Management | EU F-Gas Regulation compliance opens engineering service contracts for redesigned engine bay packaging in German commercial vehicles. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with tier-one supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet maintenance managers. Secondary validation draws from EPA certification databases, EU type-approval registries, MIIT fuel consumption filings, and vehicle production statistics. Bottom-up segment sizing triangulates against top-down macroeconomic indicators to constrain forecast variance.
Rate-of-change decomposition separates volume drivers from value-mix effects across the projection horizon. Segmentation dimensions span component tier, technology generation, application vertical, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to replacement-cycle timing, emission mandate phase-in schedules, and electrification substitution elasticities. Industry-specific inputs include commercial vehicle fleet age distributions and certified test facility capacity constraints.
Regulatory timeline slippage, platinum-group-metal price spikes, and battery-electric bus procurement acceleration are the dominant revision risks that could compress or extend modeled demand windows. Forecasts reflect documented assumptions regarding mandate enforcement rigor and hybrid-platform adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Emission Control Catalyst for Small Engines Market
Powertrain
Automotive Power Modules Market
Powertrain
Automotive Transmission System Market
Powertrain
Fuel Pumps Market
Powertrain
North America Automotive Engine Oils Market
Powertrain
North America Electro Hydraulic Power Steering Market
Powertrain
Drive Shaft Market
Powertrain
Car Oil Filter Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Global Automotive Drive Shaft Market
Powertrain
Timing Belt Kits Market
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
Automotive Conversion Kit Market
Powertrain
Clutch Market
Powertrain
Global Automotive GD Injector Market
Powertrain
United States Electro Hydraulic Power Steering Market