
 Transmission Oil Filters Market | 2026-2036
Transmission Oil Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Transmission Oil Filters Market Intelligence
Aftermarket service revenue from fleet operators is rewriting the competitive landscape for transmission oil filter manufacturers. Mann+Hummel leverages its extensive original equipment manufacturer relationships to secure a strong position in the replacement parts channel. Mahle differentiates through its focus on integrated thermal management and filtration systems for both internal combustion and electric vehicle transmissions. WIX Filters competes by offering a broad product portfolio that covers passenger cars, commercial vehicles, and off-highway applications.
A transmission oil filter is a critical component designed to remove contaminants like metal shavings and clutch material from automatic transmission fluid. Its primary function is to protect sensitive transmission components, such as solenoids and valve bodies, ensuring smooth gear shifts and extending the transmission's operational life. Cartridge-type filters show significant adoption in modern automatic transmissions, while spin-on designs remain prevalent in older vehicle models. The aftermarket providers segment represents the largest revenue pool, driven by routine vehicle maintenance schedules.
Vehicle efficiency standards from regulators like the US EPA and China's MIIT indirectly influence filter design to support advanced, multi-speed transmissions. Material composition is governed by frameworks such as the EU's REACH regulation, which restricts certain hazardous substances in automotive components. Future product development will depend on balancing filtration efficiency, material sustainability, and compatibility with next-generation transmission fluids for electric and hybrid vehicles.
Market Dynamics
The central structural force shaping the market is the technical co-evolution of transmission fluids and filter media. Mandates for vehicle efficiency from regulators like the US EPA and China's MIIT are driving the adoption of complex, multi-speed transmissions that require advanced, low-viscosity fluids and highly efficient filtration.
Growth Catalysts
- Vehicle Efficiency Standards:Regulations from entities like the US EPA and China's MIIT mandate lower emissions and improved fuel economy, accelerating the adoption of advanced transmissions that require superior filtration to protect sensitive components.
- Heavy-Duty Fleet Demands:Commercial fleet operators prioritize vehicle uptime and longer service intervals, creating strong demand for high-performance filters using synthetic media that enable extended transmission fluid drain schedules.
- Aftermarket Expansion in China:China's vast and growing commercial vehicle parc generates substantial and consistent demand for replacement filters, anchoring a large portion of the global aftermarket revenue stream.
Market Restraints
- Input Material Cost Volatility:Price fluctuations for raw materials, particularly specialized synthetic fibers and high-performance polymers used in advanced filter media, can compress manufacturer margins and create pricing instability.
- Electric Vehicle Substitution:The long-term shift toward battery electric vehicles, which often have simpler single-speed transmissions or no transmission, presents a structural threat to demand for traditional transmission oil filters.
- Design Trade-offs:A fundamental technical conflict exists between maximizing filtration efficiency to capture microscopic particles and minimizing flow restriction, which is critical for the performance of modern, low-viscosity transmission fluids.
Strategic Opportunities
- EV Drivetrain Fluids:Developing specialized filtration solutions for electric vehicle transmission and e-axle fluids, which have unique requirements for thermal management and electrical insulation, opens a new product category.
- Sustainable Filter Media:The creation of effective, biodegradable, or recyclable filter media addresses growing regulatory pressure from frameworks like the EU Green Deal and appeals to sustainability-focused fleet customers.
- Southeast Asian Aftermarket:Targeting the expanding vehicle parc in fast-growing economies across Southeast Asia represents an opportunity to capture new growth in the replacement parts market as vehicle density increases.
Industry Challenges
- OEM Validation Complexity:Securing approvals for new filter designs is a lengthy and costly process, as each component must be validated against the unique performance specifications of multiple automotive original equipment manufacturers.
- Lack of Test Standardization:The absence of globally harmonized testing protocols for filter performance with next-generation transmission fluids creates ambiguity and increases the burden of compliance for suppliers operating in multiple regions.
- Supply Chain Reconfiguration:Shifting to more sustainable or circular material inputs requires significant investment in qualifying new suppliers and redesigning supply chains without compromising filter performance or cost-effectiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transmission Oil Filters Market |
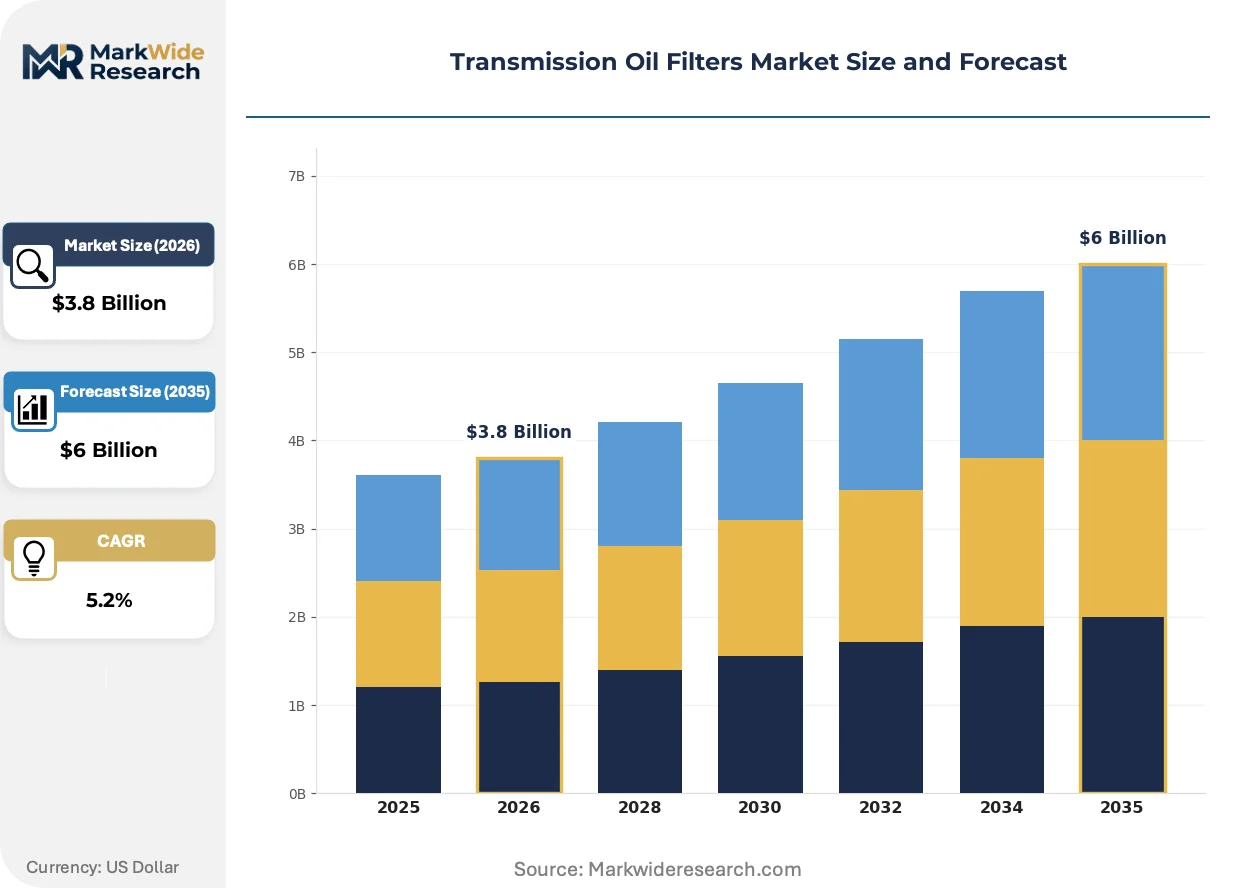
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spin-on, Cartridge, In-line, Magnetic Vehicle Type: Passenger Cars, Commercial Vehicles, Heavy-duty Trucks, Motorcycles Material: Paper, Synthetic, Metal, Polyester End User: Automakers, Aftermarket Providers, Fleet Operators, Repair Shops |
| Companies Covered | ACDelco, Fram, Mann+Hummel, K&N Engineering, Hengst, Mahle, WIX Filters, Sakura Filter, Baldwin Filters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transmission Oil Filters Market Strategic Shifts & Innovations
Balancing the demands of internal combustion engine efficiency with the needs of emerging electric drivetrains defines current product strategy. This dual focus requires innovation in both material science and filter architecture to serve two distinct technological pathways.
Multi-layer synthetic media combines depth and surface filtration, capturing finer particles than traditional cellulose. Heavy-duty and premium passenger vehicle segments are rapidly adopting these media for extended service intervals. This advanced performance is rendering obsolete older, single-layer cellulose filters unable to meet the cleanliness requirements of modern multi-speed transmissions.
The EU's REACH regulation restricts certain chemicals in automotive components, including adhesives and polymers within filters. This forces manufacturers to reformulate materials and re-validate products, adding cost and complexity to development. The European aftermarket is most affected, requiring suppliers to provide documentation proving compliance for all components sold.
Fleet operators increasingly favor total cost of ownership models over simple upfront price for maintenance components. This disrupts the transactional sales model in the aftermarket, favoring suppliers who demonstrate longer filter life and reduced vehicle downtime. This behavior is most prominent in North American and European heavy-duty trucking where operational efficiency is paramount.
Transmission Oil Filters Market Segmentation
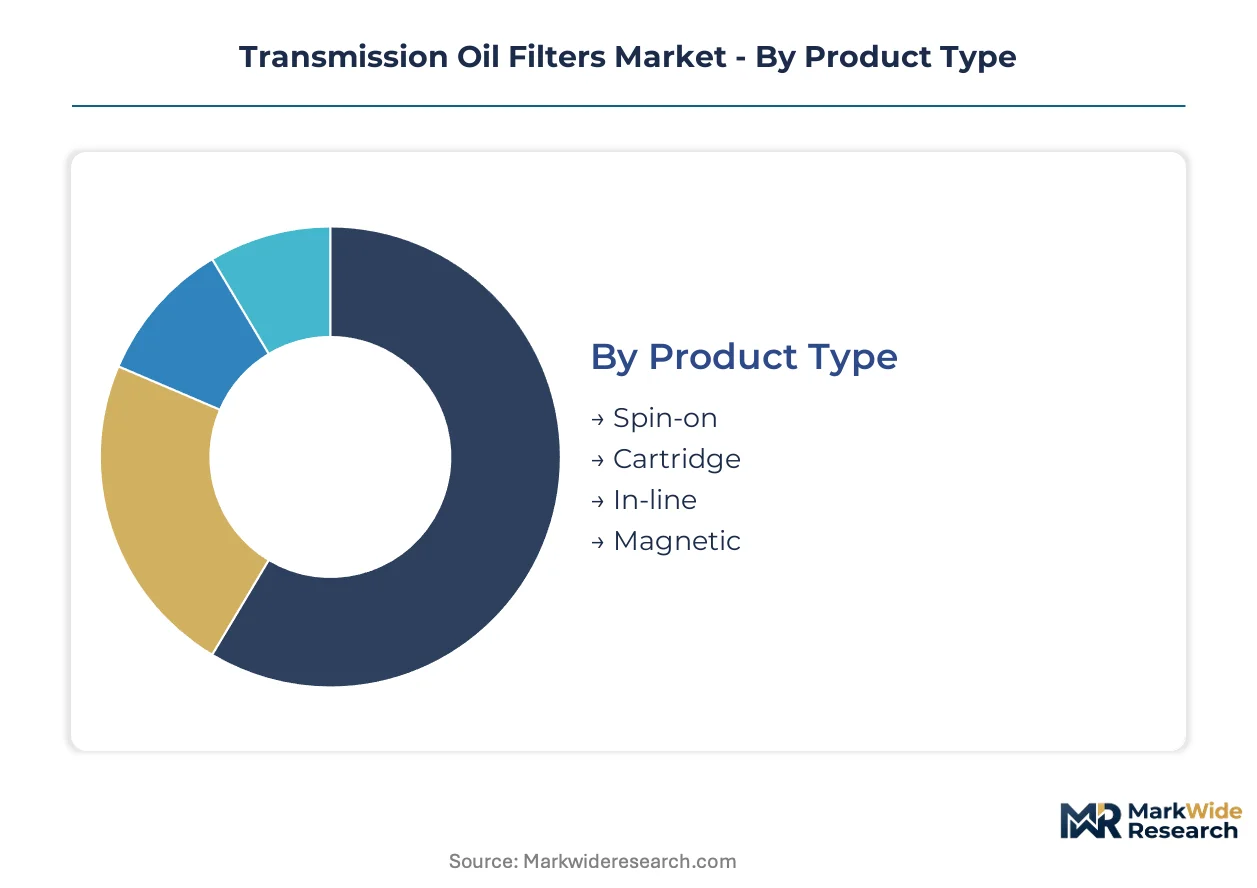
The transmission oil filters market exhibits distinct characteristics across its various segments, reflecting diverse operational demands and technological requirements. Understanding these segment dynamics is crucial for manufacturers to align product development with specific vehicle types and end-user needs. This granular view highlights areas of concentrated demand and emerging opportunities.
Product Type:
The turnover rate for transmission oil filters varies significantly by product type, with some designs requiring more frequent replacement than others. This directly impacts aftermarket revenue streams and inventory management for suppliers. Design complexity and fluid compatibility also influence replacement cycles.
- Cartridge:These filters are integrated within the transmission housing, often requiring specialized tools for replacement. Their design supports advanced filtration media for modern multi-speed transmissions, protecting sensitive components in passenger cars and commercial vehicles. Demand concentrates in new vehicle production and subsequent maintenance cycles.
- Spin-on:Encased in a metal canister, spin-on filters are externally mounted and designed for easier, quicker replacement during routine service. They remain prevalent in older vehicle models and some heavy-duty applications due to their robust construction and straightforward maintenance. The aftermarket in North America and Europe drives consistent replacement volumes.
- In-line:Positioned in the transmission fluid line, in-line filters capture contaminants before they reach critical components.
- Magnetic:These filters utilize magnets to attract ferrous metal particles, often used as a supplementary filtration method in conjunction with other filter types.
Spin-on filters anchor the volume base while cartridge filters gains share at the steepest rate.
Vehicle Type:
Application-specific requirements drive differentiation across vehicle types, influencing filter design, material selection, and service intervals. Each vehicle category presents unique challenges related to transmission size, fluid volume, and operational stress. The filter's resilience and efficiency must match the vehicle's duty cycle.
- Heavy-duty Trucks:These vehicles demand robust, high-capacity filters capable of extended service intervals and superior contaminant retention due to severe operating conditions. Fleet operators prioritize filters that enhance vehicle uptime and reduce maintenance costs. Demand is particularly strong in China and North America due to large commercial fleets.
- Commercial Vehicles:Covering light and medium-duty trucks and vans, this segment requires durable filters that balance cost-effectiveness with reliable performance for frequent stop-and-go operations. Filtration efficiency is crucial for protecting transmissions under varying loads. The European market shows consistent demand for these filters.
- Passenger Cars:This segment represents the largest volume market, driven by the sheer number of vehicles on the road, requiring filters optimized for smooth shifting and transmission longevity.
- Motorcycles:Filters for motorcycles are typically smaller and designed to withstand high engine speeds and compact transmission designs, often integrated into engine oil filtration systems.
Heavy-duty trucks require filters with the highest durability, while passenger cars represent the largest installed base for replacement filters.
Material:
The choice of filter material directly impacts filtration efficiency, lifespan, and compatibility with advanced transmission fluids. Different materials offer varying levels of particle capture, flow characteristics, and chemical resistance. Material innovation is critical for next-generation transmission systems.
- Synthetic:Composed of engineered fibers like polyester or fiberglass, synthetic media offers superior filtration efficiency and dirt-holding capacity compared to traditional materials. These filters enable longer drain intervals and protect sensitive multi-speed transmissions. Demand is accelerating in premium and heavy-duty vehicle segments.
- Metal:Typically stainless steel mesh, metal filters provide robust filtration for larger particles and are often used as pre-filters or in applications requiring high flow rates. They offer excellent durability and can be cleanable in some industrial settings. Certain off-highway applications utilize metal filters for their resilience.
- Paper:Cellulose-based paper media offers cost-effective filtration but has lower dirt-holding capacity and shorter service life compared to synthetic alternatives.
- Polyester:A type of synthetic fiber, polyester media provides good chemical resistance and filtration performance, often used in multi-layer filter constructions for enhanced efficiency.
Synthetic materials are expanding most quickly, while paper remains a significant volume component in older vehicle maintenance.
End User:
The purchasing behaviors and service requirements of end users shape distribution channels and product specifications for transmission oil filters. Each end-user group prioritizes different aspects, from upfront cost to long-term operational efficiency. Understanding these preferences is key for market penetration.
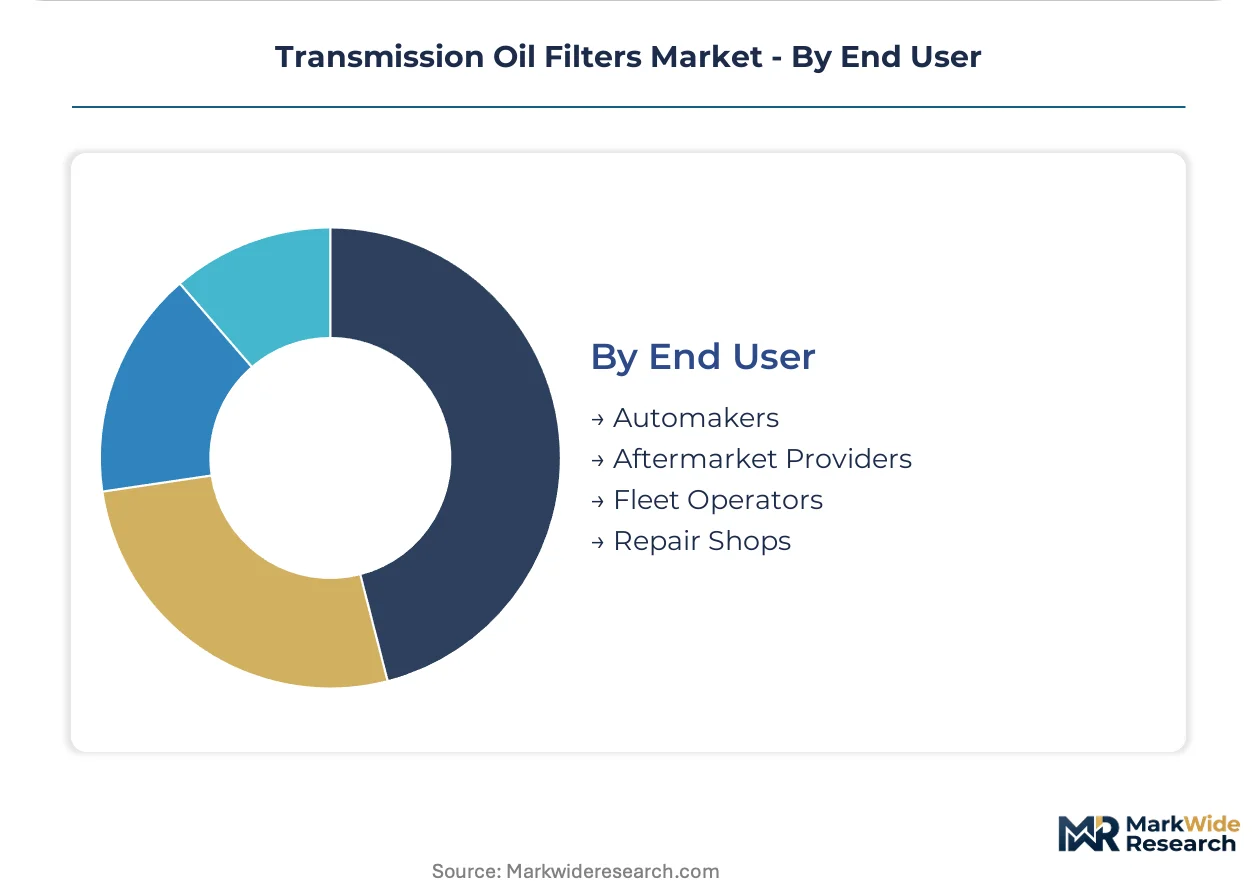
- Aftermarket Providers:This segment includes independent parts distributors and retailers supplying replacement filters for routine vehicle maintenance and repairs. They represent the largest revenue pool, driven by consistent demand for replacement parts across all vehicle ages. China's expansive vehicle parc generates substantial aftermarket demand.
- Fleet Operators:Companies managing large vehicle fleets, particularly heavy-duty trucks, prioritize filters that extend service intervals and minimize vehicle downtime. Their procurement decisions emphasize total cost of ownership and filter performance over simple upfront price. North American and European fleet operators are highly sensitive to these factors.
- Automakers:Original equipment manufacturers (OEMs) purchase filters for installation in new vehicles, with rigorous validation processes for performance and integration.
- Repair Shops:Independent and franchised repair facilities source filters for vehicle servicing, often influenced by brand reputation, availability, and pricing from their suppliers.
Aftermarket providers command the largest revenue share, with fleet operators demonstrating the highest sensitivity to filter performance metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers of transmission oil filters exhibit varying price sensitivities, with fleet operators prioritizing long-term performance over upfront cost, while some passenger car owners may seek more economical aftermarket options. This elasticity shapes regional market dynamics, influencing product adoption and distribution strategies. Specific geographies demonstrate distinct demand patterns for advanced filtration solutions.
China
Demand for transmission oil filters in China stems from its vast commercial vehicle production and a large, expanding aftermarket for replacement parts. China's MIIT regulations on vehicle efficiency drive the adoption of multi-speed transmissions requiring superior filtration. The Yangtze River Delta region, a major automotive manufacturing hub, concentrates significant production and aftermarket service activities.
United States
The United States market is driven by heavy-duty fleet demands for extended service intervals and the large passenger car parc requiring routine maintenance. US EPA standards for vehicle emissions indirectly influence filter design for advanced transmission systems. The Detroit automotive cluster continues to innovate in transmission technology, impacting filter specifications for new vehicle models.
Germany
Germany's market for transmission oil filters benefits from a strong commercial vehicle segment and stringent European vehicle efficiency standards. The EU's REACH regulation mandates specific material compositions, influencing filter development for both OEM and aftermarket channels. Bavaria, with its prominent automotive manufacturers, leads in developing advanced transmission systems and associated filtration components.
India
India's growing vehicle parc, particularly in the commercial and passenger car segments, generates consistent demand for replacement transmission oil filters. The country's evolving vehicle emission norms encourage the adoption of more efficient transmissions, necessitating effective filtration. The Chennai-Bengaluru industrial corridor is witnessing increased automotive component manufacturing, including specialized filter production.
Transmission Oil Filters Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure for transmission oil filters. Original equipment manufacturers (OEMs) and their primary suppliers dominate the high-performance segment, while a broader set of aftermarket providers competes on price and availability. Strategic archetypes include integrated filtration specialists, broad-portfolio aftermarket suppliers, and niche players focusing on specific vehicle types. Companies are pursuing strategic partnerships and portfolio diversification to maintain competitive advantage.
Integrated filtration specialists like Mann+Hummel GmbH and Mahle GmbH exemplify the premium OEM supplier archetype, leveraging deep engineering expertise to meet stringent validation requirements for new vehicle platforms. These companies often develop advanced synthetic media for next-generation transmissions and integrated thermal management solutions. Conversely, WIX Filters, Inc. represents the broad aftermarket supplier archetype, offering a wide product portfolio that spans various vehicle types and off-highway applications. These players focus on extensive distribution networks and consistent product availability for routine maintenance across diverse customer bases.
| Leading Market Players |
|---|
| ACDelco |
| Fram |
| Mann+Hummel |
| K&N Engineering |
| Hengst |
| Mahle |
| WIX Filters |
| Sakura Filter |
| Baldwin Filters |
| Others |
Cost & Logistics Intelligence
Raw material cost volatility, especially for synthetic fibers, significantly impacts manufacturer margins for transmission oil filters. This upstream pressure directly influences pricing strategies and profitability across the aftermarket supply chain.
Pricing Analysis
Aftermarket replacement parts revenue drives lifetime value for transmission oil filter manufacturers. The dominant pricing structure remains per-unit transactional, though long-term contracts with fleet operators are increasing. Price differentiation stems from filter performance specifications and brand reputation. Pricing softness impacts the economy tier due to intense competition, while fleet operators are least price-sensitive, prioritizing total cost of ownership.
Supply Chain Analysis
Input material cost volatility for specialized synthetic fibers and high-performance polymers creates a structural risk for transmission oil filter supply chains. Geographic supply concentrates in China, Germany, and the United States for filter media production. The industry draws from global suppliers for raw materials like polyester and fiberglass. Distribution runs through a fragmented network of independent aftermarket providers and direct channels to fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transmission oil filters market presents a defensive moat story, primarily due to high switching costs associated with OEM validation and integration. Manufacturers benefit from established relationships and the critical function of their products.
For Market Incumbents:Build regulatory entrenchment through early engagement with evolving vehicle efficiency standards and material regulations like EU REACH. Deepen OEM relationships by co-developing filtration solutions for next-generation EV drivetrains, countering the threat of electric vehicle substitution. Invest in sustainable filter media R&D to meet future EU Green Deal requirements, securing long-term market relevance. Control aftermarket channels via strategic partnerships, mitigating competitive pressure from broad-portfolio suppliers.
For New Entrants and Emerging Players:Establish a beachhead in the Southeast Asian aftermarket by focusing on cost-effective, durable spin-on filters for the expanding vehicle parc. Target niche applications like off-highway equipment or specialized industrial transmissions where OEM validation barriers are lower. Leverage agile manufacturing and localized distribution networks for rapid market penetration. Offer sustainable filter media solutions as a differentiated go-to-market angle, appealing to environmentally conscious fleet operators.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across advanced synthetic media production due to R&D and specialized equipment needs. The transmission oil filters market offers long-term viability, driven by essential maintenance cycles and evolving filtration demands for new vehicle technologies. Target acquisition archetypes include integrated filtration specialists with strong OEM ties or niche players possessing advanced material science capabilities. Watch for increased M&A activity among Tier 1 suppliers as a signal of market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop EV Drivetrain Filtration | Secures position in next-generation vehicle platforms and addresses new thermal management requirements. |
| Expand Synthetic Media Production | Meets growing demand for extended drain intervals and higher filtration efficiency in heavy-duty segments. |
| Acquire Aftermarket Distribution Network | Enhances market reach and control over replacement parts channels, especially in emerging economies. |
| Invest in Sustainable Material R&D | Ensures compliance with environmental regulations like EU REACH and attracts sustainability-focused fleet customers. |
| Standardize Global Test Protocols | Reduces OEM validation complexity and accelerates product launch cycles across multiple regions. |
Research Approach
Operator-level perspectives from OEM engineers, fleet managers, aftermarket distributors, and material scientists anchored the qualitative base of this study. Primary interviews combined with extensive secondary research validated market dynamics. Data sources included automotive production databases, regulatory filings from the US EPA and China's MIIT, and industry association reports. Bottom-up and top-down triangulation ensured data accuracy.
Scenario-bracketing across optimistic and conservative outlooks informed the market projections. The analytical framework modeled segmentation dimensions by product type, vehicle type, material, and end user. CAGRs were derived from historical trends and projected adoption rates for advanced filtration technologies over the analysis window. Key inputs included vehicle parc growth and regulatory compliance timelines.
Sensitivities concentrate around raw material price volatility and the pace of electric vehicle adoption. Forecasts reflect documented assumptions regarding technological advancements and regulatory shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
France Automotive Engine Oils Market
Powertrain
LNG Engine Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Automotive Brake Booster Market
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
New Energy Vehicle Scroll Compressor Market
Powertrain
Global Automotive Electric Drivetrain System Market
Powertrain
Europe Internal Combustion Engines Market
Powertrain
Automotive Driveline Market
Powertrain
Automotive Power Steering Cooler Market
Powertrain
South America Internal Combustion Engines Market
Powertrain
Electric Powertrain Systems Market
Powertrain
Drive Mode-Linked Powertrain Actuator Systems Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market